
 Polyethylene Furanoate Films Market | 2026-2036
Polyethylene Furanoate Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Furanoate Films Market Intelligence
Modular packaging configurations that separate barrier layers from structural substrates is realigning procurement strategies across flexible packaging value chains. Avantium N.V. anchors its position through proprietary YXY technology for 2,5-furandicarboxylic acid production. Toray Industries, Inc. leverages its film extrusion expertise to develop biaxially oriented PEF variants with enhanced oxygen barrier properties. Origin Materials sustains cost-competitive feedstock access through its chloromethylfurfural platform derived from lignocellulosic biomass.
Polyethylene furanoate films are semi-crystalline thermoplastic polyester films manufactured from polymerized 2,5-furandicarboxylic acid and monoethylene glycol, exhibiting oxygen barrier performance approximately six times superior to standard polyethylene terephthalate. These films serve primarily as high-performance barrier layers in food packaging, medical blister packs, and industrial protective films where extended shelf life and reduced material thickness are critical. Food packaging applications dominate current volume allocation, while medical applications represent the fastest-expanding segment as pharmaceutical companies adopt mono-material compatible barrier solutions. Industrial films occupy a mature niche with stable specifications but limited margin expansion potential compared to certified food-contact and pharmaceutical grades.
The European Chemicals Agency enforces REACH registration requirements for novel monomers including FDCA derivatives, while the EU Green Deal's packaging and packaging waste regulation mandates recycled content thresholds that bio-based materials can help satisfy. The U.S. Food and Drug Administration maintains food-contact notification protocols that PEF producers must navigate for commercial adoption in North American beverage packaging. Stakeholders must monitor polymerization scale-up economics and downstream compounding partnerships to secure film-grade resin availability before committed brand owner conversion timelines activate.
Market Dynamics
Modular packaging architectures are dismantling traditional film procurement hierarchies as converters decouple barrier performance from structural bulk. The shift toward mono-material compatible laminates is compressing specification cycles and forcing resin suppliers to certify film-grade PEF ahead of committed brand conversion timelines.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content thresholds and bio-based material recognition under the packaging and packaging waste regulation are accelerating substitution of petroleum-derived polyester in German and French flexible packaging supply chains.
- Medical blister pack conversion:Pharmaceutical packaging specifications are pivoting toward mono-material barrier solutions that simplify end-of-life sorting and satisfy hospital sustainability procurement criteria.
- Oxygen barrier performance differential:PEF's six-fold improvement over standard PET enables downgauging in shelf-sensitive food applications without secondary barrier coatings.
Market Restraints
- FDCA monomer supply concentration:Commercial-scale 2,5-furandicarboxylic acid production remains anchored to a limited number of pilot and demonstration facilities, creating resin availability bottlenecks for film extrusion trials.
- REACH registration friction:ECHA novel monomer protocols impose multi-year evaluation timelines and data requirements that delay commercial deployment of next-generation furan-based polymers.
- Polymerization economics:Ring-opening polymerization of FDCA-derived monomers requires specialized catalyst systems and process conditions that elevate unit costs versus commodity PET at current scale.
Strategic Opportunities
- US food-contact notification pathway:FDA clearance for PEF in beverage packaging applications remains underexploited, offering first-mover positioning in North American carbonated soft drink and bottled water segments.
- Industrial protective film premiumization:Electronics and automotive component shipping applications are specifying thinner-gauge barrier films with extended weathering resistance, opening volume outside commoditized food packaging.
- Chloromethylfurfural platform integration:Lignocellulosic feedstock conversion technologies are converging with catalytic FDCA production to decouple resin economics from sugar crop price volatility.
Industry Challenges
- Film-grade resin certification timelines:Downstream converters require 18-24 month qualification cycles for new barrier materials in pharmaceutical and infant food applications, compressing the window between resin availability and committed brand launches.
- Compounding capability gaps:Masterbatch and additive formulation expertise for PEF film extrusion concentrates among a limited supplier base, constraining rapid specification changes.
- Legacy PET recycling stream contamination:Sorting infrastructure at municipal recovery facilities lacks near-infrared detection calibration for furan-based polyester identification, risking downcycling penalties.
Report Scope
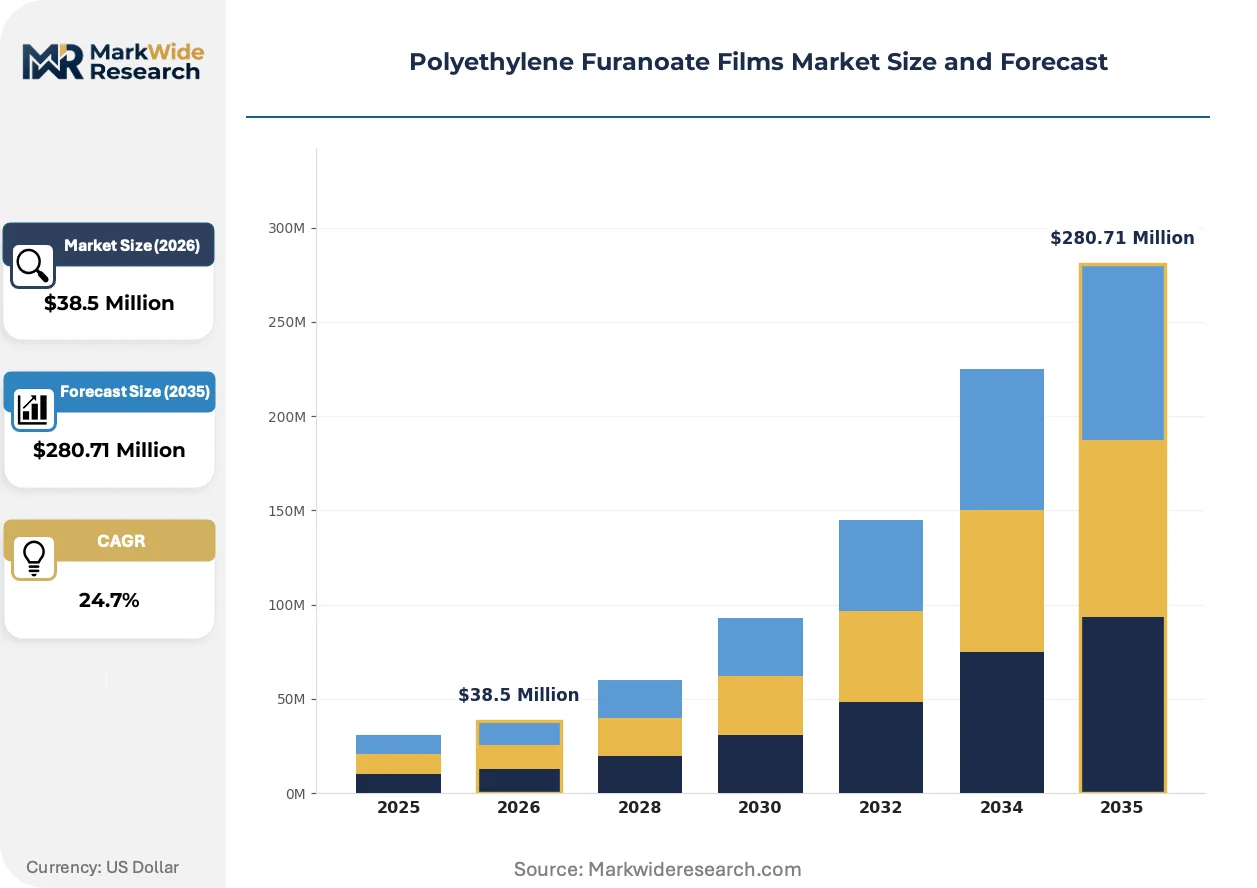
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Furanoate Films Market |
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $280.71 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle Grade, Food Packaging, Industrial Films, Coatings Application: Beverage Packaging, Food Storage, Industrial Uses, Medical Applications End User: Food Industry, Beverage Sector, Pharmaceutical Companies, Consumer Goods Technology: Biopolymer Processing, Extrusion Coating, Injection Molding, Film Blowing |
| Companies Covered | AVA Biochem AG, Toray Industries, Inc., Avantium N.V., Origin Materials, Swicofil AG, Sulzer Ltd., ALPLA Werke Alwin Lehner GmbH & Co. KG, BASF SE, Toyobo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Furanoate Films Market Strategic Shifts & Innovations
Biaxial orientation and co-extrusion advances are compressing the performance gap between bio-based barrier films and multi-layer petroleum-derived laminates. These process innovations are enabling converters to meet aggressive sustainability targets without sacrificing shelf-life extension.
Biaxially oriented PEF variants are consolidating technical credibility among skeptical packaging engineers who previously dismissed bio-based alternatives as performance-compromised. Major European converters are adopting these films for modified atmosphere meat and cheese packaging where oxygen ingress tolerance measures in single-digit parts per million. The technology is consolidating supply chain influence around resin producers capable of delivering consistent biaxial orientation yield rates.
REACH registration requirements for FDCA derivatives are compressing the competitive field to well-capitalized producers capable of sustaining multi-year regulatory investment. ECHA data requirements for novel polymer monomers are elevating compliance costs that smaller specialty chemical entrants cannot absorb. Medical device and pharmaceutical packaging categories are most affected, with several converters delaying PEF adoption until full monomer dossier approval.
Brand owner sustainability scorecards are rewiring procurement authority toward centralized packaging engineering functions and away from regional purchasing departments. Food and beverage multinationals are consolidating film specification decisions at headquarters level to ensure supply base alignment with science-based targets. This concentration is most visible in German and Benelux retail supply chains, where private label sustainability commitments are cascading through tier-one packaging suppliers.
Polyethylene Furanoate Films Market Segmentation
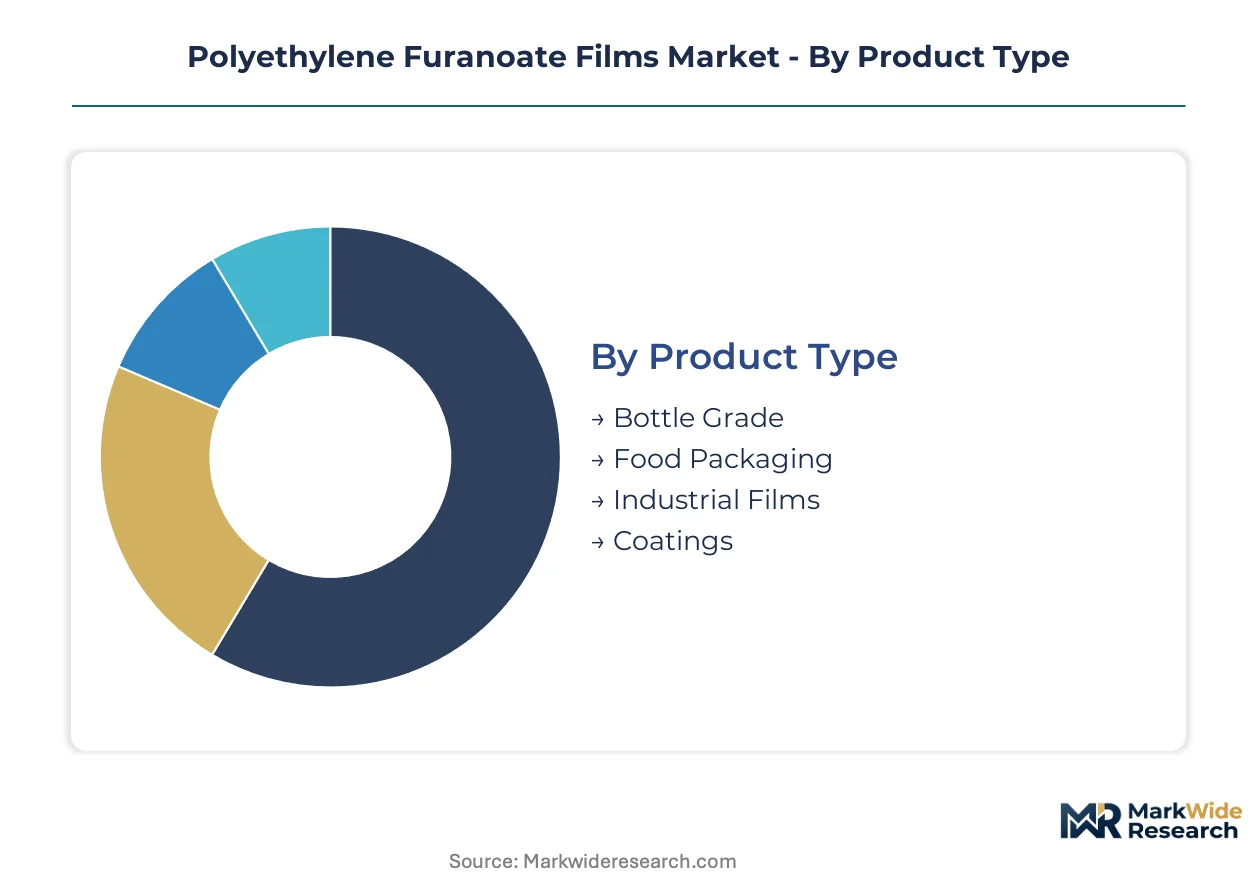
Segmentation in polyethylene furanoate films reveals how bio-based polyester penetrates distinct value chains with divergent technical requirements. Each dimension—product grade, application end-use, customer vertical, and manufacturing process—exposes different margin structures and certification barriers that shape supplier prioritization.
Product Type:
Integration depth varies sharply across product grades, with some functioning as standalone barrier layers and others requiring embedding within multi-material laminates.
- Food Packaging:Semi-crystalline thermoplastic films engineered for oxygen barrier performance six times superior to standard PET. Demand concentrates in German and French flexible packaging supply chains where EU Green Deal mandates accelerate substitution of petroleum-derived polyester in modified atmosphere meat and cheese applications.
- Bottle Grade:Higher intrinsic viscosity resins designed for stretch blow molding of carbonated beverage containers. Pharmaceutical companies in the Benelux region are piloting this grade for mono-material blister packs that simplify hospital waste sorting.
- Industrial Films:Protective barrier layers for electronics and automotive component shipping with extended weathering resistance specifications.
- Coatings:Thin-film barrier depositions applied to structural substrates via extrusion or solution coating processes.
Volume placements concentrate in Food Packaging; the faster expansion belongs to Bottle Grade.
Application:
Application segments diverge by regulatory exposure, with food-contact and medical categories demanding multi-year certification cycles that filter out undercapitalized suppliers.
- Food Storage:Modified atmosphere packaging for shelf-sensitive proteins and dairy where oxygen ingress tolerance measures in single-digit parts per million. Retail supply chains in Germany are consolidating specifications at headquarters level to align private label sustainability commitments with science-based targets.
- Medical Applications:Mono-material compatible barrier solutions for pharmaceutical blister packs and medical device packaging. ECHA REACH registration requirements for FDCA derivatives are compressing the competitive field to well-capitalized producers capable of sustaining multi-year regulatory investment in this segment.
- Beverage Packaging:Carbonated soft drink and bottled water containers requiring FDA food-contact notification for North American commercial deployment.
- Industrial Uses:Protective films for electronics manufacturing and automotive logistics with stable specifications but limited margin expansion potential.
Food Storage commands the largest volume allocation; Medical Applications are climbing the fastest as pharmaceutical sustainability procurement criteria tighten.
End User:
End user categories reflect procurement authority concentration, with multinational headquarters increasingly overriding regional purchasing decisions.
- Food Industry:Retail brand owners and private label operators specifying barrier films for meat, cheese, and ready-meal packaging. German converters are decoupling barrier performance from structural bulk through modular packaging architectures that favor high-performance bio-based layers.
- Pharmaceutical Companies:Drug manufacturers and medical device firms requiring certified mono-material solutions for hospital waste stream compatibility. EMA and national European regulators enforce medical device packaging standards that PEF producers must navigate alongside ECHA monomer registration.
- Beverage Sector:Bottled water and carbonated soft drink brand owners with centralized packaging engineering functions.
- Consumer Goods:Personal care and household product manufacturers with less stringent barrier requirements than food or pharmaceutical categories.
The Food Industry anchors current demand; Pharmaceutical Companies show the steepest expansion trajectory as mono-material mandates spread through hospital procurement.
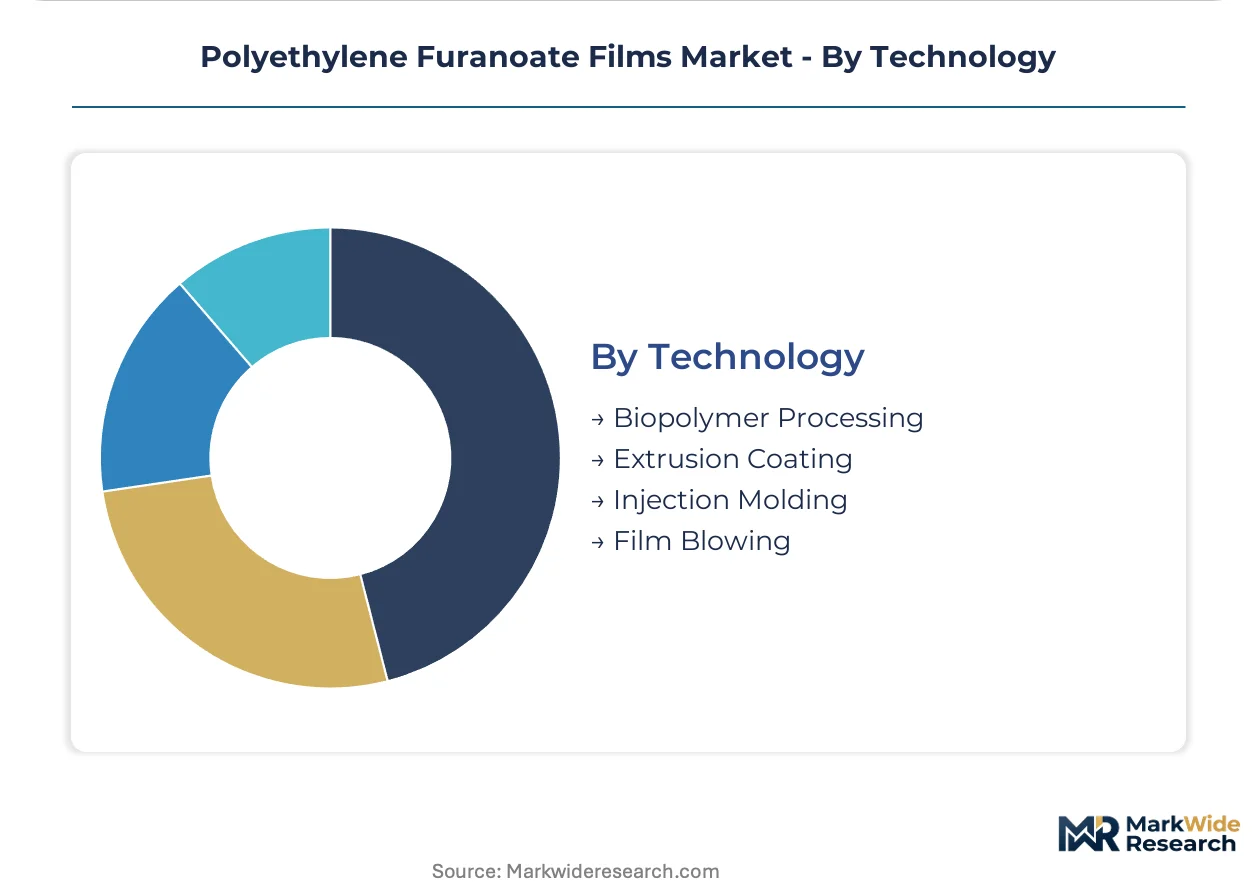
Technology:
Technology segments map to equipment intensity and yield consistency requirements, with biaxial orientation processes consolidating supply chain influence around capable resin producers.
- Biopolymer Processing:Catalytic conversion of 2,5-furandicarboxylic acid and monoethylene glycol into polymer-grade resin. Ring-opening polymerization requires specialized catalyst systems that elevate unit costs versus commodity PET at current demonstration scale.
- Film Blowing:Extrusion of tubular film for flexible packaging applications with lower barrier performance requirements than biaxially oriented variants.
- Extrusion Coating:Application of molten PEF as a barrier layer onto paper or polymer substrates for multi-material laminates.
- Injection Molding:Conversion of bottle-grade resin into preforms for stretch blow molding of rigid containers.
Biopolymer Processing absorbs the greatest capital deployment; Film Blowing is gaining share fastest as converters seek lower-threshold entry points for bio-based material trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for FDCA monomers concentrates in European pilot facilities while consumption demand spreads across German packaging converters, North American beverage brand owners, and Asian electronics manufacturers seeking bio-based barrier solutions.
Germany
Modified atmosphere meat and cheese packaging drives film trials at flexible packaging converters in the Rhine-Ruhr industrial corridor. The EU Green Deal's packaging and packaging waste regulation mandates recycled content thresholds that bio-based materials help satisfy. Brand owners in Hamburg and Frankfurt are consolidating specification decisions at headquarters level to align private label sustainability commitments with science-based targets.
United States
Beverage packaging applications remain underexploited as brand owners await FDA food-contact notification clearance for carbonated soft drink and bottled water segments. The U.S. Food and Drug Administration maintains notification protocols that PEF producers must navigate for commercial adoption. Electronics manufacturers in California and Texas are piloting industrial protective films with extended weathering resistance specifications.
Japan
Biaxially oriented film development leverages established polymer processing expertise in the Osaka-Kobe industrial zone. METI supports bio-based material substitution through national sustainability procurement guidelines for consumer goods packaging. Toray Industries anchors technical credibility among packaging engineers evaluating high-performance barrier alternatives.
Netherlands
Avantium N.V. anchors its position through proprietary YXY technology for 2,5-furandicarboxylic acid production in the Chemelot chemical cluster near Geleen. ECHA REACH registration requirements for novel monomers impose multi-year evaluation timelines that filter the competitive field. Pharmaceutical companies in the Benelux region are piloting bottle-grade resins for mono-material blister packs that simplify hospital waste sorting.
China
Electronics manufacturing logistics generate demand for industrial protective films with oxygen barrier specifications in the Yangtze River Delta and Pearl River Delta clusters. NMPA and national standards bodies are developing bio-based polymer certification frameworks aligned with dual carbon goals. Domestic converters are evaluating film-grade resin samples for downgauged barrier applications in consumer electronics shipping.
Polyethylene Furanoate Films Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the PEF value chain, creating a tiered structure where resin producers, film extruders, and packaging converters occupy distinct competitive positions. The field compresses around three strategic archetypes: integrated chemical producers with catalytic FDCA platforms, specialized film manufacturers with biaxial orientation capabilities, and downstream packaging converters with brand owner qualification relationships. Dominant competitive moves include strategic partnerships between monomer producers and film extruders, plus capacity reservation agreements that lock in resin availability ahead of commercial scale-up.
Among European-based specialists, Avantium N.V. and AVA Biochem AG occupy positions within the catalytic platform tier, representing divergent approaches to FDCA production scale. Toray Industries, Inc. anchors the film manufacturing segment, exemplifying the biaxial orientation expertise required for high-barrier food packaging applications. These three companies represent the core competitive anchors around which downstream qualification partnerships and supply agreements are consolidating.
| Leading Market Players |
|---|
| AVA Biochem AG |
| Toray Industries, Inc. |
| Avantium N.V. |
| Origin Materials |
| Swicofil AG |
| Sulzer Ltd. |
| ALPLA Werke Alwin Lehner GmbH & Co. KG |
| BASF SE |
| Toyobo Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Food packaging converters in Germany and the Benelux region command substantial pricing leverage through centralized procurement functions that negotiate long-term offtake agreements for film-grade PEF resin. This buyer concentration compresses margin capture for FDCA monomer producers while rewarding extruders with proven biaxial orientation yield consistency.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade film tiers accelerates as ECHA REACH registration timelines extend qualification cycles and elevate compliance burdens. Three-tier pricing structure across certified pharmaceutical, food-contact, and industrial grades separates segments by barrier performance specifications and regulatory dossier completeness. Pricing pressure stems from limited resin availability at commercial scale, forcing converters to absorb premium markups for qualified batches. Industrial film buyers exhibit highest price sensitivity due to commoditized specifications, while pharmaceutical packaging procurement tolerates substantial premiums for mono-material compatibility.
Supply Chain Analysis
Freight costs for FDCA monomer shipments from Netherlands pilot facilities to German extrusion plants concentrate supply chain risk around Rhine-Ruhr logistics corridors. Production gravity centers on the Netherlands, Germany, and Japan, with each node serving distinct regional converter networks. Raw material flows draw from lignocellulosic biomass feedstocks, catalytic hydrogenation inputs, and specialized polymerization catalyst systems. Single-source vulnerability for commercial-scale FDCA creates bottleneck exposure as brand owner conversion timelines activate. Distribution runs through direct mill relationships with tier-one packaging converters, bypassing commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDCA monomer supply scarcity props pricing power for qualified resin producers, compressing the window for downstream converters to secure volume commitments before committed brand launches activate.
For Market Incumbents: Acquire biaxial orientation yield optimization expertise to defend barrier performance credibility against emerging bio-based polyester alternatives. Secure backward integration into catalytic FDCA production or lock in multi-year offtake agreements with Avantium N.V. and AVA Biochem AG before capacity reservation windows close. ECHA registration acceleration represents the critical certification lever for pharmaceutical segment expansion. For New Entrants and Emerging Players: Begin with industrial protective film applications in Chinese electronics manufacturing corridors, where barrier specifications remain less stringent than food-contact or pharmaceutical tiers. Target co-extrusion coating partnerships with established flexible packaging converters rather than direct resin sales, reducing capital requirements for film-grade certification. Chloromethylfurfural platform licensing offers the most penetrable entry vector for feedstock cost competitiveness. For Investors and Strategic Acquirers: The window for entry favors integrated chemical producers with existing catalytic platform expertise and regulatory affairs infrastructure capable of sustaining multi-year ECHA dossier investment. FDCA monomer production assets with demonstrated pilot-scale yields represent the priority acquisition archetype. Signal to watch: FDA food-contact notification clearance for North American beverage packaging, which would trigger brand owner conversion timeline acceleration and resin availability crunches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FDCA Production | Captive monomer supply secures resin availability ahead of committed brand owner conversion timelines. |
| REACH Registration Acceleration | ECHA dossier completion filters competitive field to well-capitalized producers in pharmaceutical packaging. |
| Biaxial Orientation Yield Optimization | Toray Industries anchors technical credibility among skeptical packaging engineers evaluating barrier alternatives. |
| Long-term Supply Agreement with Converters | German flexible packaging consolidators lock in volume commitments through centralized procurement functions. |
| Chloromethylfurfural Platform Licensing | Origin Materials decouples resin economics from sugar crop price volatility through lignocellulosic feedstock conversion. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with film extrusion plant managers, pharmaceutical packaging procurement leads, and ECHA regulatory affairs specialists. Primary fieldwork combined with Cefic chemical industry reports, FDA food-contact notification databases, and EU packaging directive implementation documents. Bottom-up resin production estimates triangulated against top-down converter demand assessments across German, Dutch, and Japanese supply chains.
Segmentation granularity modeled product grade tiers, application end-uses, and manufacturing process technologies at the country-cluster level across the projection horizon. CAGRs derived from polymerization scale-up economics and downstream compounding capacity buildout trajectories. Forecast inputs incorporated REACH registration timeline scenarios and FDA notification pathway probabilities for North American beverage packaging adoption.
Underlying measurement precision varies by segment; food packaging volume estimates carry tighter precision than pharmaceutical applications where qualification cycles introduce uncertainty. Forecasts reflect assumptions regarding FDCA monomer commercialization timelines and brand owner sustainability commitment durability. Stakeholders should weight assumptions against their own operating context and polymerization scale-up partnerships.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Nylon Films for Liquid Packaging Market
Poly film
PET Lidding Films Market
Poly film
Metallized Film Market
Poly film
High Density Polyethylene Film Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Twist Wrap Film Market
Poly film
Waste Wrap Film Market
Poly film
Co Extruded Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Polycoated Packaging Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Starch-Based Plastic Films Market
Poly film
Laminated Packaging Films Market
Poly film
Blown Film Extruder Market
Poly film
Easy Peel Film Packaging Market