
 High Density Polyethylene Film Market | 2026-2036
High Density Polyethylene Film Market Size, Share, and Industry Trends Forecast 2026-2036
High Density Polyethylene Film Market Foresight
Consolidation among North American food packaging converters is repositioning procurement leverage toward larger volume commitments with resin-integrated film suppliers. Berry Global Group leverages captive polyethylene resin access and multi-site blown film capacity to sustain cost-advantaged supply contracts with retail grocery chains. Amcor PLC anchors its position through pharmaceutical and food-grade certification breadth, competing on compliance rather than price. Sealed Air Corporation specializes in automated packaging system integration, extending HDPE film sales through equipment-tied supply agreements.
High density polyethylene film is a thermoplastic polymer sheet manufactured through blown or cast extrusion of ethylene monomer, yielding a material with density ranging from 0.941 to 0.965 g/cm³, high tensile strength, and moisture barrier properties essential for protective and containment applications. The film serves primary industrial purposes in food packaging, agricultural mulching, construction vapor barriers, and consumer goods overwrap where stiffness, chemical resistance, and sealability matter. Food grade HDPE film commands the dominant value share due to stringent migration limits and contact-clearance requirements that sustain premium positioning over non-food grades. Agricultural film represents the fastest-expanding application segment, driven by silage wrap and greenhouse cover demand in water-stressed growing regions. Thickness segmentation above 50 micron captures concentrated margin pools, as heavy-duty construction and industrial liner applications tolerate limited substitution from thinner gauges.
The US FDA governs food-contact substances under 21 CFR, while EPA oversees resin manufacturing emissions under Clean Air Act Title V permits, together shaping formulation and plant siting decisions for domestic producers. REACH registration requirements in Europe constrain imported HDPE film formulations containing Substances of Very High Concern, redirecting supplier certification investments toward full composition disclosure. China's SAMR enforces GB standards for food packaging plastics, including specific migration limits that foreign exporters must validate through accredited testing. Stakeholders should monitor regulatory divergence between FDA, EFSA, and GB migration limit frameworks, as divergent testing protocols threaten to fragment film qualification costs and complicate multinational supply strategies.
Market Dynamics
Mono-material HDPE structures are displacing multi-layer laminates as EU recyclability mandates tighten, forcing converters to requalify entire film portfolios around single-polymer sealant and barrier combinations.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated recyclability thresholds redirect converter R&D spend toward pure HDPE formats, accelerating mono-material adoption across frozen food and dairy segments.
- Silage wrap demand in water-stressed agriculture:Israeli, Spanish, and Australian growers expand HDPE film coverage for moisture retention, driving above-trend volume in 50-micron-plus agricultural grades.
- Blown film line automation:Real-time gauge control and automatic die adjustment reduce thickness variation, enabling downgauging without sacrificing tensile performance in industrial liner applications.
Market Restraints
- Ethylene feedstock volatility:Naphtha and ethane price swings compress film extruder margins, particularly for non-integrated processors lacking captive cracker supply.
- REACH Substances of Very High Concern disclosure:Full composition certification requirements for European import entry raise qualification costs and extend supplier onboarding timelines by 4-6 months.
- Mechanical recycling contamination limits:Post-consumer HDPE film streams carry adhesive and print residues that degrade regranulate quality, constraining closed-loop supply availability.
Strategic Opportunities
- Chemical recycling scale-up in Germany and Netherlands:Pyrolysis and depolymerization investments promise food-grade recycled HDPE feedstock, unlocking premium positioning for circular-certified film.
- Pharmaceutical cold-chain expansion:Temperature-stable HDPE formats gain traction in vaccine transport pouches and diagnostic kit overwrap, displacing PVC where migration limits tighten.
- Direct converter-to-retailer contracting:Large grocery chains bypass distributor layers to negotiate volume commitments with film extruders, capturing 8-12 point margin compression.
Industry Challenges
- Food-contact migration testing capacity:Accredited laboratories face 12-16 week backlogs for GB standard validation, delaying Chinese market entry for Western film suppliers.
- Blown film technician scarcity:Experienced die technicians and process engineers command 25-35% wage premiums, constraining capacity expansion at mid-tier extrusion operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density Polyethylene Film Market |
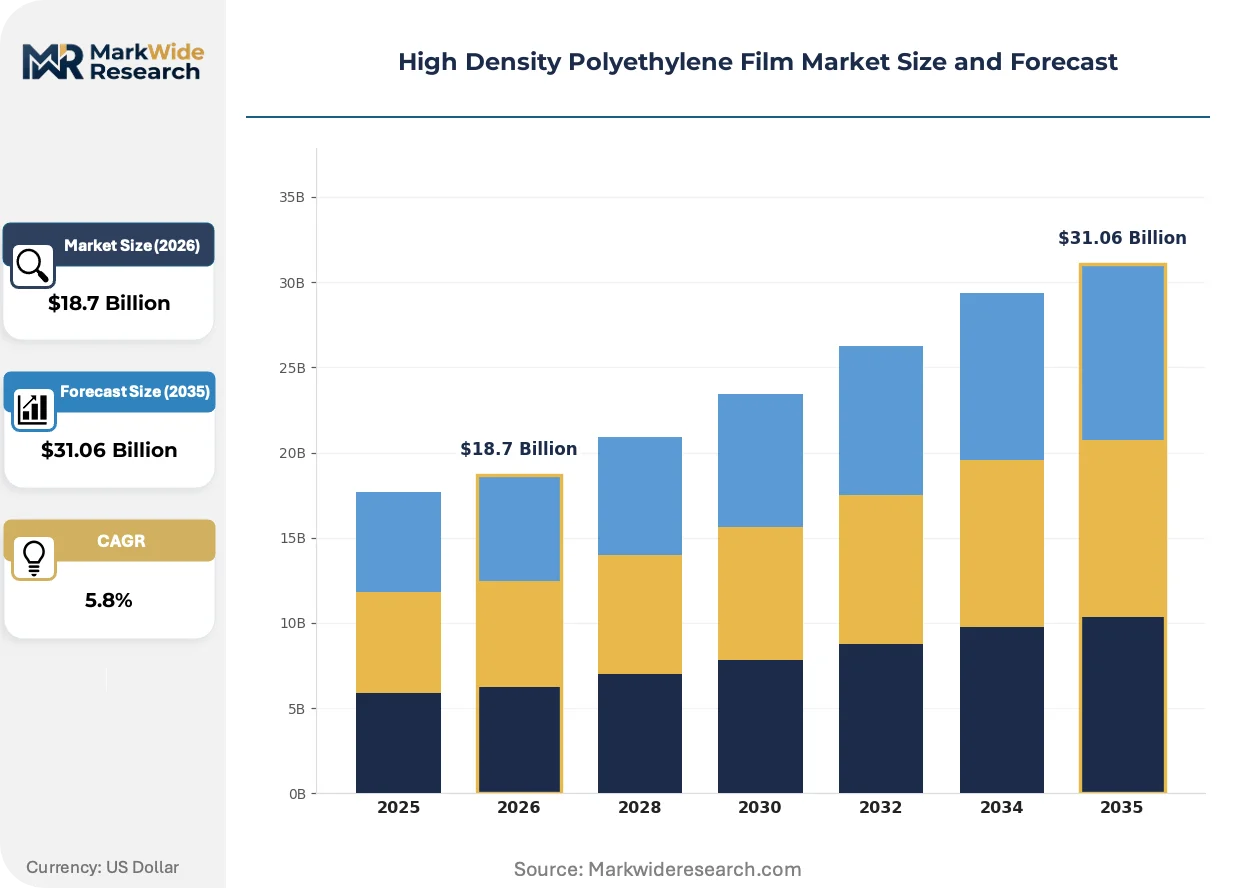
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Food Grade, Food Grade, Agricultural Film, Stretch Film End Use Industry: Packaging, Agriculture, Consumer Goods, Construction Thickness: Below 10 Micron, 10-20 Micron, 20-50 Micron, Above 50 Micron Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Nova Chemicals Corp., SIGMA Plastics Group, Berry Global Group, SINGHAL Industries Private Limited, Novolex Holdings, Amcor PLC, Dunmore Corp., Winpak, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density Polyethylene Film Market Shifts & Advancements
Digital printing and barrier coating technologies are converging to enable short-run customization, collapsing minimum order quantities and compressing film converter response times to brand packaging redesign cycles.
Metallocene-catalyzed HDPE resins are integrating into high-clarity food wrap formulations, delivering puncture resistance equivalent to linear low-density polyethylene while maintaining the stiffness and moisture barrier of conventional high-density grades. Premium snack and confectionery brands in Japan and South Korea are adopting these materials for transparent stand-up pouches. The technology is integrating formerly separate film converter and resin supplier specification workflows into joint development agreements.
China's SAMR enforcement of GB 4806.7-2016 migration limits is tightening allowable extractables in food-contact films, compelling foreign exporters to reformulate antioxidant and slip additive packages. Domestic Chinese laboratories are gaining ISO 17025 accreditation for parallel testing, reducing validation dependency on European facilities. Agricultural film exporters to China now face dual certification requirements for both food-contact and soil-contact applications.
Retail grocery procurement teams are consolidating film specifications across private-label suppliers, replacing fragmented SKU-by-SKU purchasing with category-managed volume commitments. This concentration is compressing distributor margins and favoring extruders with multi-site capacity able to guarantee geographic redundancy. The shift is most visible in Germany and France, where Rewe and Carrefour have centralized flexible packaging tendering.
High Density Polyethylene Film Market Segmentation
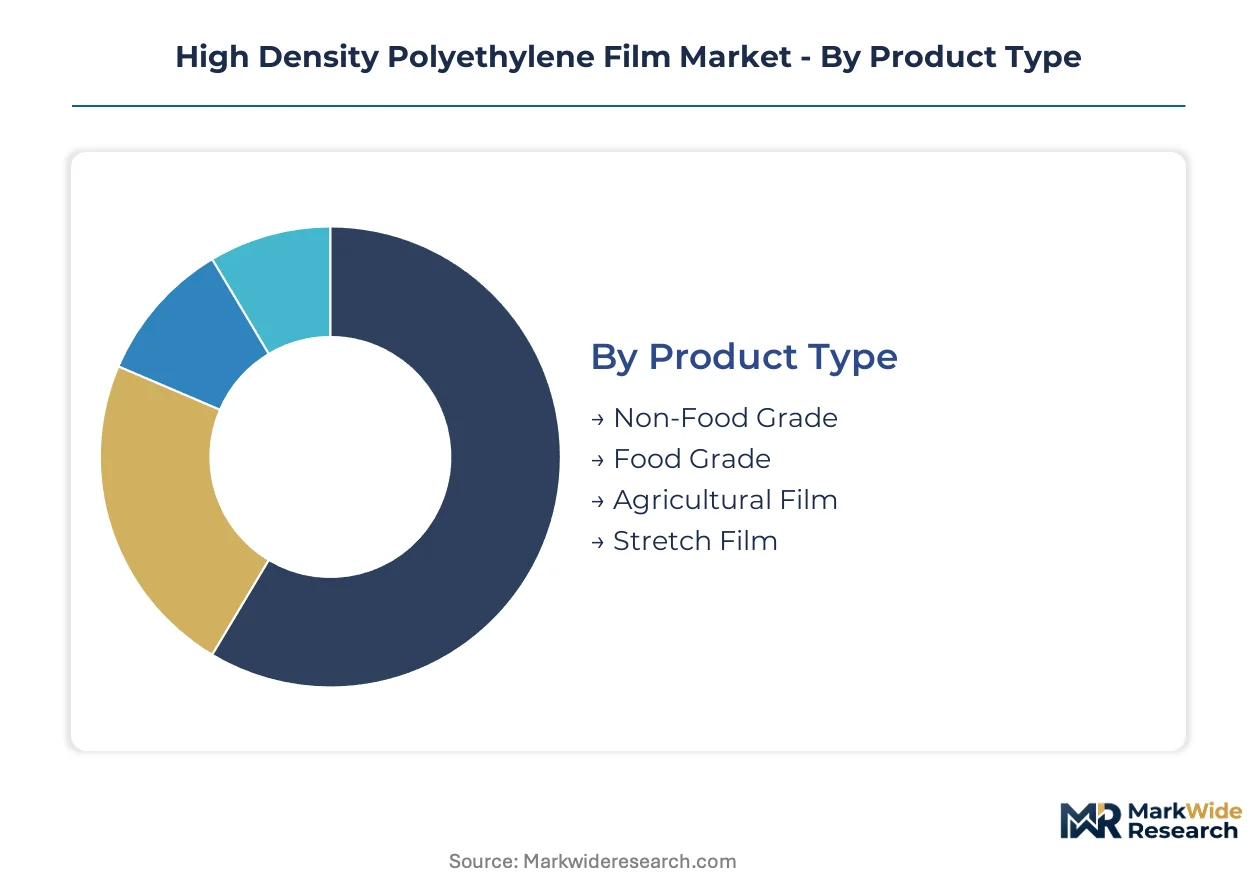
HDPE film buyers segment procurement by certification burden and performance tier, with food-contact approvals commanding price premiums and agricultural specifications driving volume scale. Thickness and distribution channel selections reflect end-use durability requirements and supply chain integration strategies.
Product Type:
Food-contact segments carry FDA 21 CFR and GB 4806.7-2016 migration testing obligations, while agricultural and industrial grades face soil-contact and mechanical performance standards instead.
- Food Grade:Manufactured with virgin resin and antioxidant packages meeting FDA 21 CFR and EFSA migration limits for direct food contact. Retail grocery chains in Germany and France consolidate procurement around certified suppliers to streamline private-label packaging compliance.
- Agricultural Film:UV-stabilized formulations for silage wrap and greenhouse cover applications, with 50-micron-plus gauges dominating Israeli and Spanish procurement for water-stressed growing regions. Silage wrap demand is expanding fastest among all product types.
- Non-Food Grade:Industrial liner and construction vapor barrier grades with reduced purity requirements, serving manufacturing and building sectors without food-contact certification costs.
- Stretch Film:Linear low-density polyethylene blends predominate, though HDPE variants gain traction in pallet wrap for stiffness-critical automated handling systems.
Leading the category by volume: Agricultural Film. Growing fastest: Food Grade.
End Use Industry:
Cost tier stratification separates premium-certified packaging from commodity construction and consumer goods applications.
- Packaging:Food, pharmaceutical, and industrial containment formats demanding sealability, clarity, and barrier performance. Mono-material HDPE structures displace multi-layer laminates as EU recyclability mandates tighten.
- Agriculture:Mulch films, silage wraps, and greenhouse covers where UV resistance and moisture retention determine replacement cycles. Israeli and Australian growers expand coverage acreage.
- Construction:Vapor barriers and concrete curing blankets tolerating lower clarity but requiring puncture resistance and thickness consistency above 50 micron.
- Consumer Goods:Overwrap and retail display films where stiffness and printability compete with lower-cost alternatives.
Packaging commands premium pricing. Agriculture delivers steepest expansion trajectory.
Thickness:
Volume concentration sits in mid-range gauges serving flexible packaging, while margin pools concentrate in heavy-duty industrial specifications.
- Above 50 Micron:Heavy-duty construction liners and agricultural silage wrap requiring puncture resistance and extended outdoor durability. Industrial buyers tolerate limited substitution from thinner gauges.
- 20-50 Micron:Standard food packaging and consumer goods formats where downgauging pressure meets seal strength requirements. Blown film automation enables thickness reduction without tensile sacrifice.
- 10-20 Micron:Lightweight overwrap and secondary packaging applications sensitive to resin cost fluctuations.
- Below 10 Micron:Specialized breathable films and medical packaging where gauge consistency and defect control dominate supplier selection.
Above 50 Micron captures concentrated margins. Below 10 Micron remains supply-constrained by technical capability.
Distribution Channel:
Customer type and procurement scale determine channel selection, with large converters bypassing intermediaries.
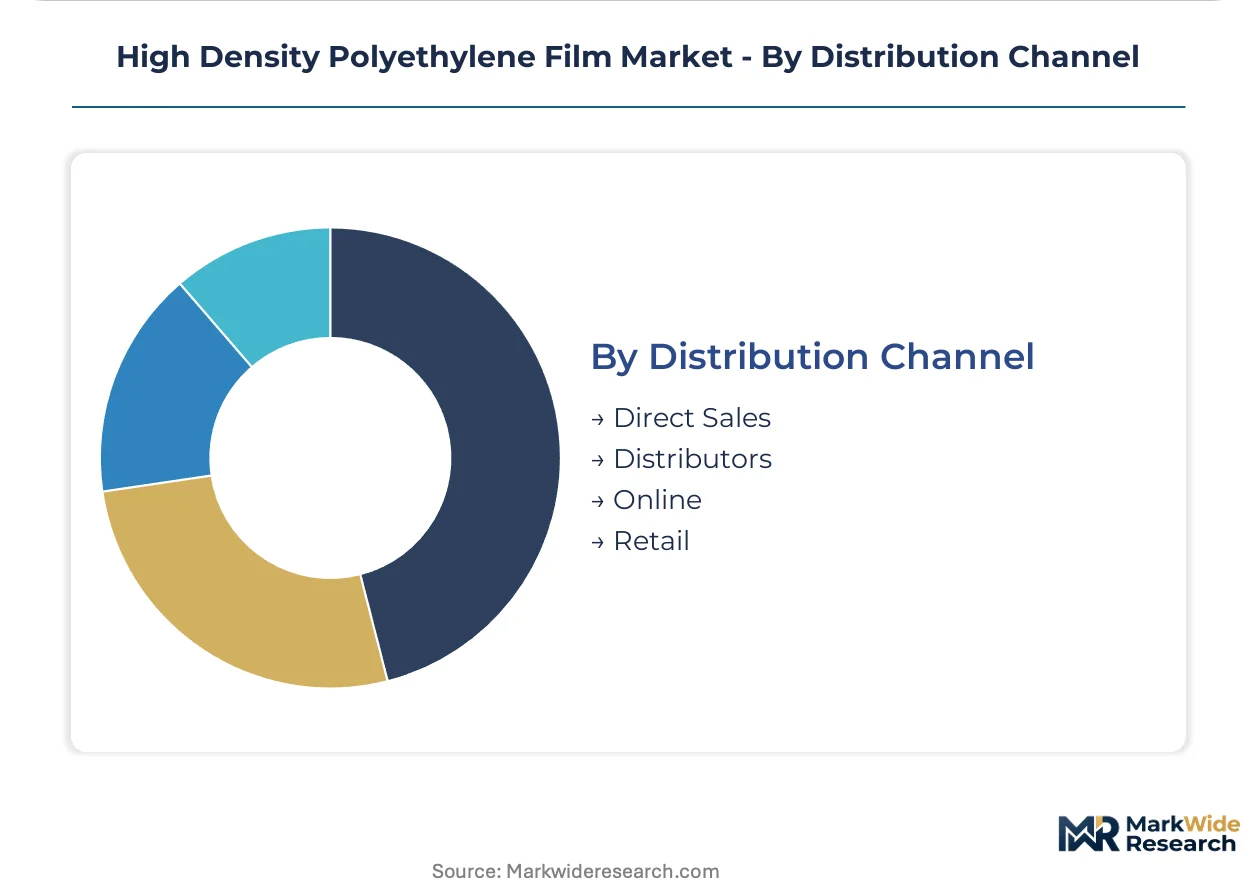
- Direct Sales:Volume commitments between film extruders and retail grocery chains, pharmaceutical packagers, and agricultural cooperatives. Rewe and Carrefour centralized tendering eliminates distributor layers.
- Distributors:Regional stocking for mid-tier converters and smaller agricultural buyers requiring technical support and mixed-SKU fulfillment.
- Online:Emerging platform for standardized industrial grades and sample procurement, constrained by freight economics for bulk film rolls.
- Retail:Limited to consumer-scale film products and small-format agricultural supplies through farm supply stores.
Direct Sales is gaining share fastest. Distributors face margin compression from converter-retailer contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the highest volume of HDPE film demand, with domestic blown film capacity serving both local food brands and export-oriented agricultural buyers. The EU Packaging and Packaging Waste Regulation is redirecting converter procurement toward mono-material structures across member states.
China
Domestic food packaging brands and agricultural film exporters drive procurement volume in the Yangtze River Delta cluster. SAMR enforces GB 4806.7-2016 migration limits that compel foreign suppliers to reformulate additive packages. Qingdao and Shanghai host expanding blown film capacity serving both local dairy converters and Israeli agricultural buyers seeking silage wrap.
United States
Retail grocery chains consolidate flexible packaging specifications across private-label suppliers, favoring multi-site extruders. FDA governs food-contact substances under 21 CFR while EPA oversees resin manufacturing emissions under Clean Air Act Title V permits. The Gulf Coast petrochemical corridor anchors captive polyethylene supply for integrated film producers.
Germany
Rewe and Carrefour have centralized flexible packaging tendering, eliminating distributor layers from procurement chains. ECHA REACH registration requirements constrain imported formulations containing Substances of Very High Concern. The Ruhr industrial region hosts chemical recycling pyrolysis investments promising food-grade recycled HDPE feedstock.
Israel
Water-stressed agricultural operations expand HDPE film coverage for moisture retention in silage wrap and greenhouse applications. The national agricultural regulator enforces soil-contact standards alongside food-contact migration limits for dual-use films. The Negev Desert growing region drives above-trend volume in 50-micron-plus UV-stabilized grades.
India
Agricultural cooperatives and food packaging converters scale procurement as domestic blown film automation improves gauge control. BIS standards govern industrial film specifications while FSSAI regulates food-contact migration limits. The Gujarat chemical belt concentrates extrusion capacity serving both local dairy brands and Middle East export markets.
High Density Polyethylene Film Market Competitive Landscape
North American producers anchor the resin-integrated tier; European specialists hold certification-advantaged positions in pharmaceutical and food-grade segments. The vendor base stratifies across three archetypes: captive resin suppliers with multi-site blown film capacity, compliance-focused converters competing on certification breadth, and equipment-tied suppliers extending film sales through automated packaging system integration. Dominant competitive moves include direct converter-to-retailer contracting that bypasses distribution layers, and backward integration into polyethylene resin production.
Among North American resin-integrated players, Nova Chemicals Corp. and Berry Global Group exemplify the captive supply archetype. Amcor PLC occupies a position within the compliance-focused tier, while Sealed Air Corporation represents the equipment-tied integration model. These three companies illustrate how geographic origin and structural configuration shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| Nova Chemicals Corp. |
| SIGMA Plastics Group |
| Berry Global Group |
| SINGHAL Industries Private Limited |
| Novolex Holdings |
| Amcor PLC |
| Dunmore Corp. |
| Winpak |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation recyclability mandates gate qualified supply access and premium-tier pricing for mono-material HDPE film structures. Converters lacking certified mono-material portfolios face exclusion from retail grocery chain procurement, while resin-integrated suppliers command 8-12 point margin premiums through direct contracting.
Pricing Analysis
Volume concentration in agricultural film runs counter to margin capture in food-grade and heavy-duty industrial specifications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-contact grades from agricultural UV-stabilized formats and non-certified industrial liners. Price differentiation hinges on migration testing burden and captive resin access, with non-integrated extruders absorbing ethylene feedstock volatility. Cost compression in standard-grade packaging intensifies as blown film automation enables downgauging without tensile sacrifice. Agricultural cooperatives exhibit highest price sensitivity; pharmaceutical cold-chain buyers tolerate premium positioning for temperature-stable certification.
Supply Chain Analysis
Dual-sourcing requirements from Rewe, Carrefour, and centralized retail procurement teams mandate multi-supplier qualification across at least two extrusion sites. Supply concentrates in China, the United States, and Germany, with the Yangtze River Delta, Gulf Coast petrochemical corridor, and Ruhr industrial region anchoring blown film capacity. Raw material dependencies center on ethylene monomer, naphtha and ethane feedstocks, and metallocene catalyst systems. Single-source vulnerability persists in specialized antioxidant and slip additive packages subject to REACH Substances of Very High Concern disclosure. Distribution runs through direct converter-to-retailer contracting that eliminates traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive polyethylene resin access determines cost position and procurement leverage. Players are pursuing backward integration into ethylene cracker assets to secure feedstock margin control.
For Market Incumbents: Deploy captive resin access to sustain cost-advantaged supply contracts with consolidating retail grocery chains. Expand multi-site blown film capacity in the Yangtze River Delta and Gulf Coast corridors to guarantee geographic redundancy against single-source disruption. Deepen certification breadth across FDA, EFSA, and GB 4806.7-2016 migration limits to defend pharmaceutical and food-grade positioning from compliance-focused European specialists. For New Entrants and Emerging Players: Capture pharmaceutical cold-chain expansion as the most penetrable white-space segment, where temperature-stable HDPE formats displace PVC in vaccine transport pouches. Target Israeli and Australian agricultural cooperatives seeking 50-micron-plus UV-stabilized silage wrap for water-stressed growing regions. Pursue equipment-tied supply agreements with automated packaging system integrators to bypass established distributor relationships. For Investors and Strategic Acquirers: Chemical recycling pyrolysis investment announcements in Germany and the Netherlands are the leading indicator that food-grade recycled HDPE feedstock will unlock premium circular-certified positioning. Long-term viability centers on resin-integrated extruders with multi-site capacity and full composition disclosure capabilities. Watch for REACH registration completion timelines as the inflection signal for European market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Production | Captive feedstock supply from Gulf Coast crackers secures margin insulation against naphtha volatility. |
| Multi-Site Blown Film Capacity Expansion | Geographic redundancy in Yangtze Delta and Ruhr regions satisfies dual-sourcing mandates from Rewe and Carrefour. |
| GB 4806.7-2016 Certification Investment | Parallel testing through ISO 17025-accredited Chinese laboratories accelerates SAMR validation for dairy converter supply. |
| Chemical Recycling Joint Venture | Pyrolysis partnerships in Germany unlock food-grade recycled HDPE positioning under EU circular packaging mandates. |
| Direct-to-Retailer Contracting | Bypassing distributor layers captures 8-12 point margin compression from centralized Carrefour and Rewe tendering. |
Research Methodology
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone for capacity and procurement pattern analysis. Primary interviews with blown film plant managers, retail grocery category buyers, agricultural cooperative procurement leads, and resin supplier technical directors combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling of extrusion capacity, resin consumption patterns, and end-use demand segments anchored the analytical lens against top-down macroeconomic and regulatory scenario testing. Segmentation dimensions included product grade tier, thickness specification, end-use industry, and regional production hub. CAGRs were derived from trend extrapolation of volume commitments and substitution elasticity across the projection horizon. Industry-specific forecast inputs incorporated ethylene feedstock cost trajectories and EU regulatory compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH disclosure expansion and chemical recycling scale-up rates. Forecasts reflect assumptions around mono-material adoption velocity and migration testing laboratory capacity expansion. Deviation in SAMR enforcement intensity or pyrolysis investment completion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PP Film Blowing Machine Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Craft Plastic Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
North America BOPP Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Cleanroom Film and Bags Market
Poly film
Forming Films Market
Poly film
North America Plastic Film Packaging Market
Poly film
China Plastic Packaging Film Market
Poly film
North America Polyimide Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Global Reclosable Films Market