
 Starch-Based Plastic Films Market | 2026-2036
Starch-Based Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Based Plastic Films Market Analysis
Subscription-based composting certification and traceability software is broadening what converters sell beyond raw film rolls. Novamont SPA leverages its integrated Mater-Bi supply chain to dominate European compostable film supply. BASF SE sustains R&D intensity across biodegradable polymer blends for high-barrier applications. Corbion anchors global lactic acid supply that underpins adjacent starch-lactic acid copolymer films.
Starch-based plastic films are thermoplastic materials formulated from native or modified starch blended with synthetic polymers or plasticizers, typically processed via blown film extrusion or cast film methods to achieve controlled moisture barriers and tensile properties for protective packaging. Their primary commercial purpose is to replace conventional polyethylene in applications requiring biodegradation within industrial composting or soil environments. Biodegradable films currently occupy the largest volume share due to established industrial composting infrastructure, while edible films represent the fastest-expanding margin pool as pharmaceutical and nutraceutical coating applications multiply. Water-soluble films are concentrating demand in agricultural chemical dosing and laundry pod segments where dissolution kinetics determine performance premiums.
The EU Green Deal, REACH, and F-Gas Regulation collectively mandate phased reduction of fossil-derived single-use plastics while establishing compostability certification requirements that starch film producers must satisfy for market access. FDA food contact notifications and USDA bio-preferred procurement standards shape parallel compliance pathways in North American food packaging segments. Stakeholders must monitor how composting infrastructure buildout pace in specific municipalities affects realized film degradation rates versus certified laboratory conditions.
Market Dynamics
The EU Green Deal's phased plastic reduction mandates are compressing converter decision timelines, forcing immediate capital allocation toward certified compostable film lines while legacy polyethylene assets face accelerated obsolescence.
Growth Catalysts
- REACH framework amendments:The European Chemicals Agency's expanded substance restrictions are disqualifying conventional multilayer films from food contact applications, redirecting procurement toward starch-polymer laminates that meet migration limits.
- Pharmaceutical coating demand:Nutraceutical manufacturers in Germany and France are specifying edible starch films for probiotic encapsulation, creating specification pull that converters are racing to fulfill.
- Blown film extrusion advances:Twin-screw processing equipment now achieves moisture barriers below 10 g/m²/day, matching mid-grade polyethylene performance for dry food applications.
Market Restraints
- Glycerol plasticizer volatility:Biodiesel co-product supply fluctuations from Southeast Asian palm oil processing are destabilizing input costs for flexible film formulations.
- Industrial composting infrastructure gaps:Municipal facilities in Eastern European member states lack the temperature-controlled aeration systems required for certified film degradation, creating geographic demand ceilings.
- Polyhydroxyalkanoate substitution:Marine-biodegradable PHA films from fermentation routes are capturing premium single-serve packaging specifications where home composting claims command price premiums.
Strategic Opportunities
- Italian converter consolidation:The Po Valley packaging cluster offers acquisition targets with established Mater-Bi tolling relationships and EN 13432 certification in-house.
- Agricultural chemical dosing films:Water-soluble starch formats for pesticide unit-dose packaging are displacing polyvinyl alcohol in French viticulture and German specialty crop applications.
- USDA BioPreferred procurement:Federal purchasing mandates for biobased content are opening institutional foodservice channels that European producers can access through US tolling partnerships.
Industry Challenges
- Composting certification timeline compression:TÜV Austria and DIN CERTCO testing queues now exceed 14 months, delaying product launches and locking working capital in pre-revenue inventory.
- Retrofitting legacy cast film lines:Starch's shear sensitivity and moisture absorption require screw redesigns and in-line drying systems that disrupt continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Based Plastic Films Market |
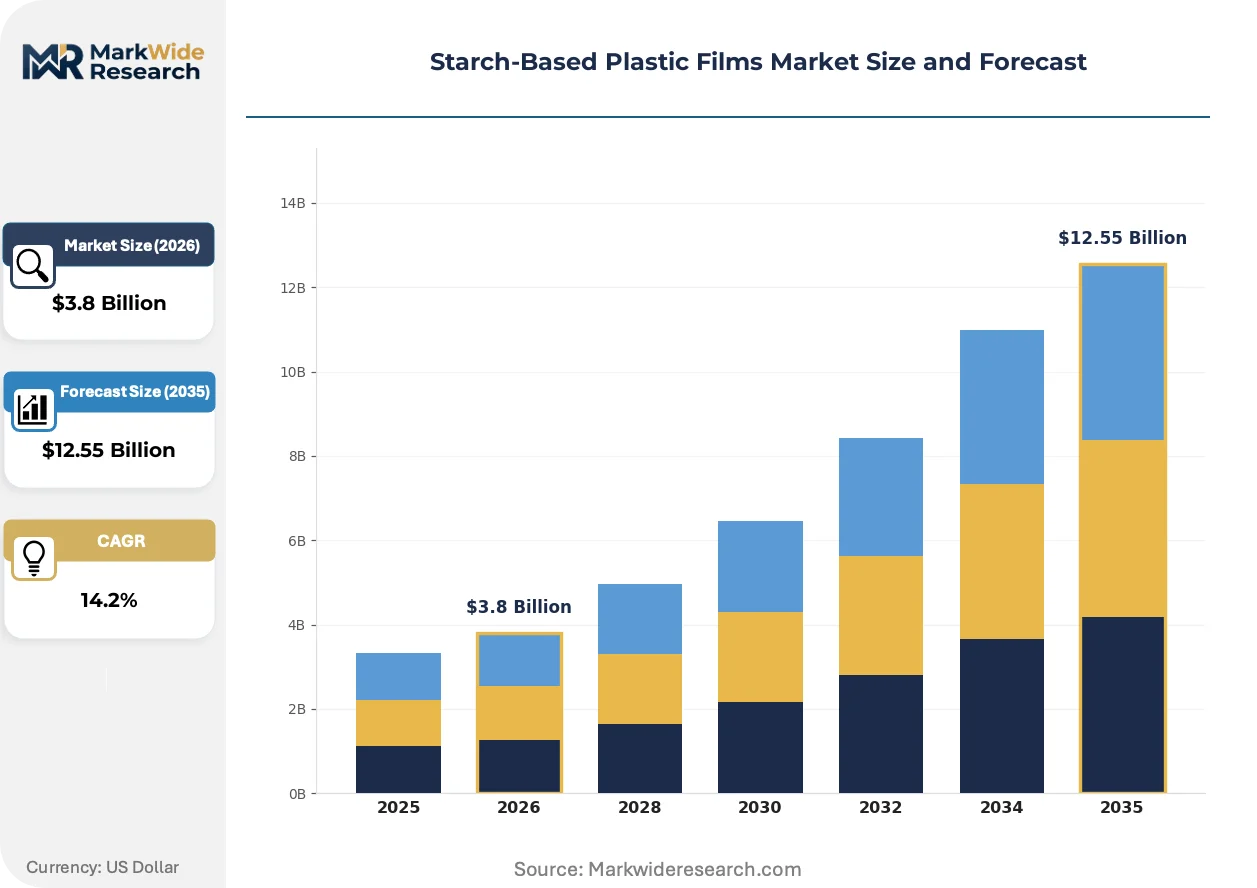
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Films, Compostable Films, Water-Soluble Films, Edible Films End User: Food Packaging, Agricultural Films, Electronics Packaging, Medical Applications Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors Feature: Barrier Properties, Mechanical Strength, Transparency, Customizability |
| Companies Covered | BASF SE, Novamont SPA, Cardia Bioplastic, Biome Bioplastics Limited, Toray Industries Inc, Corbion, Rodenburg Biopolymers, Nihon Cornstarch Corporation, BIOTEC GmbH & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Based Plastic Films Market Emerging Trajectories
Active packaging functionality and blockchain traceability are merging with base film specifications, transforming what converters must deliver from commodity rolls to certified, data-rich product systems.
Modified starch nanocrystal reinforcement is converging with conventional thermoplastic starch extrusion to yield films with puncture resistance matching oriented polypropylene. Snack food packagers in the Netherlands and Belgium are piloting these structures for brittle product protection. The technology is compressing the performance gap that has restricted starch films to low-stress applications.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant coatings from conventional flexible packaging. The European Food Safety Authority's 2023 opinion on PFAS migration has accelerated reformulation timelines. High-barrier starch-lipid composite films are capturing the displaced specifications in bakery and fried food segments.
Retail compliance programs are consolidating supplier bases around vertically integrated producers with captive composting certification. French supermarket chains Carrefour and Intermarché now require batch-level traceability data. German discount retailers are following with similar mandates, concentrating procurement among converters who control both film production and certification documentation.
Starch-Based Plastic Films Market Segmentation
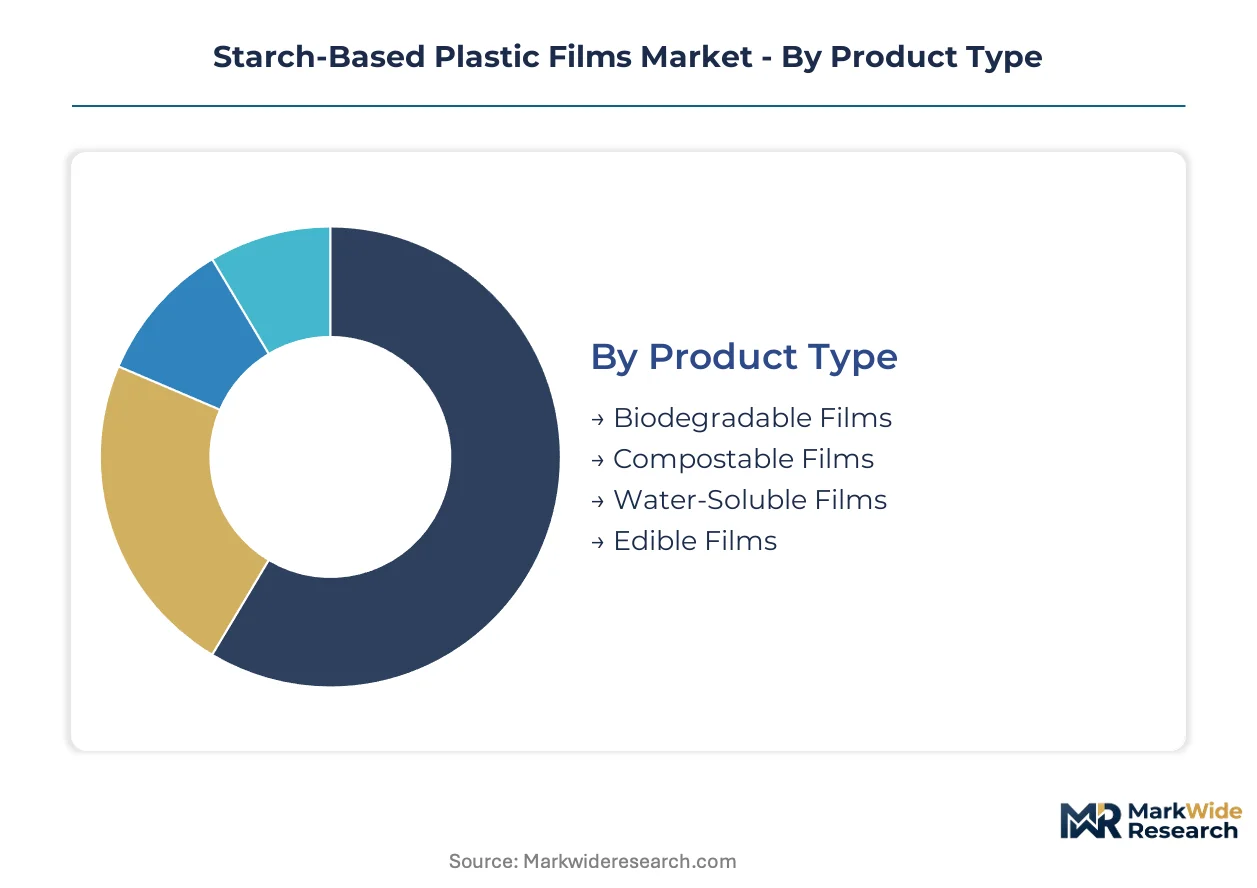
Segmentation in the starch-based plastic films market reveals how certification requirements, performance specifications, and channel economics fragment procurement patterns. Understanding these divisions exposes where converter investments align with regulatory timelines versus where margin compression threatens viability.
Product Type:
Certification burdens vary sharply across product types, with industrial composting standards governing biodegradable and compostable formats while edible films face food contact and pharmaceutical purity mandates.
- Biodegradable Films:Thermoplastic starch blends with synthetic aliphatic polyesters degrade under industrial composting conditions per EN 13432. German and Italian packaging converters dominate procurement for dry food pouches where municipal composting infrastructure supports end-of-life claims.
- Compostable Films:Stricter home composting certification under OK Compost HOME from TÜV Austria commands price premiums. French retail compliance programs now require this specification for private-label fruit and vegetable bags, compressing supplier qualification timelines.
- Water-Soluble Films:Cold-water dissolution kinetics determine agricultural chemical dosing applications. PVOH replacement in French viticulture drives specification pull.
- Edible Films:Pharmaceutical-grade purity for nutraceutical encapsulation requires migration testing beyond standard food contact protocols. German probiotic manufacturers specify these for moisture-sensitive active ingredients.
Biodegradable films sit at the top of the volume ranking, with edible films climbing the fastest.
End User:
Application-specific performance thresholds dictate which starch formulations converters prioritize, with food packaging demanding barrier precision and agricultural films tolerating lower specifications for biodegradation speed.
- Food Packaging:Oxygen and moisture barriers below 10 g/m²/day match mid-grade polyethylene for snack foods. Dutch and Belgian packagers pilot nanocrystal-reinforced structures for brittle product protection.
- Agricultural Films:Mulch films and controlled-release fertilizer coatings prioritize soil biodegradation rates over mechanical durability. Italian vegetable growers in Emilia-Romagna drive regional demand concentration.
- Electronics Packaging:Antistatic and moisture protection for semiconductors and components. REACH substance restrictions on halogenated flame retardants redirect procurement toward starch-based alternatives.
- Medical Applications:Sterile barrier properties and biocompatibility for device packaging and wound care. EMA medical device regulations govern migration limits for blood-contact applications.
Food packaging commands the largest procurement volumes, while agricultural films expand most quickly as soil biodegradation claims capture crop protection specification.
Distribution Channel:
Channel selection reflects order scale and technical service intensity, with direct relationships dominating certified compostable film procurement where documentation requirements exceed standard commercial transactions.
- Direct Sales:Converter-to-brand relationships for certified compostable films requiring batch-level traceability. Carrefour and Intermarché mandate this channel for supplier base consolidation.
- Online Retail:Small-volume sampling and rapid prototyping for specialty film developers. German mid-tier converters use this channel to reach artisanal food producers.
- Wholesalers:Standard-grade biodegradable films for price-sensitive agricultural applications. Eastern European distributors aggregate fragmented farm demand.
- Distributors:Technical stocking and local inventory for just-in-time food packaging lines. Italian Po Valley logistics clusters support this channel.
Direct sales channels handle the highest value throughput, with online retail gaining share fastest among emerging specialty film developers.
Feature:
Performance tier differentiation determines which starch modifications converters specify, with barrier properties commanding premium pricing and mechanical strength requirements driving nanocomposite adoption.
- Barrier Properties:Oxygen transmission rates and moisture vapor transmission rates determine shelf-life extension for oxygen-sensitive foods. Lipid-starch composites replace PFAS-coated conventional films in bakery applications.
- Mechanical Strength:Puncture resistance and tensile modulus specifications for automated packaging lines. Modified starch nanocrystal reinforcement matches oriented polypropylene performance.
- Transparency:Optical clarity for retail display and consumer acceptance. Glycerol plasticizer selection affects haze and gloss metrics.
- Customizability:Printability, seal strength, and dimensional stability for brand-specific packaging formats. Twin-screw extrusion advances enable rapid formulation adjustments.
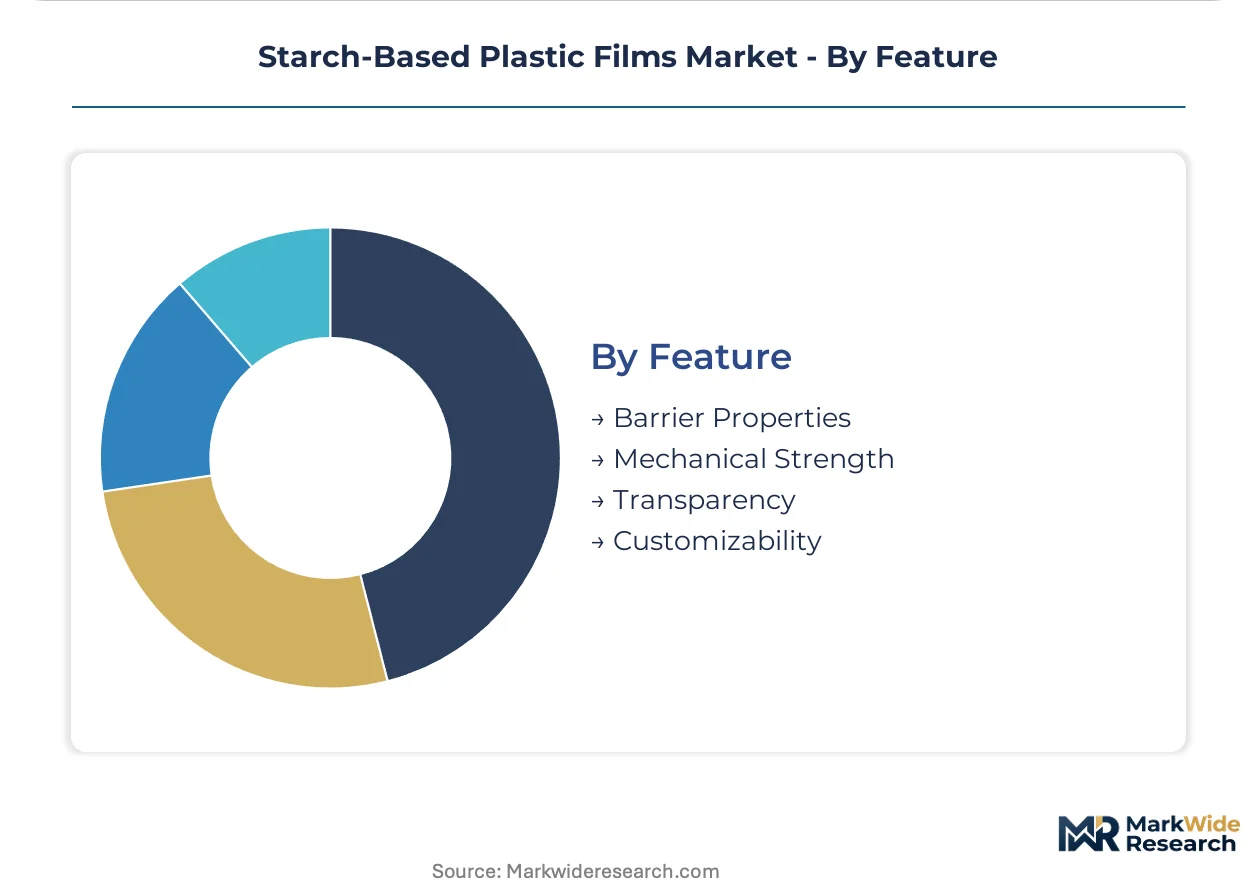
Barrier properties anchor the highest-margin specifications, with mechanical strength requirements expanding most quickly as snack food automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge in composting infrastructure maturity, with German municipalities operating temperature-controlled facilities while French retail chains drive home composting certification demand ahead of facility buildout.
Germany
Industrial composting infrastructure and pharmaceutical coating applications concentrate converter investment in the country. The EU Green Deal's plastic reduction mandates accelerate polyethylene asset obsolescence timelines. The Baden-Württemberg packaging cluster hosts twin-screw extrusion pilots achieving sub-10 g/m²/day moisture barriers for snack food specifications.
France
Retail compliance programs at Carrefour and Intermarché mandate batch-level traceability and OK Compost HOME certification for private-label produce bags. REACH framework amendments on PFAS migration redirect bakery packaging procurement toward starch-lipid composites. The Lyon-Avignon corridor anchors water-soluble film production for viticulture chemical dosing applications.
Italy
The Po Valley converter cluster offers established Mater-Bi tolling relationships and EN 13432 certification capabilities. Emilia-Romagna vegetable growers drive mulch film demand prioritizing soil biodegradation rates. Italian distributors aggregate fragmented agricultural demand through wholesaler channels serving Eastern European markets.
Netherlands
Snack food packagers pilot nanocrystal-reinforced starch structures matching oriented polypropylene puncture resistance. The country's national pharmaceutical regulator enforces EMA medical device migration limits for edible film encapsulation applications. Amsterdam-Rotterdam logistics clusters support just-in-time technical stocking for food packaging lines.
United States
USDA BioPreferred procurement mandates open institutional foodservice channels for biobased content compliance. FDA food contact notifications shape parallel compliance pathways distinct from European frameworks. Midwest tolling partnerships enable European producers to access federal purchasing programs without domestic manufacturing assets.
Starch-Based Plastic Films Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated compounders controlling premium compostable film supply while tolling relationships dominate price-sensitive agricultural grades. Three archetypes define competitive positioning: integrated biopolymer producers with captive starch supply, converter-focused compounders relying on external certification, and fermentation-derived alternative suppliers capturing marine-biodegradable specifications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with acquisition activity concentrating in Italian Po Valley clusters possessing in-house EN 13432 capabilities.
Among European integrated producers, Novamont SPA exemplifies the captive supply chain archetype through its Mater-Bi compound dominance, while BASF SE occupies a position spanning biodegradable polymer blends for high-barrier applications. Corbion anchors global lactic acid supply that underpins adjacent starch-lactic acid copolymer film development. These three represent distinct strategic postures: regional vertical integration, diversified chemical R&D leverage, and upstream fermentation feedstock control.
| Leading Market Players |
|---|
| BASF SE |
| Novamont SPA |
| Cardia Bioplastic |
| Biome Bioplastics Limited |
| Toray Industries Inc |
| Corbion |
| Rodenburg Biopolymers |
| Nihon Cornstarch Corporation |
| BIOTEC GmbH & Co |
| Others |
Supply Flow & Price Mechanics
Twin-screw extrusion advances in Germany and Italy are compressing moisture barrier thresholds below 10 g/m²/day, simultaneously raising capital intensity for new entrants and concentrating pricing power among converters with certified production assets. This equipment transition feeds back into supply chain configuration, as batch-level traceability requirements from French retail chains force tolling relationships toward vertically integrated compounders who control both extrusion capacity and EN 13432 certification documentation.
Pricing Analysis
Capacity additions in Italy's Po Valley cluster are reshaping price floors for standard-grade biodegradable films, while premium compostable grades retain margin insulation through OK Compost HOME certification scarcity. Three-tier pricing structure across premium, standard, and economy levels separates certified home-compostable films from industrial-grade alternatives and uncertified commodity rolls. Cost compression in standard biodegradable tiers is intensifying because Eastern European converter expansion is flooding price-sensitive agricultural channels. Agricultural film buyers exhibit highest price sensitivity, while pharmaceutical nutraceutical manufacturers tolerate premium pricing for edible film purity specifications.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Milan, and Lyon operate hub-and-spoke patterns that aggregate fragmented converter output for just-in-time food packaging lines. Supply concentrates in Germany, Italy, and France, with Dutch logistics nodes serving as throughput arbitrage points for Belgian and Netherlands snack food packagers. Raw material dependencies center on native maize and potato starch feedstocks, glycerol plasticizers from Southeast Asian biodiesel co-processing, and synthetic aliphatic polyester blending resins. Single-source vulnerability runs through TÜV Austria and DIN CERTCO certification queues now exceeding 14 months. Distribution runs through direct converter-brand relationships for certified grades, with wholesaler channels handling price-sensitive agricultural volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The starch-based plastic films market compounds steadily as EU Green Deal mandates force polyethylene asset obsolescence timelines that guarantee replacement demand for certified compostable alternatives.
For Market Incumbents: Acquire Italian Po Valley converters with in-house EN 13432 certification capabilities to consolidate tolling relationships before competitor capacity additions compress margin pools. Polyhydroxyalkanoate fermentation-derived films threaten premium single-serve specifications; defend positioning through nanocrystal-reinforced starch structures matching oriented polypropylene puncture resistance. Backward integration into glycerol plasticizer supply hedges biodiesel co-product volatility destabilizing flexible film formulations. For New Entrants and Emerging Players: Launch via USDA BioPreferred tolling partnerships that access federal institutional foodservice procurement without domestic manufacturing asset requirements. Water-soluble starch formats for French viticulture pesticide unit-dose packaging represent the most penetrable white-space segment, displacing polyvinyl alcohol with dissolution kinetics advantages. German mid-tier artisanal food producers offer rapid prototyping channels through online retail sampling before scaling to direct converter-brand relationships. For Investors and Strategic Acquirers: Roll-up economics work for Italian converter specialists because certification queue bottlenecks create captive customer relationships that sustain pricing power. Long-term viability hinges on composting infrastructure buildout pace matching certified film supply expansion; acquisition targets should demonstrate established Mater-Bi tolling relationships rather than speculative capacity. Watch municipal temperature-controlled aeration system deployment in Eastern European member states as the inflection signal for geographic demand ceiling removal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Queue Investment | TÜV Austria partnership compresses 14-month testing timelines that currently lock working capital in pre-revenue inventory. |
| Backward Integration into Starch Supply | Captive maize and potato feedstock procurement hedges agricultural commodity volatility affecting thermoplastic starch input costs. |
| Nanocrystal Reinforcement R&D | Modified starch nanocrystal technology matches oriented polypropylene puncture resistance for snack food automation specifications. |
| USDA BioPreferred Tolling Partnership | Midwest tolling relationships enable European producers to access federal biobased procurement mandates without domestic manufacturing assets. |
| Water-Soluble Film Capacity Expansion | Cold-water dissolution kinetics capabilities capture French viticulture chemical dosing specifications displacing polyvinyl alcohol formats. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blown film extrusion equipment manufacturers, starch compound procurement leads at European packaging converters, EN 13432 certification auditors, and agricultural chemical dosing film specification managers with secondary validation against EU Green Deal regulatory filings, REACH framework amendment texts, TÜV Austria certification database records, and USDA BioPreferred procurement program disclosures. Bottom-up demand modeling from end-use application volumes and top-down supply validation from converter capacity announcements were triangulated to constrain forecast variance.
Segment-weighting applied product type, end user industry, distribution channel, and performance feature tier dimensions across the modeling period. CAGRs derived from regression analysis against historical adoption curves for comparable biopolymer transitions, with explicit modeling of composting infrastructure buildout pace as a demand ceiling variable and glycerol plasticizer cost volatility as a margin compression input.
Forecast precision tightens around the base case; tail outcomes carry wider variance under municipal composting facility deployment delays or accelerated polyhydroxyalkanoate fermentation cost reductions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Spain Plastic Packaging Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Global EVOH Films for Packaging Market
Poly film
India BOPP Films Market
Poly film
Polycoated Packaging Market
Poly film
Poly Tubing Market
Poly film
Isotropic Film Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Stretch Films Packs Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Colourless Polyimide Films Market
Poly film
PVC Film for Medical Market
Poly film
PE Foam Films Market
Poly film
Vinyl Films Market
Poly film
EVOH Encapsulation Film Market
Poly film
Foamed Polypropylene Films Market