
 Metallized Film Market | 2026-2036
Metallized Film Market Size, Share, and Industry Trends Forecast 2026-2036
Metallized Film Market Intelligence
Expertise in polymer science and vacuum deposition process engineering is bifurcating the competitive landscape. This separates commodity film producers from specialists in high-performance applications. UFlex Limited leverages its extensive manufacturing scale in flexible packaging materials to serve high-volume segments. In contrast, Toray Industries, Inc. differentiates through its focus on advanced polyester films for electronics and industrial applications.
Metallized film is a polymer substrate, such as polyester or polypropylene, coated with a thin layer of metal, typically aluminum. This vacuum metallizing process imparts high barrier properties against oxygen and moisture, as well as a reflective aesthetic. Flexible packaging applications represent the largest demand segment due to the material's protective qualities. Within product types, polypropylene film is experiencing significant uptake for its cost-effectiveness, while polyester film commands a premium in high-performance uses like electrical capacitors.
Regulations concerning food contact materials, such as those from the US FDA and the EU's REACH framework, govern material composition and safety. In India, standards set by the FSSAI influence the grade of metallized films used in food packaging, impacting market access. Decisions on investments in sustainable substrates and recyclable barrier technologies will determine long-term competitive positioning for manufacturers.
Market Dynamics
The primary force shaping the metallized film market is the bifurcation of expertise between commodity production and high-performance specialization. Advances in vacuum deposition engineering allow for enhanced barrier properties, separating mass-market producers from specialists serving demanding electronics and industrial sectors.
Growth Catalysts
- Flexible Packaging Demand:Expansion of the packaged food and beverage industry, particularly in India, drives volume consumption of metallized films for their shelf-life extension properties.
- Coating Technology:Advancements in high-speed roll-to-roll vacuum metallizing processes are lowering production costs and improving the consistency of the metal deposition layer, enhancing barrier performance.
- Food Safety Standards:Regulations like the US FDA's food contact material guidelines and the FSSAI's standards in India mandate the use of safe, high-barrier packaging, favoring metallized films.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, specifically polymer resins like polypropylene and polyester, as well as aluminum, directly impact manufacturing costs and profitability.
- Substitution Threat:Increasing performance from non-metallized barrier films, such as those with EVOH or PVDC layers, presents a viable alternative in some packaging applications.
- Technical Limitations:Susceptibility to flex-cracking can compromise the barrier integrity of the thin metal layer in certain high-flexibility packaging formats, limiting its application scope.
Strategic Opportunities
- Emerging Applications:Development of specialized films for flexible electronics, decorative surfaces, and insulation offers avenues for value-added growth beyond traditional packaging.
- Sustainable Substrates:Creating metallized films based on biodegradable or recycled polymer substrates aligns with circular economy goals and appeals to environmentally conscious brand owners.
- Pharmaceutical Packaging:Targeting the pharmaceutical blister pack market in Southeast Asia and Latin America represents a significant opportunity for high-barrier metallized films.
Industry Challenges
- Capital Intensity:The significant capital investment required for high-vacuum metallizing chambers and precision slitting equipment creates a high barrier to entry for new manufacturers.
- Regulatory Compliance:Adhering to the complex and evolving chemical safety regulations, such as the EU's REACH framework, necessitates extensive compliance resources and continuous material testing.
- Workforce Skills Gap:A shortage of skilled technicians and process engineers with expertise in vacuum deposition and polymer science can constrain production efficiency and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallized Film Market |
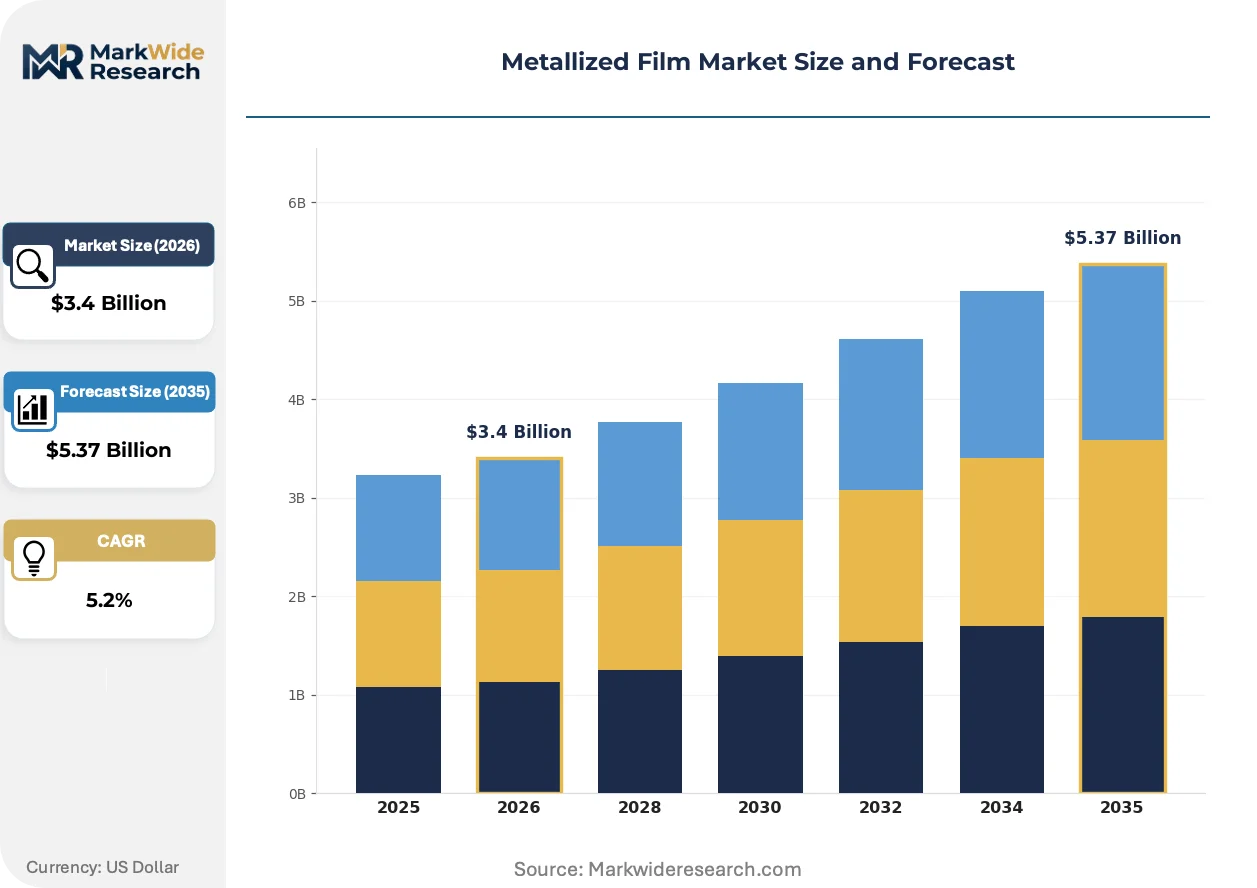
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Film, Polypropylene Film, Nylon Film, Polyethylene Film, Cellophane Film Application: Flexible Packaging, Insulation, Decoration, Printing, Automotive Components, Electrical Capacitors End Use Industry: Consumer Goods, Electronics Manufacturing, Construction, Agriculture, Packaging Industry Technology: Vacuum Metallizing, Chemical Metallizing, Sputtering, Roll-to-Roll Coating, Thermal Metallizing |
| Companies Covered | UFlex Limited, DUNMORE, Cosmo Films Ltd., Tredegars Corporation, Taghleef Industries, Jindal Poly Films Ltd., Polyplex Corporation Ltd., Flex Films, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallized Film Market Strategic Shifts & Innovations
Innovation is focused on reconciling the competing demands for enhanced performance and improved sustainability. This drives material science advancements in substrates and barrier layers, as well as process optimizations aimed at reducing waste and energy consumption in manufacturing.
Transparent high-barrier coatings, such as aluminum oxide (AlOx) or silicon oxide (SiOx), provide an alternative to opaque aluminum metallization. These coatings are being adopted by premium food producers who require product visibility through the package. This technology is fragmenting the high-barrier segment by creating a distinct performance tier between standard metallized films and basic transparent packaging.
The European Union's proposed Packaging and Packaging Waste Regulation (PPWR) is a significant driver of material redesign. This policy framework mandates design-for-recyclability, creating challenges for conventional multi-material metallized film structures. The flexible packaging segment is most affected, spurring research and development into mono-material solutions, such as metallized polypropylene films that are compatible with established recycling streams.
A shift toward smaller, more frequent orders from end-users in the specialty food and industrial sectors is altering supply chain dynamics. This pattern disrupts the traditional long-run production model favored by large-scale film manufacturers. The change creates an opening for specialized converters and regional distributors who can offer greater agility and shorter lead times, a trend most visible in North America and Europe.
Metallized Film Market Segmentation

Understanding the market for metallized film requires disaggregating demand across various product types, applications, and end-use industries. This granular view reveals distinct value propositions and competitive dynamics for manufacturers.
Product Type:
The geographic distribution of manufacturing capabilities influences predominant product types in regional markets. Countries like India leverage cost-effective films for domestic consumption, while export economies focus on specialized films.
- Polyester Film:This polymer substrate offers superior thermal stability and mechanical strength for demanding applications. Demand concentrates in East Asia's electronics manufacturing, driven by the need for high-performance dielectric materials in capacitors.
- Polypropylene Film:Known for its excellent moisture barrier and cost-effectiveness, polypropylene film dominates flexible packaging for food. Its widespread uptake in India's consumer goods market reflects a strong preference for economical, protective solutions.
- Nylon Film:Nylon films provide high tensile strength and puncture resistance for vacuum packaging of meat and cheese.
- Polyethylene Film:Polyethylene films offer good sealability and flexibility, metallized for lidding and protective liners.
- Cellophane Film:Derived from cellulose, cellophane film offers biodegradability and good barrier properties for sustainable packaging.
Polypropylene Film holds the largest share; Polyester Film shows strong momentum.
Application:
Demand for metallized films varies significantly by end-use application, with some segments prioritizing barrier performance and others aesthetic appeal. This differentiation influences material selection and processing.
- Flexible Packaging:This application represents the primary demand segment for metallized films, extending shelf-life for perishable goods through oxygen and moisture barriers. The packaged food and beverage industry in South Asia drives substantial volume consumption.
- Electrical Capacitors:Metallized films serve as dielectric layers in capacitors, offering high energy density and compact designs for electronics. Manufacturers in Germany and Japan require precise metallization for these components, ensuring reliability.
- Insulation:Metallized films contribute to thermal insulation in construction and automotive by reflecting radiant heat.
- Decoration:These films provide a metallic aesthetic for labels, gift wrap, and textiles, enhancing visual appeal.
- Printing:Metallized films serve as substrates for specialized printing, offering a reflective surface for high-impact graphics.
- Automotive Components:Films are used in automotive interiors for decorative trim and under-the-hood heat shielding.
Flexible Packaging commands the largest volume; Electrical Capacitors are expanding quickly.
End Use Industry:
The maturity of end-use industries shapes adoption patterns for metallized films, with established sectors driving consistent demand. This influences the innovation cycle for film manufacturers.
- Consumer Goods:This sector utilizes metallized films extensively for packaging food and personal care items, ensuring product freshness and visual appeal. The expanding retail landscape in India fuels consistent demand for high-barrier films.
- Electronics Manufacturing:Metallized films are critical components in various electronic devices, including flexible circuits, displays, and capacitors. Specialized film suppliers cater to stringent quality requirements of producers in South Korea and Taiwan.
- Construction:Metallized films integrate into insulation and vapor barriers, improving building energy efficiency.
- Agriculture:Films find application in agricultural mulches and greenhouses, regulating soil temperature and light.
- Packaging Industry:This industry directly consumes metallized films, converting them into finished packaging formats.
The Packaging Industry represents the largest consumer segment; Electronics Manufacturing shows steepest expansion.
Technology:
Production technologies for metallized films exhibit varying capital expenditure and operational costs, influencing the competitive landscape. Specialized processes enable enhanced barrier properties or unique finishes.
- Vacuum Metallizing:This established process evaporates metal, typically aluminum, in a vacuum chamber to deposit a thin layer onto a polymer substrate. Advancements in roll-to-roll metallizing enhance production efficiency and coating consistency.
- Roll-to-Roll Coating:This high-speed manufacturing method applies metal or barrier layers continuously onto flexible substrates, optimizing throughput and material handling. Its efficiency drives cost reductions for high-volume film production in North America.
- Chemical Metallizing:This technique involves chemical reduction of metal ions onto a substrate, used for conductive or decorative films.
- Sputtering:Sputtering deposits metal layers using plasma, offering precise control over film thickness for high-performance films.
- Thermal Metallizing:Thermal metallizing uses heat to evaporate and deposit metal for specific decorative or low-barrier applications.
Vacuum Metallizing remains the predominant technology; Roll-to-Roll Coating is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Food Safety and Standards Authority of India (FSSAI) influences the metallized film market by setting stringent food contact material standards. These regulations ensure safety and quality for packaging applications. Global demand patterns for metallized films are shaped by diverse regional requirements.
India
India's FSSAI standards significantly impact metallized film use in food packaging. Strong demand from the packaged food and beverage industry drives volume consumption. The consumer goods sector in Mumbai exemplifies this preference for economical, protective solutions.
Japan
Japan's electronics manufacturing sector drives demand for high-performance polyester films. The Ministry of Economy, Trade and Industry (METI) guides material specifications for advanced components. Capacitor producers in Tokyo require precise metallization for specialized applications.
United States
Demand in the United States reflects advancements in high-speed roll-to-roll coating technologies. The US FDA's food contact material guidelines mandate specific safety profiles for packaging. Packaging innovation clusters in Chicago focus on barrier performance improvements.
Germany
Germany's electrical capacitor industry requires specialized metallized films for energy storage. The EU's REACH framework governs chemical composition and material safety for these applications. Precision engineering firms in Bavaria specialize in high-performance dielectric film production.
South Korea
South Korea's electronics manufacturing drives significant uptake of specialized film suppliers. The country's industrial standards body ensures quality compliance for critical components. Major technology hubs in Seoul concentrate on advanced material development.
Metallized Film Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the metallized film market. This bifurcation separates commodity film producers, focusing on volume and cost-efficiency, from specialists in high-performance applications. These high-performance players target demanding sectors like electronics and industrial components. Competition within these tiers often involves optimizing production processes or investing in advanced material science. Companies pursue capacity expansion to meet growing demand and engage in portfolio diversification to capture niche segments.
Specialists in high-performance applications include Japan-based Toray Industries, Inc., which anchors advanced polyester films for electronics and industrial uses. Toray's focus exemplifies differentiation through material science and precise vacuum deposition. Conversely, UFlex Limited, an India-based company, represents the large-scale manufacturing archetype in flexible packaging materials, serving high-volume segments. UFlex leverages extensive production scale to address the broad consumer goods market. These distinct approaches highlight the market's segmentation by product capability and end-use focus.
| Leading Market Players |
|---|
| UFlex Limited |
| DUNMORE |
| Cosmo Films Ltd. |
| Tredegars Corporation |
| Taghleef Industries |
| Jindal Poly Films Ltd. |
| Polyplex Corporation Ltd. |
| Flex Films |
| Toray Industries, Inc. |
| Others |
Cost & Logistics Intelligence
A 30-day inventory cycle for metallized films reflects a balance between volatile raw material costs and the need for just-in-time delivery, influencing pricing power across the supply chain.
Pricing Analysis
Geographic price spreads for metallized films exhibit regional variations, driven by local production costs and demand dynamics. The dominant pricing model is contract-based long-term offtake, particularly for high-volume flexible packaging applications. Price differentiation stems from quality grade, specifically barrier performance, and the volume scale of orders. Pricing softness intensifies due to raw material volatility, impacting packaging industry buyers who demonstrate high price sensitivity, unlike electronics manufacturing clients.
Supply Chain Analysis
Logistics chokepoints in global shipping routes affect the timely delivery of polymer resins and aluminum, critical inputs for metallized film production. Supply concentration centers on manufacturing hubs in India for commodity films and Japan and Germany for specialized high-performance films. The market relies on polymer resins like polypropylene and polyester, alongside aluminum, making it susceptible to commodity price volatility. Distribution runs through direct sales channels to large flexible packaging converters and regional distributors for smaller, specialized orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metallized film market offers a defensive moat due to regulatory entrenchment, particularly with stringent food contact material standards. This structural advantage secures demand for compliant, high-barrier solutions.
For Market Incumbents:Fortify market position by investing in sustainable substrates and recyclable barrier technologies, especially against the threat of non-metallized film substitution. Expand manufacturing capacity in high-demand regions like India to leverage economies of scale. Leverage R&D to develop mono-material solutions compatible with circular economy goals.
For New Entrants and Emerging Players:A service-layer gap exists in fulfilling smaller, more frequent orders for specialty food and industrial sectors. Target specialized films for flexible electronics and decorative surfaces, where incumbents prioritize volume. Penetrate the specialty food packaging segment in North America and Europe by offering greater agility and shorter lead times.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core metallized film assets. The market offers long-term viability as an essential material for food packaging and electronics manufacturing. Acquire specialized converters possessing unique coating technologies or strong regional distribution networks. Watch for increased adoption rates of mono-material recyclable films as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meets rising demand for flexible packaging films in emerging markets like India. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns with circular economy goals for sustainable production. |
| Technology Licensing | Accesses advanced vacuum deposition techniques to enhance barrier properties and efficiency. |
| Joint Venture | Combines R&D capabilities to accelerate development of next-generation high-performance films. |
| Distribution Channel Expansion | Reaches new end-use industries and geographic regions for specialized film applications. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade association reports, government regulatory filings, and company annual reports. Primary interviews engaged R&D directors, procurement leads, production managers, and packaging engineers across the value chain. This approach involved both bottom-up market sizing and top-down validation to ensure data accuracy.
Segmentation dimensions modeled include product type, application, end-use industry, technology, and regional adoption patterns across the analysis window. Compound annual growth rates were derived through regression analysis, validated by expert consensus. Forecast inputs incorporated raw material price forecasts and anticipated regulatory compliance timelines.
Forecasts assume regulatory continuity in US FDA and EU REACH frameworks; material policy shifts would require re-modeling. This analysis reflects assumptions regarding polymer supply stability and evolving food safety standards. Practitioners should keep alternative scenarios live as raw material costs and regulatory landscapes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Vinyl Films Market
Poly film
Bio-PET Film Market
Poly film
Shrink Bundling Films Market
Poly film
Forming Films Market
Poly film
Polystyrene Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Cellulose Film Packaging Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Poly Tubing Market
Poly film
Lidding Films Market
Poly film
Hexacomb Packaging Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Polybag Mailers Market
Poly film
Global Cast Polypropylene Packaging Films Market