
 Polyethylene Terephthalate (PET) Market | 2026-2036
Polyethylene Terephthalate (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate (PET) Market Intelligence
Revenue from recycled PET (rPET) processing is reshaping competitive positioning among polymer producers. Indorama Ventures Public Company Limited expands its global recycling footprint to capture this value. Meanwhile, Alpek, S.A.B. de C.V. leverages its integrated production scale across the Americas. Eastman Chemical Company differentiates with its advanced molecular recycling technologies for hard-to-recycle waste streams.
Polyethylene terephthalate is a thermoplastic polymer created through the polymerization of ethylene glycol and terephthalic acid. Its high strength, thermal stability, and excellent gas barrier properties make it ideal for industrial and consumer applications. While virgin PET constitutes the bulk of production, the recycled PET segment is expanding rapidly due to circular economy initiatives. Beverage bottles command the largest share of applications, with textile fibers for apparel and home furnishings representing another major demand center.
Regulatory frameworks significantly influence market dynamics, with the US FDA setting stringent standards for food-contact grade PET. In parallel, the EU's REACH and single-use plastics directives mandate chemical safety and promote recycled content. These rules, alongside China's national GB standards, create complex compliance requirements for producers. Navigating the evolving cost and supply-chain trade-offs between virgin and recycled feedstocks is a critical strategic imperative.
Market Dynamics
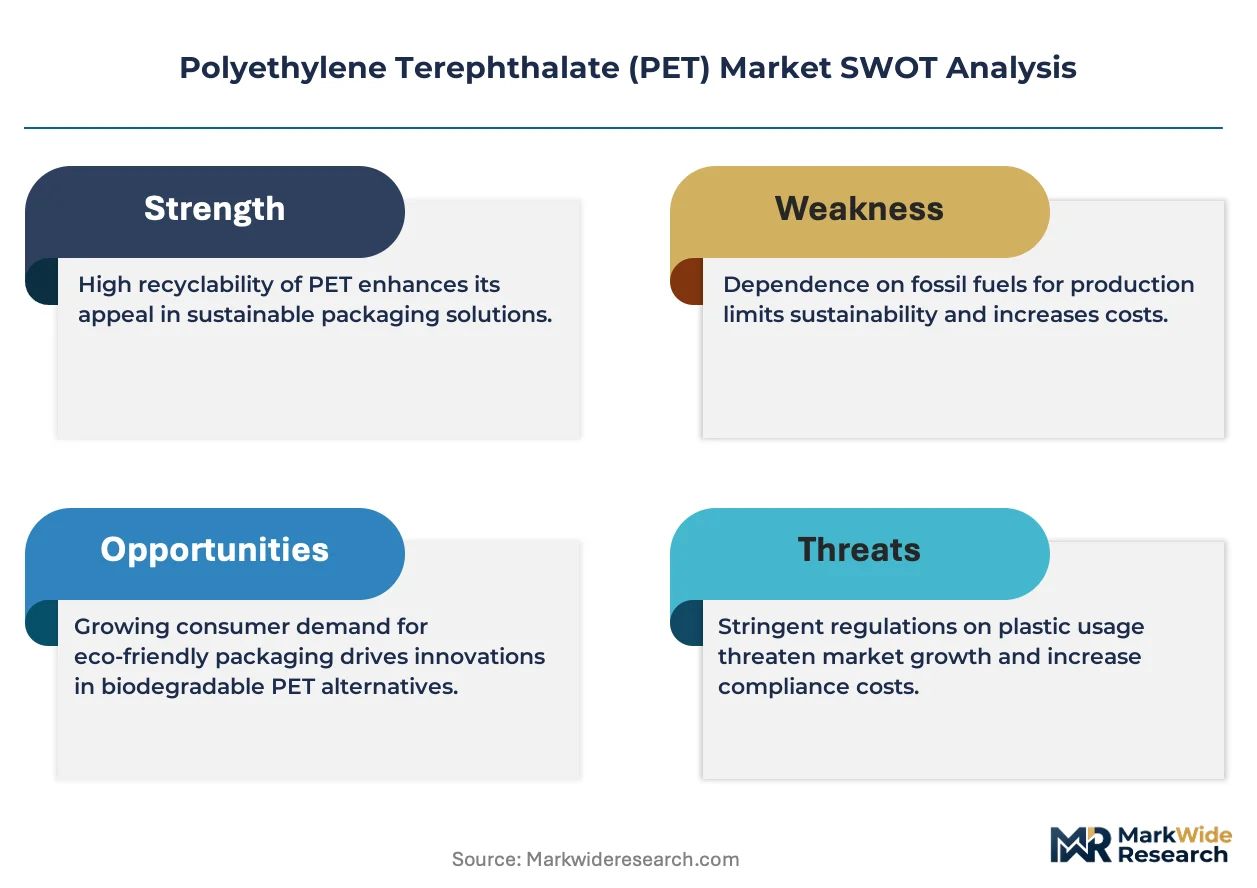
The central structural force shaping the polyethylene terephthalate market is the regulatory-driven mandate for a circular economy. This pressure forces a systemic recalibration of supply chains, technology investment, and material sourcing away from a purely linear, virgin-based model.
Growth Catalysts
- Regulatory Mandates:The EU's directives requiring minimum recycled content in beverage bottles create a guaranteed demand floor for rPET, compelling investment in collection and processing infrastructure to meet compliance targets.
- Beverage Packaging Dominance:Sustained use in carbonated soft drinks and bottled water, which rely on PET's gas barrier and safety properties, underpins a massive and consistent volume base for the entire market.
- Textile Industry Demand:China's vast textile sector provides a significant secondary demand center, absorbing large quantities of PET fiber for apparel and home furnishings, supporting overall production scale.
Market Restraints
- Feedstock Price Volatility:The PET market is directly exposed to price fluctuations in crude oil derivatives, specifically purified terephthalic acid (PTA) and mono-ethylene glycol (MEG), creating margin uncertainty.
- Substitution from Alternatives:In certain applications, PET faces competition from materials like aluminum for cans and glass for bottles, particularly where consumers perceive these alternatives as more premium or sustainable.
- Fragmented Recycling Infrastructure:The inconsistent availability and quality of post-consumer PET feedstock globally hinders the ability of producers to scale rPET production efficiently and meet rising demand for certified recycled content.
Strategic Opportunities
- Advanced Chemical Recycling:New molecular recycling technologies that break down complex or contaminated PET waste into virgin-quality monomers open up previously inaccessible feedstock pools and enable true circularity.
- High-Performance Applications:Developing specialized PET grades for demanding end-uses, such as engineering components in the automotive sector or specialty films for electronics, offers a path to higher-margin segments.
- Emerging Market Expansion:As disposable incomes rise in regions across Southeast Asia and Africa, the associated growth in demand for packaged consumer goods presents a significant long-term opportunity for PET packaging.
Industry Challenges
- Feedstock Quality Control:A primary operational challenge is managing the inconsistent quality and contamination levels of post-consumer resin bales, which complicates the production of high-grade, food-contact-safe rPET.
- High Capital Investment:The construction of world-scale chemical recycling facilities and food-grade rPET plants requires significant capital expenditure, creating high barriers to entry and long investment return cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate (PET) Market |
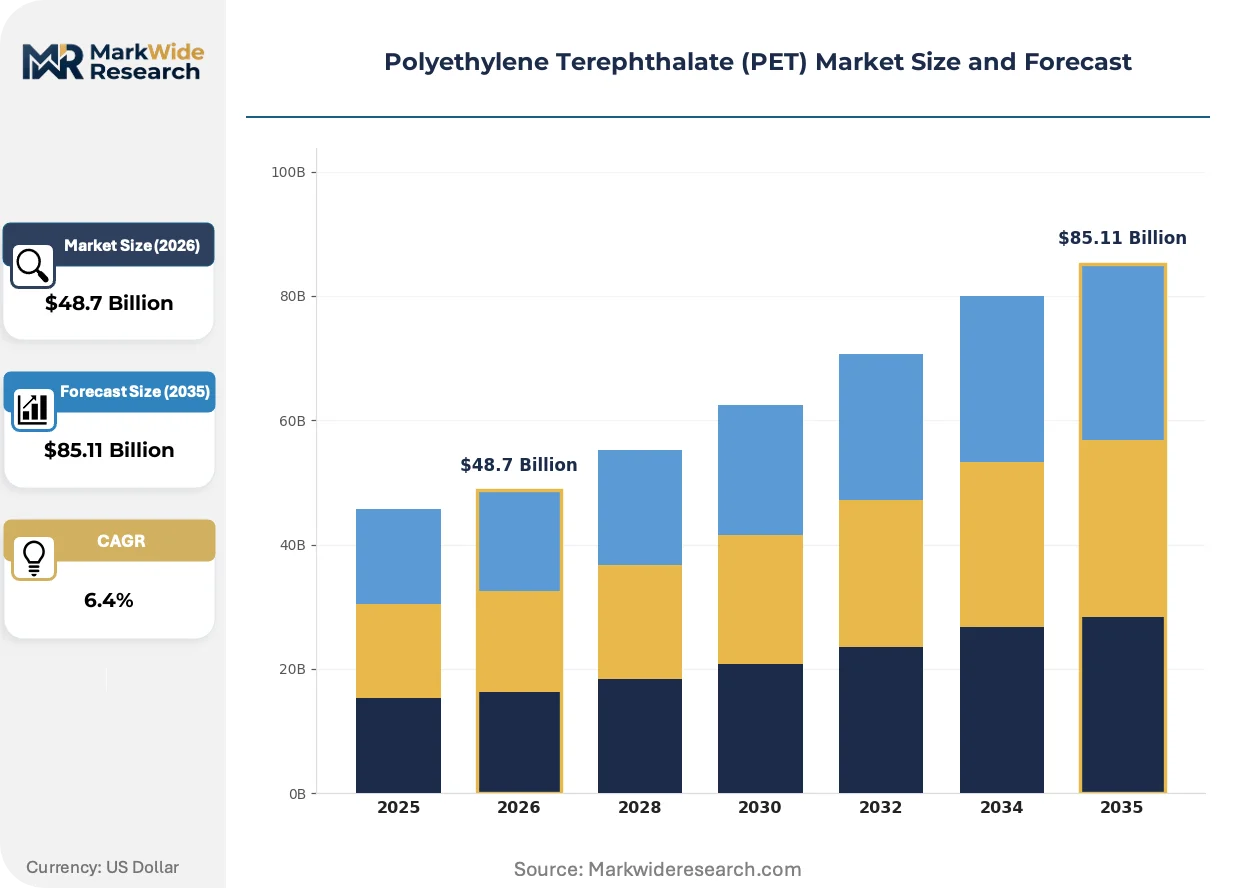
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin PET, Recycled PET, Bio-based PET, PET Copolymer Application: Beverage Bottles, Textile Fibers, Packaging Films, Electrical Components, Automotive Parts End User Industry: Consumer Goods Manufacturers, Textile Producers, Electronics Manufacturers, Automotive Assemblers Form: Sheets, Films, Fibers, Resin Pellets, Strips |
| Companies Covered | Saudi Basic Industries Corporation, Alpek, S.A.B. de C.V., Indorama Ventures Public Company Limited, Eastman Chemical Company, Lotte Chemical Corporation, Far Eastern New Century Corporation, China Petroleum & Chemical Corporation, Mitsubishi Chemical Group Corporation, Alfa S.A.B. de C.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate (PET) Market Strategic Shifts & Innovations
Industrialization of recycling is fundamentally altering PET value chains. The market is transitioning from a focus on virgin material efficiency to managing the complex interplay between recycled feedstock availability, processing technology capabilities, and regulatory compliance demands for circularity.
Advanced chemical recycling, which uses processes like glycolysis to depolymerize PET waste into its base monomers, is a key technological evolution. Major consumer brand owners and polymer producers are adopting this to meet aggressive recycled content targets set by frameworks like the EU Green Deal. This technology is collapsing the quality gap between virgin and recycled feedstocks, enabling the production of food-grade rPET from difficult-to-recycle post-consumer waste streams.
Regulatory frameworks like the US FDA's stringent requirements for food-contact substances create a critical compliance pathway for rPET. These rules establish the safety testing and process validation necessary for recycled plastics to be used in beverage bottles and food containers. The packaging segment is most affected, investing heavily in purification technologies and obtaining Letters of No Objection to secure market access for their rPET products.
Major consumer packaged goods companies are embedding sustainability metrics into their procurement criteria for PET resins. This shift moves purchasing decisions beyond price, incorporating factors like certified recycled content levels and the carbon footprint of the material, which disrupts traditional supplier contracts. This trend is most prominent in Europe and North America, where corporate sustainability reporting is under intense scrutiny from investors and regulatory bodies like the SEC.
Polyethylene Terephthalate (PET) Market Segmentation
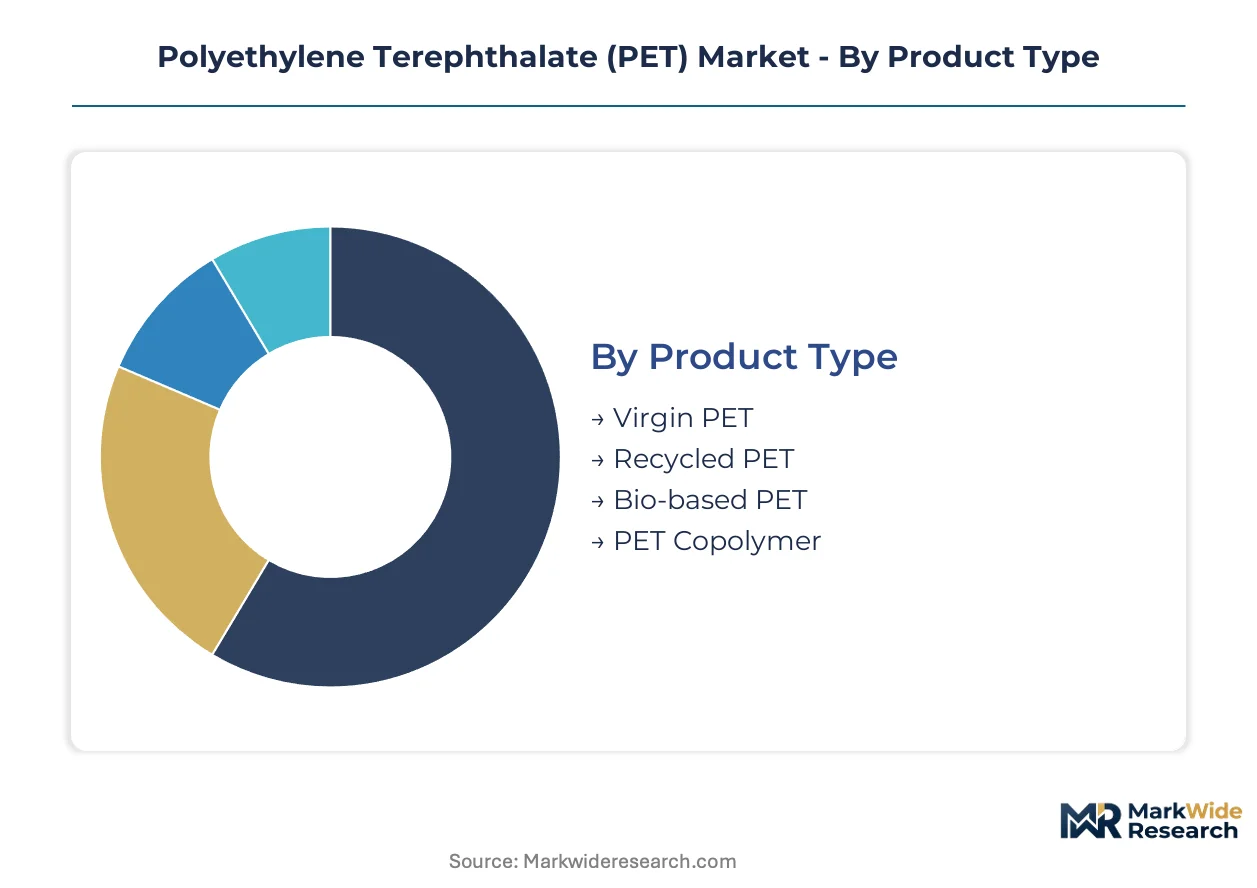
The polyethylene terephthalate market is intrinsically linked to its diverse material compositions and end-use applications, each presenting unique value propositions and demand characteristics. Understanding these segments clarifies the varying pressures on feedstock sourcing, processing technologies, and regulatory compliance across the value chain.
Product Type:
The various product types within PET exhibit distinct cycle times, influencing the speed at which materials re-enter the production loop and the investment required for their processing.
- Recycled PET:This material is derived from post-consumer waste through mechanical or advanced chemical processes, offering a circular solution. Demand in Europe and the United States is accelerating due to stringent regulatory mandates, particularly for beverage bottle content.
- Virgin PET:Produced directly from petrochemical feedstocks like purified terephthalic acid and mono-ethylene glycol, it represents the foundational polymer. Its sustained use in beverage bottles and textile fibers underpins global production volumes due to established infrastructure and consistent quality.
- Bio-based PET:Utilizing renewable resources such as plant-derived mono-ethylene glycol, this variant aims to reduce the carbon footprint of PET production. Development efforts in countries like Japan and Germany focus on scaling production and improving cost competitiveness against traditional PET.
- PET Copolymer:Modified with additional monomers during polymerization, this type offers enhanced properties like improved barrier performance or lower crystallization rates. Applications often include specialized packaging films and certain industrial components where specific material characteristics are paramount.
Virgin PET dominates the installed base. Recycled PET is where expansion concentrates.
Application:
Application segments are primarily driven by volume requirements, with certain end-uses consuming significantly larger quantities of PET than others due to their scale and market penetration.
- Beverage Bottles:This segment represents the largest volume consumer of PET, valued for its clarity, light weight, and excellent gas barrier properties for carbonated soft drinks and bottled water. Regulatory frameworks in the EU and US FDA standards for food contact drive significant investment in food-grade recycled PET for this application.
- Textile Fibers:PET is widely converted into fibers for apparel, home furnishings, and industrial textiles, particularly in China's vast manufacturing sector. Its strength, wrinkle resistance, and dyeability make it a cost-effective material for high-volume textile production.
- Packaging Films:Used in flexible packaging, trays, and laminates, PET films provide a robust barrier against moisture and oxygen, extending the shelf life of various food and consumer products. This application benefits from PET's mechanical strength and thermal stability.
- Electrical Components:PET is utilized in various electrical and electronic parts for its dielectric properties, thermal resistance, and dimensional stability. Applications include insulation, connectors, and casings in consumer electronics.
- Automotive Parts:In the automotive industry, PET finds use in lightweighting initiatives, offering strength and rigidity for interior components, under-the-hood applications, and certain structural elements. The material contributes to fuel efficiency and design flexibility.
Beverage Bottles command the largest market share. Textile Fibers are climbing the fastest.
End User Industry:
The profitability and margin profiles for PET producers vary across end-user industries, influenced by product specifications, volume consistency, and the value added by specialized grades.
- Consumer Goods Manufacturers:These companies utilize PET extensively for packaging food, beverages, personal care items, and household products. Their procurement decisions are increasingly influenced by sustainability metrics and the availability of certified recycled content to meet corporate and regulatory targets.
- Automotive Assemblers:Demanding high-performance and specialized PET grades, this industry uses the polymer for components requiring durability, impact resistance, and thermal stability. The focus here is often on material innovation that supports vehicle lightweighting and enhanced safety features.
- Textile Producers:This industry converts PET resins into fibers for a wide array of fabrics, clothing, and home textiles. Global textile manufacturing hubs, notably in Asia, drive substantial demand for PET fiber, balancing cost-efficiency with performance requirements.
- Electronics Manufacturers:Using PET for insulation, casings, and specialized films, this sector values the polymer's electrical properties and thermal stability. Compliance with international standards for electronic components is a critical purchasing criterion.
Consumer Goods Manufacturers hold the largest segment. Automotive Assemblers are gaining share fastest.
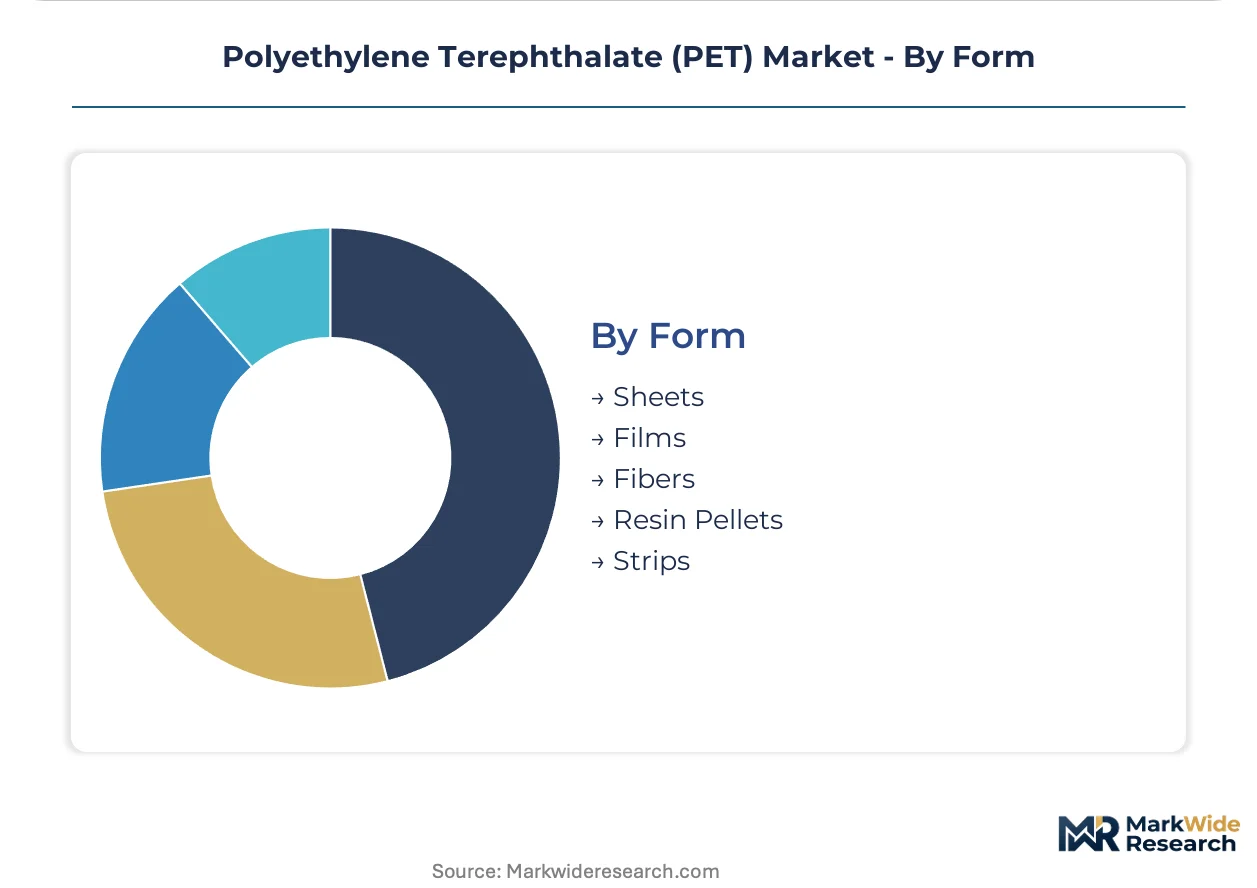
Form:
The concentration of supply for PET in various forms reflects the primary processing stages and the subsequent value chain for further manufacturing.
- Resin Pellets:This is the primary and most concentrated form of PET, serving as the feedstock for virtually all downstream processing. Producers supply these pellets to converters for injection molding, extrusion, and fiber spinning operations worldwide.
- Fibers:PET fibers are produced by spinning molten PET resin into continuous filaments or staple fibers, which are then woven or knitted into textiles. China remains a dominant producer and consumer of PET fibers for its vast textile industry.
- Films:PET films are manufactured through extrusion and stretching processes, creating thin, strong sheets used in packaging, industrial applications, and electrical insulation. These films offer excellent mechanical properties and barrier characteristics.
- Sheets:Thicker than films, PET sheets are used for thermoforming applications, signage, and protective barriers. Their rigidity and clarity make them suitable for various consumer and industrial products.
- Strips:PET strips are typically used for strapping and banding applications in packaging and logistics, providing high tensile strength and elasticity to secure goods during transport.
Resin Pellets constitute the largest volume. Fibers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand elasticity for polyethylene terephthalate varies significantly across geographies. In mature markets, stringent regulatory pressures for recycled content drive premium pricing for rPET. Emerging economies often prioritize cost-effectiveness for virgin material, which shapes investment in recycling infrastructure and feedstock procurement strategies globally.
China
Demand for PET in China is primarily driven by its vast textile and packaging industries. The national GB standards establish quality benchmarks for both virgin and recycled PET applications. Production hubs in the Yangtze River Delta consistently expand capacity for both fiber and bottle-grade resins.
United States
Consumption of PET in the United States is heavily concentrated in beverage bottles and food packaging. The US FDA sets stringent standards for food-contact grade recycled PET, ensuring product safety and market access. Major packaging converters in states like Texas and Ohio are investing in advanced purification technologies for rPET.
Germany
Germany's PET market is strongly influenced by circular economy initiatives and bio-based material development. EU REACH regulations and single-use plastics directives mandate high recycled content targets for packaging. The chemical industry in the Rhine-Main region actively scales up advanced chemical recycling facilities and bio-PET production.
India
India's PET demand is accelerating due to the expansion of packaged consumer goods and textile manufacturing. The country's BIS standards guide quality and safety for PET usage across diverse applications. Industrial clusters in Gujarat and Maharashtra are expanding capacities for both virgin PET production and mechanical recycling.
Polyethylene Terephthalate (PET) Market Key Industry Players
Capability concentration sits with one tier of specialized technology providers, while scale advantage underpins the position of large integrated polymer producers. The polyethylene terephthalate market exhibits a tiered structure, encompassing global chemical giants, regional specialists, and emerging recycling innovators. Global players prioritize capacity expansion and strategic partnerships to secure both virgin and recycled feedstock. Regional manufacturers often pursue technology licensing and portfolio diversification to serve niche applications and meet specific regulatory demands.
Within the integrated polymer production tier, Indorama Ventures Public Company Limited and Alpek, S.A.B. de C.V. exemplify companies leveraging vast operational scale across multiple geographies. Indorama Ventures, a Public Company Limited, represents an archetype focused on expanding its global recycling footprint to capture value from circular economy mandates. Meanwhile, Alpek, S.A.B. de C.V., a Mexican S.A.B. de C.V., occupies a position characterized by integrated production capabilities across the Americas. Eastman Chemical Company, an American company, anchors the innovation-driven segment with its advanced molecular recycling technologies for hard-to-recycle waste streams. These players collectively shape the market's response to shifting feedstock dynamics and regulatory demands.
| Leading Market Players |
|---|
| Saudi Basic Industries Corporation |
| Alpek, S.A.B. de C.V. |
| Indorama Ventures Public Company Limited |
| Eastman Chemical Company |
| Lotte Chemical Corporation |
| Far Eastern New Century Corporation |
| China Petroleum & Chemical Corporation |
| Mitsubishi Chemical Group Corporation |
| Alfa S.A.B. de C.V. |
| Others |
Cost & Logistics Intelligence
Underutilization of advanced rPET processing capacity influences both supplier investment decisions and the pricing strategies for recycled materials. This dynamic creates a tension between the cost-effectiveness of virgin PET and the premium commanded by certified recycled content.
Pricing Analysis
The premium derived from certified, food-grade rPET represents a critical value-added tier for PET producers. Pricing operates on a hybrid model, combining contract-based long-term offtake agreements with commodity spot market influences for virgin feedstocks. Price differentiation hinges on certification level, particularly US FDA food-contact grade approval, and specialized properties for high-performance applications. Pricing pressure stems from crude oil derivative volatility, impacting virgin PET margins. Consumer goods manufacturers seeking certified recycled content exhibit lower price sensitivity compared to emerging market buyers prioritizing virgin material cost-effectiveness.
Supply Chain Analysis
Regulatory mandates, such as the EU's single-use plastics directives, restrict the flow of virgin PET into specific applications. Geographic supply concentrates in China, the United States, and Germany, reflecting diverse production and consumption patterns. The supply chain depends on critical raw materials like purified terephthalic acid and post-consumer PET waste. A structural risk involves fragmented recycling infrastructure, creating inconsistent feedstock quality for rPET production. Distribution runs through a B2B model, supplying resin pellets to converters and fiber spinners globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyethylene terephthalate market requires a robust substitution defense against alternative materials. Incumbents must navigate the persistent threat from aluminum and glass, particularly in premium beverage packaging segments.
For Market Incumbents:Pre-empt market share erosion by investing in advanced chemical recycling technologies. This move produces virgin-quality rPET, directly addressing the regulatory shift towards circularity. Secure long-term feedstock agreements for post-consumer waste to mitigate supply inconsistencies. Further R&D in specialized PET grades can differentiate products against competition from alternative packaging materials.
For New Entrants and Emerging Players:Pursue niche opportunities within specialized PET grades and bio-based variants. Advanced molecular recycling solutions for hard-to-recycle waste streams represent a significant white space. Target high-performance applications in automotive and electronics, where material innovation commands premium pricing. A go-to-market angle focusing on technology licensing and strategic partnerships with established polymer producers can accelerate market entry.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among integrated polymer producers with a strong rPET footprint. Long-term viability across the next decade hinges on the ability to manage circular economy mandates and feedstock volatility. Identify acquisition targets specializing in advanced chemical recycling technologies or bio-based PET production. The industrialization of chemical recycling technologies represents a critical inflection indicator for future investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for rPET | This initiative directly addresses regulatory mandates for recycled content in beverage bottles. |
| Advanced Chemical Recycling Investment | This enables the processing of complex PET waste, producing virgin-quality monomers for re-use. |
| Long-term Supply Agreement for Waste Feedstock | Securing consistent, quality post-consumer PET feedstock mitigates operational challenges for rPET producers. |
| Specialized PET Grade Development | This targets higher-margin segments like automotive components and electronics, enhancing product portfolio value. |
| Bio-based PET Research and Development | This reduces the carbon footprint of PET production, aligning with consumer and corporate sustainability goals. |
Research Approach
Cross-validation between primary interviews and secondary market intelligence anchors the qualitative findings. This involved discussions with plant managers, procurement leads at consumer goods manufacturers, and R&D directors at polymer producers. Secondary data sources included customs data, SEC 10-K filings, and industry association reports. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Model calibration involved iterative adjustments against historical market performance and economic indicators. The analytical framework segmented the market by product type, application, end-user industry, form, and regional regulatory frameworks across the analysis window. Compound annual growth rates were derived using regression analysis. Key industry-specific forecast inputs included crude oil price forecasts and evolving recycled content mandates.
Sensitivities concentrate around feedstock price volatility and regulatory policy shifts. Forecasts reflect assumptions regarding current market dynamics, acknowledging potential impacts from unforeseen technological breakthroughs in alternative materials. Material shifts in global economic downturns or major regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Cast Films Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
Germany Plastic Packaging Market