
 Nylon Films for Liquid Packaging Market | 2026-2036
Nylon Films for Liquid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nylon Films for Liquid Packaging Market Outlook
ISO 17025 laboratory accreditation is unwinding competitive access for regional converters seeking multinational beverage contracts. Amcor plc leverages integrated film extrusion and converting assets across Asia-Pacific to sustain supply security for dairy pouch programs. Mitsubishi Chemical Group anchors its position through captive caprolactam production and differentiated biaxially oriented nylon grades. Kuraray Co., Ltd. specializes in EVOH-nylon coextrusion structures that dominate aseptic liquid food barrier specifications.
Nylon films for liquid packaging constitute polyamide-based flexible substrates engineered with oxygen transmission rates below 50 cm³/m²/day and seal strengths exceeding 40 N/15mm, manufactured through sequential biaxial orientation or cast coextrusion to prevent flavor oxidation and microbial ingress in shelf-stable liquids. Barrier Films command the dominant margin pool due to multilayer EVOH-nylon lamination complexity and extended shelf-life premiums in aseptic dairy. Flexible Pouches represent the fastest-growing packaging type as beverage brands displace rigid bottles with lightweight, logistics-efficient formats in e-commerce distribution.
FDA Title 21 CFR food contact substance notifications govern nylon resin approvals for U.S. liquid food packaging, while EU REACH restrictions on adipic acid derivatives and F-Gas Regulation phase-downs are accelerating converter migration toward bio-based polyamide feedstocks. China's GB standards for composite food packaging materials, administered by SAMR, mandate solvent residue limits and migration testing that filter subscale domestic suppliers from national dairy brand supply chains. Stakeholders must monitor regulatory divergence between biopolymer certification pathways in Europe and China's dual carbon compliance timelines to align capital allocation with emerging qualification requirements.
Market Dynamics
Converters face a structural squeeze between EU REACH mandates on adipic acid derivatives and China's GB standards for solvent residues, forcing simultaneous retooling of resin sourcing and lamination chemistry without margin recovery mechanisms.
Growth Catalysts
- ASEAN Dairy Expansion:Vietnam and Indonesia's chilled distribution networks are absorbing multilayer pouch formats for UHT milk, displacing glass bottle infrastructure in provincial markets.
- F-Gas Regulation Phase-Down:EU converters are accelerating solvent-free adhesive adoption and bio-based polyamide trials to preempt regulatory non-compliance in aseptic liquid food barrier specifications.
- Caprolactam Supply Integration:Captive feedstock production in China's Yangtze River Delta manufacturing cluster is compressing working capital cycles for integrated film-to-pouch operations serving domestic juice brands.
Market Restraints
- Adipic Acid Derivative Restrictions:EU REACH Annex XIV authorization requirements are elevating formulation costs for conventional nylon 6,6 grades used in high-barrier dairy laminations.
- Caprolactam Concentration Risk:Three integrated petrochemical complexes control over sixty percent of Asian monomer supply, exposing converters to force majeure vulnerability without hedge instruments.
- Recyclability Technical Ceiling:Current multilayer EVOH-nylon structures lack economically viable delamination pathways, blocking circular packaging claims for premium beverage clients.
Strategic Opportunities
- India Cold Chain Inflection:FSSAI enforcement of packaged food safety standards in tier-two cities is creating first-mover advantage for aseptic pouch converters with ISO 22000 certification.
- Bio-Based Polyamide Scale-Up:Castor oil-derived PA 10,10 and PA 11 feedstocks are achieving cost parity in European dairy applications, qualifying for EU Green Deal procurement preferences.
- E-Commerce Pouch Formats:Lightweight flexible packaging with puncture-resistant biaxially oriented nylon skins is capturing logistics cost savings in direct-to-consumer beverage subscription channels.
Industry Challenges
- Coextrusion Technician Scarcity:Seven-layer blown film operations require operators capable of managing EVOH-nylon interlayer adhesion control, a skill profile concentrated among aging workforces in Germany and Japan.
- ISO 17025 Accreditation Timelines:Regional converters in China's interior provinces face eighteen-month laboratory qualification periods to access multinational beverage supplier approved vendor lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nylon Films for Liquid Packaging Market |
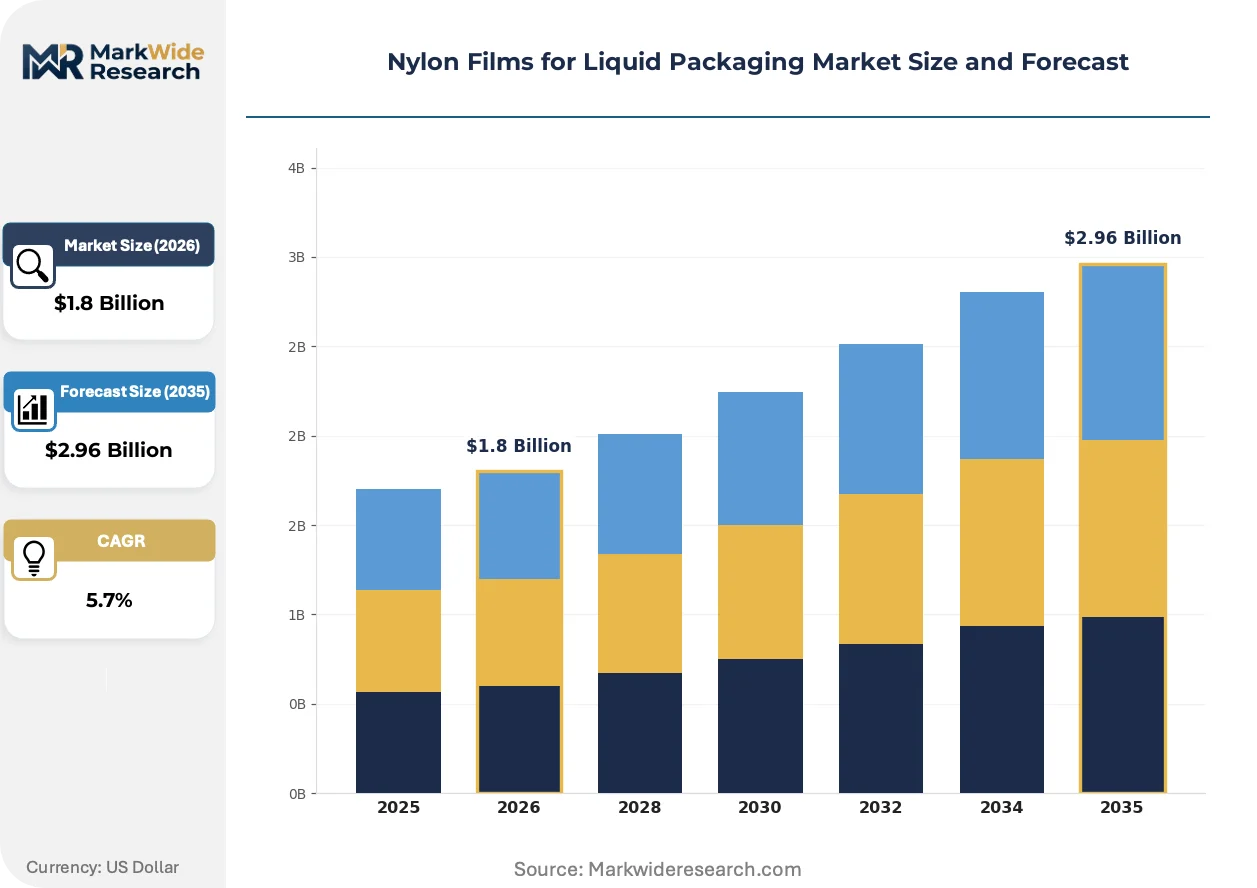
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Films, Shrink Films, Stretch Films, Laminated Films Application: Dairy Products, Water, Beverages, Liquid Food End User: Food Industry, Beverage Industry, Chemical Sector, Pharmaceutical Sector Packaging Type: Flexible Pouches, Roll Stock, Bags, Squeeze Bottles |
| Companies Covered | Amcor plc, Sealed Air Corporation, Mitsubishi Chemical Group, Winpak Ltd., Kuraray Co., Ltd., Toppan Inc., Constantia Flexibles, Uflex Ltd., Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nylon Films for Liquid Packaging Market Strategic Shifts
Digital print integration with pre-made pouch converting lines is collapsing minimum order quantities and compressing new product introduction cycles for regional beverage brands.
Sequential biaxial orientation lines with inline spectroscopic thickness monitoring are displacing offline quality control protocols in high-volume dairy film operations. European converters with Amcor plc-scale asset bases are adopting these systems to reduce laminate defect rates below 0.3 percent. The technology is displacing statistical sampling-based release procedures that previously delayed shipment confirmation by forty-eight hours.
EU F-Gas Regulation phase-down schedules are forcing accelerated solvent recovery system installation across Italian and Spanish converting facilities. The industrial consequence is a bifurcation between capitalized players with regenerative thermal oxidizers and subscale competitors facing operational shutdowns during peak summer ozone alert periods. Aseptic dairy pouch specifications in Germany and France are experiencing the most acute supply tightness as converters prioritize compliant capacity.
Beverage brand procurement departments are consolidating supplier panels from twelve-vendor rosters to three approved partners with integrated film extrusion and converting capabilities. The distribution channel being disrupted is the traditional converter-distributor-reseller hierarchy that previously served mid-tier juice and dairy processors. This concentration is most visible in China's Yangtze River Delta, where SAMR-mandated composite packaging traceability requirements favor vertically qualified suppliers with in-house laboratory testing infrastructure.
Nylon Films for Liquid Packaging Market Segmentation
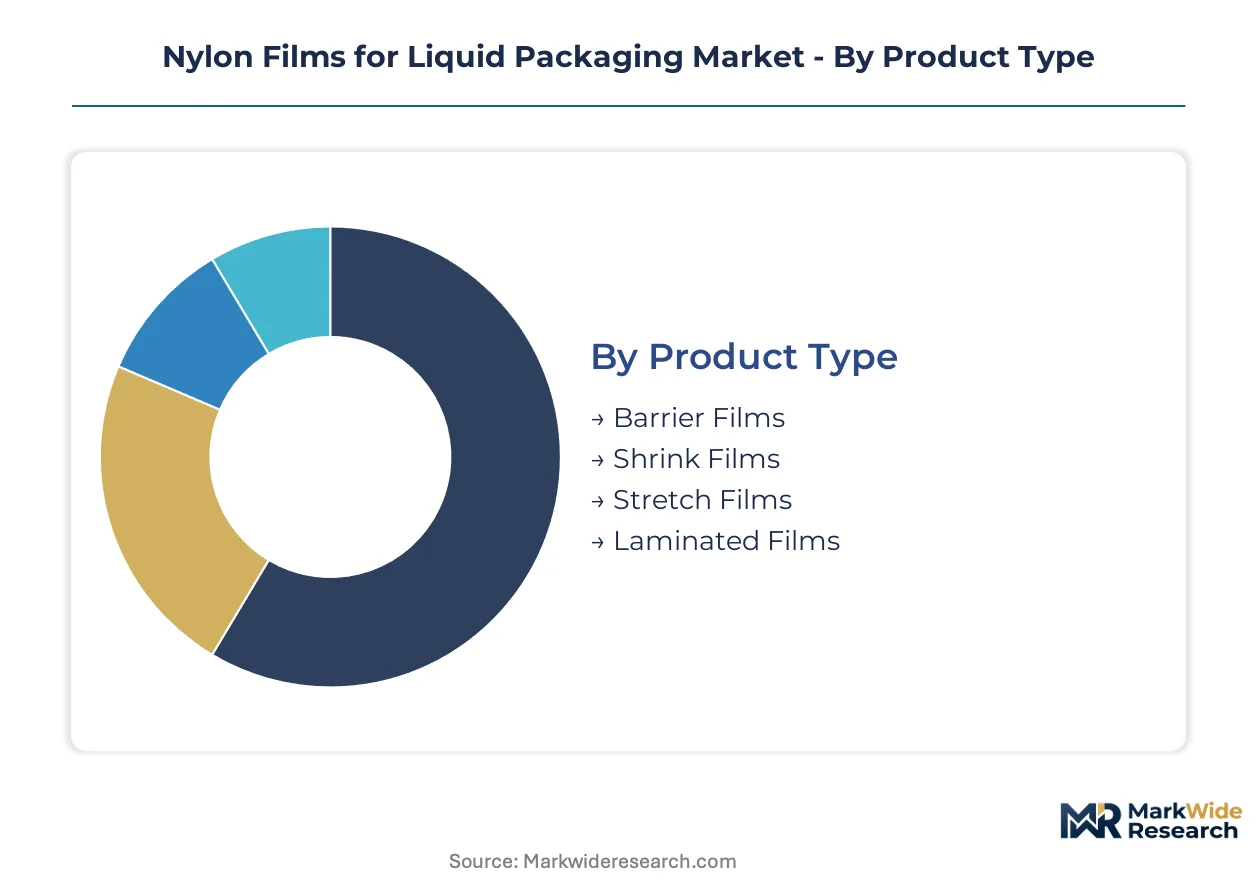
Nylon film specifications diverge sharply across liquid packaging applications, with oxygen barrier requirements and seal strength tolerances dictating resin grade selection and converting technology investments. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning among converters.
Product Type:
Barrier Films concentrate in domestic supply chains serving shelf-stable dairy, while Shrink Films and Stretch Films flow disproportionately to export-oriented beverage bottlers in Southeast Asia and Latin America.
- Barrier Films:Multilayer EVOH-nylon laminations achieve oxygen transmission rates below 50 cm³/m²/day through sequential biaxial orientation. Demand clusters in China's Yangtze River Delta for UHT milk pouches, where SAMR-mandated migration testing filters subscale suppliers from national dairy brand procurement.
- Shrink Films:Heat-shrinkable biaxially oriented nylon grades provide puncture resistance for multi-pack beverage collation. Vietnamese and Indonesian converters are absorbing capacity for bottled water shrink-wrapping as provincial retail modernizes chilled distribution infrastructure.
- Stretch Films:Cast coextrusion produces cling properties for palletized liquid container unitization. Chemical sector procurement in Germany favors stretch hood formats with REACH-compliant adhesive layers.
- Laminated Films:Adhesive and extrusion lamination bonds nylon to polyethylene or polypropylene substrates for intermediate barrier applications. Roll stock converters in India's Maharashtra state supply regional juice processors with FSSAI-certified structures.
Barrier Films hold the largest share; momentum sits with Shrink Films as ASEAN beverage bottlers displace rigid secondary packaging.
Application:
Cost tier stratification separates premium aseptic dairy specifications from commodity water packaging, with formulation complexity and laboratory accreditation requirements widening the margin spread.
- Dairy Products:UHT milk and yogurt drink pouches demand the highest barrier specifications with EVOH-nylon coextrusion and aluminum oxide metallization. EU F-Gas Regulation compliance is forcing Italian converters toward solvent-free adhesive systems for aseptic dairy laminations.
- Beverages:Ready-to-drink coffee and tea formulations require flavor scalping resistance through amorphous nylon surface layers. Japanese beverage brands specify biaxially oriented nylon grades from domestic suppliers with METI-certified carbon footprint disclosures.
- Water:Mineral and purified water pouch formats prioritize puncture resistance and cost minimization over oxygen barrier. Chinese domestic brands in Guangdong province drive volume through integrated film-to-pouch operations.
- Liquid Food:Cooking oils and sauces utilize medium-barrier nylon-polyethylene laminations with moderate seal strength requirements. Indian FSSAI enforcement in tier-two cities is accelerating qualification demand for liquid food pouch converters.
Dairy Products command the premium tier; Beverages are climbing the fastest as functional drink brands adopt multilayer pouch formats.
End User:
Customer type determines certification burden and contract duration, with pharmaceutical and food industry procurement imposing the most stringent traceability and change-control protocols.
- Food Industry:Shelf-stable and refrigerated liquid food processors specify nylon films with FDA Title 21 CFR food contact substance notifications for U.S. export eligibility. Extended shelf-life premiums support multilayer structure investments.
- Beverage Industry:Carbonated and non-carbonated drink brands prioritize logistics efficiency through lightweight flexible formats. E-commerce subscription channels in South Korea favor puncture-resistant biaxially oriented nylon skins.
- Chemical Sector:Agricultural and industrial liquid packaging demands chemical resistance and UV stability through nylon 6,6 grades. German KBA transport regulations influence secondary packaging specifications for hazardous liquid containment.
- Pharmaceutical Sector:Oral and topical liquid drug packaging requires ISO 15378-compliant primary packaging materials with extractables testing. European converters with EMA-registered manufacturing sites capture multinational pharmaceutical contracts.
Food Industry represents the volume anchor; Pharmaceutical Sector offers the steepest expansion trajectory as biologic liquid formulations proliferate.
Packaging Type:
Supply concentration varies by format complexity, with pre-made pouch converting requiring integrated extrusion assets while roll stock tolerates fragmented converter bases.
- Flexible Pouches:Stand-up and flat pouch formats with spout fitments dominate ready-to-drink beverage innovation. China's SAMR composite packaging traceability requirements favor vertically qualified suppliers with in-house laboratory infrastructure.
- Roll Stock:Unconverted film webs supply downstream form-fill-seal operations for high-volume dairy processors. Indonesian and Vietnamese converters are expanding multilayer blown film capacity for regional roll stock distribution.
- Bags:Pillow and gusseted bag configurations serve bulk liquid food and chemical containment. Cost-sensitive procurement in Brazil's interior states favors simplified nylon-polyethylene two-layer structures.
- Squeeze Bottles:Coextruded blow-molded containers with nylon barrier layers compete with flexible formats for condiment and sauce applications. Japanese METI plastic resource circulation guidelines are squeezing conventional multilayer bottle designs.
Roll Stock holds the largest share; Flexible Pouches are gaining share fastest as beverage brands consolidate supplier panels toward integrated film-and-convert partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
F-Gas Regulation phase-downs in the EU and China's dual carbon compliance timelines are redirecting capital toward bio-based polyamide production. National regulators in major liquid food processing markets are tightening food contact material standards, filtering subscale converters from approved supplier lists.
China
Yangtze River Delta manufacturing clusters absorb two-thirds of domestic dairy pouch film demand through integrated film-to-pouch operations. SAMR-administered GB standards for solvent residues and migration testing exclude unaccredited converters from national dairy brand supply chains. Zhejiang and Jiangsu provinces host the densest concentrations of seven-layer blown film capacity serving juice and UHT milk processors.
Germany
Aseptic dairy pouch specifications face acute supply tightness as converters prioritize F-Gas Regulation-compliant capacity with regenerative thermal oxidizers. KBA transport regulations influence secondary packaging specifications for hazardous liquid containment in chemical sector procurement. Bavarian and North Rhine-Westphalian converting facilities lead solvent-free adhesive adoption for high-barrier laminations.
United States
FDA Title 21 CFR food contact substance notifications govern nylon resin approvals for liquid food packaging export eligibility. Extended shelf-life premiums in organic dairy support multilayer structure investments across Wisconsin and California dairy processing corridors. Midwestern converters leverage proximity to caprolactam supply chains for working capital efficiency.
India
FSSAI enforcement of packaged food safety standards in tier-two cities accelerates qualification demand for aseptic pouch converters with ISO 22000 certification. Maharashtra and Gujarat roll stock converters supply regional juice processors with FSSAI-certified nylon-polyethylene laminations. Mumbai-Pune industrial corridor concentrates multilayer blown film expansion for domestic liquid food brands.
Japan
METI-certified carbon footprint disclosures differentiate domestic biaxially oriented nylon suppliers in beverage brand procurement. Kansai and Chubu regions maintain specialized coextrusion expertise for EVOH-nylon interlayer adhesion control. Osaka-based converters supply ready-to-drink coffee and tea brands with flavor scalping-resistant amorphous nylon surface layers.
Nylon Films for Liquid Packaging Market Competitive Environment
Player mix skews toward integrated chemical-film-convert conglomerates and specialized barrier film specialists. The competitive structure concentrates around upstream caprolactam producers with captive film extrusion assets and downstream converters with accredited laboratory infrastructure. Two archetypes dominate: integrated petrochemical-film operations leveraging feedstock cost advantages, and specialized coextrusion houses commanding premium margins through EVOH-nylon barrier expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, with converters securing resin supply agreements to preempt force majeure exposure.
Within the integrated chemical-film tier, Mitsubishi Chemical Group and Kuraray Co., Ltd. exemplify archetypes combining upstream monomer control with differentiated biaxially oriented grades. Amcor plc occupies a position spanning integrated extrusion and converting assets across Asia-Pacific. Among specialized barrier houses, Sealed Air Corporation and Winpak Ltd. sit within the premium tier focused on aseptic liquid food specifications. Constantia Flexibles and Uflex Ltd. represent European and Asian converters respectively, navigating divergent regulatory compliance pathways. Toppan Inc. and Mondi Group anchor regional positions through accredited laboratory infrastructure and multinational beverage supplier relationships.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Mitsubishi Chemical Group |
| Winpak Ltd. |
| Kuraray Co., Ltd. |
| Toppan Inc. |
| Constantia Flexibles |
| Uflex Ltd. |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Bio-based polyamide feedstocks displacing conventional caprolactam-derived grades are simultaneously redrawing raw material sourcing maps and compressing margin structures for converters caught between EU REACH compliance premiums and China's dual carbon cost absorption mandates.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA Title 21 CFR and EU F-Gas Regulation-compliant grades commanding substantial premiums over standard industrial specifications. Pricing stratifies across premium aseptic dairy laminations, standard multilayer pouch structures, and economy water packaging tiers based on oxygen barrier performance and laboratory accreditation status. Cost compression in the economy tier is intensifying as Chinese integrated film-to-pouch operators leverage captive caprolactam supply. Beverage brand procurement teams exhibit the highest price sensitivity, while pharmaceutical sector buyers prioritize barrier reliability over unit cost.
Supply Chain Analysis
Strait of Malacca transit vulnerability underwrites working capital risk for European converters dependent on Asian monomer supply. Manufacturing gravity centers on China, Germany, and Japan, with the Yangtze River Delta hosting the densest concentration of seven-layer blown film capacity. Feedstock supply draws from caprolactam, adipic acid, and castor oil-derived sebacic acid sources. Single-source vulnerability concentrates around three Asian petrochemical complexes controlling majority monomer output. Distribution runs through vertically integrated film-to-pouch operations serving multinational beverage accounts and fragmented roll stock converters supplying regional dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative against bio-based polyamide challengers and recyclable mono-material formats that threaten to delaminate established EVOH-nylon barrier specifications.
For Market Incumbents: Shield barrier film margins through backward integration into caprolactam production or captive bio-based polyamide offtake agreements. Accelerate solvent-free adhesive system deployment ahead of EU F-Gas Regulation enforcement windows. Prioritize ISO 17025 laboratory accreditation to maintain multinational beverage supplier approved vendor list status against emerging regional competitors. For New Entrants and Emerging Players: Anchor in India's tier-two city cold chain buildout where FSSAI enforcement is filtering unaccredited converters from liquid food pouch supply chains. Target Maharashtra and Gujarat roll stock demand from regional juice processors seeking FSSAI-certified nylon-polyethylene laminations. Pursue coextrusion technician partnerships with aging German or Japanese specialist workforces to bridge capability gaps. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European converters facing F-Gas Regulation compliance capex burdens without margin recovery mechanisms. Five-to-ten year viability hinges on successful bio-based feedstock transition and circular packaging qualification. Monitor EU Green Deal procurement preference implementation as inflection signal for bio-based polyamide cost parity achievement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Mitsubishi Chemical Group's captive feedstock model compresses working capital cycles for integrated converters. |
| Solvent-Free Adhesive System Deployment | EU F-Gas Regulation compliance separates capitalized players with regenerative thermal oxidizers from subscale competitors. |
| Bio-Based Polyamide Scale-Up | Castor oil-derived PA 10,10 and PA 11 feedstocks qualify for EU Green Deal procurement preferences in European dairy applications. |
| ISO 17025 Laboratory Accreditation | SAMR-mandated migration testing filters unaccredited Chinese interior province converters from national dairy brand supply chains. |
| Seven-Layer Blown Film Capacity Expansion | Indonesian and Vietnamese converters absorb ASEAN dairy pouch demand as provincial retail modernizes chilled distribution infrastructure. |
Study Parameters
The analysis maps barrier film, shrink film, stretch film, and laminated film sub-sectors, each validated through extrusion plant managers, beverage brand procurement leads, dairy processor packaging engineers, and chemical sector technical directors. Primary interview findings triangulated against customs and trade data, SEC 10-K filings, SAMR GB standard disclosures, and ECHA REACH authorization databases. Bottom-up capacity and demand modeling reconciled with top-down value chain analysis.
Volume and value outputs were validated against external benchmarks across the projection horizon, with segmentation modeling spanning product type, application, end user, and packaging format dimensions. CAGRs derived from historical trajectory analysis and demand driver elasticity assessment. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules, China's dual carbon compliance timelines, and ASEAN dairy cold chain infrastructure buildout rates.
Decision-makers should treat outputs as directional under sustained regulatory enforcement and bio-based feedstock scale-up assumptions; material deviation in caprolactam supply concentration or recyclability technology breakthrough would warrant model refresh. Practitioners should keep alternative scenarios live as biopolymer certification pathways diverge between European and Chinese regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Bopet Films Market
Poly film
PVC Film for Medical Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Craft Plastic Films Market
Poly film
China BOPP Film Market
Poly film
Bundling Film Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Polyolefin Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Surface Printed Film Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Co Extruded Films Market
Poly film
India BOPP Films Market