
 Polycoated Packaging Market | 2026-2036
Polycoated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Polycoated Packaging Market Analytics
Project finance for coating lines is fragmenting the competitive landscape by lowering capital barriers for mid-scale entrants. Amcor Plc leverages its integrated film supply chain to sustain cost advantages in high-volume flexible packaging contracts. Mondi Group anchors its position through captive pulp-to-paperboard operations across Central European mills. WestRock competes via containerboard integration that extends its reach into food-service polycoated grades.
Polycoated packaging consists of paperboard or paper substrates laminated with extruded polyethylene or polypropylene layers, typically achieving moisture vapor transmission rates below 10 g/m²/day to protect perishable contents. The manufacturing process employs tandem extrusion coating at line speeds exceeding 300 m/min, bonding molten polymer directly to primed cellulose surfaces for liquid and grease resistance. Flexible packaging leads volume consumption due to its dominance in snack and frozen food applications, while rigid packaging commands premium positioning in pharmaceutical blister formats where barrier properties determine shelf-life certification. Bags represent the fastest-growing product type as e-commerce fulfillment drives demand for lightweight, weather-resistant shipping enclosures.
FDA food-contact substance regulations and EPA emissions standards for extrusion coating operations shape product formulation and plant siting decisions across the United States. The EU Green Deal packaging waste framework and REACH chemical compliance requirements are redirecting R&D spending toward recyclable mono-material structures in European operations. Stakeholders must monitor evolving extended producer responsibility schemes and substrate recyclability certifications as these criteria increasingly gate retail channel access and brand procurement approvals.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing design cycles across European supply chains, forcing substrate redesign toward recyclable mono-material structures before recyclability certifications gate retail channel access.
Growth Catalysts
- Extended Shelf-Life Food Demand:Food processors in Germany's industrial corridor are expanding polycoated packaging procurement for moisture-sensitive applications requiring vapor transmission rates below 10 g/m²/day.
- REACH Chemical Compliance:The EU's REACH framework is redirecting R&D spending toward barrier coatings that eliminate perfluorinated substances while maintaining grease resistance.
- E-Commerce Fulfillment Surge:Third-party logistics providers are driving bag volume growth through demand for weather-resistant shipping enclosures that withstand last-mile handling stress.
Market Restraints
- Polymer Feedstock Volatility:Extrusion coating operations face margin compression from polyethylene and polypropylene price swings tied to naphtha-cracker output decisions in the Gulf Coast petrochemical cluster.
- Recyclability Certification Friction:Extended producer responsibility schemes in France and Italy are creating compliance fragmentation as national labeling requirements diverge from harmonized EU standards.
- Paperboard Substitution Pressure:Molded fiber formats with aqueous barrier coatings are capturing share in food-service applications where heat tolerance requirements have relaxed.
Strategic Opportunities
- Central European Captive Integration:Mid-scale converters can secure cost positions through backward integration into primed paperboard production, replicating Mondi's pulp-to-paperboard model at smaller scale.
- Pharmaceutical Blister Expansion:High-barrier polycoated grades for thermoformed pharmaceutical packaging offer premium positioning as FDA food-contact substance regulations tighten traceability requirements.
- Digital Print Compatibility:Water-based ink adhesion on modified polyethylene surfaces is opening short-run customization for regional snack brands seeking SKU proliferation without plate costs.
Industry Challenges
- Extrusion Coating Technician Scarcity:Tandem line operation at speeds exceeding 300 m/min demands specialized polymer rheology expertise that vocational programs in Central Europe have not scaled to match equipment installation rates.
- Legacy Lamination Asset Stranding:Solvent-based adhesive lines face accelerated obsolescence as EPA emissions standards for coating operations tighten volatile organic compound thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycoated Packaging Market |
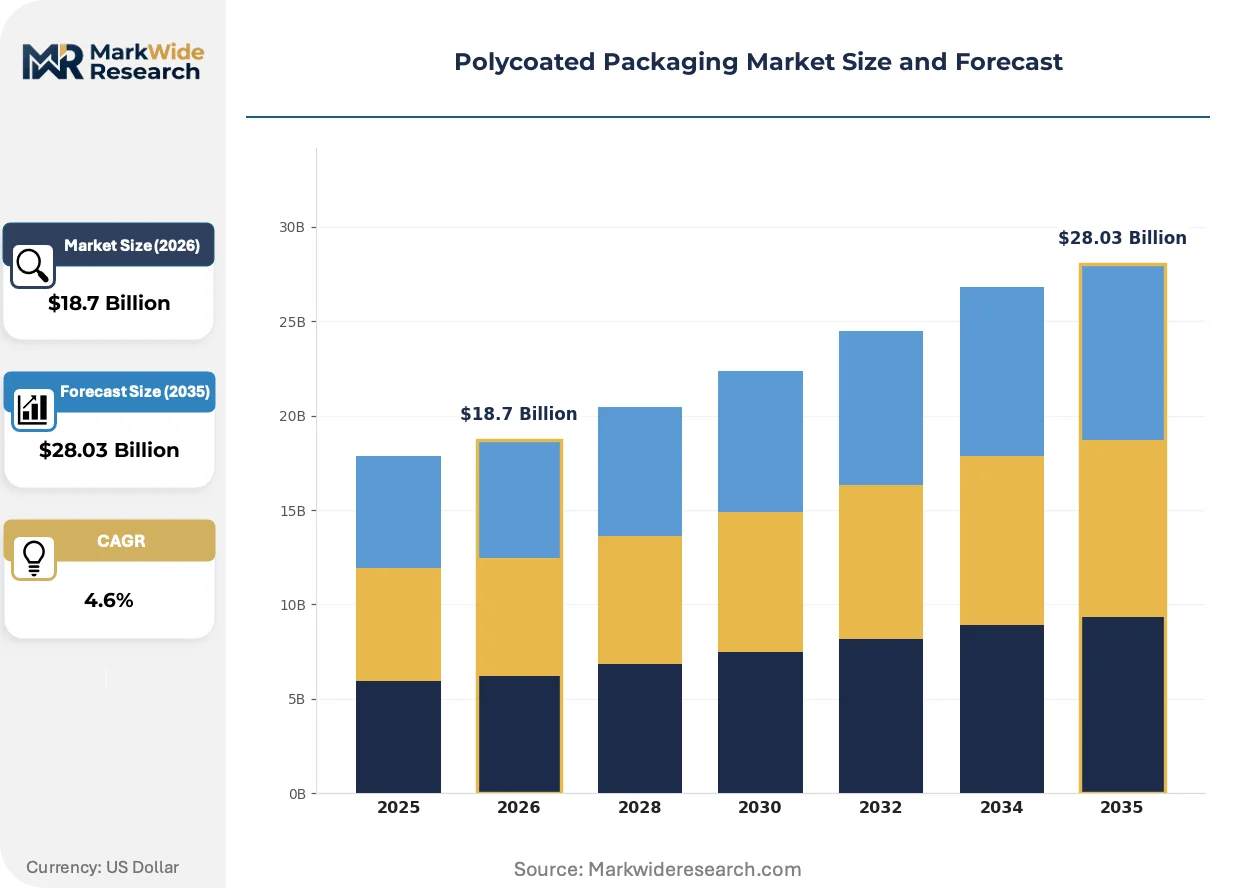
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Bags, Blisters End User: Food Industry, Pharmaceutical Sector, Personal Care, Household Products Material: Polyethylene, Polypropylene, Paperboard, Cardboard Feature: Moisture Resistance, Tear Resistance, Chemical Resistance, Barrier Properties |
| Companies Covered | Amcor Plc, Mondi Group, WestRock, Sealed Air Corporation, UFlex, Huhtamaki, Tetra Pak, Stora Enso, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycoated Packaging Market Evolving Landscape
Barrier technology is pivoting toward mono-material architectures as recyclability becomes a procurement gate, while coating deposition methods and substrate priming chemistries undergo simultaneous revision.
Water-based barrier coatings are migrating from niche bakery applications to mainstream frozen food packaging as Nestlé and Unilever procurement teams mandate home-compostable alternatives to polyethylene laminates. The technology is migrating from pilot-line trials to commercial-scale deployment across Nordic retail private-label programs, compressing the viable window for conventional extrusion coating investments in ambient shelf-stable segments.
The EU Green Deal packaging waste framework is mandating design-for-recycling protocols that prohibit multi-material structures from bearing recyclability logos. This industrial consequence is redirecting capital toward extrusion coating lines capable of processing bio-based polyethylene with identical melt-flow characteristics to fossil grades. Frozen food and ready-meal segments in Germany and the Netherlands are responding fastest, with several suppliers achieving APR recyclability recognition ahead of 2025 enforcement milestones.
Brand procurement teams are consolidating supplier panels around certified circularity credentials rather than unit cost alone. Food manufacturers in the Benelux region are displacing spot-market purchasing with multi-year tolling agreements that guarantee recycled content percentages. This pattern is most visible in dairy and chilled prepared meals, where retailer sustainability scorecards now weight packaging recyclability above historical price-performance metrics.
Polycoated Packaging Market Segmentation
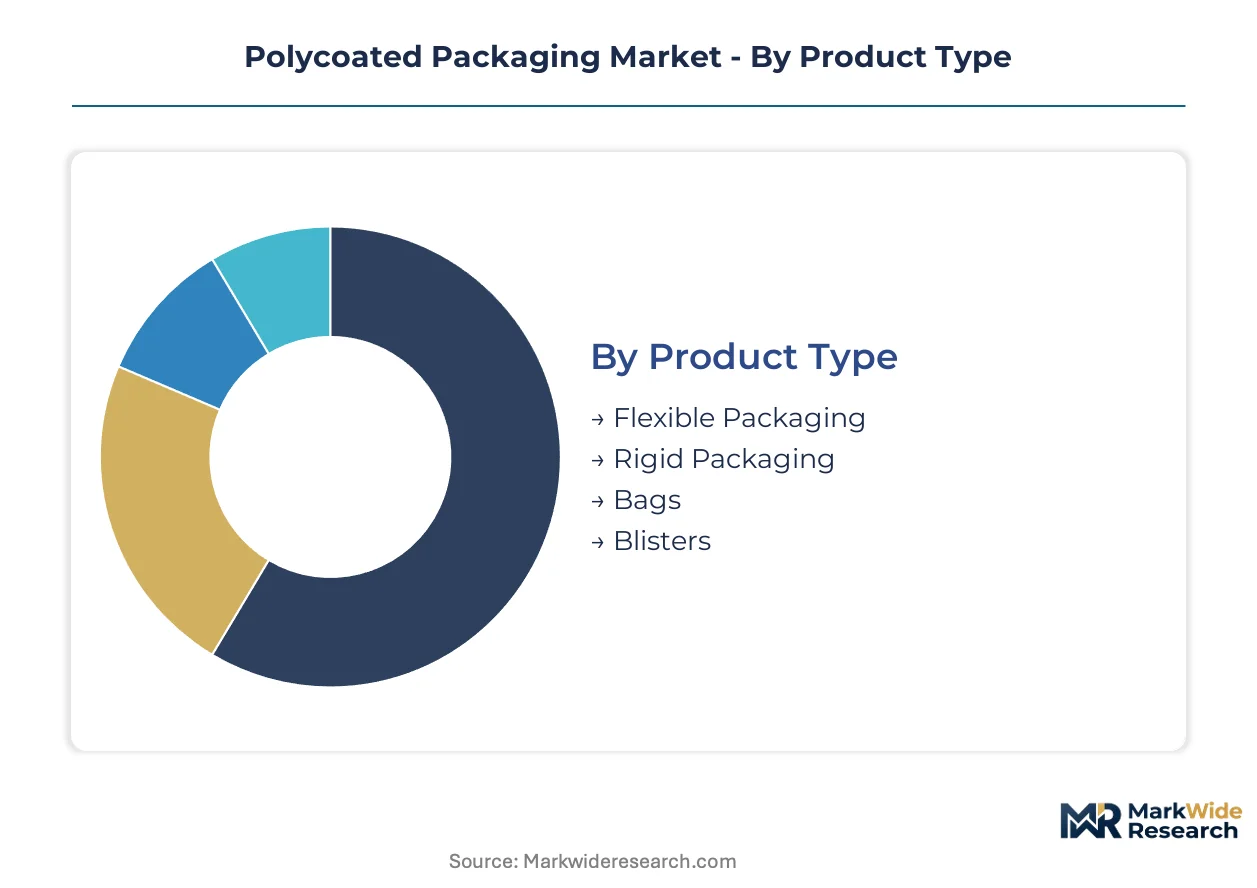
Polycoated packaging demand fragments across performance requirements that trade barrier specifications against recyclability mandates. Each segmentation dimension reveals distinct procurement patterns driven by shelf-life sensitivity, regulatory exposure, and substrate compatibility.
Product Type:
Packaging formats span a use-case spectrum from high-volume flexible wraps to precision-engineered rigid formats, with line speed and barrier specification determining equipment investment thresholds.
- Flexible Packaging:Multi-layer films laminated with extruded polyethylene dominate snack and frozen food applications, achieving moisture vapor transmission rates below 10 g/m²/day through tandem extrusion coating at speeds exceeding 300 m/min. German food processors in the industrial corridor are expanding procurement for extended shelf-life applications where barrier consistency gates retail distribution.
- Bags:Lightweight weather-resistant enclosures are capturing e-commerce fulfillment volume as third-party logistics providers prioritize last-mile durability. The segment is climbing the fastest as fulfillment networks replace corrugated boxes with polymer-laminated paper shipping sleeves.
- Rigid Packaging:Thermoformed paperboard structures serve prepared meal trays and pharmaceutical formats requiring dimensional stability under thermal stress.
- Blisters:High-barrier polycoated grades for pharmaceutical thermoforming command premium positioning where FDA food-contact substance regulations tighten traceability requirements.
The dominant share belongs to Flexible Packaging, while Bags is closing the gap fastest.
End User:
Customer concentration varies by margin structure, with pharmaceutical procurement teams paying barrier premiums that food manufacturers resist.
- Food Industry:Moisture-sensitive applications in Germany's processing corridor drive specification of vapor transmission rates below 10 g/m²/day for ambient and chilled shelf-stable segments. EU Green Deal packaging waste directives are compressing design cycles toward recyclable mono-material structures.
- Pharmaceutical Sector:Thermoformed blister formats demand high-barrier polycoated grades where shelf-life certification determines regulatory approval. FDA food-contact substance regulations and REACH chemical compliance requirements are redirecting R&D spending toward traceable coating chemistries.
- Personal Care:Tubes and sachets for cosmetics and hygiene products prioritize grease resistance and aesthetic print compatibility.
- Household Products:Detergent and cleaning supply packaging emphasizes chemical resistance for caustic contents.
Food Industry commands the volume base, though Pharmaceutical Sector captures the steepest expansion trajectory as barrier specifications tighten.
Material:
Substrate selection tracks polymer feedstock volatility and recyclability certification requirements that diverge across national extended producer responsibility schemes.
- Polyethylene:Extrusion coating operations bond low-density and linear low-density grades to primed cellulose surfaces for liquid and grease resistance. The EU Green Deal is redirecting capital toward lines processing bio-based polyethylene with identical melt-flow characteristics to fossil grades.
- Paperboard:Captive pulp-to-paperboard operations across Central European mills anchor cost positions for converters serving frozen food and ready-meal segments. APR recyclability recognition is displacing spot-market purchasing with multi-year tolling agreements in Benelux dairy applications.
- Polypropylene:Higher heat tolerance serves microwaveable applications where thermal stability exceeds polyethylene performance.
- Cardboard:Lower-grade recycled fiber substrates compete in cost-sensitive shipping and protective packaging.
Polyethylene retains the installed base, while Paperboard is gaining share fastest as recyclability certifications gate retail channel access.
Feature:
Performance attributes map directly to regulatory compliance and end-use risk exposure, with moisture specifications dominating food procurement while chemical resistance governs pharmaceutical and industrial applications.
- Moisture Resistance:Vapor transmission specifications below 10 g/m²/day protect perishable contents in Germany's frozen food and ready-meal supply chains. Water-based barrier coatings are migrating from niche bakery applications to mainstream deployment as Nestlé and Unilever procurement teams mandate home-compostable alternatives.
- Barrier Properties:Multi-functional protection combining moisture, oxygen, and light resistance serves pharmaceutical blister formats where shelf-life certification determines market access. FDA and EMA regulations are tightening traceability requirements for coating chemistries.
- Tear Resistance:Polymer lamination thickness and orientation enhance durability for e-commerce shipping applications.
- Chemical Resistance:Grease and solvent barriers maintain package integrity for household cleaning products and industrial lubricants.
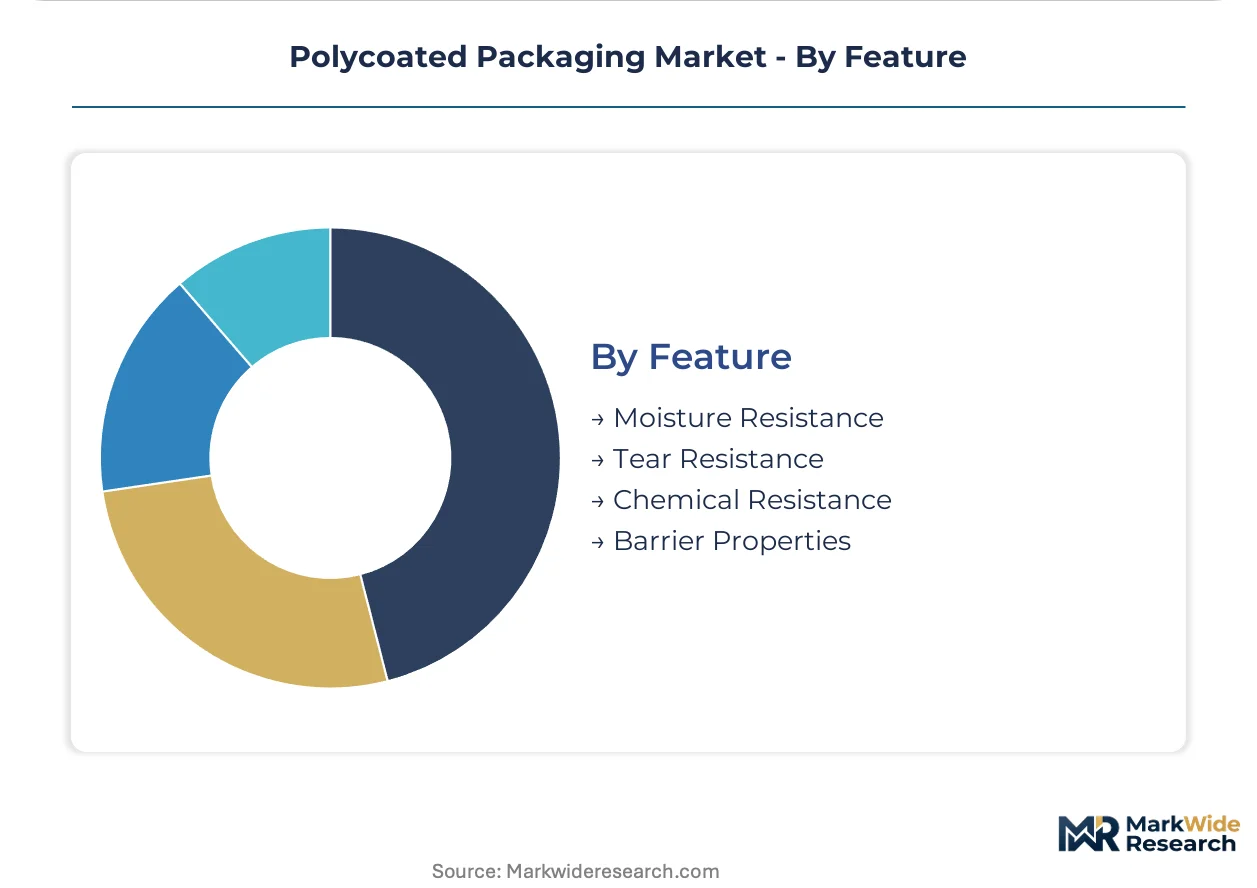
Moisture Resistance holds the specification frequency lead, though Barrier Properties is expanding most quickly as pharmaceutical procurement consolidates around certified circularity credentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processors and pharmaceutical contract manufacturers dominate procurement across concentrated industrial corridors. Buyers in Germany's processing belt specify vapor transmission rates below 10 g/m²/day for moisture-sensitive applications. EU Green Deal packaging waste directives are compressing design cycles toward recyclable mono-material structures.
Germany
Frozen food and ready-meal processors in the industrial corridor are expanding polycoated packaging procurement for extended shelf-life applications. REACH chemical compliance requirements are redirecting R&D spending toward barrier coatings that eliminate perfluorinated substances while maintaining grease resistance. Production clusters in Lower Saxony and Bavaria are retrofitting extrusion coating lines to process bio-based polyethylene ahead of 2025 enforcement milestones.
United States
Snack food manufacturers and third-party logistics providers are driving bag volume growth through demand for weather-resistant shipping enclosures. FDA food-contact substance regulations and EPA emissions standards for extrusion coating operations shape product formulation and plant siting decisions. Gulf Coast petrochemical clusters supply polyethylene feedstock to coating operations, though naphtha-cracker output decisions create margin volatility for converters.
Netherlands
Dairy and chilled prepared meal producers are displacing spot-market purchasing with multi-year tolling agreements that guarantee recycled content percentages. EU Green Deal packaging waste framework mandates design-for-recycling protocols that prohibit multi-material structures from bearing recyclability logos. Benelux retail private-label programs are achieving APR recyclability recognition ahead of harmonized EU standards.
China
E-commerce fulfillment networks are replacing corrugated boxes with polymer-laminated paper shipping sleeves, driving bag segment expansion. GB standards and MIIT regulations govern food-contact material safety and industrial emissions for coating operations. Yangtze River Delta manufacturing hubs are installing tandem extrusion coating lines at speeds exceeding 300 m/min to serve domestic frozen food brands.
India
Regional snack brands are adopting digital print-compatible polycoated formats for SKU proliferation without plate costs. FSSAI food safety regulations and BIS standards shape barrier coating approvals for domestic and export markets. Maharashtra and Gujarat industrial corridors are attracting mid-scale converters seeking backward integration into primed paperboard production.
Polycoated Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Consolidation pressure concentrates around integrated film supply chains and captive pulp-to-paperboard operations that anchor cost positions. Three archetypes dominate: multinational packaging conglomerates with extrusion coating scale, regional converters with backward integration into substrate production, and specialty coating technology licensors. Competitive moves center on capacity expansion in Central European industrial corridors and portfolio diversification toward pharmaceutical barrier grades.
Within the multinational conglomerate tier, Amcor Plc and Mondi Group exemplify divergent integration strategies. Amcor leverages integrated film supply chains for flexible packaging scale, while Mondi anchors positions through captive pulp-to-paperboard operations across Central European mills. WestRock occupies a position bridging containerboard integration with food-service polycoated grades. These three represent the dominant competitive anchors shaping procurement consolidation around certified circularity credentials.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| WestRock |
| Sealed Air Corporation |
| UFlex |
| Huhtamaki |
| Tetra Pak |
| Stora Enso |
| Smurfit Kappa |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container rate volatility transmits directly into polycoated packaging landed costs, amplifying price differentiation between integrated producers and toll-dependent converters while compressing margins for mid-scale entrants lacking captive pulp supplies.
Pricing Analysis
Cost-plus contracts indexed to ICIS polyethylene assessments dominate long-term supply agreements between German food processors and coating converters. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-certified barrier grades from commodity frozen-food specifications. Pricing pressure stems from naphtha-cracker output decisions in Gulf Coast petrochemical clusters that swing polymer feedstock costs. Food manufacturers exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize barrier consistency over unit cost.
Supply Chain Analysis
Extended payment terms stretching to 90 days and supply-chain finance facilities anchored by Nordic banks have become standard procurement terms for Benelux retail private-label programs. Geographic concentration centers on Germany, Finland, and the Netherlands for captive pulp-to-paperboard operations. Raw material dependencies draw from Nordic softwood pulp, Saudi polyethylene resin, and Chinese coating additives. Single-source vulnerability runs through Gulf Coast naphtha crackers supplying polymer feedstock. Distribution runs through Central European converting hubs serving industrial corridor food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycoated packaging market faces high-growth disruption as EU Green Deal recyclability mandates compress design cycles toward mono-material architectures before certification gates retail access.
For Market Incumbents: Harden barrier technology positions through captive integration into primed paperboard production across Lower Saxony and Bavaria mill clusters. Accelerate APR recyclability certification ahead of enforcement milestones to preempt competitor displacement in Benelux dairy supply chains. Molded fiber substitution with aqueous coatings threatens food-service share. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer underpenetrated white-space for digital print-compatible formats serving regional snack brand SKU proliferation. Target pharmaceutical blister barrier grades where FDA traceability requirements tighten procurement consolidation. Pursue tolling agreements with Nordic retail private-label programs seeking guaranteed recycled content percentages. For Investors and Strategic Acquirers: Specialty coating technology licensors with bio-based polyethylene processing capabilities represent the most defensible acquisition archetype across the analysis window. Mid-scale converters achieving backward integration into primed paperboard production replicate Mondi's cost position at smaller scale. Monitor APR recyclability recognition rates as inflection indicator for procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primed Paperboard | Captive pulp supply replicates Mondi's Central European cost position for mid-scale converters. |
| Bio-Based Polyethylene Line Retrofit | German producers achieve identical melt-flow processing ahead of EU Green Deal enforcement milestones. |
| APR Recyclability Certification | Benelux dairy suppliers displace spot-market purchasing with multi-year tolling agreements. |
| Pharmaceutical Blister Grade Expansion | FDA food-contact substance regulations tighten traceability requirements for high-barrier formats. |
| Digital Print Compatibility Investment | Water-based ink adhesion opens short-run customization for India's regional snack brands. |
Research Methodology
Two parallel data streams informed the analysis: primary fieldwork with extrusion coating plant managers, food processor procurement leads, pharmaceutical packaging engineers, and Nordic retail sustainability directors; and secondary validation through ECHA REACH filings, EU Green Deal directive texts, FDA food-contact substance notifications, and trade flow data from Central European customs authorities. Bottom-up capacity assessments triangulated against top-down demand modeling across product type, end user, material, and feature segmentation dimensions.
Forecast inputs considered polymer feedstock price trajectories, recyclability certification adoption curves, and e-commerce fulfillment volume expansion across the analysis window. Segmentation modeling spanned product format, barrier specification tier, substrate material, and geographic regulatory cluster. CAGRs were derived from installed coating line capacity growth correlated with downstream demand elasticity in food and pharmaceutical end-use segments. Line speed thresholds exceeding 300 m/min and vapor transmission rate specifications below 10 g/m²/day anchored technical performance assumptions.
Practitioners should monitor EU member state divergence in extended producer responsibility implementation and bio-based polyethylene scale-up timelines for early signals of competitive repositioning. Forecasts reflect assumptions about harmonized recyclability standard adoption and polymer feedstock cost stabilization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
France Plastic Packaging Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
PE Foam Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Global PVDC Coated Films Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
In-Mould Label Film Market
Poly film
Polystyrene Films Market
Poly film
Recyclable Lidding Films Market
Poly film
Polysaccharide Films Market
Poly film
Global BOPET Packaging Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Soft Touch Lamination Film Market