
 Polytetrafluoroethylene (PTFE) Films Market | 2026-2036
Polytetrafluoroethylene (PTFE) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polytetrafluoroethylene (PTFE) Films Market Analytics
Subscription-based technical support and software-defined thickness calibration is shifting how PTFE film suppliers monetize long-term customer relationships. 3M leverages its fluoropolymer R&D infrastructure to sustain premium positioning in aerospace-grade laminates. Saint-Gobain Performance Plastics anchors European supply through vertically integrated PTFE resin-to-film operations. Rogers Corporation differentiates via specialized dielectric formulations for 5G infrastructure substrates.
Polytetrafluoroethylene films are thin, high-molecular-weight fluoropolymer membranes typically manufactured through skived extrusion or paste extrusion, exhibiting dielectric constants below 2.1 and continuous service temperatures up to 260 degrees Celsius; they function primarily as chemically inert barriers and electrical insulators in aggressive thermal and corrosive environments. Sheet formats dominate volume throughput in chemical processing gasket applications where standardized dimensions reduce fabrication waste. Roll formats are expanding fastest in electronics, driven by continuous-feed requirements for flexible printed circuit lamination. Coated variants command margin concentration due to customized adhesive layers that eliminate downstream bonding steps for valve seat and seal integrators.
EPA regulates PTFE processing emissions under fluoropolymer fume guidelines, while REACH restricts perfluorinated precursor substances in European resin supply chains. FDA compliance governs food-contact PTFE films through 21 CFR 177.1550, constraining additive packages and extraction limits for conveyor and processing equipment. Semiconductor fabricators, aerospace tier-1 suppliers, and chemical OEMs must monitor regulatory divergence between US fluoropolymer emission rules and EU substance restrictions as they qualify dual-source film specifications.
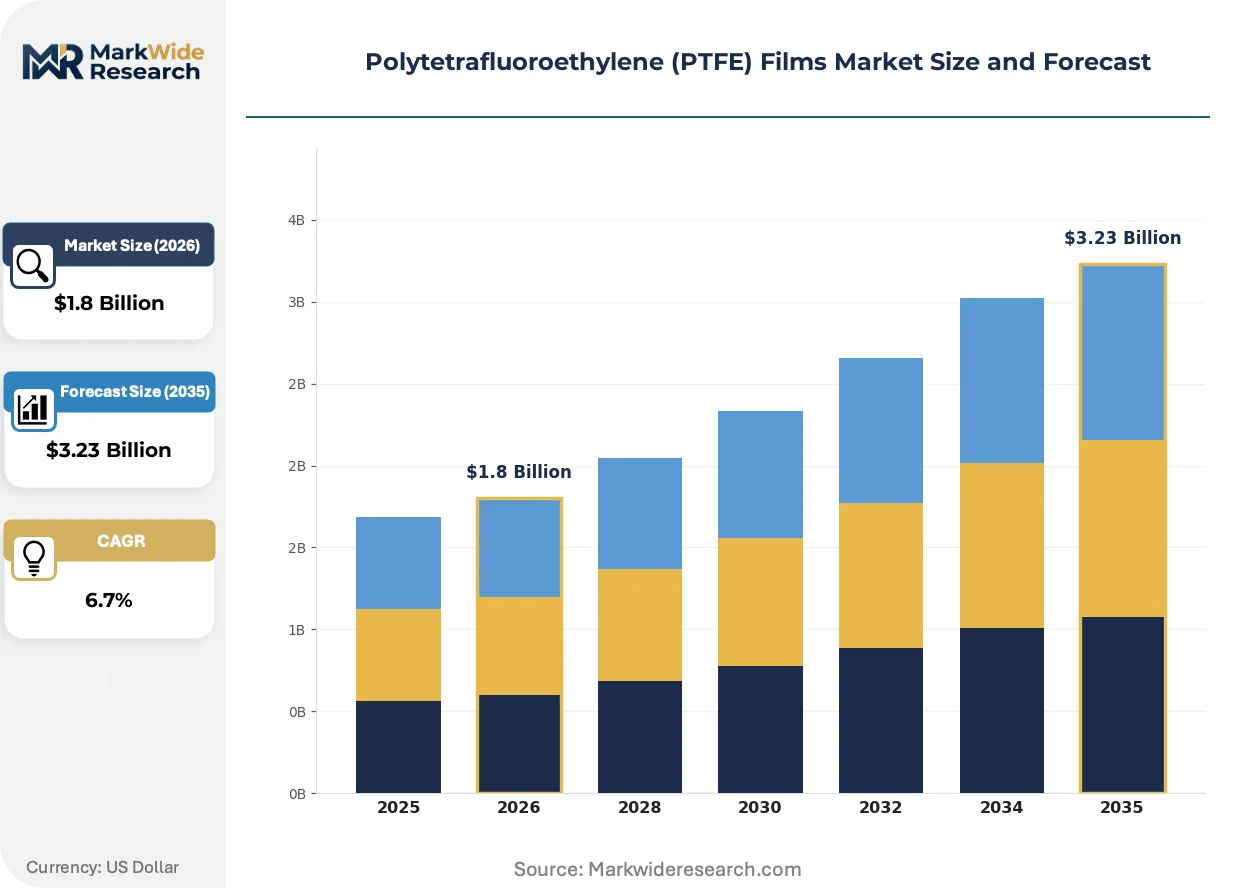
Market Dynamics
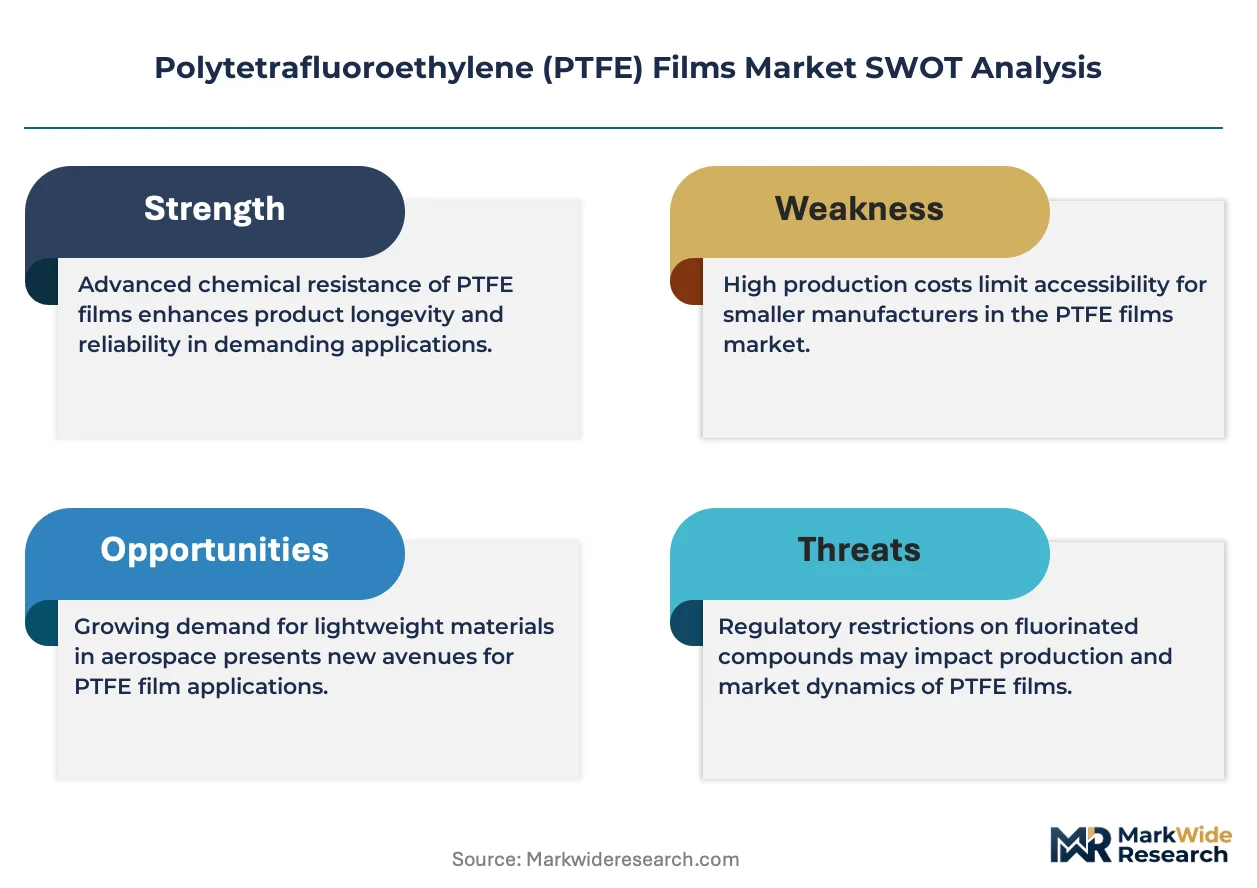
Semiconductor substrate manufacturers are compressing dielectric thickness tolerances below 25 microns, forcing PTFE film extruders to retrofit skiving lines with laser-gauged feedback systems or exit high-frequency laminate supply chains entirely.
Growth Catalysts
- REACH substance restrictions:European resin purity mandates are disqualifying lower-grade fluoropolymer imports, creating specification premiums for ECHA-compliant film suppliers.
- 5G base station deployment:Dielectric substrate fabricators in China and South Korea are qualifying PTFE laminates for millimeter-wave antenna modules.
- Fluoropolymer fume guidelines:EPA emission controls are accelerating capital upgrades at US-based paste extrusion facilities, tightening domestic supply availability.
Market Restraints
- Fluorspar concentrate volatility:Acid-grade fluorspar pricing swings directly transmit to PTFE resin costs, squeezing film processor margins during procurement cycles.
- Skived film thickness limitations:Mechanical skiving cannot reliably produce sub-12.5 micron films without pinhole defects, capping penetration in advanced flexible circuit stacks.
- Perfluorinated precursor scrutiny:ECHA restrictions on long-chain fluorinated substances are constraining European resin supply chains and extending qualification timelines.
Strategic Opportunities
- India semiconductor fabrication:PLI scheme incentives for domestic chip manufacturing are creating first-mover advantages for film suppliers establishing local lamination partnerships.
- Adhesive-coated roll formats:Pre-applied silicone and acrylic bonding layers eliminate downstream lamination steps for valve seal integrators, capturing margin concentration.
- Dual carbon goals:China's MEE emission reduction mandates are accelerating fluoropolymer process efficiency investments, favoring suppliers with captive resin-to-film operations.
Industry Challenges
- Dielectric metrology expertise:Semiconductor fabricators require sub-0.5% dielectric constant variation certification, creating talent scarcity in RF materials characterization.
- Multi-jurisdiction qualification fatigue:Dual-source specifications must simultaneously satisfy FDA 21 CFR 177.1550, REACH Annex XVII, and EPA fume guidelines, extending validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polytetrafluoroethylene (PTFE) Films Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Roll, Laminate, Coated Application: Electrical Insulation, Gaskets, Seals, Valve Seats End User: Aerospace, Chemical Processing, Food Industry, Electronics Manufacturing Stage: Extrusion, Casting, Machining, Joining |
| Companies Covered | 3M, Rogers Corporation, Saint-Gobain Performance Plastics, Nitto Denko Corporation, Lenzing Plastics GmbH & Co. KG, Chukoh Chemical Industries Ltd, DUNMORE Corporation, Guarniflon SpA, Technetics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polytetrafluoroethylene (PTFE) Films Market Evolving Landscape
Modified PTFE formulations and precision thickness control systems are compressing the performance gap between commodity skived films and aerospace-grade laminates, reshaping supplier tiering across end-use verticals.
Expanded PTFE (ePTFE) membranes with node-fibril microstructures are overtaking conventional skived films in high-frequency printed circuit applications. 5G infrastructure substrate manufacturers in South Korea and China are specifying ePTFE for dielectric layers below 50 microns. The technology is overtaking legacy paste-extruded films in millimeter-wave antenna modules where controlled porosity reduces signal loss.
EU F-Gas Regulation phase-down schedules are constraining hydrofluorocarbon feedstock availability for European PTFE resin production. German and French chemical processors are reformulating polymerization initiators to reduce perfluorinated byproduct generation. Aerospace gasket and seal manufacturers are accelerating qualification of alternative cure chemistries to preempt supply interruption.
Buyers in semiconductor fabrication are consolidating film procurement through direct mill relationships, bypassing regional distributors. Large substrate laminators in Taiwan and Japan are negotiating annual volume commitments with extruders for dedicated production slots. This concentration is most visible in 300mm wafer processing equipment supply chains where traceability requirements favor single-source qualification.
Polytetrafluoroethylene (PTFE) Films Market Segmentation
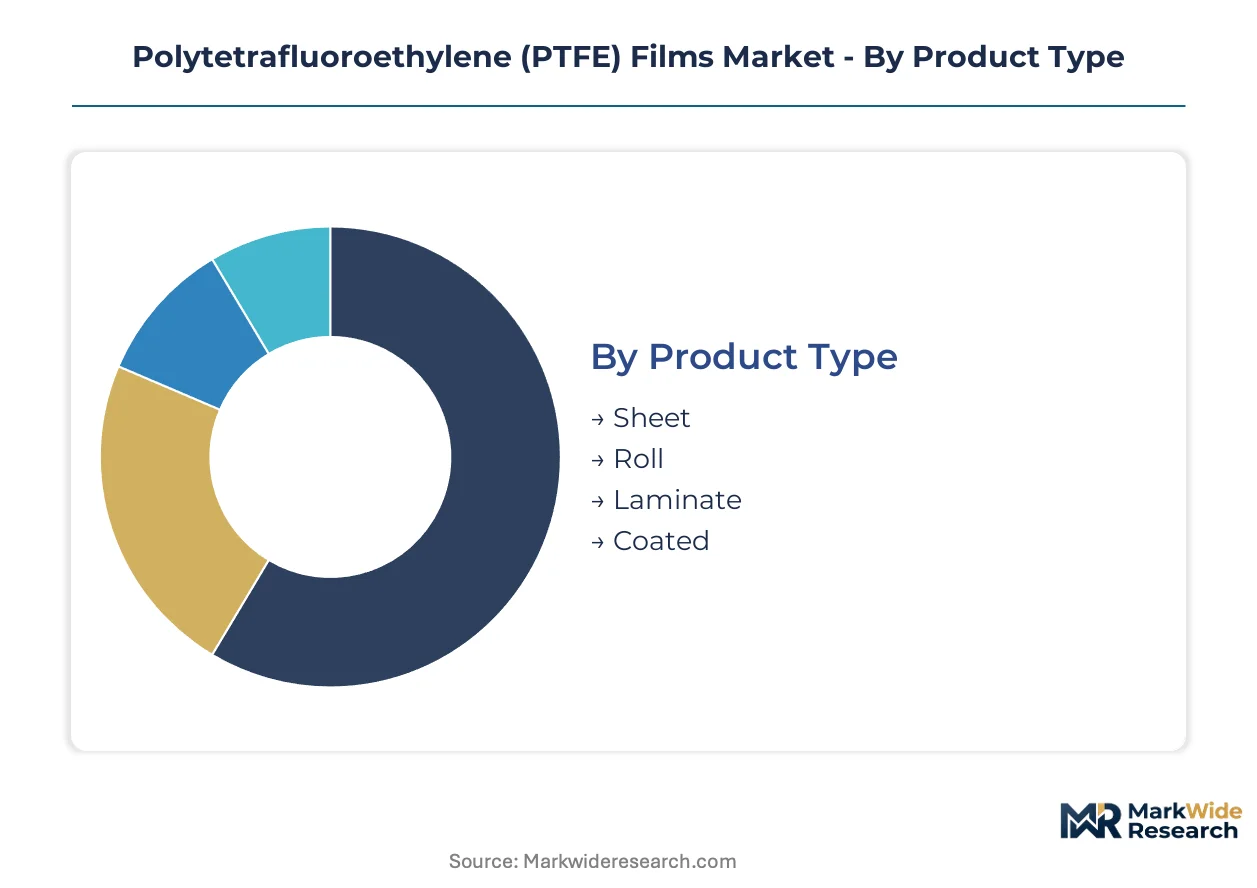
PTFE film procurement patterns diverge sharply across product formats and end-use certifications. Semiconductor fabricators, aerospace tier-1 suppliers, and chemical OEMs each impose distinct specification burdens that reshape supplier tiering and margin capture.
Product Type:
FDA 21 CFR 177.1550 governs sheet and roll formats destined for food-contact conveyor systems, while aerospace-grade laminates must satisfy FAA material flame-resistance protocols alongside EPA fluoropolymer fume compliance during manufacture.
- Sheet:Standardized dimensional formats dominate chemical processing gasket fabrication where die-cutting waste reduction drives procurement economics. Demand concentrates in German and French chemical OEMs qualifying REACH Annex XVII compliant material for reactor sealing systems, with thickness tolerances above 100 microns.
- Roll:Continuous-feed formats serve flexible printed circuit lamination for 5G antenna substrate manufacturers in South Korea and Taiwan. Millimeter-wave dielectric specifications below 50 microns compress thickness variation requirements, forcing extruders to deploy laser-gauged skiving lines.
- Laminate:Multi-layer bonded structures for aerospace pressure vessel insulation.
- Coated:Pre-applied adhesive variants eliminating downstream bonding steps for valve seat integrators.
Leading the category by volume: Sheet formats in chemical processing gasket applications. Growing fastest: Roll formats for electronics lamination.
Application:
Application selection dictates whether PTFE films function as passive barriers or active electrical components, with semiconductor substrate requirements imposing the most stringent dielectric metrology.
- Electrical Insulation:Dielectric constant stability below 2.1 with sub-0.5% variation certification separates qualified suppliers from commodity extruders. Semiconductor fabricators in Taiwan and Japan specify these films for 300mm wafer processing equipment, requiring traceability documentation that favors direct mill relationships over distribution.
- Gaskets:Compression set resistance and chemical inertness against aggressive process media define specification. Chemical processors in Germany specify ECHA-compliant material for reactor sealing, with qualification cycles extending 18-24 months for new resin sources.
- Seals:Dynamic sealing surfaces for valve and pump applications.
- Valve Seats:Dimensional stability under thermal cycling for process control equipment.
Highest certification burden: Electrical insulation for semiconductor fabrication. Steepest expansion trajectory: Gaskets as European chemical OEMs dual-source away from constrained fluorspar supply chains.
End User:
End-user verticals impose divergent purity, traceability, and documentation requirements that fragment supplier qualification pools across aerospace, chemical, food, and electronics sectors.
- Aerospace:Tier-1 suppliers mandate flame-resistance certification per FAA guidelines alongside lot-level traceability for pressure vessel and insulation applications. German and French aerospace gasket manufacturers are accelerating alternative cure chemistry qualifications to preempt EU F-Gas Regulation feedstock interruptions.
- Chemical Processing:Aggressive media exposure drives specification toward modified PTFE formulations with enhanced creep resistance. REACH substance restrictions on long-chain fluorinated precursors are disqualifying lower-grade imports, creating specification premiums for ECHA-compliant European suppliers.
- Food Industry:FDA 21 CFR 177.1550 extraction limits constrain additive packages for conveyor and processing equipment films.
- Electronics:Substrate lamination for 5G infrastructure and semiconductor fabrication equipment.
Deepest qualification moats: Aerospace tier-1 supply chains. Fastest volume scaling: Electronics as China domestic semiconductor fabrication scales PTFE procurement.
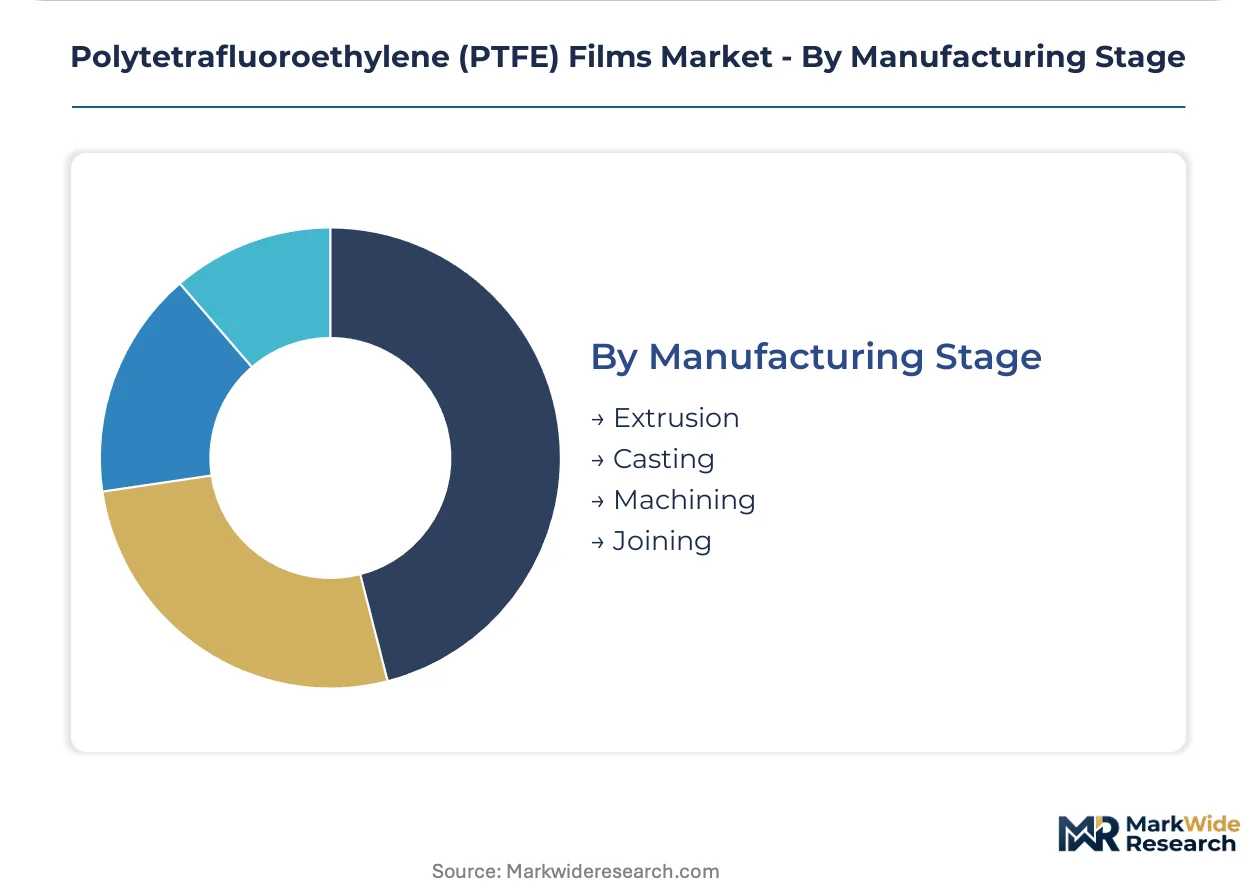
Manufacturing Stage:
Process stage selection determines whether PTFE films achieve the thickness precision and defect control required for high-frequency electronics versus the cost economics of industrial sealing applications.
- Extrusion:Paste extrusion followed by skiving yields films from 12.5 to 500 microns. EPA fluoropolymer fume guidelines are accelerating capital upgrades at US-based facilities, tightening domestic supply availability while South Korean and Chinese extruders capture 5G substrate qualification.
- Casting:Solvent-cast films achieve sub-10 micron thicknesses for advanced flexible circuit stacks where mechanical skiving produces pinhole defects. Demand concentrates in Japanese and Taiwanese flexible printed circuit manufacturers.
- Machining:Post-extrusion dimensional refinement for tight-tolerance gasket applications.
- Joining:Thermal and adhesive bonding processes for laminate assembly.
Highest capital intensity: Extrusion with emission control retrofits. Expanding most quickly: Casting for sub-25 micron electronics specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of PTFE resin feedstock, yet semiconductor-grade film demand concentrates in Japan, South Korea, and Taiwan where substrate laminators impose sub-25 micron specifications. This production-consumption divide shapes cross-border qualification cycles and regional pricing premiums.
United States
EPA fluoropolymer fume guidelines are accelerating capital upgrades at paste extrusion facilities in Texas and Ohio, tightening domestic supply availability. Semiconductor equipment OEMs in California's Bay Area specify direct mill relationships for 300mm wafer processing films. Rogers Corporation anchors North American supply through specialized dielectric formulations.
Germany
Chemical OEMs in the Rhine-Ruhr industrial cluster specify ECHA-compliant material for reactor sealing systems with qualification cycles extending 18-24 months. REACH Annex XVII restrictions on long-chain fluorinated precursors are disqualifying lower-grade imports. German aerospace tier-1 suppliers mandate FAA flame-resistance certification alongside lot-level traceability.
China
Domestic semiconductor fabrication scaling under the dual carbon goals is accelerating fluoropolymer process efficiency investments. Yangtze River Delta substrate laminators are negotiating annual volume commitments for dedicated production slots. MEE emission reduction mandates favor suppliers with captive resin-to-film operations.
Japan
Flexible printed circuit manufacturers in Kansai and Chubu regions drive demand for solvent-cast films below 12.5 microns where mechanical skiving produces pinhole defects. METI industrial standards govern dielectric metrology certification for 5G antenna substrate exports. Japanese semiconductor fabricators require sub-0.5% dielectric constant variation documentation.
South Korea
5G base station deployment is qualifying PTFE laminates for millimeter-wave antenna modules in the Seoul Capital Area. Samsung and LG substrate divisions are compressing thickness tolerances below 25 microns, forcing extruders to deploy laser-gauged skiving lines. MFDS regulatory alignment with REACH substance restrictions streamlines export qualification.
Polytetrafluoroethylene (PTFE) Films Market Competitive Landscape
Top-tier vendors anchor premium aerospace and semiconductor-grade supply chains, while mid-scale fabricators compete on chemical processing and industrial sealing volumes. The market structures around three strategic archetypes: fluoropolymer conglomerates with captive resin operations, specialized dielectric formulators serving 5G infrastructure, and regional sheet converters for gasket applications. Dominant competitive moves include backward integration into fluorspar refining and strategic partnerships with substrate laminators for dedicated production slots.
Among diversified materials conglomerates, 3M and Saint-Gobain exemplify the integrated archetype through in-house fluoropolymer R&D infrastructure. Rogers Corporation occupies a position within the specialized tier, representing dielectric-focused competitors that differentiate through formulation expertise rather than scale. Nitto Denko anchors Japanese supply for flexible circuit applications. These three named entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning across premium, standard, and economy certification grades.
| Leading Market Players |
|---|
| 3M |
| Rogers Corporation |
| Saint-Gobain Performance Plastics |
| Nitto Denko Corporation |
| Lenzing Plastics GmbH & Co. KG |
| Chukoh Chemical Industries Ltd |
| DUNMORE Corporation |
| Guarniflon SpA |
| Technetics Group |
| Others |
Value Network & Pricing Analysis
Acid-grade fluorspar pricing volatility cascades through PTFE resin procurement into three-tier pricing stratification across premium aerospace laminates, standard industrial sheets, and economy-grade chemical gaskets. Buyers in semiconductor fabrication absorb specification premiums for sub-25 micron dielectric certification, while chemical OEMs in Germany negotiate contract-based offtake agreements to hedge raw material swings.
Pricing Analysis
Cost compression in standard-grade sheet formats accelerates as Chinese resin oversupply pressures European extruders. Premium-mid-economy pricing differentiation hinges on REACH Annex XVII compliance status and dielectric constant certification precision. Semiconductor substrate laminators in Taiwan exhibit lowest price sensitivity due to traceability requirements, while valve seat integrators in industrial sealing drive hardest volume discounts.
Supply Chain Analysis
Fluorspar concentrate supply rests on Chinese mining operations, Mexican acid-grade processors, and South African metallurgical-grade exporters. PTFE resin production draws from tetrafluoroethylene monomer feedstocks subject to EPA fluoropolymer fume guidelines and EU F-Gas Regulation constraints. Single-source vulnerability concentrates in acid-grade fluorspar purification capacity. Distribution runs through direct mill relationships for semiconductor-grade film and regional distributors for chemical processing gasket stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PTFE film supply chains are consolidating around captive resin-to-film operations as fluorspar volatility and REACH substance restrictions reward upstream control. Players securing ECHA-compliant raw material pipelines and laser-gauged skiving capacity capture specification premiums in semiconductor and aerospace tiers.
For Market Incumbents: Deepen backward integration into acid-grade fluorspar refining or captive tetrafluoroethylene monomer production to defend margin position against Chinese resin oversupply. Accelerate laser-gauged skiving line deployment before South Korean substrate laminators finalize dual-source qualification pools. Preempt EU F-Gas Regulation feedstock interruptions through alternative cure chemistry partnerships with German aerospace tier-1 suppliers. For New Entrants and Emerging Players: Enter via solvent-cast film capabilities for sub-12.5 micron flexible circuit specifications where mechanical skiving produces pinhole defects. Target Japanese and Taiwanese flexible printed circuit manufacturers underserved by incumbent paste extrusion infrastructure. Qualify adhesive-coated roll formats for valve seat integrators seeking eliminated downstream bonding steps. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European sheet converters with ECHA-compliant resin pipelines and established chemical OEM qualification relationships. Long-term viability centers on dual carbon goals compliance and semiconductor fabrication equipment traceability certification. Watch acid-grade fluorspar price spreads against Chinese domestic resin indices as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Refining | Captive acid-grade supply secures margin stability against Mexican and Chinese concentrate volatility. |
| Laser-Gauged Skiving Line Deployment | Sub-25 micron thickness precision qualifies suppliers for Samsung and LG millimeter-wave antenna substrate programs. |
| REACH Annex XVII Compliance Investment | ECHA-certified resin access unlocks specification premiums in German chemical OEM reactor sealing procurement. |
| Adhesive-Coated Roll Format Expansion | Pre-applied silicone bonding layers capture valve seat integrator margin through eliminated lamination steps. |
| Alternative Cure Chemistry Partnership | F-Gas Regulation-resilient formulations preempt supply interruption for French aerospace gasket manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fluoropolymer plant managers, semiconductor substrate procurement leads, aerospace tier-1 supplier quality directors, and chemical OEM sealing system engineers validated demand assumptions. EPA fluoropolymer fume guidelines, ECHA REACH substance restriction updates, FDA 21 CFR 177.1550 extraction limit documentation, and semiconductor equipment OEM capex disclosures furnished cross-reference points. Bottom-up resin consumption models and top-down electronics substrate lamination forecasts underwent triangulation.
Segment-level granularity applied across product format, application function, end-user vertical, and manufacturing process stage throughout the projection horizon. Dielectric constant certification tiers, thickness tolerance bands, and geographic regulatory clusters shaped volume and value modeling. CAGRs derived from fluorspar price elasticity coefficients, semiconductor fabrication equipment installation trajectories, and 5G infrastructure deployment schedules across South Korea, China, and Japan.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluorspar concentrate supply disruption or accelerated EU perfluorinated precursor restrictions. Forecasts reflect documented assumptions regarding resin purity qualification timelines and substrate laminator dual-source consolidation patterns. A small set of triggers—acid-grade fluorspar price spikes, ECHA substance list expansion, and semiconductor capital expenditure cycle turns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Film Market
Poly film
APET Film Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Tube Laminating Films Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Recyclable Lidding Films Market
Poly film
EVOH Encapsulation Film Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Laminating Film Market
Poly film
Polyolefin Films Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Polymer Waterproof Rolls Market
Poly film
US Cleanroom Film and Bags Market