
 LDPE Containers Market | 2026-2036
LDPE Containers Market Size, Share, and Industry Trends Forecast 2026-2036
LDPE Containers Market Foresight
Asset-light leasing models for blow-molding equipment is fragmenting competitive dynamics among LDPE container producers. Berry Global Inc. leverages its North American manufacturing footprint to sustain cost-competitive supply agreements with food service distributors. ALPLA Werke Alwin Lehner anchors European demand through specialized barrier-coating technologies for sensitive personal care formulations. Graham Packaging Co. LP differentiates via in-house preform design capabilities that reduce material waste across high-volume bottle programs.
LDPE containers are thermoplastic vessels formed from low-density polyethylene resin through extrusion blow-molding or injection blow-molding processes, typically exhibiting density ranges of 0.910–0.940 g/cm³ and dart impact resistance suited to flexible, squeezable formats. Their primary commercial purpose centers on moisture-sensitive product protection combined with consumer convenience in dispensing and reclosure. Bottles occupy the dominant position within product type segmentation, reflecting entrenched demand from beverage and household chemical brands, while pouches represent the fastest-expanding category as portion-control and e-commerce-compatible formats gain traction across food packaging and personal care applications. Bags maintain mature volume positions in industrial bulk handling, though margin pools have compressed amid commoditization of standard gusseted designs.
FDA food-contact substance notifications govern LDPE resin approvals for domestic U.S. packaging applications, while EU REACH and the F-Gas Regulation constrain additive chemistries and processing aids permitted in European-manufactured containers. China's SAMR enforces GB 4806.6 standards for food-contact plastics, creating divergent compliance pathways for multinational producers serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to regionalize formulation portfolios or pursue unified global resin specifications that satisfy the most restrictive regulatory denominator.
Market Dynamics
Food service operators are consolidating procurement around flexible LDPE pouches for prepared meal delivery, compressing traditional rigid container volumes while redirecting resin demand toward high-clarity, thin-gauge extrusion grades. This demand rotation is forcing blow-molders to reconfigure asset utilization between bottle and pouch production lines.
Growth Catalysts
- EU REACH additive compliance:Reformulation toward non-phthalate plasticizers is opening specification windows for bio-based LDPE alternatives in personal care packaging.
- India organized retail expansion:Private-label grocery chains are scaling centralized packaging programs that specify LDPE containers for store-brand edible oils and dairy products.
- Barrier-coating advancement:Silicon oxide and EVOH coextrusion technologies are extending LDPE pouch shelf life into oxygen-sensitive food categories previously reserved for glass or metal.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker margins in Northeast Asia swing with crude oil indices, transmitting cost instability to LDPE resin contract pricing.
- Mechanical recycling contamination:Multi-layer barrier constructions and adhesive labels degrade regrind quality, limiting closed-loop supply availability for food-contact applications.
- China dual carbon policy:Provincial emissions caps on petrochemical clusters are constraining domestic LDPE resin output growth despite downstream demand expansion.
Strategic Opportunities
- Indonesia cold-chain buildout:Refrigerated logistics investment across archipelago distribution networks is creating demand for insulated LDPE liner bags in fresh produce handling.
- Extended producer responsibility mandates:EU packaging waste directives are incentivizing lightweighting designs that reduce per-unit polymer mass without sacrificing performance.
- E-commerce fulfillment optimization:Parcel-compatible flexible pouches with tamper-evident closures are displacing corrugated secondary packaging in direct-to-consumer personal care shipments.
Industry Challenges
- Blow-molding technician scarcity:Skilled operators capable of calibrating parison programming for thin-wall container production are concentrated among aging workforce cohorts in mature manufacturing regions.
- GB 4806.6 testing timelines:China's food-contact substance migration protocols require 90-day evaluation windows that delay new product launches versus FDA notification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LDPE Containers Market |
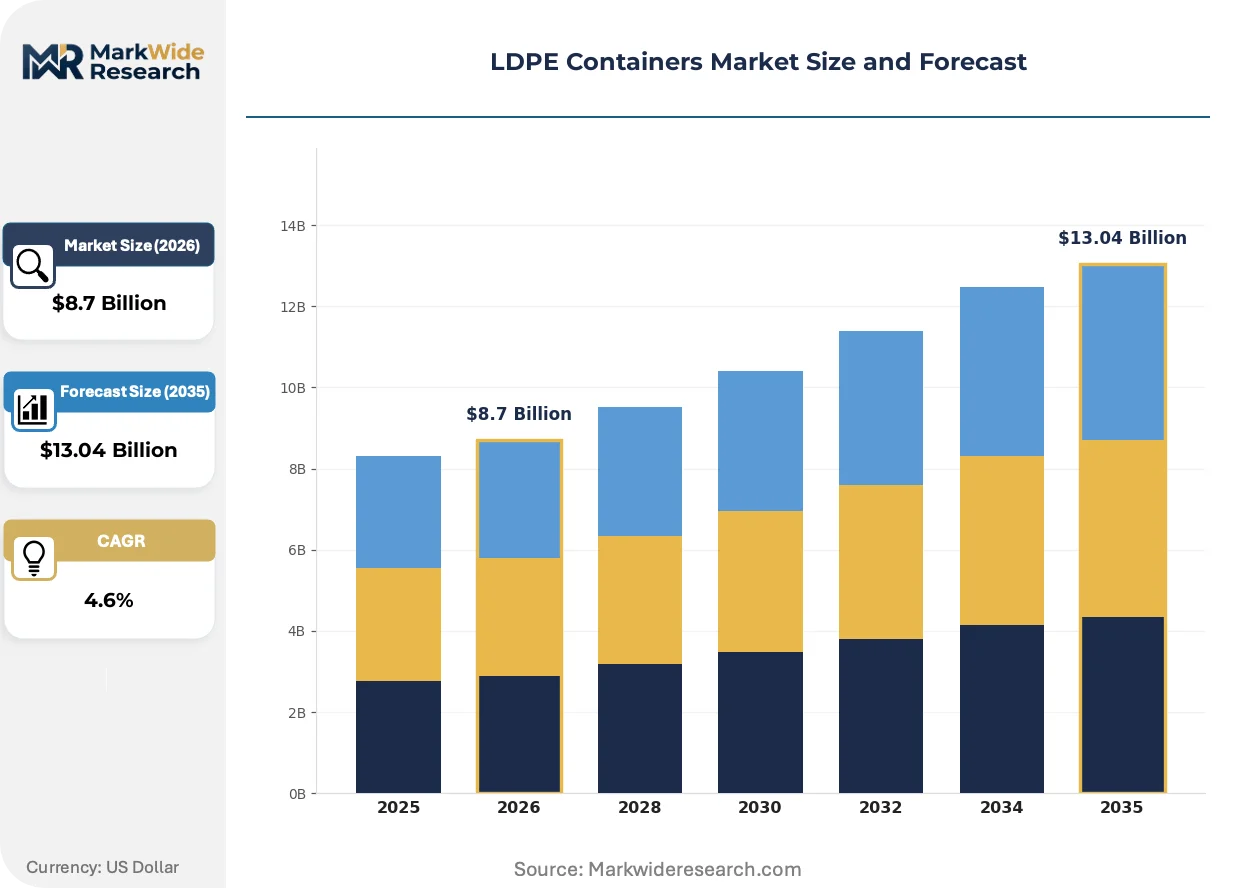
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Pouches, Bags Application: Food Packaging, Personal Care, Household Products, Medical Supplies End User: Retail, Food Service, Healthcare, Industrial Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Amcor Plc, Berry Global Inc., Winpak Ltd., Plastipak Holdings Inc., ALPLA Werke Alwin Lehner, Silgan Holdings Inc., Graham Packaging Co. LP, CKS Packaging Inc., Airlite Plastics Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LDPE Containers Market Shifts & Advancements
Active packaging functionality and circular material design are converging to redefine LDPE container value propositions. Manufacturers are racing to integrate sensory indicators and mono-material constructions ahead of tightening regulatory timelines.
Mono-material barrier films incorporating metallized polyethylene layers are collapsing the technical distinction between flexible pouches and rigid containers for shelf-stable foods. CPG brands in North American snack and condiment categories are accelerating specification shifts to qualify for store-dropoff recycling streams. This collapse is eroding the traditional volume premium historically commanded by multilayer laminate structures.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon blowing agents in foamed LDPE insulation applications. Processors are retrofitting extrusion lines to accommodate hydrocarbon and CO2-based alternatives with modified safety infrastructure. Personal care cold-chain shippers in Germany and France are absorbing capital costs to maintain temperature-controlled distribution compliance.
Direct-store-delivery networks are unbundling bulk container procurement from national distribution agreements. Regional dairy processors in the US Midwest are negotiating spot resin contracts with independent compounders rather than accepting formula pricing from integrated suppliers. This fragmentation is compressing contract duration and intensifying price transparency across spot polyethylene markets.
LDPE Containers Market Segmentation
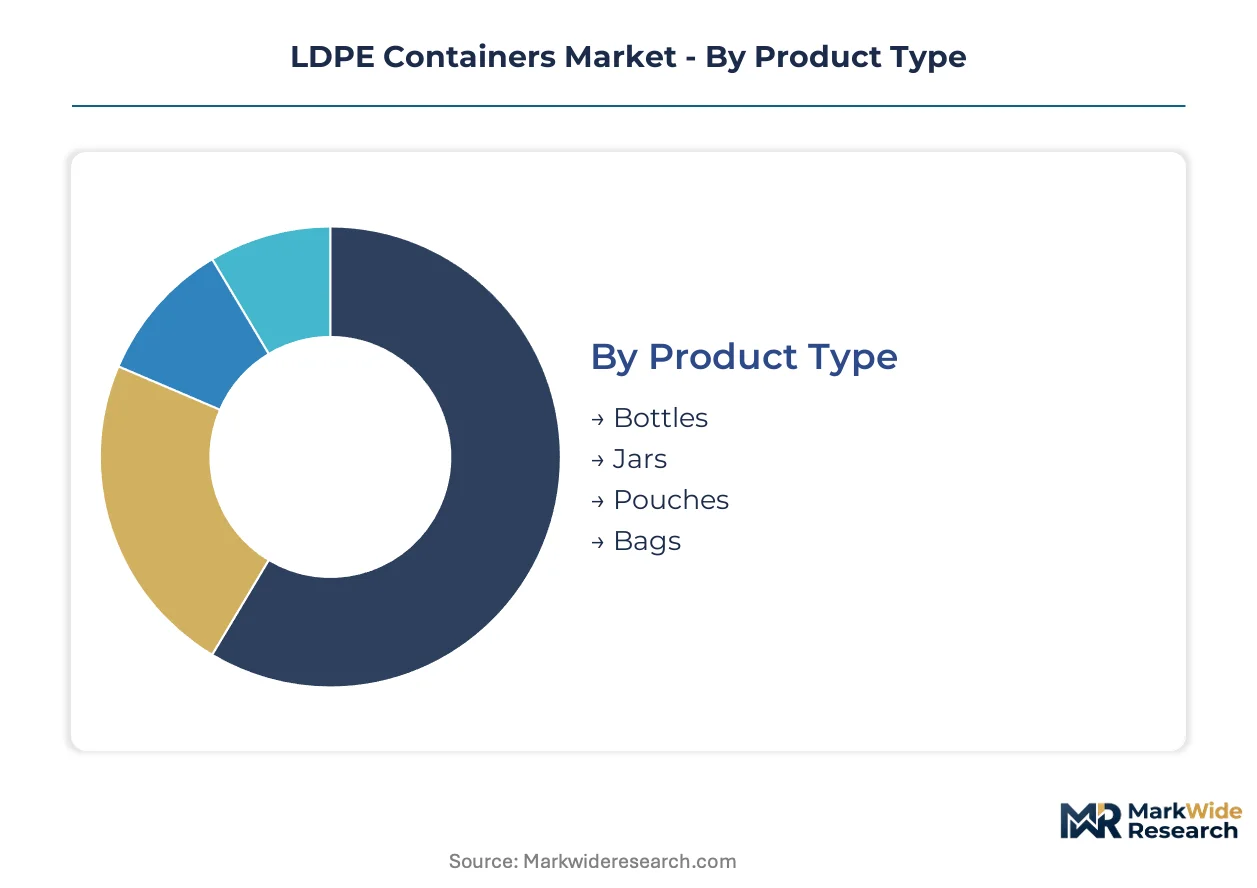
LDPE container specifications diverge sharply across end-use requirements, with food-contact migration limits, barrier performance, and dispensing mechanics driving formulation and design choices. Understanding segment boundaries clarifies where resin grades, conversion technologies, and compliance investments concentrate.
Product Type:
Mature formats dominate volume positions while emerging constructions reshape growth trajectories across the value chain.
- Bottles:Extrusion blow-molded vessels with neck finishes ranging from 20mm to 63mm dominate beverage and household chemical dispensing. Dairy processors in India and edible oil packers specify high-clarity LDPE grades with dart impact resistance above 80g for cold-chain distribution.
- Pouches:Flexible formats produced via blown film extrusion and form-fill-seal integration are displacing rigid alternatives in meal-kit delivery and personal care sampling. Silicon oxide barrier coatings extend oxygen transmission rates below 0.5 cc/m²/day, qualifying pouches for sauce and condiment applications previously reserved for glass.
- Jars:Wide-mouth containers with injection blow-molded threads serve scoopable personal care and food segments. Margins compress amid commoditization of standard 8-16oz formats.
- Bags:Gusseted and wicketed designs handle industrial bulk handling and retail produce merchandising. Standard constructions face substitution from reusable tote programs in European grocery channels.
Bottles handle the majority of throughput; pouches are the fastest mover on share.
Application:
Regulatory stringency and shelf-life requirements segment the market into distinct compliance tiers.
- Food Packaging:The largest application by resin volume, spanning dairy, edible oils, sauces, and prepared meals. FDA food-contact notifications and EU REACH additive restrictions govern plasticizer selection, with phthalate-free formulations becoming mandatory for European export qualification.
- Personal Care:Shampoo, lotion, and cosmetic containers demand squeezability and chemical resistance to surfactant formulations. EVOH coextrusion barriers protect fragrance integrity in premium segments.
- Household Products:Cleaners, detergents, and automotive chemicals utilize recycled-content LDPE where FDA migration limits do not apply. Industrial compounders source wide-spec regrind at 15-20% discounts to prime resin.
- Medical Supplies:Sterile packaging for diagnostic kits and specimen transport requires gamma-stabilized resins with low extractable profiles. CDSCO and FDA dual registrations extend qualification timelines.
Food packaging commands the resin volume base; personal care delivers the steepest expansion trajectory amid premiumization and barrier coating adoption.
End User:
Procurement scale and specification authority separate volume buyers from fragmented, price-sensitive accounts.
- Retail:Organized grocery chains and mass merchandisers drive private-label packaging standardization. Centralized procurement at chains like Reliance Retail and DMart specifies LDPE containers for store-brand edible oils across India.
- Food Service:Quick-service restaurants and meal-kit aggregators prioritize portion-control formats and tamper-evident closures. Flexible pouches with resealable zippers displace rigid clamshells in delivery-optimized menus.
- Healthcare:Hospital systems and diagnostic laboratories require lot-traceable packaging with validated sterilization compatibility. Contract manufacturers serving this segment maintain dedicated cleanroom conversion lines.
- Industrial:Chemical processors and agricultural distributors purchase bulk containers on spot resin pricing. This segment accepts wider dimensional tolerances in exchange for cost minimization.
Retail channels absorb the dominant share of unit volume; food service is climbing the fastest as delivery infrastructure scales.
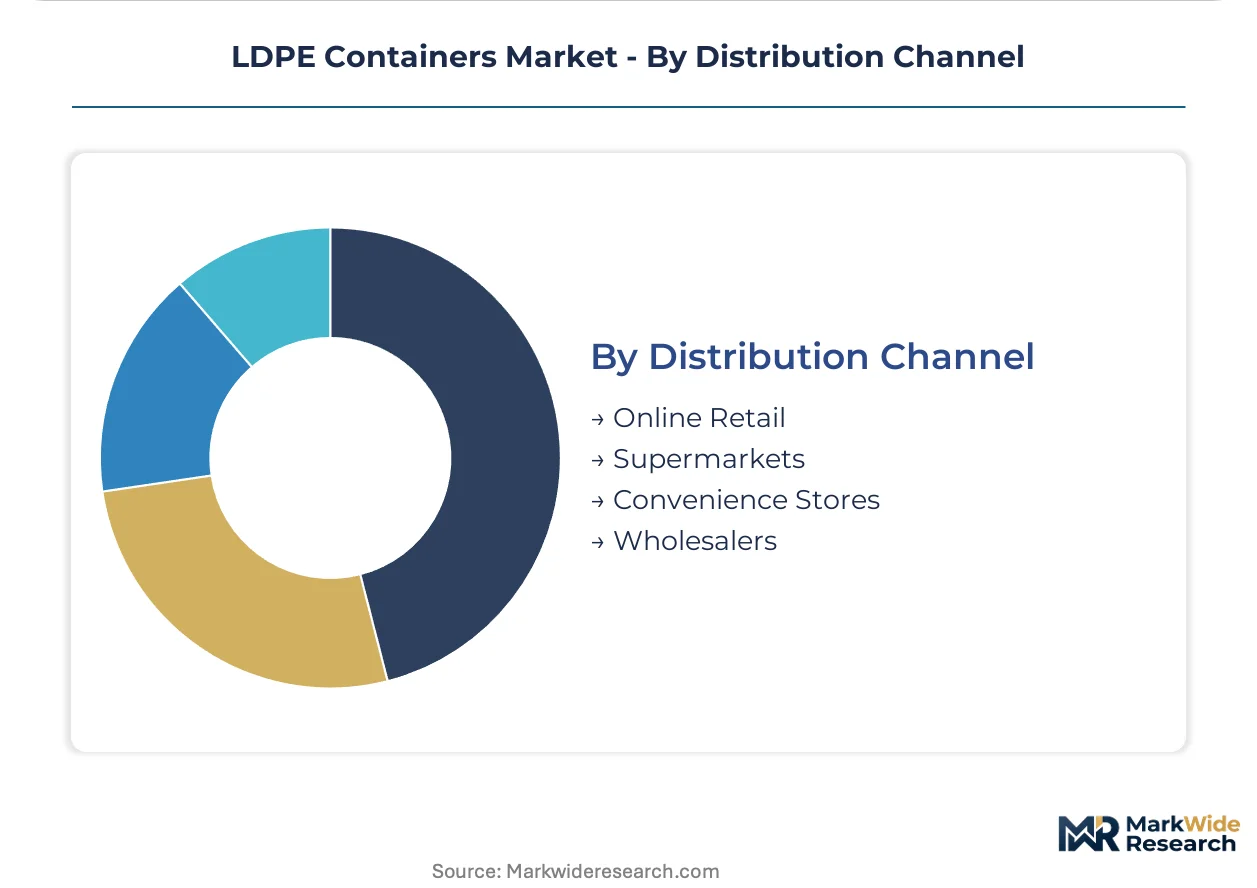
Distribution Channel:
Channel selection determines pack size, labeling requirements, and logistics compatibility.
- Supermarkets:Multi-unit packs and club-store formats require shelf-ready secondary packaging. Pallet pattern optimization drives container dimensional standardization.
- Online Retail:Direct-to-consumer shipments demand parcel-compatible flexible formats that minimize dimensional weight charges. Amazon Frustration-Free Packaging certification influences specification decisions.
- Convenience Stores:Single-serve and impulse formats prioritize shelf visibility and reclosure functionality. Higher per-unit packaging costs are offset by price premiums.
- Wholesalers:Cash-and-carry and distributor networks supply independent retailers and food service operators. Bulk case packs and generic labeling accommodate fragmented downstream demand.
Supermarkets and online retail together capture the bulk of volume flow; online channels are gaining share fastest as e-commerce penetration deepens in personal care and household categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service distributors and organized retail chains concentrate procurement authority across distinct national markets, with regulatory divergence shaping formulation strategies and barrier technology investments.
United States
Meal-kit delivery operators and quick-service restaurants drive flexible pouch specification for prepared food distribution. FDA food-contact substance notifications govern resin approvals, with phthalate-free formulations becoming baseline for export qualification. Blow-molding capacity clusters around Ohio and Indiana serve dairy processors and household chemical brands with high-clarity extrusion grades.
Germany
Personal care cold-chain shippers demand EVOH-barrier pouches for temperature-sensitive cosmetic distribution. EU F-Gas Regulation phase-down schedules restrict hydrofluorocarbon blowing agents, forcing extrusion line retrofits for CO2-based alternatives. The Rhine-Ruhr industrial corridor hosts barrier-coating specialists serving premium fragrance and skincare segments.
China
Provincial dual carbon emissions caps constrain petrochemical cluster expansion despite downstream packaging demand growth. SAMR enforces GB 4806.6 standards for food-contact plastics, creating 90-day evaluation windows that delay product launches versus FDA pathways. Yangtze River Delta converters supply edible oil packers with dart-impact-resistant bottles for cold-chain distribution.
India
Organized grocery chains Reliance Retail and DMart scale private-label packaging programs specifying LDPE containers for store-brand edible oils. FSSAI food-contact regulations align with CODEX migration limits for dairy and oil applications. Gujarat and Maharashtra house the dominant blow-molding capacity serving domestic retail and Middle East export markets.
Indonesia
Refrigerated logistics investment across archipelago distribution networks creates demand for insulated LDPE liner bags in fresh produce handling. The national pharmaceutical regulator enforces ASEAN harmonized standards for medical supply packaging. Java-based converters supply barrier-coated pouches to expanding quick-service restaurant chains in Jakarta and Surabaya.
LDPE Containers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement networks. The vendor base spans integrated resin-to-container conglomerates, independent blow-molders leasing asset-light equipment, and regional compounders supplying spot resin contracts. Three archetypes dominate: scale-driven multinationals with North American manufacturing footprints, European barrier-technology specialists, and Asia-Pacific converters serving price-sensitive bulk industrial accounts. Competitive intensity centers on M&A consolidation of independent molders and strategic partnerships between resin suppliers and food service distributors.
Among North American packaging conglomerates, Berry Global Inc. and Graham Packaging Co. LP exemplify scale-driven archetypes with extensive manufacturing footprints. ALPLA Werke Alwin Lehner occupies a position within the European specialist tier, representing barrier-coating expertise for sensitive personal care formulations. These three entities anchor competitive positioning across distinct geographic and technology vectors without dominating any single segment.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Winpak Ltd. |
| Plastipak Holdings Inc. |
| ALPLA Werke Alwin Lehner |
| Silgan Holdings Inc. |
| Graham Packaging Co. LP |
| CKS Packaging Inc. |
| Airlite Plastics Co. |
| Others |
Supply & Pricing Matrix
Overcapacity in Northeast Asian naphtha crackers is compressing resin contract premiums and forcing integrated producers toward spot market exposure. This utilization imbalance simultaneously erodes supplier pricing power and accelerates buyer migration toward short-duration procurement agreements.
Pricing Analysis
Cost-plus contracts indexed to ICIS Asia naphtha assessments dominate resin procurement between integrated producers and blow-molders. Three-tier pricing structure across premium, standard, and economy levels separates FDA food-contact certified grades from industrial wide-spec regrind and unclassified off-spec material. Pricing pressure stems from ethylene feedstock volatility transmitted through cracker margin swings. Industrial bulk buyers exhibit highest price sensitivity, while personal care brands prioritize barrier performance over resin cost differentials.
Supply Chain Analysis
Contract manufacturing concentration resides with Berry Global Inc., Graham Packaging Co. LP, and ALPLA Werke Alwin Lehner across North American and European production networks. Geographic supply concentration centers on China, India, and Germany as primary conversion hubs. Raw material dependencies encompass naphtha-derived ethylene, imported catalyst systems for metallocene grades, and silicon oxide barrier precursors. Single-source vulnerability concentrates in metallocene catalyst supply from specialized chemical producers. Distribution runs through food service distributor networks and organized retail procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LDPE container procurement is consolidating around platform-standardized specifications that enable supplier interoperability, mirroring the ecosystem shift seen in Amazon Frustration-Free Packaging certification programs.
For Market Incumbents: Pre-empt flexible pouch displacement of rigid bottle volumes by retrofitting extrusion lines for thin-gauge high-clarity grades. Secure backward integration into barrier-coating technology to defend margin position against mono-material film substitution. Prioritize phthalate-free formulation certification ahead of EU REACH enforcement timelines. For New Entrants and Emerging Players: Pursue Indonesia cold-chain liner bag demand as the most penetrable geography, where refrigerated logistics investment outpaces domestic converter capacity. Target spot resin contract relationships with independent compounders serving Midwest US dairy processors. Position around EVOH coextrusion capability as the critical go-to-market differentiator. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because asset-light leasing models have fragmented independent blow-molder networks into acquisition-ready targets. Focus on regional converters with established FSSAI or SAMR registrations that accelerate market access. Monitor GB 4806.6 testing timeline extensions as the signal for regulatory-driven competitive restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating Technology Acquisition | EVOH and silicon oxide capabilities protect fragrance integrity for premium personal care brands. |
| Phthalate-Free Formulation Transition | EU REACH compliance opens specification windows for bio-based LDPE alternatives. |
| India Manufacturing Footprint Expansion | Gujarat and Maharashtra capacity serves Reliance Retail and DMart private-label programs. |
| Mono-Material Film Line Retrofit | Store-dropoff recycling qualification addresses extended producer responsibility mandates. |
| Cold-Chain Logistics Partnership | Indonesian refrigerated distribution networks demand insulated LDPE liner bags for fresh produce. |
Research Methodology
A spread of perspectives from blow-molding plant managers, resin procurement leads at food service distributors, barrier-coating R&D directors, and retail category buyers converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, SEC 10-K filings, ACC industry reports, and SAMR regulatory bulletins. Bottom-up capacity utilization assessments triangulated against top-down resin demand forecasts.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions encompassed product type, application tier, end-user procurement scale, and regional regulatory cluster. CAGRs derived from weighted average of historical trajectory and forward-looking capacity expansion announcements. Industry-specific inputs included naphtha cracker operating rates and GB 4806.6 testing protocol timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, ethylene contract pricing, or Chinese provincial emissions enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding barrier technology adoption curves and recycling stream development. Quarterly review of resin spot market liquidity and regulatory testing backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Wire Containers Market
Containers
EPS Container Market
Containers
Screw Top Lids Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Thermoformed Containers Market
Containers
Club Store Packaging Tray Market
Containers
Asia and Africa Food Cans Market
Containers
Shipping Container Liners Market
Containers
Jug Shipper Market
Containers
Cylindrical Cans Market
Containers
Bulk Containers Market
Containers
Packaging Bins Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Algeria Container Glass Market
Containers
Container Fixed Fittings Market
Containers
Bulk Container Packaging Market