
 Laminated Packaging Films Market | 2026-2036
Laminated Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Packaging Films Market Analytics
Project finance tied to circular-economy targets is rewriting competitive entry conditions for laminated film producers. Amcor plc leverages its integrated recycling infrastructure to secure green-linked credit facilities. Mondi plc anchors its expansion through asset-light leasing models for coextrusion lines in emerging markets. Berry Global Group Inc. competes by sustaining high-volume polyethylene supply agreements that lock in resin cost predictability.
Laminated packaging films are multi-layer structures combining polyethylene, polypropylene, polyester, or paper substrates through adhesive lamination or extrusion coating, typically achieving oxygen transmission rates below 1 cc/m²/day to preserve shelf-sensitive contents. These constructions serve primarily to extend product freshness and provide barrier protection against moisture, light, and gases in packaged goods distribution. The food application segment leads in volume terms, though pharmaceuticals generates superior margin pools due to validation requirements and barrier precision. Thickness categories between 20-50 microns dominate flexible pouch formats, while above 100-micron constructions occupy industrial and bulk liquid packaging where puncture resistance commands premium positioning.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications shape laminate composition choices, with REACH compliance adding compliance cost layers for adhesive systems containing SVHC candidates. ECHA's evolving restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant barrier layers across European supply chains. Stakeholders must monitor regulatory divergence between EU extended producer responsibility frameworks and India's BIS standards for food-grade laminates, as compliance fragmentation will determine which material platforms achieve cross-border scale.
Market Dynamics
Multi-layer recyclability mandates under the EU Packaging and Packaging Waste Regulation are forcing converters to redesign adhesive chemistries and substrate combinations, compressing margins for legacy laminate architectures while rewarding mono-material-compatible platforms.
Growth Catalysts
- Extended Shelf-Life Demand:Ready-to-eat meal producers in India and Southeast Asia are specifying high-barrier laminates with oxygen transmission rates below 0.5 cc/m²/day to enable ambient distribution without cold chain dependency.
- REACH SVHC Restrictions:ECHA's evolving candidate list for substances of very high concern is accelerating migration away from solvent-based adhesives toward waterborne and UV-cured alternatives in European food-contact applications.
- Pharmaceutical Validation Requirements:Blister foil and sachet formats for moisture-sensitive APIs are demanding laminate constructions with aluminum oxide or silicon oxide vapor-deposited layers, creating premium specification tiers.
Market Restraints
- Resin Cost Volatility:Polyethylene and polypropylene feedstock prices track naphtha and natural gas liquids, exposing converters to margin compression when olefin spreads widen without pass-through mechanisms.
- Recycling Infrastructure Gaps:Mechanical separation of multi-layer films remains uneconomical in most Indian municipalities, limiting circular-economy claims and extended producer responsibility compliance.
- Substitution by Rigid Formats:Glass and aluminum cans are reclaiming share in premium beverage segments where perceived recyclability outweighs flexible packaging convenience.
Strategic Opportunities
- Mono-Material Platform Adoption:Full-polyethylene or full-polypropylene laminates compatible with existing store-dropoff recycling streams are capturing specification wins from brand owners with 2025-2030 sustainability commitments.
- Active Packaging Integration:Oxygen scavenger and moisture absorber films embedded within laminate layers are extending viable shelf life for retort pouches in ambient distribution channels.
- India PLI Scheme Alignment:Domestic converters qualifying under the Production Linked Incentive scheme for specialty chemicals and advanced materials are accessing capital subsidies for coextrusion line upgrades.
Industry Challenges
- Adhesive Reformulation Timeline:Replacing legacy polyurethane laminating adhesives with FDA-compliant, PFAS-free alternatives requires 18-24 month validation cycles that delay new product qualification.
- Barrier-Performance Trade-offs:Thinner gauge mono-material constructions struggle to match metalized or aluminum-foil laminate barrier performance, forcing compromises between recyclability claims and shelf-life guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Packaging Films Market |
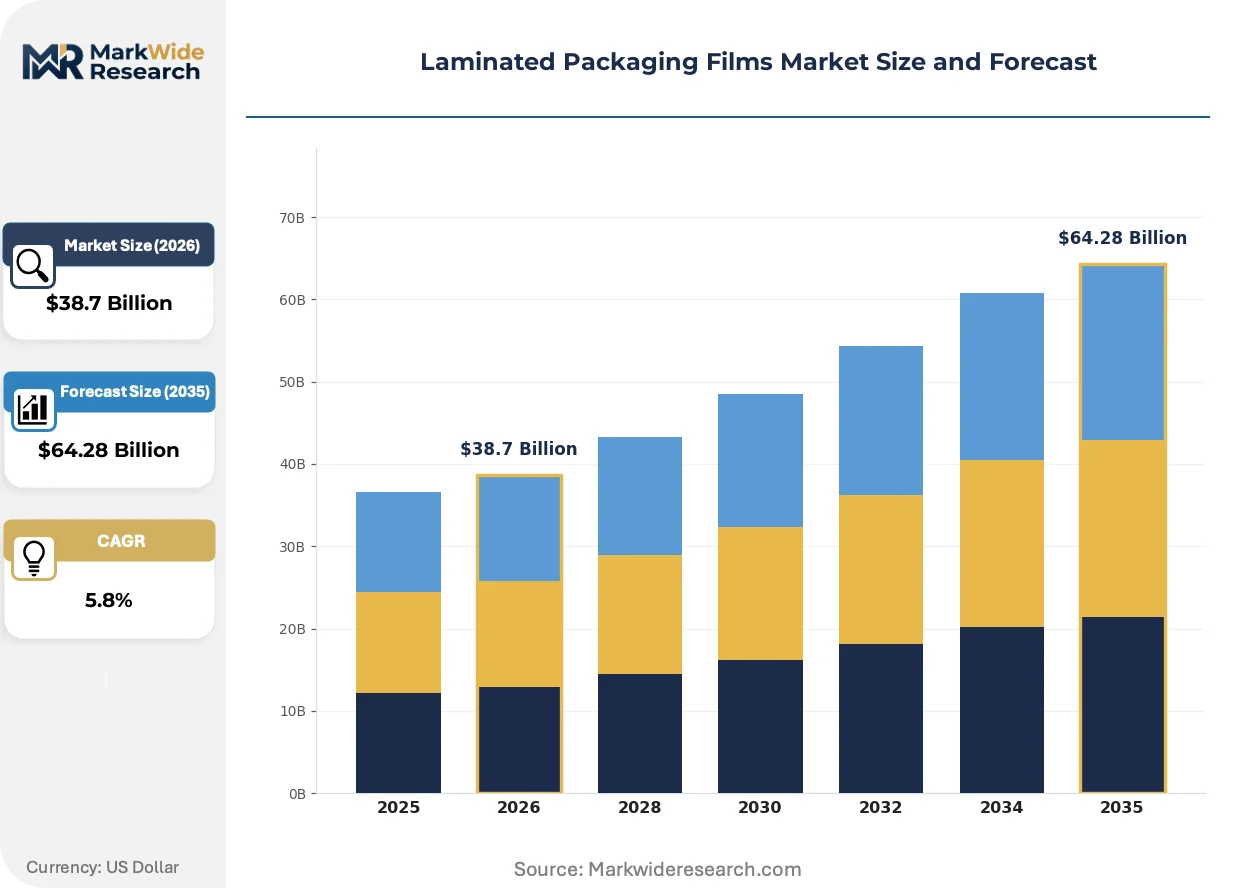
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polypropylene, Polyester, Paper Application: Food, Pharmaceuticals, Personal Care, Electronics End User: Retail, Wholesale, E-commerce, Manufacturing Thickness: Below 20 Microns, 20-50 Microns, 50-100 Microns, Above 100 Microns |
| Companies Covered | Amcor plc, Berry Global Group Inc., Mondi plc, Constantia Flexibles GmbH, Cosmo Films, UFLEX Limited, Taghleef Industries LLC, ProAmpac LLC, Coveris Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Packaging Films Market Evolving Landscape
Digital printing integration and solventless adhesive systems are converging to enable shorter production runs with reduced environmental compliance burden, reshaping converter capital allocation and customer minimum order quantities.
Water-based barrier coatings incorporating nanocellulose or clay platelets are rendering obsolete conventional polyethylene extrusion coating for medium-barrier applications in snack and bakery packaging. European brand owners with 2025 recyclability targets are specifying these platforms for pilot production. The shift is compressing demand for conventional extrusion coating lines and redirecting capital toward aqueous coating and drying infrastructure.
ECHA's restriction proposal for per- and polyfluoroalkyl substances in food-contact materials is compelling laminate producers to eliminate grease-resistant fluoropolymer treatments from paper-based structures. The regulation is accelerating qualification of silicone and bio-wax alternative barriers. Breakfast cereal and confectionery segments in Germany, France, and the Netherlands are experiencing the most intensive supplier auditing and material requalification activity.
Brand-owner sustainability scorecards are embedding recycled content thresholds and end-of-life recyclability assessments as mandatory supplier selection criteria. Major food and personal care manufacturers are consolidating vendor panels to favor converters with third-party certified recycling partnerships and mass-balance accounting systems. This behavioral shift is most pronounced in procurement decisions by multinational packaged goods companies with European headquarters and North American manufacturing footprints.
Laminated Packaging Films Market Segmentation
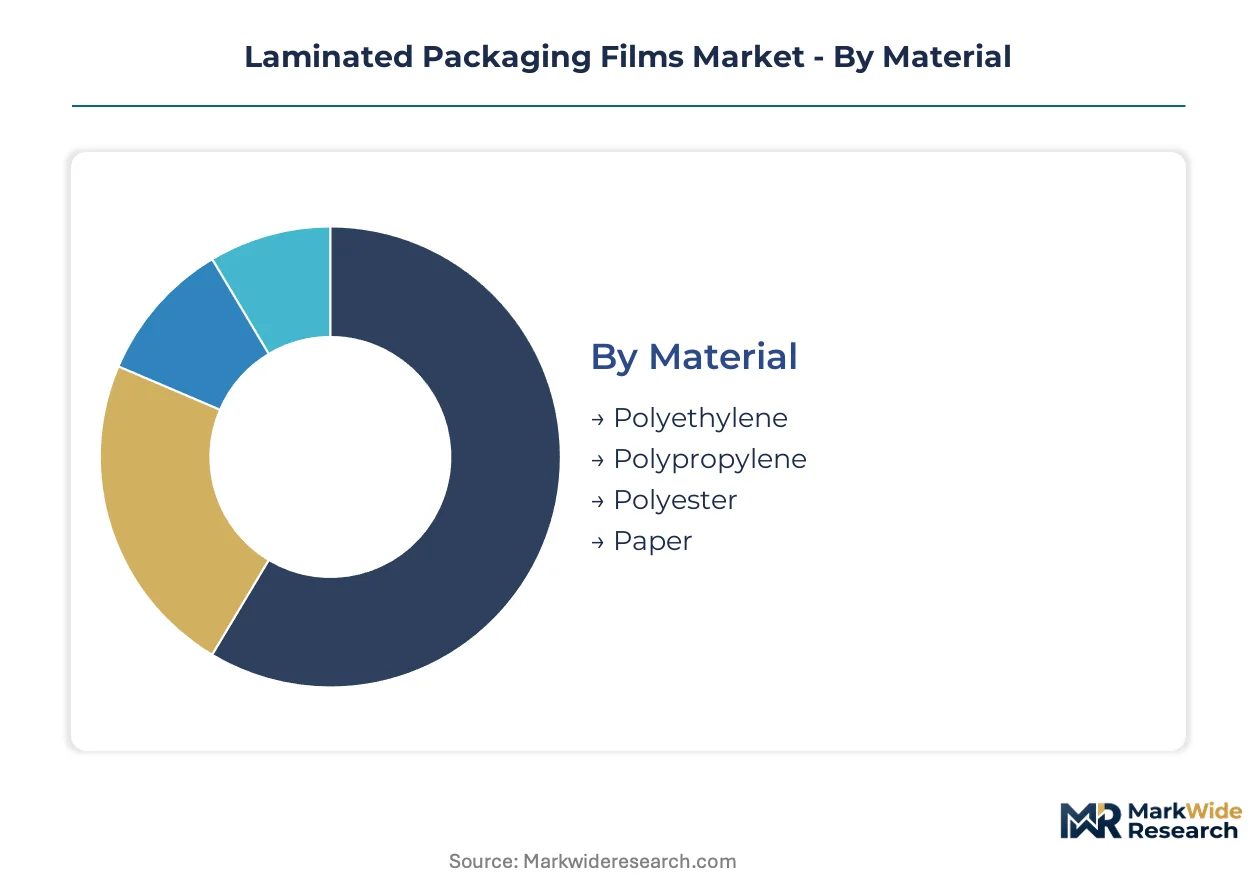
Segmentation in laminated packaging films reveals how material choices, barrier specifications, and distribution channels align with diverging end-use requirements. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning across converter tiers.
Material:
Cost tier differentiation in substrate selection determines barrier performance, recyclability compliance, and resin cost volatility exposure.
- Polyethylene:Dominates flexible pouch constructions through low-density and linear low-density variants, with full-PE mono-material laminates capturing specification wins from brand owners with store-dropoff recycling commitments. Indian converters under the PLI scheme are scaling coextrusion capacity for PE-dominant structures serving processed food exports.
- Polypropylene:Biaxially oriented PP delivers superior clarity and moisture barrier for snack and confectionery applications, though its higher melting point complicates heat-seal layer compatibility in multi-layer stacks. European demand concentrates in retort pouch formats where PP-based structures replace metalized alternatives.
- Polyester:PET substrates provide dimensional stability and printability for high-graphics flexible packaging, with silicon oxide vapor-deposited variants addressing pharmaceutical blister foil requirements.
- Paper:Fiber-based structures with extruded or aqueous barrier coatings serve breakfast cereal and bakery segments, though ECHA PFAS restrictions are forcing rapid reformulation of grease-resistant treatments.
Polyethylene commands the established base. The steepest expansion runs through paper-based barrier platforms.
Application:
Application scope determines validation intensity, barrier precision requirements, and margin capture potential across converter tiers.
- Food:Ready-to-eat and shelf-stable categories drive volume, with oxygen transmission specifications below 0.5 cc/m²/day enabling ambient distribution without cold chain dependency in India and Southeast Asia.
- Pharmaceuticals:Blister foil and sachet formats for moisture-sensitive APIs demand aluminum oxide or silicon oxide vapor-deposited layers, creating premium specification tiers with extended validation cycles and superior margin pools.
- Personal Care:Sachet and stick-pack formats for single-use cosmetics and hygiene products emphasize puncture resistance and printability over extreme barrier performance.
- Electronics:Anti-static and moisture-barrier laminates protect semiconductors and components during shipping, with ESD-grade specifications requiring conductive layer integration.
Food applications anchor volume throughput. Pharmaceuticals deliver the highest margin expansion trajectory.
End User:
Customer type shapes order scale, customization requirements, and inventory velocity through the converter base.
- Retail:Supermarket and hypermarket private-label programs demand high-volume consistency with short lead times, favoring converters with integrated printing and slitting operations.
- Wholesale:Bulk distribution channels for institutional foodservice prioritize cost-optimized specifications with standardized dimensions over premium graphics or barrier tiers.
- E-commerce:Direct-to-consumer fulfillment requires puncture-resistant constructions and right-sized formats to minimize dimensional weight shipping penalties.
- Manufacturing:Industrial captive converters for food and pharmaceutical producers maintain in-house lamination capacity to protect formulation confidentiality and accelerate packaging change cycles.
Retail channels concentrate procurement scale. E-commerce specifications are climbing the fastest.
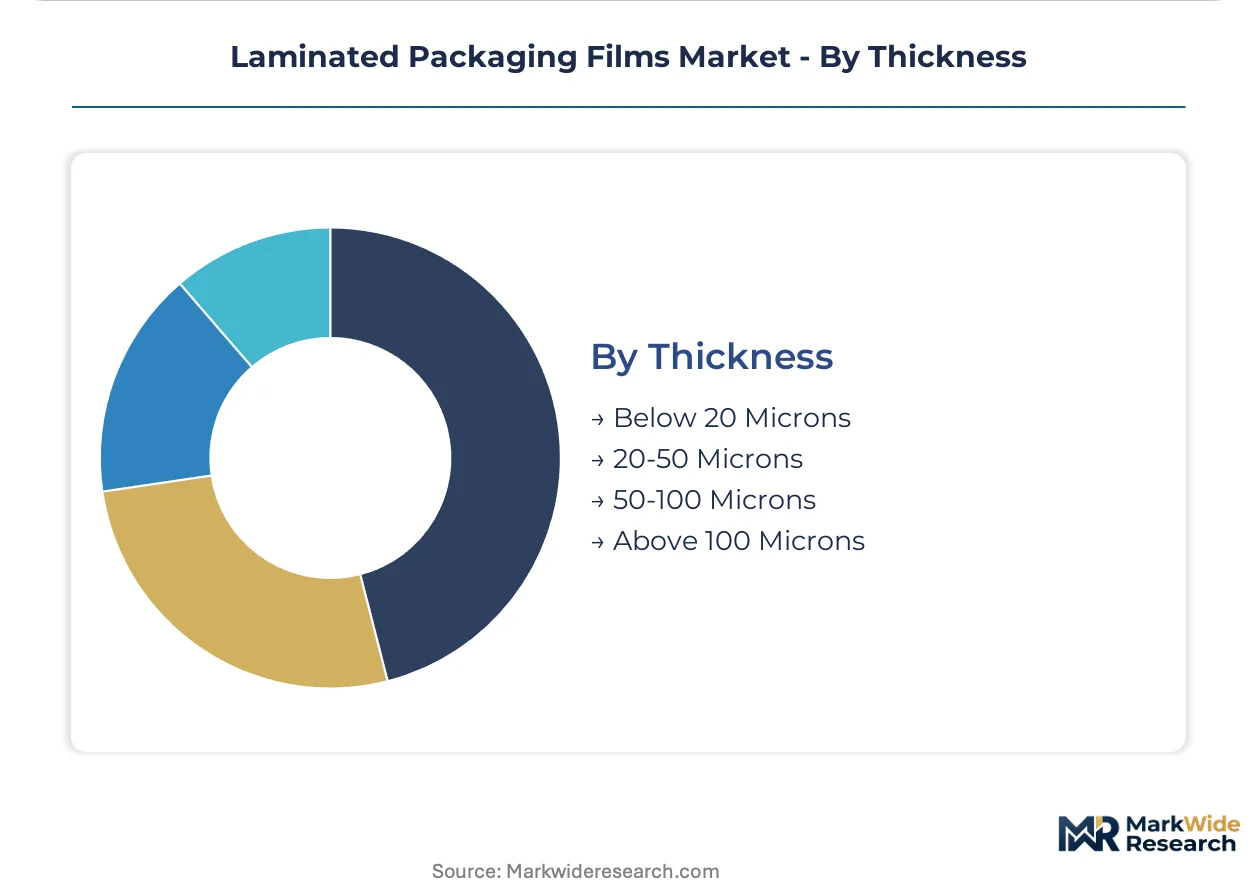
Thickness:
Gauge selection trades material cost, barrier performance, and mechanical durability against sustainability positioning and regulatory scrutiny.
- Below 20 Microns:Ultra-thin constructions for single-serve sachets and portion packs reduce material intensity but sacrifice puncture resistance, limiting application to dry, non-abrasive contents.
- 20-50 Microns:Flexible pouch formats for snacks, confectionery, and personal care sachets balance barrier adequacy with cost efficiency, representing the dominant specification band for digital printing integration.
- 50-100 Microns:Mid-gauge structures serve retort pouches and bulk liquid packaging where seal integrity and drop resistance outweigh lightweighting priorities.
- Above 100 Microns:Heavy-duty laminates for industrial chemicals, agricultural inputs, and bulk pharmaceuticals command premium positioning through multi-ply reinforcement and specialized barrier layers.
The 20-50 micron band holds the volume center. Above 100 micron applications are expanding most quickly in industrial and pharmaceutical bulk formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping laminated packaging film trade flows, with India emerging as a net exporter of processed food-grade laminates while European converters face rising compliance costs that compress re-export competitiveness.
United States
Retort pouch demand from ready-to-eat meal producers in the Southeast and Midwest is accelerating specification upgrades for high-barrier constructions. FDA food-contact substance notifications govern adhesive selection, pushing converters toward waterborne systems. The Chicago-Milwaukee corridor hosts concentrated coextrusion capacity serving private-label retail programs.
Germany
Breakfast cereal and confectionery brand owners are auditing suppliers for PFAS-free barrier coatings under ECHA restriction proposals. REACH SVHC compliance adds validation layers for solvent-based adhesive replacements. The Düsseldorf-Cologne industrial cluster anchors European laminate innovation, with pilot lines testing nanocellulose aqueous coatings.
India
Processed food exports to the Middle East and Africa are driving capacity expansion for shelf-stable laminate specifications. The PLI scheme for specialty chemicals subsidizes coextrusion line upgrades for domestic converters. UFLEX Limited and regional competitors are scaling operations in Gujarat and Maharashtra to serve pharmaceutical and food-grade demand.
China
Domestic consumption of flexible pouches for snack and personal care applications sustains massive substrate demand, though environmental inspections tighten adhesive emission standards. GB standards for food-grade laminates are converging with stricter migration limits. The Yangtze River Delta concentration of converters is pivoting toward mono-material platforms for export compliance.
Japan
Pharmaceutical blister foil and sachet formats for moisture-sensitive APIs command premium positioning with silicon oxide vapor-deposited layers. METI circular economy guidelines pressure redesign of multi-layer structures for chemical recycling compatibility. The Kansai region around Osaka maintains specialized capacity for validation-intensive medical packaging.
Laminated Packaging Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and adhesive supply. The market exhibits moderate consolidation, with global converters holding scale advantages in resin procurement and recycling infrastructure while regional players compete on customization velocity and local regulatory fluency. Two archetypes dominate: vertically integrated multinationals with captive recycling networks, and asset-light specialists leveraging leased equipment for emerging market penetration. Competitive moves center on green-linked financing access and mono-material platform qualification cycles.
Among integrated packaging conglomerates, Amcor plc, Berry Global Group Inc., and Mondi plc exemplify divergent capital deployment models. Amcor anchors the recycling-integrated archetype, Berry occupies the resin-cost-hedging position, and Mondi represents the asset-light emerging market expansion pattern. These three demonstrate how scale, supply chain configuration, and financing structure separate competitive outcomes in a compliance-intensive segment.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group Inc. |
| Mondi plc |
| Constantia Flexibles GmbH |
| Cosmo Films |
| UFLEX Limited |
| Taghleef Industries LLC |
| ProAmpac LLC |
| Coveris Group |
| Others |
Value Network & Pricing Analysis
Resin cost volatility tethered to naphtha and natural gas liquid spreads determines both pricing tier compression and supply chain regionalization across converter networks. This volatility forces tiered pricing stratification between PE-dominant mono-material platforms and legacy multi-layer constructions while accelerating geographic supply shifts toward India and Southeast Asia.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure with volume-scale and certification-grade differentiation separating premium pharmaceutical-grade laminates from economy food-contact specifications. Pricing pressure stems from olefin spread widening without pass-through mechanisms, compressing margins for mid-tier converters. Brand owners with sustainability scorecards demonstrate lowest price sensitivity, while wholesale institutional foodservice channels exhibit highest elasticity to resin cost fluctuations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from resin majors are restructuring working capital dynamics for mid-cap converters. Raw material supply concentrates in China, South Korea, and Saudi Arabia for polyethylene and polypropylene feedstocks, while adhesive chemistries draw from German and Japanese specialty chemical producers. Single-source vulnerability runs through vapor-deposited barrier equipment suppliers in Japan and Germany. Distribution runs through converter-direct relationships with multinational FMCG procurement hubs and regional distributor networks serving fragmented food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation's multi-layer recyclability mandates constitute a technological inflection that will displace legacy laminate architectures within a single replacement cycle.
For Market Incumbents: Harden barrier-performance validation capabilities for mono-material platforms to defend against substitution by rigid formats in premium beverage segments. Pursue backward integration into aqueous coating and nanocellulose barrier technology to secure green-linked financing access and preempt adhesive reformulation bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical-grade laminate exports to Middle East and African markets where PLI scheme subsidies offset capital intensity. Target active packaging integration for oxygen scavenger and moisture absorber films as a specification-led entry vector with shorter qualification cycles than barrier-layer redesign. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light specialists with leased coextrusion capacity and regional regulatory fluency. Five-to-ten year viability hinges on mono-material platform qualification velocity rather than scale. Monitor ECHA PFAS restriction implementation timelines as the critical signal for adhesive chemistry winners and losers.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Qualification | Secures brand owner specification wins under EU extended producer responsibility frameworks. |
| Active Packaging Integration | Extends shelf-life guarantees for retort pouches in ambient distribution channels. |
| Backward Integration into Barrier Coatings | Captures margin from nanocellulose and clay platelet aqueous systems displacing extrusion coating. |
| PLI Scheme Alignment | Unlocks Indian government capital subsidies for coextrusion line upgrades serving export markets. |
| Green-Linked Financing Access | Lowers cost of capital for converters with third-party certified recycling partnerships. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations directors, brand owner packaging procurement managers, adhesive R&D leads, and regulatory affairs specialists at laminate producers, then refined against secondary validation from FDA food-contact substance notifications, ECHA restriction proposal documentation, EU Packaging and Packaging Waste Regulation impact assessments, and Indian PLI scheme administrative guidelines. Bottom-up capacity and demand modeling was triangulated with top-down trade flow analysis across the analysis window.
Demand-supply balance dynamics anchored the forecast framework across material, application, end user, and thickness segmentation dimensions, with particular weighting toward mono-material platform adoption curves and pharmaceutical validation cycle durations. CAGRs were derived from recursive substitution modeling of legacy multi-layer structures by recyclable-compatible alternatives, incorporating resin cost volatility scenarios and regulatory compliance cost layering.
Stress conditions across olefin spread ranges, ECHA PFAS restriction implementation timelines, and Indian PLI scheme subsidy continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticity and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
China Plastic Packaging Film Market
Poly film
EVOH Encapsulation Film Market
Poly film
Soft Touch Lamination Film Market
Poly film
Poly Coated Paper Market
Poly film
Automotive Wrap Films Market
Poly film
Blown Film Extruder Market
Poly film
Thermoforming Films Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Multi-Layer Blown Films Market
Poly film
Recyclable Lidding Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
China BOPP Film Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Bopet Films Market
Poly film
Global Thermoplastic Films Market