
 Polyurethane (PU) Film Market | 2026-2036
Polyurethane (PU) Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane (PU) Film Market Analytics
Multi-source procurement for aliphatic polyester raw materials is hardening across the PU film value chain. Covestro AG leverages captive isocyanate production to sustain margin control in specialty grades. BASF SE anchors European supply through backward integration into polyol manufacturing. DingZing Advanced Materials Inc. competes on thermoplastic polyurethane film thickness precision for medical and industrial tapes.
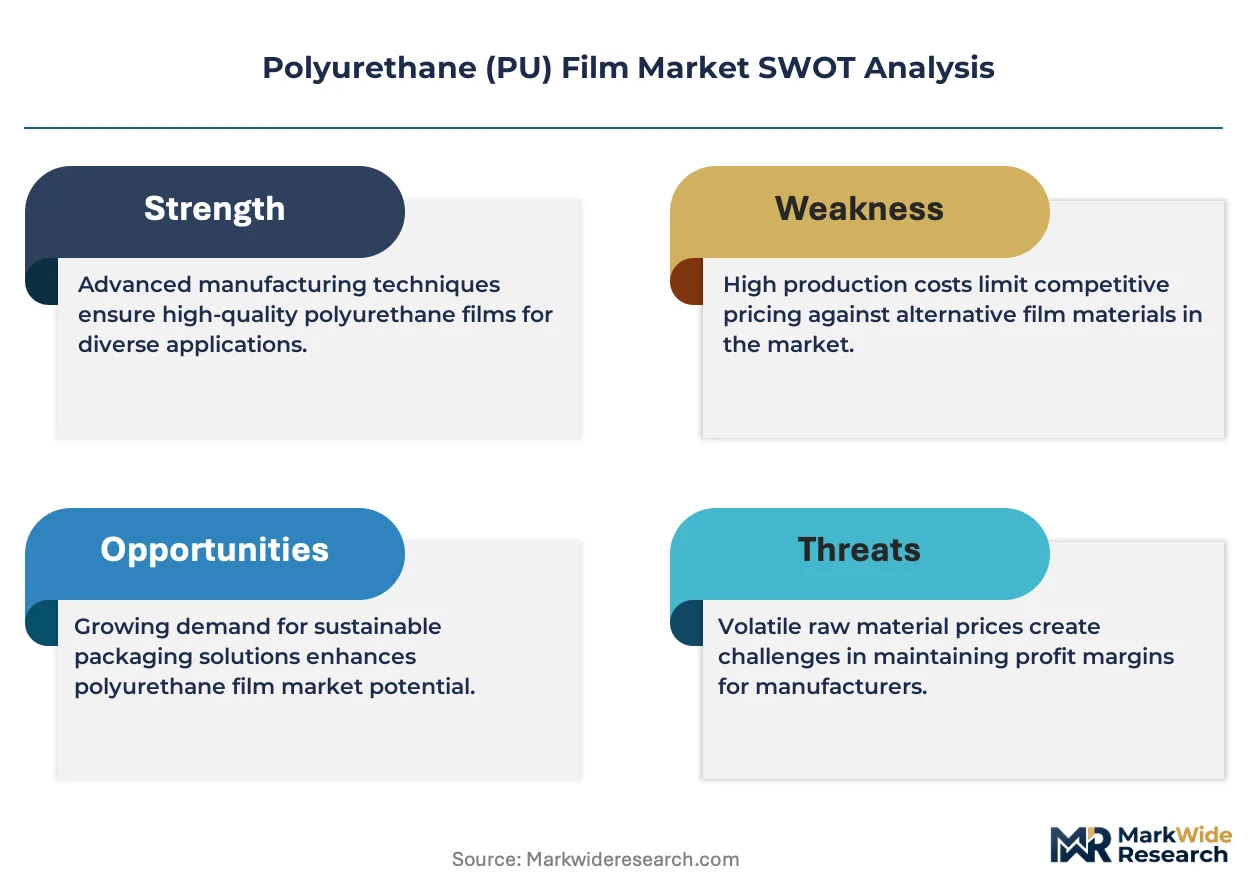
Polyurethane film comprises a thermoplastic or thermoset polymer layer formed from diisocyanate and polyol reactions, typically ranging from 0.01 to 3.0 mm in thickness with Shore A hardness between 80 and 95. These films provide abrasion resistance, elasticity, and moisture vapor transmission for bonding, protection, and surface engineering across automotive, healthcare, and consumer goods sectors. Specialty Films command premium positioning due to custom-formulated optical and barrier properties for display and electronics applications. Biodegradable Films represent the fastest-expanding product category as brand owners phase out conventional films under extended producer responsibility frameworks. Coextrusion technology dominates volume output where multi-layer barrier structures serve food and medical packaging requirements.
REACH registration obligations through ECHA govern diisocyanate monomer handling across European manufacturing facilities, while FDA biocompatibility standards under ISO 10993 shape qualification pathways for medical-grade film entrants into US device supply chains. China's GB standards for plastic film migration limits constrain export-bound production from domestic extrusion lines. Stakeholders must monitor regulatory divergence between EU F-Gas phase-down timelines and emerging state-level chemical disclosure rules in the United States to align capacity investments with compliant formulation portfolios.
Market Dynamics
REACH diisocyanate restrictions and EU Green Deal mandates are forcing polyurethane film producers to reformulate entire product portfolios while medical device OEMs simultaneously scale breathable film procurement for advanced wound care platforms.
Growth Catalysts
- REACH Phase-Down Deadlines:ECHA diisocyanate authorization requirements are accelerating R&D investment in aliphatic polyester alternatives across European extrusion facilities.
- Medical Device Qualification:FDA ISO 10993 biocompatibility pathways are opening US device supply chains to specialty film entrants with validated vapor transmission rates.
- Automotive Interior Specifications:German OEMs are consolidating procurement of haptic surface films from integrated chemical suppliers with captive polyol production.
Market Restraints
- MDI Feedstock Concentration:Asian aromatic isocyanate suppliers control 70% of global merchant supply, exposing European compounders to freight and duty volatility.
- Biodegradable Performance Gap:Current compostable formulations sacrifice 40-60% of tensile strength versus conventional grades, limiting adoption in load-bearing medical tapes.
- F-Gas Processing Constraints:EU F-Gas Regulation phase-down timelines are restricting access to HFC blowing agents used in cellular film structures.
Strategic Opportunities
- Extended Producer Responsibility:EU packaging waste directives are creating first-mover advantage for film producers with certified biodegradable portfolios and closed-loop collection partnerships.
- Coextrusion Technology Convergence:Multi-layer barrier structures combining TPU with EVOH or PA layers are penetrating modified atmosphere food packaging previously served by conventional laminates.
- India Medical Device Localization:CDSCO production-linked incentive schemes are attracting film extruders to establish sterile-grade capacity for domestic wound care manufacturing.
Industry Challenges
- ISO 10993-5 Cytotoxicity Testing Bottlenecks:Medical-grade qualification requires 18-24 month validation cycles that strain working capital for mid-cap film specialists.
- Legacy Extrusion Asset Retrofit Costs:Biodegradable formulations demand modified screw geometries and cooling profiles that incompatible cast lines cannot accommodate without six-figure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane (PU) Film Market |
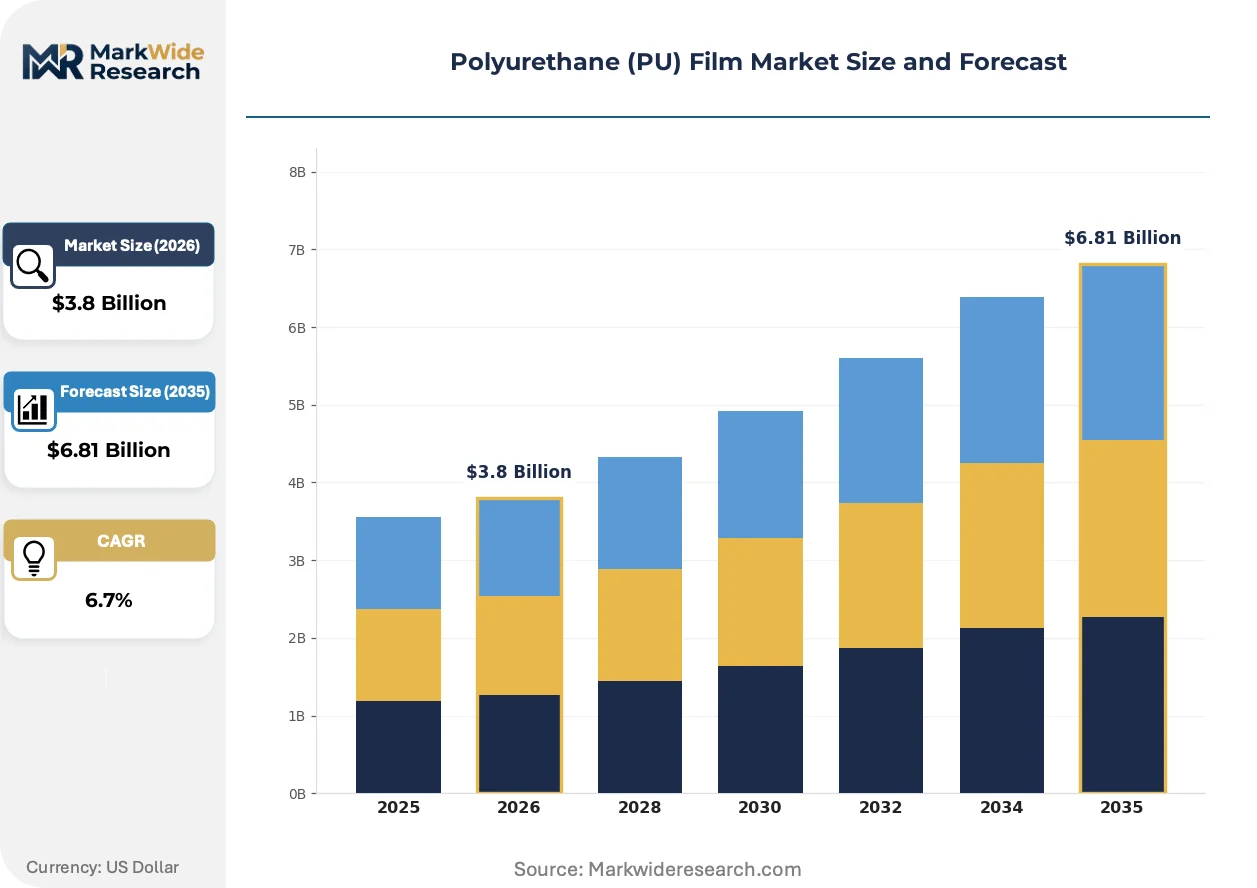
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Films, Medium-Duty Films, High-Duty Films, Specialty Films Application: Automotive Interiors, Protective Covers, Textiles, Packaging Solutions End User: Manufacturers, Retailers, Distributors, Exporters Technology: Coextrusion, Injection Molding, Lamination, Extrusion |
| Companies Covered | 3M, Huntsman International LLC, BASF SE, Permali Gloucester Limited, American Polyfilm Inc., Covestro AG, Avery Dennison Corporation, DingZing Advanced Materials Inc., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane (PU) Film Market Evolving Landscape
Waterborne PU dispersion technology is displacing solvent-based coating systems while regulatory pressure on perfluorinated compounds accelerates fluorine-free barrier film development across food and medical packaging segments.
Aliphatic waterborne polyurethane dispersions are expanding into automotive interior surface films where low-VOC emissions and soft-touch haptics converge. Tier 1 seating suppliers in Germany and the Czech Republic are qualifying these systems for dashboard and door panel applications previously dominated by PVC skins. The technology is expanding into premium electric vehicle platforms where cabin air quality certification has become a competitive specification.
EU F-Gas Regulation phase-down mandates are compressing availability of HFC-134a and HFC-152a blowing agents for cellular TPU production. Extruders serving medical packaging and protective sports equipment segments are reformulating with hydrocarbon or CO2 physical blowing systems. German chemical regulators are prioritizing inspection of facilities still dependent on high-GWP process agents.
Hospital procurement consortia are consolidating film sourcing through outcome-based supplier partnerships that bundle material supply with sterilization validation and inventory management. Medical device OEMs in the US Northeast and German hospital networks are displacing transactional spot purchasing with multi-year sole-source agreements. This restructuring concentrates volume with film producers capable of integrated regulatory documentation and lot-level traceability systems.
Polyurethane (PU) Film Market Segmentation
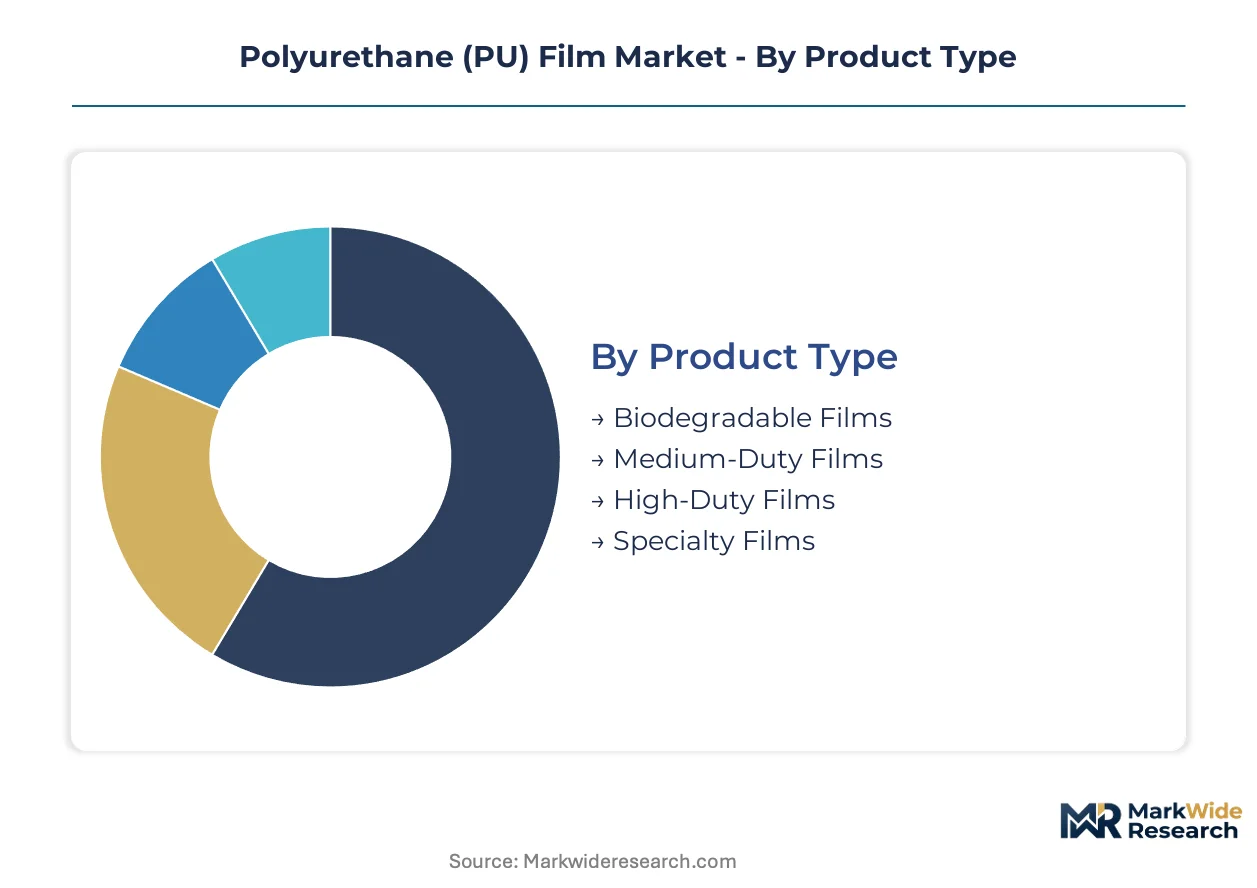
Polyurethane film producers navigate a fragmented demand landscape where medical device OEMs require validated biocompatibility documentation while automotive buyers prioritize haptic consistency across million-unit programs. Segmentation discipline separates commodity extruders from specialists commanding formulation premiums.
Product Type:
Customization intensity varies sharply across this spectrum, from catalog-grade medium-duty films to engineered specialty grades requiring joint development agreements with end-users.
- Specialty Films:These incorporate optical-grade clarity, selective vapor transmission, or electrostatic dissipation through custom diisocyanate-polyol ratios. German automotive OEMs and US medical device manufacturers dominate procurement, with qualification cycles extending 18-24 months for new formulations.
- Biodegradable Films:Aliphatic polyester formulations degrade under industrial composting conditions while maintaining 60-70% of conventional tensile strength. EU packaging waste directives and extended producer responsibility frameworks in Germany and France are accelerating procurement shifts.
- High-Duty Films:Shore A hardness above 90 and abrasion resistance exceeding 100,000 cycles serve industrial belting and protective sports equipment.
- Medium-Duty Films:Standard extrusion grades balance cost and performance for consumer goods protection and general industrial masking.
Most installed capacity flows through Specialty Films. Expansion is steepest in Biodegradable Films.
Application:
Performance requirements diverge by end-use environment, from sterilization-grade moisture vapor transmission in healthcare to UV-stable haptic surfaces in automotive cabins.
- Automotive Interiors:Dashboard skins, door panels, and seating surfaces demand low-VOC aliphatic formulations with soft-touch Shore A 85-95 hardness. German OEMs consolidate procurement with integrated chemical suppliers possessing captive polyol production.
- Packaging Solutions:Modified atmosphere structures combine TPU barrier layers with EVOH or PA in coextruded formats for protein and medical device packaging. REACH compliance and FDA ISO 10993 pathways shape regional qualification requirements.
- Textiles:Laminated waterproof-breathable membranes serve outdoor apparel and protective workwear segments.
- Protective Covers:Temporary surface protection films for electronics and appliance manufacturing prioritize clean peel adhesion.
Volume concentrates in Automotive Interiors. Fastest share gains occur in Packaging Solutions.
End User:
Procurement sophistication separates transaction-oriented buyers from partners requiring integrated regulatory documentation and lot-level traceability systems.
- Manufacturers:Medical device OEMs and automotive Tier 1 suppliers drive specification development through multi-year sole-source agreements. Hospital procurement consortia in Germany and the US Northeast are consolidating film sourcing through outcome-based partnerships bundling material supply with sterilization validation.
- Distributors:Technical distributors serve mid-cap industrial converters requiring rapid turnaround on slit-roll formats and custom adhesive lamination.
- Retailers:Private-label packaging film procurement is consolidating under sustainability scorecard requirements.
- Exporters:China-based extruders serving EU and US markets navigate GB standards migration limits and REACH registration obligations.
Contract value concentrates with Manufacturers. Fastest relationship restructuring occurs among Distributors.
Technology:
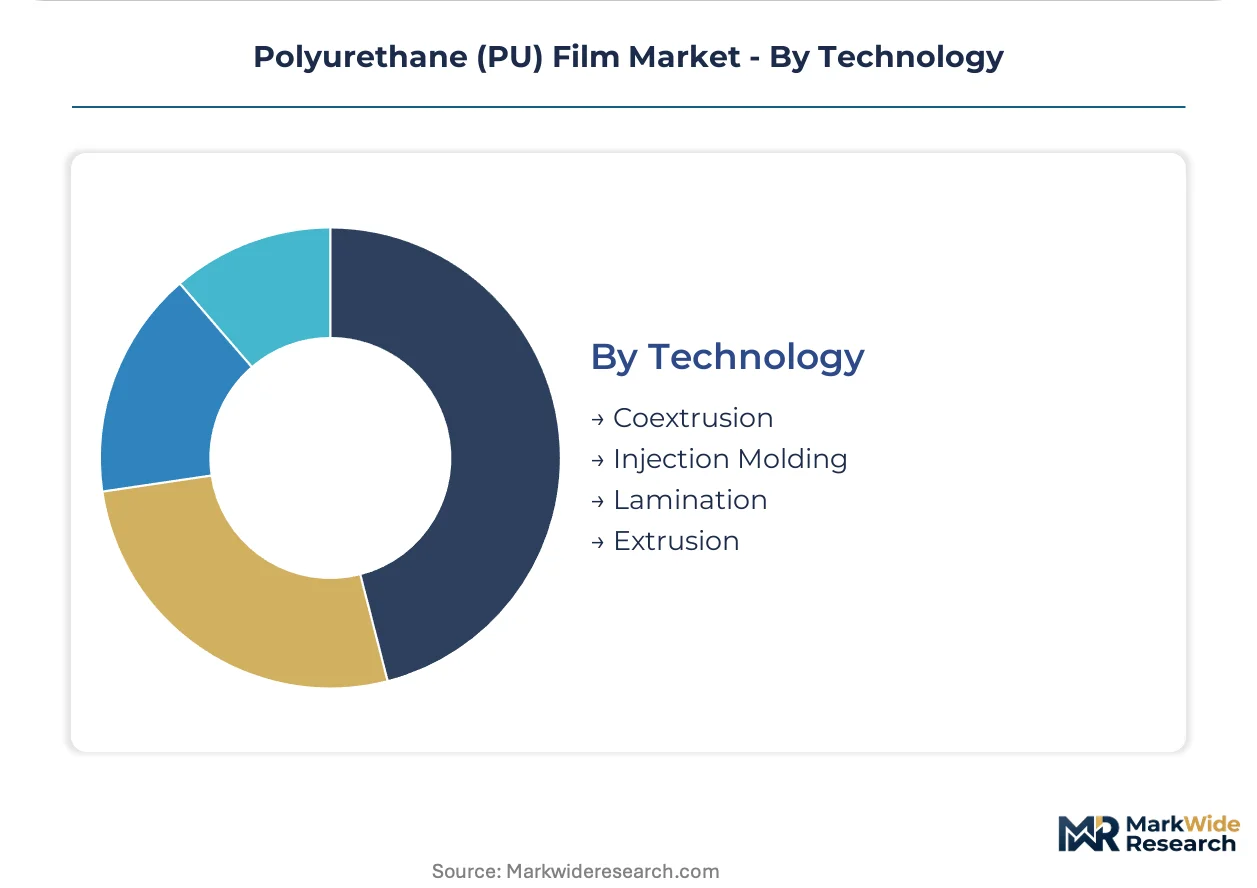
Capital intensity and formulation flexibility separate continuous extrusion operations from batch-oriented molding processes.
- Coextrusion:Multi-layer barrier structures dominate food and medical packaging volume, combining TPU with tie layers and high-barrier polymers in single-pass operations. EU F-Gas Regulation phase-down timelines are forcing reformulation of cellular structures away from HFC blowing agents.
- Extrusion:Cast and blown film lines produce monolayer grades for textile lamination and industrial protection. Legacy asset retrofit costs for biodegradable formulations exceed six figures for cooling profile modifications.
- Lamination:Adhesive and thermal bonding processes combine TPU films with woven or nonwoven substrates.
- Injection Molding:Limited to thick-section parts and overmolding applications outside mainstream film markets.
Output volume flows predominantly through Coextrusion. Fastest process investment occurs in Extrusion lines reconfigured for biodegradable grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting polyurethane film investment toward jurisdictions with clearer chemical authorization pathways and lower compliance friction. Producers are relocating extrusion capacity to exploit gaps between REACH enforcement timelines and emerging market registration requirements.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify aliphatic TPU interior films with captive Shore A hardness tolerances. ECHA diisocyanate authorization deadlines are accelerating reformulation R&D at Ludwigshafen and Leverkusen chemical clusters. The Rhine-Ruhr industrial corridor hosts integrated suppliers with backward integration into polyol manufacturing.
United States
FDA ISO 10993 biocompatibility pathways are opening device supply chains to specialty film entrants with validated vapor transmission documentation. Medical device OEMs in Massachusetts and Minnesota consolidate procurement through multi-year sole-source agreements. EPA state-level chemical disclosure rules in California and New York are diverging from federal timelines.
China
GB standards for plastic film migration limits constrain export-bound production from Yangtze River Delta extrusion lines. Domestic wound care manufacturers in Jiangsu and Zhejiang are scaling breathable film capacity for hospital procurement consortia. MIIT dual carbon goals are pressuring producers toward waterborne dispersion technologies.
India
CDSCO production-linked incentive schemes are attracting film extruders to establish sterile-grade capacity for domestic medical device manufacturing. Maharashtra and Gujarat industrial zones are emerging as preferred locations for wound care film investment. BIS certification requirements are creating compliance bottlenecks for imported specialty grades.
Japan
METI chemical management frameworks are accelerating fluorine-free barrier film development for food and medical packaging applications. Osaka-based converters serve precision electronics protection segments with thickness-tolerance specifications. PMDA medical device regulations shape qualification pathways for breathable film entrants.
Polyurethane (PU) Film Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable formulation niches and regional medical qualification pathways. The vendor base stratifies across three maturity levels: integrated chemical conglomerates with captive raw material supply, mid-cap specialists with validated regulatory documentation, and regional extruders competing on slit-roll turnaround speed. Two strategic archetypes dominate: backward-integrated suppliers controlling polyol and isocyanate production, and technology-focused specialists commanding premium positioning through coextrusion precision. Competitive intensity centers on portfolio diversification into certified biodegradable grades and geographic expansion through sterile-grade capacity establishment in India.
Among German chemical conglomerates, BASF SE and Covestro AG exemplify the integrated archetype with in-house control over critical raw material streams. DingZing Advanced Materials Inc. represents the precision-specialist tier competing on thermoplastic polyurethane film thickness control for medical and industrial tape applications. These three anchors illustrate the competitive spectrum from scale-driven chemical integration to specification-driven niche positioning.
| Leading Market Players |
|---|
| 3M |
| Huntsman International LLC |
| BASF SE |
| Permali Gloucester Limited |
| American Polyfilm Inc. |
| Covestro AG |
| Avery Dennison Corporation |
| DingZing Advanced Materials Inc. |
| The Lubrizol Corporation |
| Others |
Value Network & Pricing Analysis
German automotive OEM consolidation around haptic surface specifications is forcing specialty film suppliers to absorb polyol cost volatility while holding contract prices fixed under multi-year procurement agreements.
Pricing Analysis
Input-cost pass-through from aromatic isocyanate and aliphatic polyester polyol fluctuations governs contract renegotiation cycles between European compounders and medical device OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from industrial masking films. Pricing pressure stems from Asian MDI suppliers controlling merchant supply routes. Industrial converters exhibit highest price sensitivity; German automotive Tier 1s accept premium positioning for validated haptic consistency.
Supply Chain Analysis
India's CDSCO production-linked incentive schemes and China's MIIT dual carbon mandates are reshaping sourcing patterns toward domestic extrusion capacity for sterile-grade and waterborne dispersion films. Manufacturing gravity centers on Germany, China, and the United States. Feedstock chains draw from Asian aromatic isocyanate production, European polyol manufacturing, and North American specialty additive compounding. Single-source vulnerability concentrates in MDI merchant supply. Distribution runs through integrated chemical suppliers with captive raw material production and technical distributors serving slit-roll converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable formulation premiums and medical-grade certification tiers as REACH compliance costs compress commodity film returns.
For Market Incumbents: Lock in sole-source agreements with German automotive OEMs and US Northeast hospital procurement consortia before CDSCO incentive schemes mature Indian domestic capacity. Prioritize captive polyol production to defend against Asian isocyanate supplier pricing power. Accelerate ECHA-compliant aliphatic polyester R&D to outpace reformulation deadlines. For New Entrants and Emerging Players: Launch via technical distributor partnerships targeting mid-cap industrial converters underserved by integrated chemical conglomerates. White-space concentrates in Indian sterile-grade capacity for domestic wound care manufacturing and fluorine-free barrier films for Japanese food packaging. Qualify biodegradable portfolios under EU extended producer responsibility frameworks to bypass incumbent certification moats. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing validated ISO 10993 documentation and coextrusion precision capabilities. Long-term viability favors producers with backward integration into polyol manufacturing or certified biodegradable portfolios aligned with EU packaging waste directives. Watch CDSCO incentive disbursement velocity as inflection indicator for Indian manufacturing migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Manufacturing | Captive raw material supply insulates BASF and Covestro from Asian isocyanate price volatility. |
| Biodegradable Portfolio Certification | EU extended producer responsibility frameworks reward first-movers with closed-loop collection partnerships. |
| Sterile-Grade Capacity Establishment | CDSCO production-linked incentives attract extruders to Maharashtra and Gujarat industrial zones. |
| Waterborne Dispersion Technology Transition | Low-VOC aliphatic systems penetrate German automotive interior specifications previously served by solvent coatings. |
| Multi-Year Sole-Source Agreements | Hospital procurement consortia consolidate film sourcing through outcome-based supplier partnerships bundling sterilization validation. |
Research Methodology
Bottom-up automotive and medical device demand modeling reconciled against top-down chemical production and trade flow tracking forms the analytical core of this study. Primary interviews with film extrusion plant managers, procurement leads at German automotive Tier 1 suppliers, biomedical engineers at US medical device OEMs, and technical directors at European chemical conglomerates combined with secondary validation from ECHA REACH registration databases, FDA 510(k) filings, SEC 10-K disclosures, and Cefic industry statistics. Triangulation across these sources calibrated volume estimates and pricing assumptions.
Input-output matrix framing connects diisocyanate and polyol production capacities to downstream film extrusion throughput across product type, application, end user, and technology segmentation dimensions. CAGRs derive from regression analysis of historical capacity utilization, substitution elasticity between conventional and biodegradable grades, and regulatory compliance cost trajectories across the analysis window. Forecast inputs incorporate REACH phase-down timelines, CDSCO incentive scheme uptake rates, and automotive platform electrification content shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU F-Gas Regulation enforcement or abrupt MDI supply disruptions from Asian merchant producers. Forecasts reflect documented assumptions regarding reformulation R&D timelines, qualification cycle durations, and extended producer responsibility scheme implementation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Stretch Films Packs Market
Poly film
Cellulose Film Packaging Market
Poly film
Bio-PET Film Market
Poly film
China Plastic Packaging Film Market
Poly film
PCR Bubble Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Global Polyethylene Packaging Market
Poly film
Forming Films Market
Poly film
Polybag Mailers Market
Poly film
Isotropic Film Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
Surface Printed Film Market
Poly film
Co Extruded Films Market
Poly film
Polypropylene Packaging Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market