
 Blown Film Extruder Market | 2026-2036
Blown Film Extruder Market Size, Share, and Industry Trends Forecast 2026-2036
Blown Film Extruder Market Outlook
Distributor networks for blown film extrusion equipment is narrowing as original equipment manufacturers build direct service arms in priority territories. Reifenhäuser leverages in-house polymer testing labs to lock in specification-driven buyers across Central Europe. Davis-Standard sustains aftermarket parts dominance in North America through region-stocked spare inventory. W&H competes on line-speed engineering, offering die-head configurations that push output thresholds for high-volume packaging converters.
A blown film extruder is a plastics processing machine that extrudes molten polymer through a circular die, inflates the resulting tube with air, and collapses it into flat film for subsequent winding or bag conversion; typical systems operate at melt temperatures between 180°C and 240°C depending on resin chemistry, with die diameters ranging from 50mm to 2000mm for applications spanning shrink wrap, agricultural mulch, and medical barrier film. Monolayer extruders occupy the volume base for commodity bag and sheet production where capital efficiency governs purchasing decisions. Multilayer and co-extrusion systems capture disproportionate margin pools as barrier specifications for modified-atmosphere packaging and pharmaceutical films tighten resin-layer tolerances. Recycled-content configurations are gaining traction among converters responding to brand-owner sustainability mandates, though feedstock consistency limits current deployment scale.
The European Union's REACH framework and F-Gas Regulation constrain fluoropolymer barrier additives in food-contact films, redirecting formulation investment toward ethylene vinyl alcohol and polyamide co-extrusion architectures. The US FDA maintains 21 CFR compliance thresholds for indirect food additives that govern resin selection and migration testing protocols for domestic packaging film exports. China's GB standards for plastic packaging set mandatory thickness floors and recycled-content floors that shape import equipment specifications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capital in incompatible extrusion configurations.
Market Dynamics
Converters are retooling extrusion lines to meet the EU's Packaging and Packaging Waste Regulation mandates for recyclable film structures, forcing a wholesale shift from multilayer fluoropolymer barriers to co-extruded ethylene vinyl alcohol and polyamide architectures.
Growth Catalysts
- Barrier specification tightening:Modified-atmosphere packaging for fresh protein and pharmaceutical films is driving multilayer co-extrusion system demand as shelf-life requirements harden.
- REACH fluoropolymer constraints:The EU's F-Gas Regulation and ECHA restrictions on perfluorinated compounds are redirecting formulation investment toward compatible resin-layer systems.
- German machinery cluster density:Reifenhäuser and W&H anchor a concentrated engineering base in Central Europe that exports turnkey lines to converters in Turkey, Poland, and Southeast Asia.
Market Restraints
- Recycled feedstock inconsistency:Post-consumer polyethylene stream variability limits deployment scale for recycled-content extrusion configurations despite brand-owner mandates.
- Die-head engineering concentration:Precision multilayer die manufacturing concentrates among a handful of German and Austrian suppliers, creating procurement bottlenecks for barrier film converters.
- Energy cost volatility:Melt processing at 180°C to 240°C consumes substantial electricity, exposing European converters to continental power price swings that compress capital return timelines.
Strategic Opportunities
- Agricultural mulch film conversion:China's GB standards mandating thickness floors and recycled-content minimums for plastic packaging create specification-driven equipment demand as domestic converters upgrade.
- Medical barrier film expansion:Sterile packaging for pharmaceutical devices represents an underpenetrated application where co-extrusion tolerances command premium system pricing.
- Direct service arm buildout:Original equipment manufacturers bypassing distributor networks to establish captive technical service in priority territories capture specification-driven buyers.
Industry Challenges
- Multilayer die calibration expertise:Barrier film production requires technicians capable of maintaining layer-thickness tolerances across five to nine resin streams, a skill set scarce outside established machinery clusters.
- Legacy line integration friction:Retrofitting recycled-content feed systems onto existing monolayer extruders demands mechanical and control-system reconciliation that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blown Film Extruder Market |
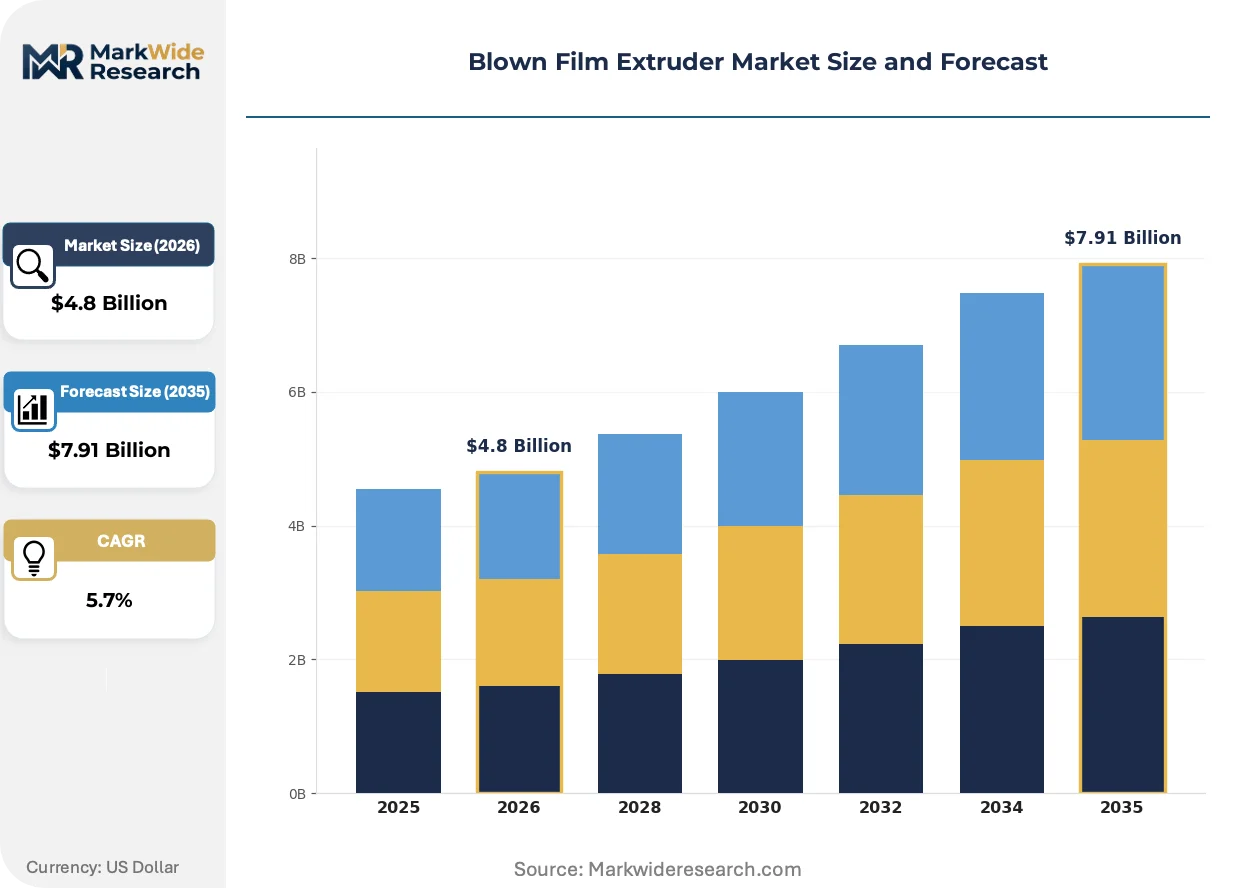
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolayer, Multilayer, Co-extrusion, Recycled End User: Packaging, Agriculture, Automotive, Consumer Goods Size: Small, Medium, Large, Custom Technology: Blown Film, Cast Film, Stretch Film, Others |
| Companies Covered | Reifenhäuser, Davis-Standard, Kiefel, W&H, Leistritz, Bausano, COWELL EXTRUSION, Kabra Extrusiontechnik, Luigi Bandera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blown Film Extruder Market Strategic Shifts
Extrusion control architecture is digitizing melt-pressure and bubble-stability monitoring, enabling real-time gauge correction that reduces resin giveaway. These advances compress the performance gap between commodity and precision systems.
Sensor-integrated die heads are digitizing blown film production through distributed temperature and pressure monitoring arrays. High-volume packaging converters in Germany and Austria are adopting these systems to minimize thickness variation and resin overconsumption. The technology is digitizing quality assurance workflows that previously required offline laboratory testing.
REACH and the F-Gas Regulation are constraining fluoropolymer barrier additives in food-contact films across the European Union. Formulators are pivoting toward ethylene vinyl alcohol and polyamide co-extrusion architectures that maintain oxygen transmission rates without restricted chemistry. Modified-atmosphere packaging converters in France and Italy face the steepest retooling burden as existing multilayer lines require die and cooling modifications.
Specification-driven procurement is consolidating buyer influence among large flexible packaging converters with in-house polymer testing capabilities. These buyers now bypass distributor networks to negotiate directly with original equipment manufacturers for line-speed guarantees and aftermarket parts commitments. The pattern is most visible in Germany, where Reifenhäuser's captive polymer laboratories lock in long-term service relationships with Central European converters.
Blown Film Extruder Market Segmentation
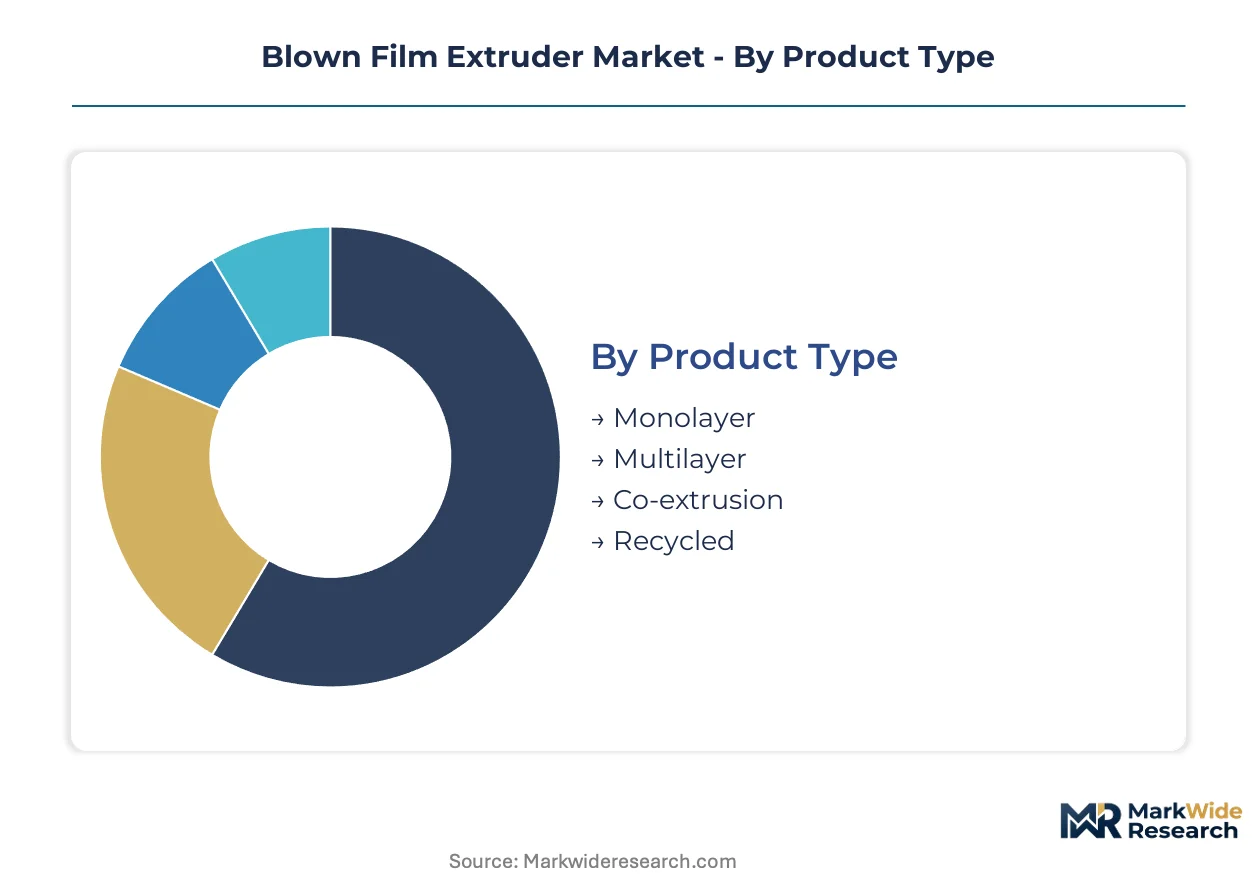
Blown film extruder purchasing cycles vary dramatically across configuration types, with commodity monolayer systems turning every 7-10 years while precision multilayer lines extend to 15-year replacement horizons. Understanding these cadences helps suppliers align service contracts and upgrade pathways with actual capital deployment patterns.
Product Type:
Monolayer extruders command the shortest replacement cycles due to standardized mechanics and price-sensitive buyer bases, while multilayer systems lock in decade-plus relationships through proprietary die-head engineering.
- Monolayer:Single-die architectures process commodity polyethylene grades at outputs up to 500 kg/hour. Turkish and Polish converters dominate procurement volume as these markets expand bag and sheet capacity for retail distribution.
- Multilayer:Five-to-nine layer configurations co-extrude ethylene vinyl alcohol and polyamide barriers for modified-atmosphere meat packaging. German food-packaging specialists anchor demand as shelf-life specifications harden across EU retail chains.
- Co-extrusion:Simultaneous resin-stream processing enables functional layer combinations without adhesive lamination steps. Medical barrier film producers in Switzerland and Austria specify these systems for pharmaceutical sterile packaging.
- Recycled:Post-consumer feedstock handling requires specialized screw geometries and filtration arrays. Deployment concentrates among Nordic converters responding to brand-owner sustainability mandates despite feedstock consistency challenges.
Monolayer dominates installed base. Multilayer is where expansion concentrates.
End User:
Packaging converters absorb the highest absolute machinery volume, though agricultural buyers are shortening replacement cycles as regulatory thickness mandates force equipment refresh.
- Packaging:Flexible film producers serving food, beverage, and pharmaceutical sectors purchase 70% of multilayer system output. French and Italian converters face the steepest retooling burden as EU Packaging and Packaging Waste Regulation mandates recyclable structures.
- Agriculture:Mulch film and greenhouse sheeting producers operate in China's Shandong and Hebei provinces where GB standards mandate minimum thickness and recycled-content floors. Domestic converters upgrade lines to meet compliance deadlines.
- Automotive:Surface protection films and interior trim applications specify medium-output systems with tight gauge control. Czech and Slovak component suppliers anchor European demand for paint-protection film extrusion.
- Consumer Goods:Retail carry-out bags and disposable sheeting drive small-system volume in Southeast Asian markets. Indonesian and Vietnamese converters prioritize capital efficiency over barrier performance.
Packaging commands premium pricing. Agriculture is climbing the fastest on regulatory-forced replacement.
Size:
Capital deployment patterns split between volume-driven large-system buyers seeking scale economies and specialty converters requiring custom die configurations for niche barrier specifications.
- Small:Die diameters below 200mm serve laboratory-scale development and regional bag producers. Portuguese and Greek converters maintain installed base for local-market flexibility.
- Medium:200-600mm die ranges balance output and versatility for mid-tier packaging houses. Polish converters expanding into barrier films favor this configuration for manageable capital outlay.
- Large:600-1500mm systems achieve outputs exceeding 1000 kg/hour for high-volume shrink wrap and stretch film. German and Austrian producers anchor demand with line-speed guarantees from machinery suppliers.
- Custom:Non-standard die geometries and multi-station configurations serve medical and optical film specialists. Swiss pharmaceutical packaging firms specify these for sterile barrier precision.
Medium systems dominate unit shipments. Large configurations capture disproportionate revenue share.
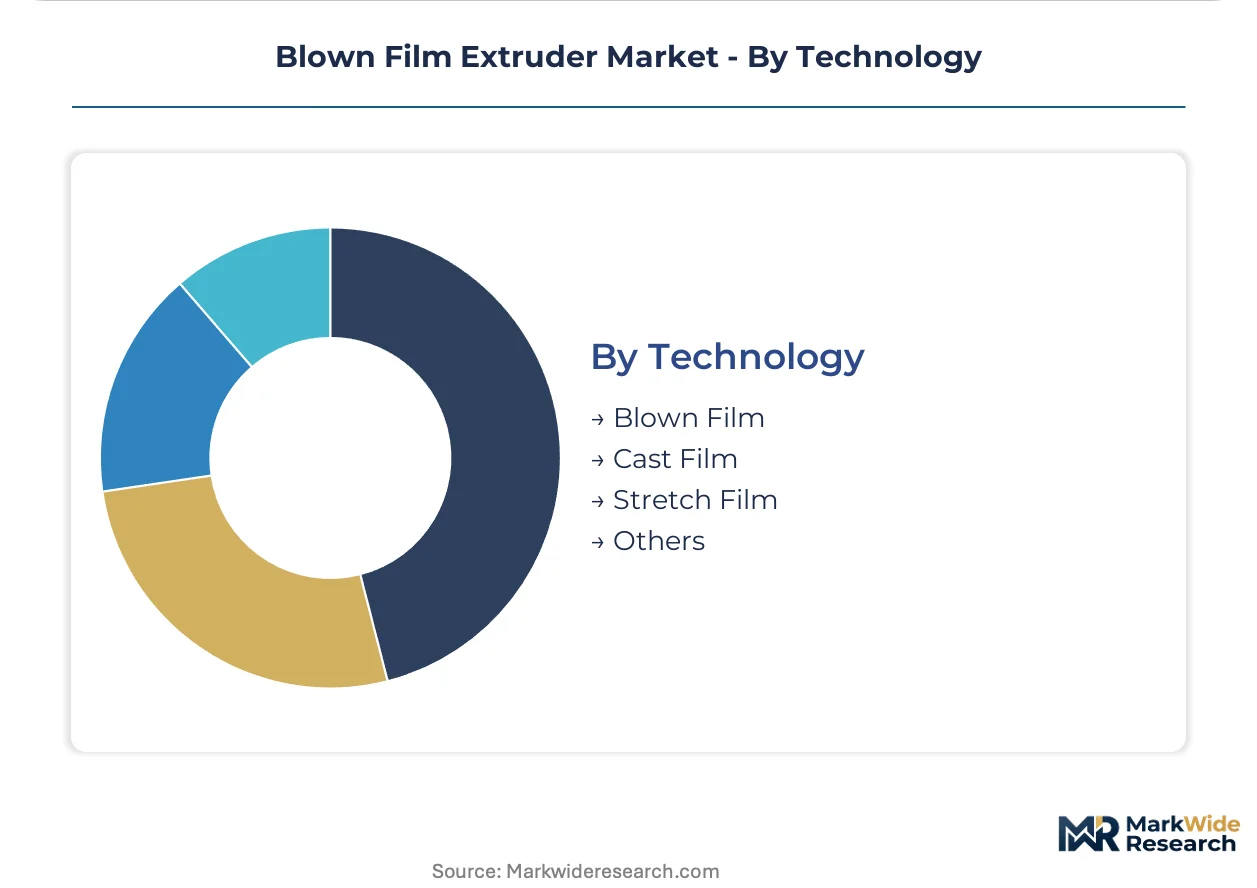
Technology:
Process technology selection determines resin compatibility, output range, and downstream conversion economics, with blown film maintaining dominance despite cast film inroads in specific applications.
- Blown Film:Circular die inflation produces biaxially oriented film with balanced mechanical properties. This remains the default technology for flexible packaging converters across all European markets.
- Cast Film:Flat die extrusion onto chilled rolls yields superior optical clarity and gauge uniformity. Italian food-wrap specialists specify cast lines where haze specifications dominate barrier requirements.
- Stretch Film:High-molecular-weight polyethylene formulations require specialized screw designs and tension control. German logistics packaging producers anchor demand for pallet-wrap extrusion systems.
- Others:Water-quenched blown film and double-bubble processes serve shrink film and high-clarity applications. Niche demand concentrates among specialty converters in Belgium and the Netherlands.
Blown film anchors installed base. Cast configurations are gaining share fastest in clarity-critical food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Central European machinery exports, connecting German extrusion equipment manufacturers to Turkish and Polish packaging converters via integrated rail-river networks.
Germany
Modified-atmosphere packaging specifications from Rewe and Aldi drive multilayer system demand. The F-Gas Regulation restricts fluoropolymer barriers, redirecting formulation toward EVOH architectures. Reifenhäuser and W&H anchor engineering clusters in Troisdorf and Lengerich serving export markets.
China
GB standards mandating thickness floors and recycled-content minimums force agricultural mulch line upgrades. MIIT enforcement timelines compress converter capital deployment into 2024-2026. Shandong Province converters in Weifang and Qingdao dominate procurement volume for compliance-driven equipment refresh.
United States
Food-contact film exporters face FDA 21 CFR migration testing protocols that govern resin selection. The EPA's emerging perfluorinated substance scrutiny parallels REACH constraints. Midwest flexible packaging converters in Wisconsin and Illinois sustain aftermarket parts demand for installed Davis-Standard systems.
Turkey
Retail bag capacity expansion concentrates in Kocaeli and Istanbul to serve Middle Eastern export markets. The country's alignment with EU packaging waste directives shapes equipment specification. Local converters prioritize monolayer systems from German suppliers for capital efficiency.
Switzerland
Pharmaceutical sterile packaging specifications command premium co-extrusion system pricing. Swissmedic device regulations enforce barrier film validation protocols that favor precision multilayer configurations. Basel-area medical packaging specialists anchor niche demand for custom die configurations.
Blown Film Extruder Market Competitive Environment
On the supply side, the industry is consolidating around machinery clusters with captive polymer testing and direct service capabilities. German and Austrian engineering bases concentrate precision multilayer die manufacturing, creating procurement bottlenecks for barrier film converters. Two strategic archetypes dominate: integrated turnkey suppliers with in-house laboratories, and aftermarket-focused specialists with region-stocked spare inventory. Competitive moves center on bypassing distributor networks to establish captive technical service arms, and engineering line-speed guarantees that compress resin giveaway for high-volume buyers.
Within the integrated laboratory tier, Reifenhäuser exemplifies specification-driven buyer lock-in through polymer testing infrastructure. Among North American aftermarket specialists, Davis-Standard occupies a position anchored by spare parts dominance. W&H represents the line-speed engineering archetype, with die-head configurations pushing output thresholds for packaging converters. These three anchors illustrate how competitive positioning diverges across service models rather than converging on identical capability stacks.
| Leading Market Players |
|---|
| Reifenhäuser |
| Davis-Standard |
| Kiefel |
| W&H |
| Leistritz |
| Bausano |
| COWELL EXTRUSION |
| Kabra Extrusiontechnik |
| Luigi Bandera |
| Others |
Value Chain & Pricing Dynamics
The Troisdorf-Lengerich machinery cluster in Germany concentrates precision multilayer die-head manufacturing, giving Reifenhäuser and W&H outsized leverage over pricing for barrier film converters in France and Italy facing EU Packaging and Packaging Waste Regulation compliance deadlines. This geographic concentration of engineering capability translates directly into premium capture for specification-driven systems while commodity monolayer equipment faces cost compression from Turkish and Polish buyers.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with three-tier pricing separating laboratory-validated multilayer configurations from standard co-extrusion systems and economy monolayer lines. Price differentiation rests on certification grade for food-contact compliance and after-sales service bundling. Cost compression in the monolayer tier is intensifying because Turkish converters prioritize capital efficiency over barrier performance. Small-scale agricultural buyers in Southeast Asia exhibit the highest price sensitivity, while Swiss pharmaceutical packaging specialists accept substantial premiums for sterile barrier validation.
Supply Chain Analysis
Upstream polymer feedstock supply concentrates in Germany, Belgium, and the Netherlands, with ethylene vinyl alcohol and polyamide resin streams drawing from petrochemical complexes along the Rhine corridor. Critical component dependencies include precision-machined die heads from Austrian suppliers, servo-controlled bubble stabilizers from Italian automation houses, and high-torque extruder screws from specialized forges in the Czech Republic. Single-source vulnerability in multilayer die manufacturing creates procurement bottlenecks for converters scaling barrier film capacity. Distribution runs through captive technical service arms that bypass traditional distributor networks in priority territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. The EU's F-Gas Regulation and REACH constraints on fluoropolymer barriers create switching costs that lock converters into established supplier relationships for compliant resin-layer architectures.
For Market Incumbents: Entrench specification-driven buyer relationships by expanding in-house polymer testing laboratories in Central Europe. Capture aftermarket parts commitments through region-stocked spare inventory to defend against emerging Chinese equipment entrants offering lower capital cost. Prioritize certification investment for food-contact compliance tiers that new competitors cannot rapidly replicate.
For New Entrants and Emerging Players: Build out recycled-content feedstock handling capabilities to serve Nordic converters responding to brand-owner sustainability mandates. Target agricultural mulch film upgrades in China's Shandong Province where GB standard compliance deadlines force equipment refresh. Lead with direct technical service presence rather than distributor partnerships to overcome incumbent specification lock-in.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because precision multilayer die manufacturing concentrates among a handful of German and Austrian engineering houses with irreplaceable calibration expertise. Acquisition targets with captive polymer laboratories and established FDA 21 CFR validation protocols command structural scarcity premiums. Watch for MIIT enforcement acceleration in China as the inflection signal for compliance-driven equipment replacement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Testing | Reifenhäuser's captive laboratories lock in Central European converter specifications against rivals. |
| Direct Service Arm Buildout | W&H bypasses distributor networks in Turkey to capture line-speed guarantee negotiations directly. |
| Recycled-Content Configuration Development | Nordic converters respond to brand-owner mandates despite post-consumer feedstock variability challenges. |
| Medical Barrier Film Certification | Swissmedic validation protocols in Basel create premium pricing for sterile packaging precision systems. |
| Regional Spare Inventory Expansion | Davis-Standard sustains North American aftermarket dominance through Wisconsin and Illinois stocking points. |
Study Parameters
Cross-validation between machinery shipment data and converter capital expenditure disclosures anchors the qualitative findings. Primary interviews with extrusion line operators, flexible packaging procurement directors, aftermarket service managers, and polymer formulation specialists combined with secondary validation from EU F-Gas Regulation filings, FDA 21 CFR migration testing protocols, Chinese GB standard enforcement timelines, and trade association capacity surveys. Bottom-up equipment unit analysis and top-down resin demand modeling provided triangulation across the projection horizon.
Calibration against historical replacement cycles and regulatory compliance deadlines shaped the analytical framework. Segmentation dimensions modeled include product configuration tier, end-use application, die diameter scale, and technology type across the analysis window. CAGRs derived from machinery order backlogs and converter expansion announcements, with specific inputs from REACH fluoropolymer restriction timelines and China's MIIT enforcement patterns for agricultural mulch specifications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese equipment manufacturers offering integrated recycled-content systems would shift outcomes. Material shifts in EU Packaging and Packaging Waste Regulation implementation timelines or feedstock consistency breakthroughs for post-consumer polyethylene streams would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyolefin Films Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Soft Touch Film Market
Poly film
Polyimide Films and Tapes Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Formable Films Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Polybag Mailers Market
Poly film
Hexacomb Packaging Market
Poly film
Waste Wrap Film Market
Poly film
Tube Laminating Films Market
Poly film
Lidding Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Global PVDC Coated Films Market