
 Twist Wrap Film Market | 2026-2036
Twist Wrap Film Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Wrap Film Market Analytics
Aftermarket technical service revenue from film line optimization and die refurbishment is reconfiguring profit pools away from pure resin sales. Exxon Mobil Corp leverages its metallocene polyethylene catalyst portfolio to anchor premium twist wrap grades with superior clarity and seal integrity. Amcor plc sustains global reach through integrated film extrusion and pre-printing operations across multiple continents. Clondalkin Group Holdings B.V. specializes in narrow-web twist wrap formats for regional confectionery brands, occupying a defensible niche in European private-label supply.
Twist wrap film denotes a thin, flexible packaging substrate engineered for manual or machine-applied helical wrapping around individual confectionery pieces, lozenges, and small consumer goods, typically manufactured via blown or cast extrusion at gauges between 18 and 40 microns with controlled coefficient of friction for high-speed twisting. The film must deliver dead-fold memory, barrier against moisture and oxygen, and compatibility with hot-stamp or flexographic decoration. Polypropylene grades lead the product type landscape due to their stiffness and twist retention, while blown film technology dominates production owing to its balanced orientation and cost efficiency. Food packaging commands the largest application share, though personal care twist wraps for bath bombs and soap samples are gaining traction as brands seek shelf differentiation.
The FDA regulates food contact substances under 21 CFR 177.1520 for olefin polymers, while REACH and the EU Packaging and Packaging Waste Directive shape material compliance and recyclability mandates across European supply chains. EFSA migration testing protocols for overall and specific migration limits directly influence resin selection and additive packages for twist wrap formulations. Stakeholders must monitor evolving extended producer responsibility schemes and chemical recycling infrastructure buildout to secure feedstock access and maintain brand license to operate.
Market Dynamics
EFSA's tightening migration limits for plastic food contact materials are compressing resin selection flexibility and forcing converters toward certified polypropylene and cyclic olefin copolymer grades, restructuring supplier relationships across European supply chains.
Growth Catalysts
- Confectionery portion-control demand:Food manufacturers in bakery and candy segments are expanding twist wrap formats for single-serve, shelf-stable products that extend retail shelf life without refrigeration infrastructure.
- REACH compliance premium:ECHA registration requirements for novel polymer additives are creating certified-grade price premiums that reward early-mover converters with verified supply chain documentation.
- German machinery clustering:Packaging equipment OEMs and material suppliers concentrate around Stuttgart and Hamburg, reducing lead times for film line optimization and die refurbishment services.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings transmit directly into polypropylene resin costs, compressing converter margins during upstream commodity spikes.
- Blown film capacity concentration:Production assets cluster among a limited set of European extrusion specialists, creating bottleneck risk during demand surges or equipment maintenance cycles.
- Monomaterial substitution pressure:Paper-based twist alternatives and cellulose films threaten volume share in premium confectionery segments where brands prioritize perceived sustainability.
Strategic Opportunities
- Personal care twist wraps:Bath bombs, soap samples, and solid cosmetics represent an underpenetrated application where brands seek shelf differentiation through distinctive helical wrapping formats.
- Chemical recycling infrastructure:EU Packaging and Packaging Waste Directive mandates are accelerating pyrolysis and depolymerization plant investments, promising certified circular feedstock access for food-grade polypropylene.
- Hot-stamp decoration convergence:Integration of digital printing with traditional flexographic pre-printing enables short-run customization for regional confectionery brands without plate changeover costs.
Industry Challenges
- Metallocene catalyst expertise scarcity:Operating advanced polyethylene catalyst systems for premium clarity grades requires specialized polymer engineering talent concentrated among a handful of technical service providers.
- Migration testing timeline compression:EFSA overall and specific migration limit certifications demand 12-18 month validation cycles that delay new additive package commercialization and lock in legacy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Wrap Film Market |
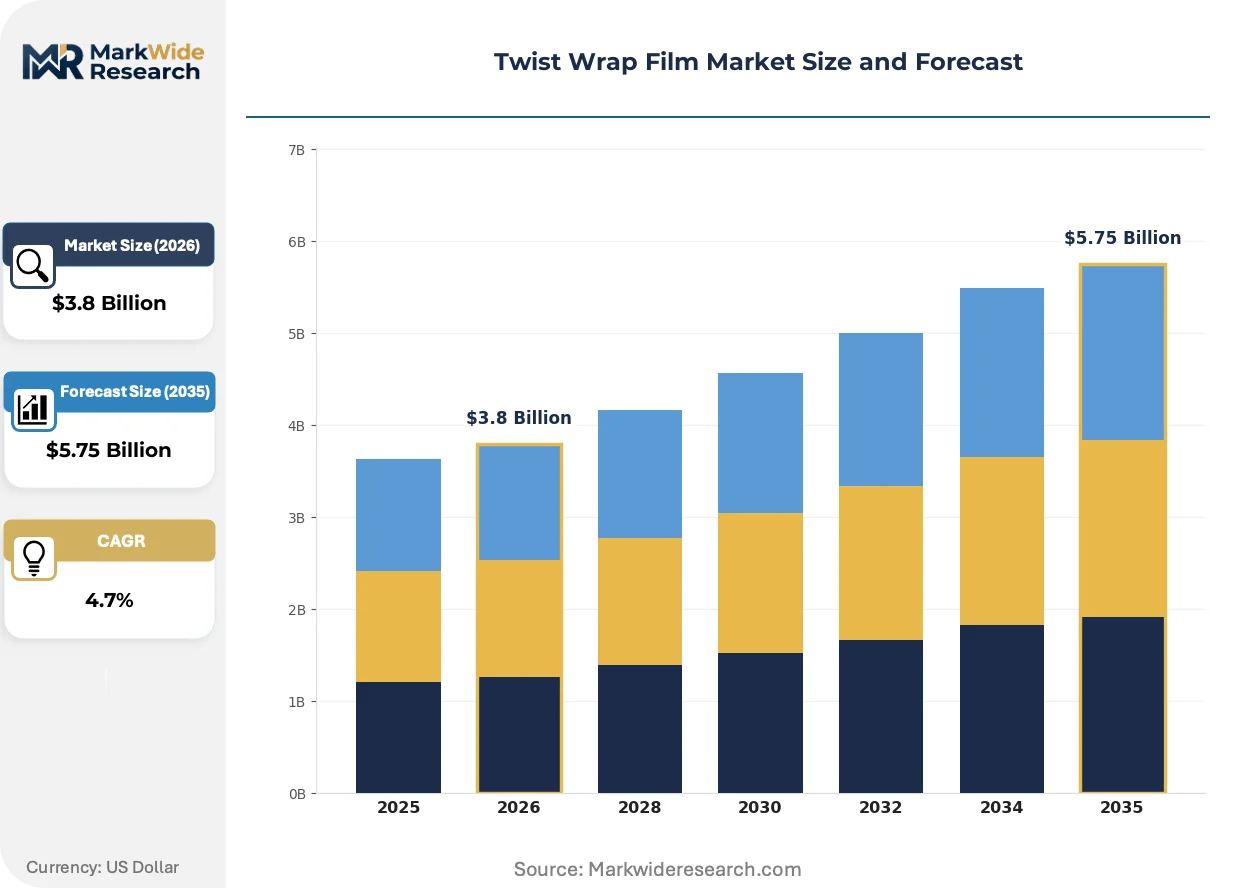
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Other Application: Food Packaging, Consumer Goods, Pharmaceuticals, Personal Care Technology: Blown Film, Cast Film, Stretch Film, Heat Shrink Film End User: Food Manufacturers, Retailers, Healthcare Providers, Others |
| Companies Covered | Exxon Mobil Corp, Clondalkin Group Holdings B.V., TOPAS Advanced Polymers GmbH, Amcor plc, Jindal Poly Films Limited, Reynolds Consumer Products, Sigma Plastics Group, NAN YA PLASTICS CORPORATION, Stratex Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Wrap Film Market Evolving Landscape
Digital workflow integration across pre-press, extrusion, and converting operations is collapsing design-to-delivery timelines and enabling mass customization at previously unattainable production economics.
Metallocene-catalyzed polyethylene is virtualizing conventional Ziegler-Natta polypropylene in high-clarity twist wrap applications. Premium confectionery brands in Germany and Switzerland are adopting these grades for superior seal integrity and optical properties. The technology is virtualizing historical material specifications and compressing the premium-standard gap in barrier performance.
REACH Annex XVII restrictions on phthalate plasticizers and EFSA's evolving overall migration limits are disqualifying legacy additive packages from food contact approval. Converters face reformulation costs or supplier switches to maintain compliance documentation. Small and mid-sized European private-label suppliers are most exposed, lacking in-house regulatory affairs capacity.
Brand procurement teams are consolidating supplier panels and demanding integrated film extrusion with pre-printing capabilities to reduce coordination friction. Regional confectionery brands are displacing fragmented converter-printer relationships with single-source contracts. This concentration is most visible in Germany, where packaging machinery OEMs increasingly specify approved material suppliers for line warranty compliance.
Twist Wrap Film Market Segmentation
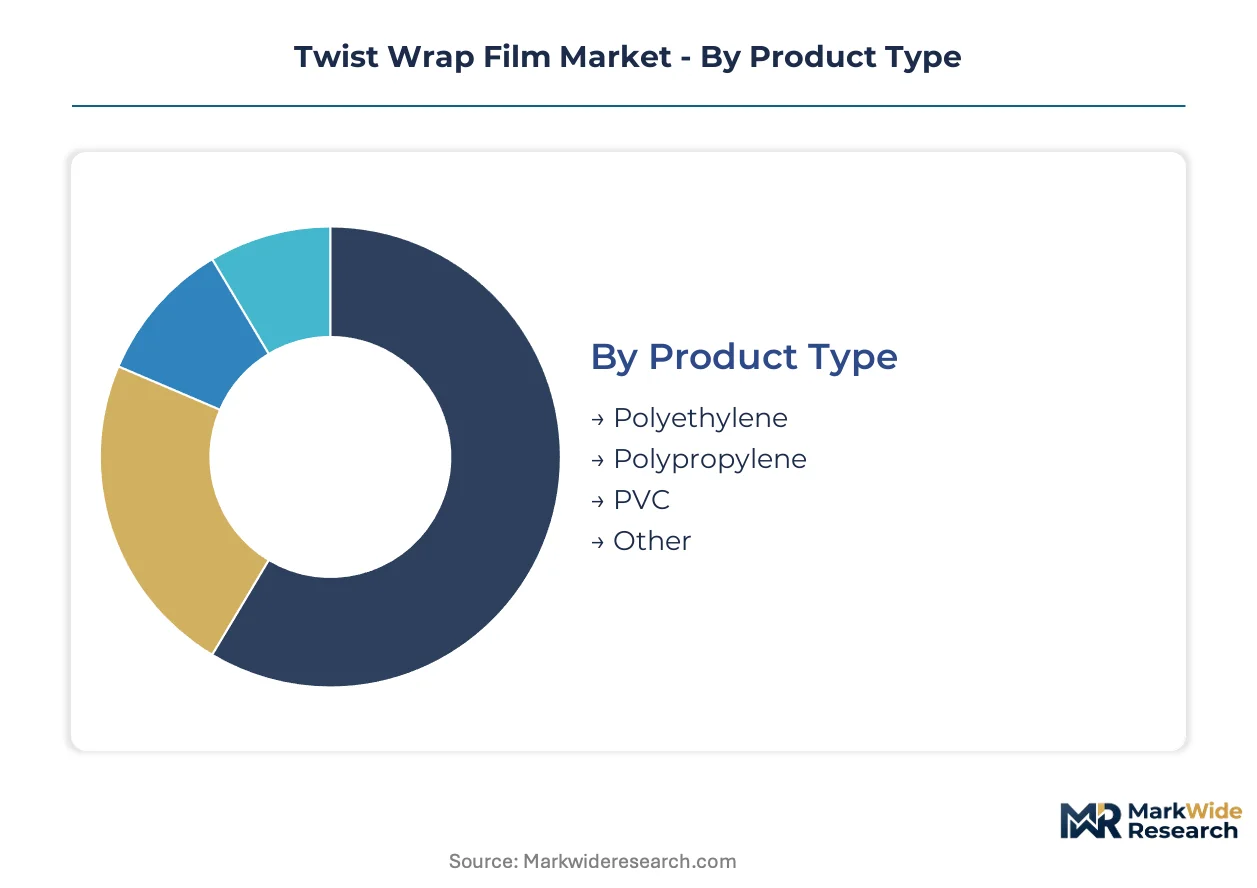
Twist wrap film segmentation reflects divergent technical requirements across confectionery protection, pharmaceutical compliance, and personal care aesthetics. Material stiffness, barrier performance, and decoration compatibility vary sharply by end-use, driving specialized resin grades and converting equipment configurations.
Product Type:
The use-case spectrum spans from high-clarity confectionery wraps demanding dead-fold memory to cost-driven bulk candy applications prioritizing seal reliability over optical properties.
- Polypropylene:Metallocene-catalyzed grades deliver superior twist retention and hot-stamp decoration adhesion for premium chocolate and hard candy segments in Germany. EFSA migration limits are compressing additive package options and certifying specific resin suppliers for food contact compliance.
- Polyethylene:Linear low-density formulations balance cost efficiency with adequate clarity for mid-tier bakery items and seasonal confectionery. Blown film lines in Hamburg and Stuttgart process these grades at high throughput for private-label supply chains.
- PVC:Phased out of food contact applications across Europe under REACH Annex XVII restrictions; residual demand concentrates in industrial twist formats with limited regulatory exposure.
- Other:Cyclic olefin copolymers and bio-based alternatives occupy niche pharmaceutical and premium personal care segments where barrier performance justifies material cost premiums.
Established volume favors Polypropylene; emerging adoption favors Polyethylene as metallocene catalyst diffusion narrows performance gaps.
Application:
Cost tier differentiation separates commodity food wraps from certified pharmaceutical formats requiring extensive migration documentation.
- Food Packaging:Confectionery portion-control formats dominate volume, with single-serve twists extending shelf stability for ambient distribution. German machinery OEMs specify material suppliers for line warranty compliance, concentrating converter relationships.
- Personal Care:Bath bombs and solid cosmetics represent an underpenetrated channel where helical wrapping delivers shelf differentiation. Brands in Switzerland and Austria are piloting these formats for premium positioning.
- Consumer Goods:Small hardware and promotional items utilize twist wraps for tamper evidence and retail display; demand clusters around seasonal promotional cycles with short lead times.
- Pharmaceuticals:Lozenge and single-dose medication wraps require EMA-compliant documentation and validated sterilization compatibility, limiting supplier pools to certified converters.
Food Packaging commands the largest revenue base; Personal Care is expanding most quickly as solid cosmetic formats gain retail traction.
Technology:
Volume concentration in blown film reflects balanced biaxial orientation and capital efficiency, while cast film serves high-speed lines demanding gauge uniformity.
- Blown Film:Dominant production method for twist wrap substrates, offering controlled coefficient of friction and balanced mechanical properties. European extrusion assets cluster among specialists around Stuttgart, creating bottleneck risk during demand surges.
- Cast Film:Superior optical clarity and gauge consistency for premium confectionery requiring high-definition flexographic decoration. Higher capital intensity limits adoption to integrated converters with pre-printing capabilities.
- Stretch Film:Modified formulations for cling-wrap applications in fresh produce and bakery segments; twist functionality secondary to elongation recovery.
- Heat Shrink Film:Cross-linked polyolefin grades for multi-pack collation and promotional bundling; distinct from helical twist applications but shares extrusion infrastructure.
Blown Film anchors production scale; Cast Film is gaining share fastest in premium segments where decoration quality determines brand selection.
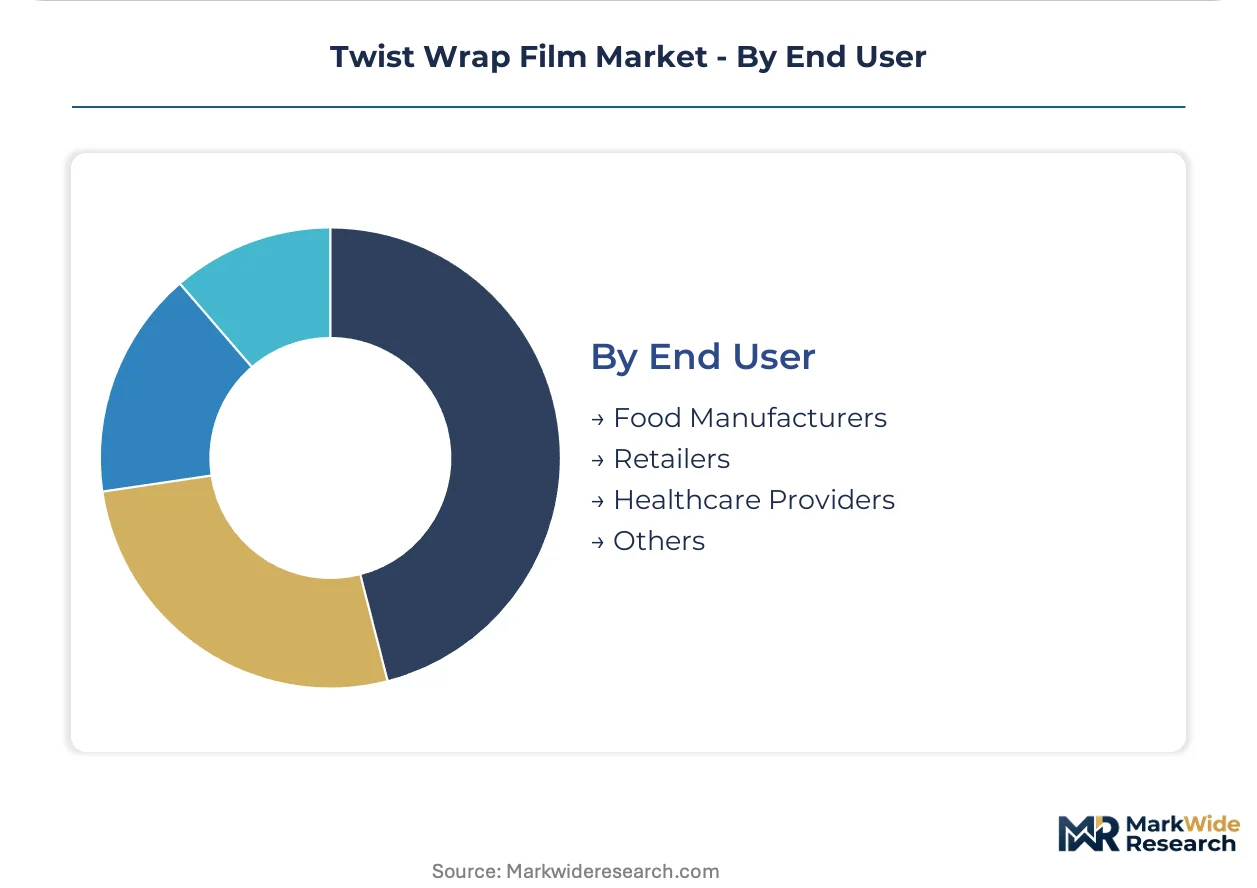
End User:
Customer type determines specification intensity, from retailer private-label cost targets to healthcare compliance documentation.
- Food Manufacturers:Confectionery and bakery producers specify twist wraps for portion control and shelf-life extension. Procurement consolidation favors integrated film-and-print suppliers to reduce coordination friction.
- Retailers:Private-label supply chains demand volume flexibility and rapid format changes; regional European brands displace fragmented converter relationships with single-source contracts.
- Healthcare Providers:Pharmaceutical packaging requires validated migration testing and batch traceability; EMA documentation timelines extend supplier qualification cycles.
- Others:Promotional product distributors and specialty chemical companies utilize twist formats for sample distribution and tamper evidence.
Food Manufacturers represent the deepest specification engagement; Retailers are driving supplier consolidation fastest through panel reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate low price elasticity for certified food-contact grades, while converters in India and Mexico face acute margin compression during resin cost spikes. This demand-elasticity contrast shapes regional investment patterns and supplier qualification timelines.
Germany
Confectionery machinery OEMs around Stuttgart specify approved material suppliers for line warranty compliance, concentrating converter relationships. EFSA migration testing protocols for overall and specific migration limits directly influence resin selection for twist wrap formulations. Hamburg hosts blown film extrusion specialists serving private-label supply chains with reduced lead times.
United States
FDA regulation under 21 CFR 177.1520 for olefin polymers governs food contact substance approvals, with confectionery brands demanding validated documentation. Portion-control packaging for single-serve candy drives volume in the Midwest bakery and snack corridors. Chicago-area converters cluster around integrated film extrusion and flexographic pre-printing operations.
Switzerland
Premium chocolate brands adopt metallocene-catalyzed polyethylene for superior seal integrity and optical properties. Swissmedic pharmaceutical packaging requirements extend supplier qualification cycles for lozenge and single-dose medication wraps. Basel-region converters specialize in EMA-compliant documentation and validated sterilization compatibility.
India
FSSAI food safety standards and BIS certification requirements compress additive package options for domestic confectionery supply chains. Jindal Poly Films Limited anchors domestic capacity in the National Capital Region. Maharashtra-based converters face feedstock volatility transmitted from crude oil and naphtha price swings.
China
GB standards for food contact materials and SAMR regulatory oversight shape material compliance for export-oriented confectionery packaging. Yangtze River Delta converters serve both domestic brands and European private-label demand. Guangdong province hosts narrow-web specialists for regional candy brand supply.
Twist Wrap Film Market Competitive Landscape
Capability concentration sits with integrated film-and-print specialists; scale advantage sits with resin producers with metallocene catalyst portfolios. The market structures around three tiers: petrochemical majors commanding raw material access, integrated converters controlling extrusion-to-decoration workflows, and regional specialists occupying narrow-web niches. Dominant competitive moves include procurement panel consolidation by brand owners and backward integration by converters into captive pre-printing operations.
Within the integrated converter tier, Amcor plc and Clondalkin Group Holdings B.V. exemplify global reach through multi-continent film extrusion networks. Exxon Mobil Corp anchors the petrochemical tier with metallocene polyethylene catalyst systems. Among Asia-Pacific fabricators, Jindal Poly Films Limited and NAN YA PLASTICS CORPORATION represent regional scale positions serving domestic confectionery demand and export markets respectively.
| Leading Market Players |
|---|
| Exxon Mobil Corp |
| Clondalkin Group Holdings B.V. |
| TOPAS Advanced Polymers GmbH |
| Amcor plc |
| Jindal Poly Films Limited |
| Reynolds Consumer Products |
| Sigma Plastics Group |
| NAN YA PLASTICS CORPORATION |
| Stratex Group Limited |
| Others |
Value Network & Pricing Analysis
Stuttgart's machinery OEM cluster concentrates converter relationships around certified material suppliers, amplifying pricing power for integrated film-and-print specialists while compressing margins for standalone resin distributors. EFSA migration testing timelines and REACH compliance documentation create certified-grade premiums that reward early-mover converters with verified supply chains.
Pricing Analysis
Aftermarket technical service revenue from film line optimization and die refurbishment drives lifetime value beyond pure resin transactions. Three-tier pricing structure across premium metallocene grades, standard polypropylene, and economy polyethylene levels reflects certification status and clarity performance. Cost compression in mid-tier segments is intensifying because propylene feedstock volatility transmits directly from crude oil and naphtha price swings. Private-label retailers demonstrate highest price sensitivity, while Swiss and German premium confectionery brands exhibit low elasticity for certified food-contact grades.
Supply Chain Analysis
Upstream propylene and ethylene feedstock sourcing draws from petrochemical complexes in Germany, Belgium, and the Netherlands. Resin selection hinges on metallocene catalyst availability, specialized additive packages, and pre-printing substrate compatibility. Single-source vulnerability concentrates among European blown film extrusion specialists clustered around Stuttgart and Hamburg. Distribution runs through integrated converter-printer networks serving consolidated brand procurement panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer engineering talent for metallocene catalyst operation remains scarce, constraining premium grade production capacity and locking competitive advantage with incumbent technical service providers.
For Market Incumbents: Entrench position through captive pre-printing operations and backward integration into film extrusion, reducing coordination friction for consolidated brand procurement panels. Defend against paper-based twist alternatives and cellulose film substitution by accelerating chemical recycling infrastructure partnerships for certified circular polypropylene feedstock. For New Entrants and Emerging Players: Personal care twist wraps for bath bombs and solid cosmetics in Switzerland and Austria offer white-space penetration with lower regulatory barriers than pharmaceutical formats. Target regional confectionery brands seeking short-run customization through digital printing integration without plate changeover costs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated film-and-print specialists with established EFSA documentation and metallocene catalyst expertise. Long-term viability rests on chemical recycling feedstock access and extended producer responsibility scheme compliance. Watch for pyrolysis and depolymerization plant commissioning announcements as inflection indicators for circular polypropylene supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pre-Printing | Captures decoration margin and reduces brand procurement friction for integrated converters. |
| Chemical Recycling Partnership | Secures EFSA-compliant circular feedstock access ahead of EU Packaging Directive mandates. |
| Digital Printing Capability Addition | Enables short-run customization for regional confectionery brands without plate costs. |
| Metallocene Catalyst Technical Service Expansion | Locks premium grade production expertise with scarce polymer engineering talent. |
| Personal Care Application Development | Diversifies revenue into underpenetrated bath bomb and solid cosmetic segments. |
Research Methodology
A standing panel of film extrusion plant managers, confectionery procurement leads, packaging machinery OEM technical directors, and regulatory affairs specialists provided ongoing calibration across the analysis window. Primary interview insights combined with secondary validation from EFSA migration testing protocols, REACH Annex XVII substance restrictions, EU Packaging and Packaging Waste Directive filings, and SEC disclosures from petrochemical majors. Bottom-up resin demand modeling and top-down packaging value chain sizing were triangulated for consistency.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions included material grade tier, application end-use, production technology, and regional regulatory cluster. CAGRs were derived from installed machinery capacity trajectories, confectionery portion-control format adoption curves, and migration testing timeline impacts on new grade commercialization. Feedstock price volatility assumptions and chemical recycling infrastructure buildout schedules informed sensitivity ranges.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by resin producers or accelerated paper substitution campaigns by sustainability-focused brands would shift outcomes. Cross-checking against EFSA additive approval databases and ECHA registration status is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Craft Plastic Films Market
Poly film
Polystyrene Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
In-Mould Label Film Market
Poly film
Poly Coated Paper Market
Poly film
Embossed Film Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Global Reclosable Films Market
Poly film
China Plastic Packaging Film Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Isotropic Film Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Polyethylene Film Market