
 Vertical Form Fill Seal Baggers Market | 2026-2036
Vertical Form Fill Seal Baggers Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Form Fill Seal Baggers Market Analytics
A capability gap between integrated motion-control platforms and standalone electromechanical systems is rotating capital deployment toward full-line automation vendors. ProMach leverages its portfolio breadth to bundle baggers with upstream filling and downstream case-packing equipment. Syntegon sustains engineering density in servo-driven forming and sealing architectures for pharmaceutical-grade applications. SACMI Imola SC anchors its position through ceramic-industry precision mechanics translated into high-speed bagging mechanics for abrasive granular products.
Vertical form fill seal baggers are continuous-motion packaging machines that draw flexible film from a roll, form a tube around a collar, fill the formed pouch with product, and seal it longitudinally and transversely at speeds reaching 200 bags per minute. These machines serve primary packaging functions across food, pharmaceutical, and chemical operations where product protection, shelf-life extension, and retail-ready presentation converge. The fully automatic automation level commands the dominant installed base as labor-cost pressures and throughput requirements intensify, while robotic integration represents the fastest-expanding configuration for changeover-intensive contract packaging environments. Plastic film materials retain volume leadership due to barrier-property tunability, though composite structures are capturing margin pools in oxygen-sensitive food and pharmaceutical segments.
FDA food safety modernization rules and EU machinery directives with CE marking requirements shape machine design, validation documentation, and export market access for bagger OEMs. ISO packaging standards and OSHA mechanical safety regulations further constrain guard design, interlock architecture, and operator training protocols. Stakeholders must weigh servo-electric replacement cycles against emerging AI-driven vision systems for real-time seal integrity verification.
Market Dynamics
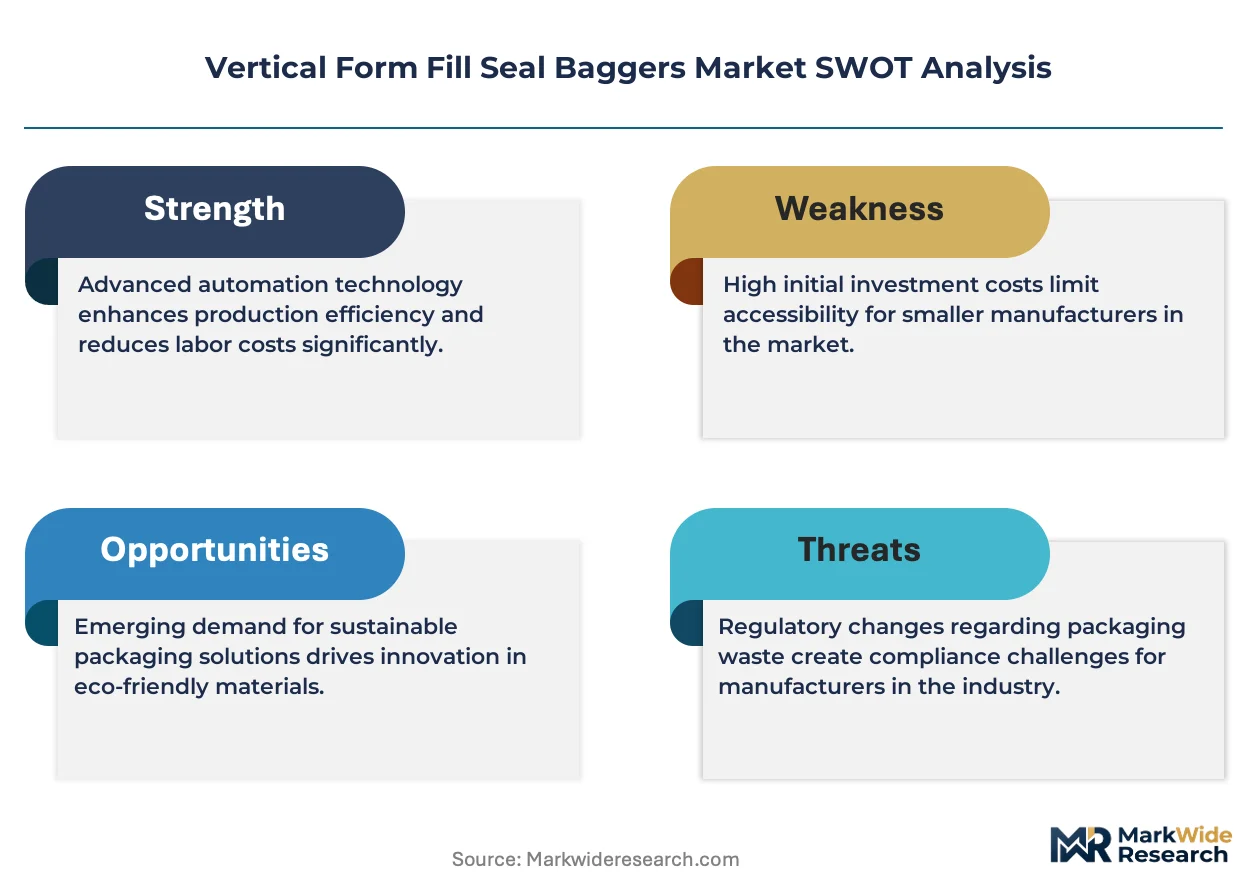
Motion-control convergence is compressing the vendor landscape as food and pharmaceutical buyers consolidate procurement around full-line automation platforms rather than standalone bagger purchases. This structural shift rewards engineering breadth over component specialization.
Growth Catalysts
- Servo-electric forming architectures:Pharmaceutical manufacturers in Germany and Switzerland demand servo-driven sealing systems to meet EU machinery directive validation requirements for batch traceability.
- FDA food safety modernization rules:US food processors must install automated baggers with integrated metal detection and vision systems to comply with preventive controls mandates.
- Ceramic-sector precision mechanics:Italian machinery clusters apply abrasive-material handling expertise from tile production to high-speed granular bagging for chemical and mineral operations.
Market Restraints
- Film resin cost volatility:Ethylene and propylene feedstock fluctuations compress margins for bagger OEMs locked into fixed-price maintenance contracts with food processors.
- Control system supplier concentration:Dependency on German and Japanese servo drive manufacturers creates lead time vulnerability for mid-tier bagger builders without captive electronics capacity.
- Composite structure technical limitations:Multi-layer oxygen barrier films remain incompatible with legacy ultrasonic sealing heads, forcing premature capital retirement.
Strategic Opportunities
- Contract packaging channel expansion:Third-party logistics providers in the Netherlands and Belgium are installing robotic changeover systems to serve SKU-proliferating snack brands.
- AI-driven seal integrity verification:Machine vision convergence with thermal imaging enables real-time defect detection that satisfies pharmaceutical-grade validation protocols.
- India food processing modernization:FSSAI packaging regulations and PLI scheme incentives are accelerating automated bagger adoption among spice and grain processors in Gujarat and Maharashtra.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and motion programming expertise concentrates in automotive regions, forcing bagger OEMs to build captive training academies.
- CE marking documentation burden:EU machinery directive technical files require extensive risk assessment protocols that extend new product introduction timelines.
- Legacy PLC integration friction:Brownfield food plants with proprietary Allen-Bradley or Siemens architectures resist full-line automation upgrades due to communication protocol incompatibilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Form Fill Seal Baggers Market |
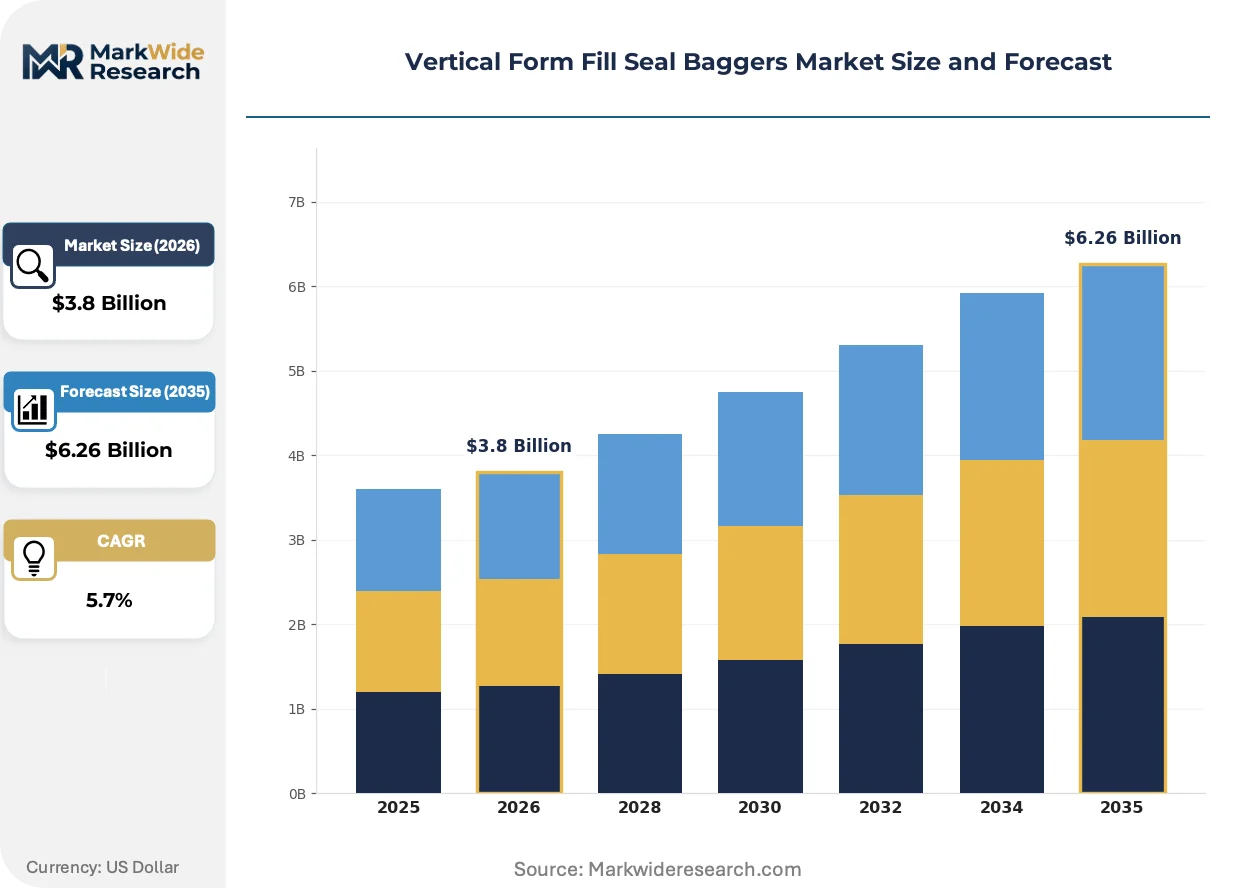
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Multi-lane, Specialty Material: Plastic, Paper, Foil, Composite End User: Food, Pharmaceuticals, Cosmetics, Chemicals Automation Level: Manual, Semi-automatic, Fully automatic, Robotic |
| Companies Covered | ProMach, Syntegon, Winpak Ltd., SACMI Imola SC, Ishida Co., Ltd., Matrix Packaging Machinery, Robert Bosch Packaging Technology GmbH, Triangle Package Machinery Company, Viking Masek Packaging Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Form Fill Seal Baggers Market Evolving Landscape
Real-time quality verification and modular robotics are reconfiguring how bagger systems interface with upstream and downstream equipment, shifting competitive advantage from mechanical speed to data integration depth.
Paper-based barrier films with bio-derived coatings are displacing conventional multilayer plastic structures in European retail-ready packaging. Snack and bakery manufacturers in France and the UK are piloting these materials to preempt extended producer responsibility fees. The displacement is compressing demand for legacy polyethylene-intensive sealing architectures.
EU Green Deal packaging waste regulations and F-Gas restrictions on fluorinated barrier layers are forcing film suppliers to reformulate oxygen transmission properties. Pharmaceutical bagger operators in Germany and Switzerland face accelerated validation cycles for alternative barrier materials. The regulatory pressure is concentrating procurement among film vendors with documented biodegradability certification.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized North American food co-packers. Monthly per-bag pricing bundles maintenance, film supply, and software updates, transferring operational risk to OEM balance sheets. The shift is most visible in California and Illinois contract packaging corridors serving direct-to-consumer snack brands.
Vertical Form Fill Seal Baggers Market Segmentation
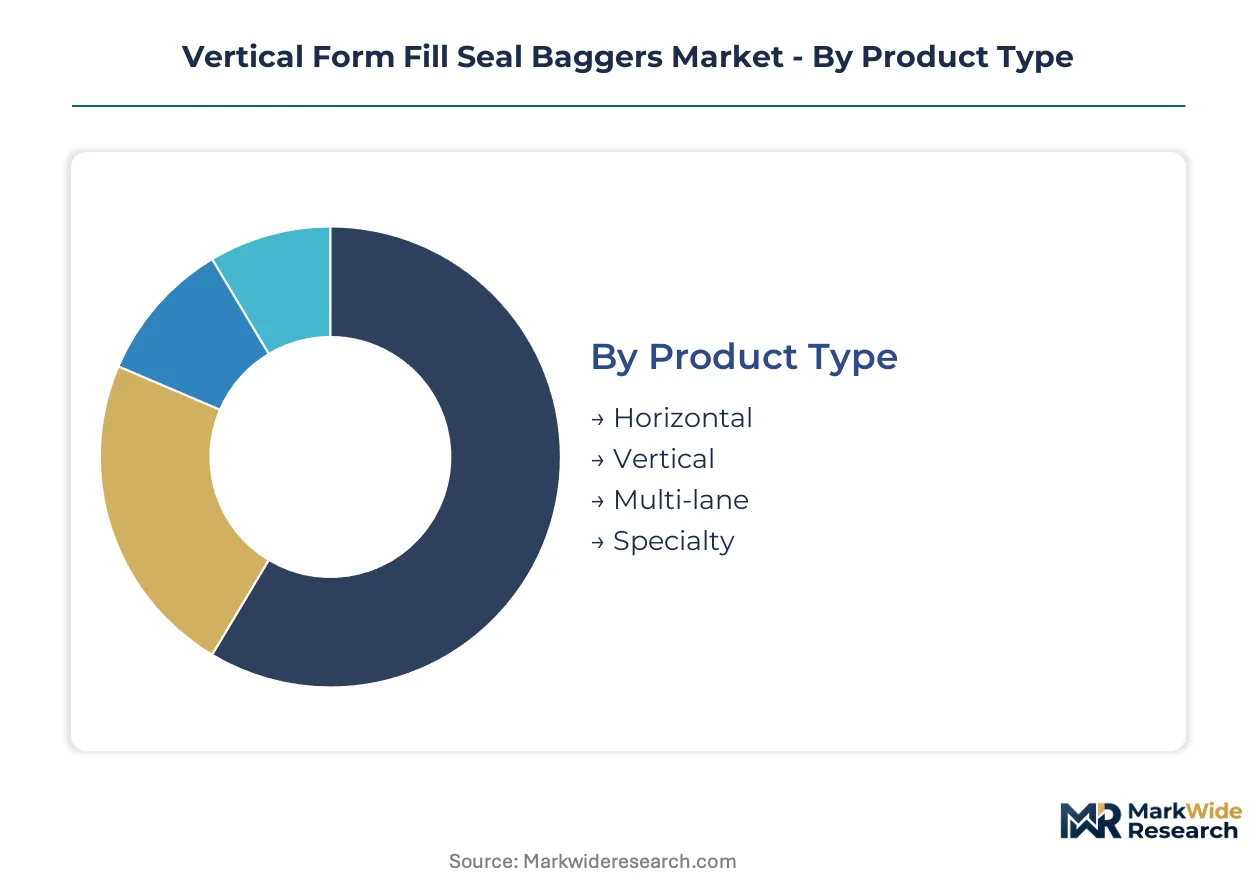
Vertical form fill seal bagger procurement patterns diverge sharply across automation tiers and material specifications. Buyers in high-volume food processing prioritize throughput-maximizing configurations, while pharmaceutical operators validate equipment against batch-traceability mandates.
Product Type:
Horizontal baggers dominate domestic North American snack production, whereas vertical and multi-lane systems anchor export-led machinery shipments to Asian food processors.
- Horizontal:Side-seal architectures accommodate wider film webs for frozen vegetable and bakery applications. Demand concentrates in California and Illinois contract packaging corridors serving direct-to-consumer brands, driven by SKU proliferation requiring rapid changeover capability.
- Vertical:Continuous-motion tube-forming designs achieve 200 bags per minute in granular and powder operations. German and Swiss pharmaceutical manufacturers specify these systems for EU machinery directive compliance, prioritizing servo-driven sealing validation.
- Multi-lane:Parallel forming stations multiply throughput for single-serve condiment and sauce portions without footprint expansion.
- Specialty:Custom collar geometries handle irregular products like fresh pasta or fragile baked goods.
Vertical configurations hold the largest share; momentum sits with multi-lane systems expanding most quickly in Asian noodle and seasoning markets.
Material:
Cost tier stratification separates commodity polyethylene buyers from premium composite film adopters seeking oxygen barrier performance.
- Plastic:Polyethylene and polypropylene films retain volume leadership due to tunable moisture barriers and heat-seal compatibility. North American frozen food processors specify these materials for FDA food safety modernization compliance, though resin cost volatility compresses maintenance contract margins.
- Composite:Multi-layer structures combining PET, aluminum oxide, and sealant polymers capture pharmaceutical and oxygen-sensitive food segments. German bagger operators face accelerated validation cycles under EU Green Deal packaging waste regulations, forcing procurement toward biodegradable-certified suppliers.
- Paper:Bio-derived coated barriers displace plastic in French and UK retail-ready snack packaging.
- Foil:Aluminum-laminate structures serve retort and extended shelf-life applications.
Plastic films retain the largest installed base; paper-based alternatives are gaining share fastest among European brands preempting extended producer responsibility fees.
End User:
Application-driven specifications separate sanitary-design food equipment from pharmaceutical-grade validation documentation.
- Food:Sanitary stainless-steel construction with washdown-rated electronics dominates meat, dairy, and produce operations. US processors integrate metal detection and vision systems to satisfy FDA preventive controls mandates, concentrating demand among automated line bundlers.
- Pharmaceuticals:cGMP-compliant servo architectures with batch-record software support drug powder and medical device packaging. Swiss and German manufacturers specify these systems for Swissmedic and EU machinery directive traceability requirements.
- Chemicals:Abrasive-material handling designs translate Italian ceramic-sector precision mechanics into mineral and fertilizer bagging.
- Cosmetics:Compact footprint machines serve high-changeover SKU environments for personal care sachets.
Food applications command the largest share; pharmaceutical-grade systems show the steepest expansion trajectory driven by serialization mandates.
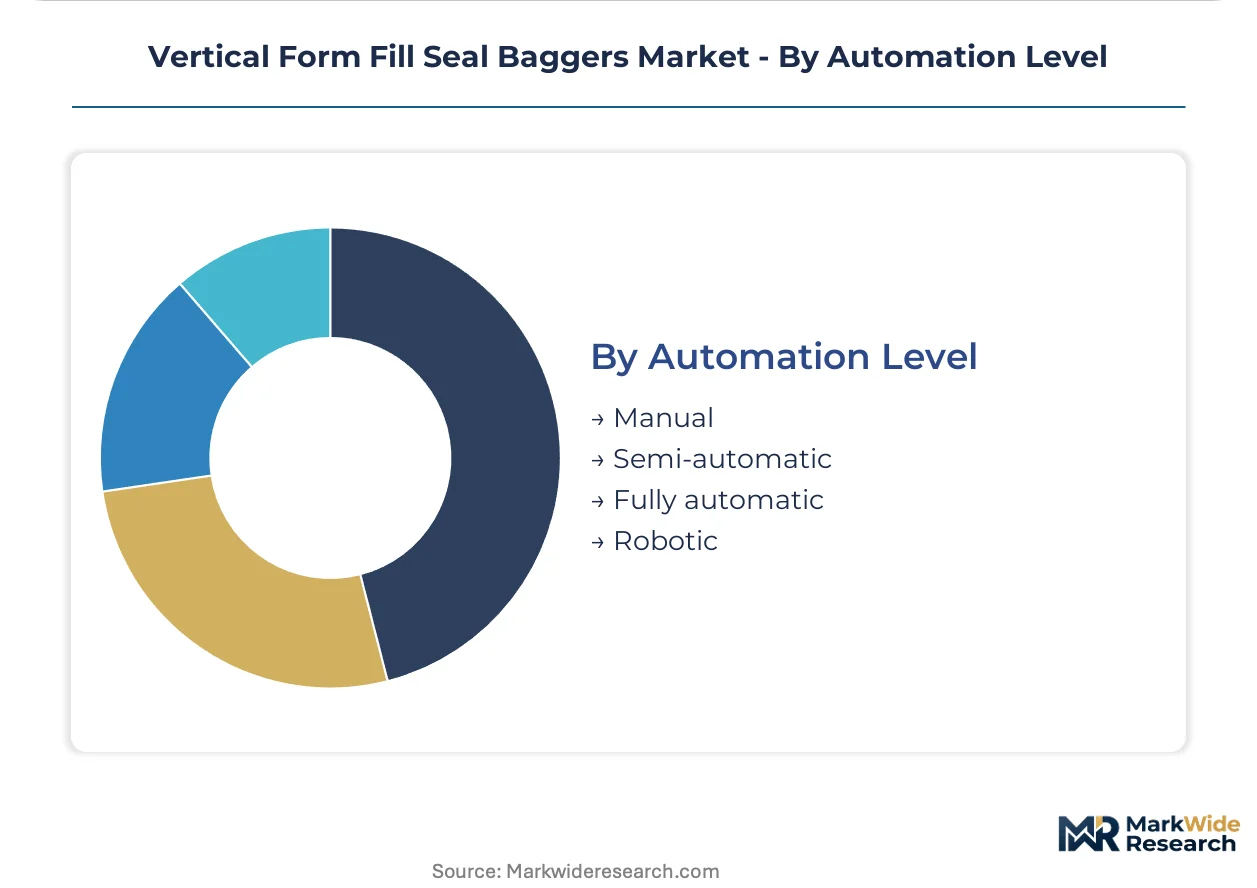
Automation Level:
Customer type bifurcation separates labor-cost-sensitive mid-tier co-packers from capital-intensive full-line automation integrators.
- Fully automatic:Continuous-motion platforms with integrated film splicing and automatic splice detection dominate high-volume operations. North American food manufacturers expand these lines to meet traceability mandates, consolidating procurement around vendors with upstream filling and downstream case-packing portfolios.
- Robotic:Articulated arm integration for changeover-intensive contract packaging represents the fastest-expanding configuration. Third-party logistics providers in the Netherlands and Belgium install these systems to serve SKU-proliferating snack brands.
- Semi-automatic:Operator-assisted loading suits low-volume specialty and pilot production.
- Manual:Hand-crank forming remains confined to artisanal and micro-batch operations.
Fully automatic systems hold the largest share; robotic integration is climbing the fastest among European contract packagers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among bagger buyers varies sharply by end-use concentration. Pharmaceutical processors in Switzerland and Germany absorb premium servo-electric architectures without volume elasticity, while North American frozen food co-packers negotiate aggressively on resin-linked maintenance contracts.
United States
FDA food safety modernization rules mandate automated baggers with integrated metal detection for preventive controls compliance. California and Illinois contract packaging corridors serve direct-to-consumer snack brands with SKU-proliferating robotic changeover systems. Equipment-as-a-service contracting displaces capital purchases among mid-sized co-packers in these states.
Germany
EU machinery directive validation requirements for batch traceability drive servo-driven sealing system specifications. Bosch packaging engineering clusters in Stuttgart and Waiblingen anchor precision machinery development for pharmaceutical-grade applications. CE marking documentation burdens extend new product introduction timelines for domestic OEMs.
Switzerland
Swissmedic serialization mandates accelerate pharmaceutical-grade bagger validation cycles. Basel and Zurich pharmaceutical manufacturing corridors specify cGMP-compliant servo architectures with batch-record software support. The country's precision mechanics heritage translates into demand for sub-micron sealing tolerance verification.
Italy
SACMI Imola SC applies ceramic-sector precision mechanics from Imola and Sassuolo tile production clusters to abrasive granular bagging. EU Green Deal packaging waste regulations force accelerated validation for alternative barrier materials among domestic operators. The Emilia-Romagna machinery belt concentrates high-speed mineral and fertilizer packaging expertise.
India
FSSAI packaging regulations and PLI scheme incentives accelerate automated bagger adoption among spice and grain processors. Gujarat and Maharashtra food processing modernization programs concentrate demand in Ahmedabad and Mumbai-Pune industrial corridors. Mid-tier domestic fabricators compete with European imports on price-sensitive grain bagging contracts.
Vertical Form Fill Seal Baggers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the vertical form fill seal baggers market. Full-line automation vendors bundle upstream filling and downstream case-packing equipment to capture consolidated procurement budgets from food and pharmaceutical buyers. Three archetypes dominate: integrated motion-control platform suppliers, ceramic-sector precision mechanics translators, and standalone electromechanical specialists. Competitive moves concentrate on portfolio breadth expansion through strategic partnerships and captive servo-drive capacity development to reduce dependency on German and Japanese component suppliers.
Among integrated full-line vendors, ProMach exemplifies the portfolio-breadth archetype through its multi-brand packaging machinery holdings. Syntegon occupies a position within the pharmaceutical-grade validation tier, reflecting German engineering density in servo-driven architectures. SACMI Imola SC anchors the ceramic-sector crossover specialization, representing Italian machinery cluster expertise translated into abrasive-material handling applications.
| Leading Market Players |
|---|
| ProMach |
| Syntegon |
| Winpak Ltd. |
| SACMI Imola SC |
| Ishida Co., Ltd. |
| Matrix Packaging Machinery |
| Robert Bosch Packaging Technology GmbH |
| Triangle Package Machinery Company |
| Viking Masek Packaging Technologies |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German servo-drive component plants establishes price floors for mid-tier bagger OEMs, compressing margin recovery while resin-linked maintenance contracts expose food processors to ethylene feedstock volatility. This scale asymmetry rewards integrated full-line vendors with captive electronics capacity and leaves standalone builders vulnerable to component lead-time premiums.
Pricing Analysis
After-sales service contracts and spare parts revenue drive lifetime value for bagger OEMs, with pharmaceutical-grade validation tiers commanding premium-mid-economy pricing differentiation based on CE marking documentation depth and servo calibration certification. Cost compression in standard automation tiers is intensifying because fixed-price maintenance agreements lock vendors into resin cost absorption, while North American frozen food co-packers exhibit highest price sensitivity and Swiss pharmaceutical manufacturers show least elasticity due to Swissmedic serialization mandates.
Supply Chain Analysis
Container availability constraints on Hamburg-Rotterdam trade lanes elevate inbound logistics costs for Japanese servo motor shipments, forcing mid-tier builders to carry safety stock. Component sourcing draws from Germany, Japan, and Italy for precision motion-control hardware, with film resin supply anchored in petrochemical clusters along the US Gulf Coast and Northwest Europe. Single-source vulnerability concentrates in German and Japanese servo drive manufacturers, while distribution runs through OEM-direct channels for pharmaceutical accounts and machinery distributor networks for food processing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA preventive controls and EU machinery directive validation protocols creates substantial switching costs for installed base customers, deepening defensive moats for incumbents with documented compliance architectures.
For Market Incumbents: Secure captive servo-drive capacity or strategic component partnerships to reduce dependency on German and Japanese suppliers, while consolidating procurement relationships through full-line automation bundling that encompasses upstream filling and downstream case-packing equipment. Emerging Asian fabricators in India threaten mid-tier price points, making certification investment in CE marking and FDA compliance documentation the critical lever for margin defense. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Italy or Germany enables market access without legacy documentation burdens, positioning entrants to capture contract packaging growth in the Netherlands and Belgium where SKU proliferation demands robotic changeover flexibility. White-space targets include equipment-as-a-service contracting among mid-sized North American co-packers and abrasive-material handling applications leveraging ceramic-sector precision mechanics expertise from Emilia-Romagna clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-line automation vendors with integrated aftermarket service platforms, suggesting superior cash-flow quality relative to standalone electromechanical specialists. Over the medium-term horizon, acquisition targets should emphasize pharmaceutical-grade validation capabilities and documented biodegradability-certified film partnerships, with the signal to watch being FSSAI enforcement acceleration in Gujarat and Maharashtra that could trigger consolidation among Indian domestic fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Capacity Expansion | Backward integration into motion-control electronics reduces lead-time vulnerability from German and Japanese suppliers. |
| Equipment-as-a-Service Launch | Per-bag pricing models transfer operational risk to OEM balance sheets among California and Illinois co-packers. |
| AI Vision System Integration | Real-time seal integrity verification satisfies pharmaceutical-grade validation protocols under EU machinery directives. |
| Bio-Derived Film Partnership | Biodegradability certification alignment preempts extended producer responsibility fees in France and UK retail channels. |
| Training Academy Development | Captive mechatronics technician programs address servo calibration expertise scarcity outside automotive regions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers at food and pharmaceutical processors, combined with secondary validation against SEC filings, customs and trade data, FDA 510(k) device listings, and EU machinery directive technical file repositories. Bottom-up unit shipment estimates triangulated against top-down capital expenditure patterns across automated packaging line investments.
The projection horizon spans multi-year modeling across automation level, end-use industry, material specification, and geographic regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic industrial production indices, with forecast inputs incorporating FSSAI enforcement timelines and EU Green Deal packaging waste regulation implementation trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained FDA preventive controls enforcement and stable ethylene-propylene feedstock pricing; material deviation in regulatory stringency or resin cost volatility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Lawn and Leaf Bags Market