
 Waste Wrap Film Market | 2026-2036
Waste Wrap Film Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Wrap Film Market Analytics
Multi-source procurement among waste management contractors is consolidating around regional film converters with captive resin supply. Trioplast anchors Nordic supply through backward integration into blown film extrusion. Berry Global sustains North American capacity across multiple resin platforms. Coveris Holdings competes on certified food-contact and industrial grades for European municipal tenders.
Waste wrap film denotes engineered polymeric sheeting, typically 20–150 microns in thickness, manufactured via cast or blown extrusion of polyethylene, PVC, or biodegradable copolymers, designed to encase waste bales for containment, transport, and odor suppression. Stretch film dominates industrial packaging applications where load unitization and puncture resistance determine specification. Biodegradable grades command premium positioning where composting infrastructure supports end-of-life breakdown, though polyethylene retains volume leadership in landfill and energy-recovery channels. Food processors and logistic companies drive specification divergence between breathable agricultural wraps and hermetically sealed municipal bale covers.
The EPA regulates landfill cover materials under Subtitle D criteria, while the EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that reshape converter material choices. Germany's national packaging regulator enforces dual-system compliance fees that incentivize thinner-gauge, higher-stretch formulations. Stakeholders must monitor evolving mechanical recycling contamination thresholds and resin certification schemes that will determine which film constructions retain market access across major waste management jurisdictions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's escalating material recovery targets are compressing converter margins while forcing rapid reformulation toward post-consumer recycled content, fundamentally restructuring resin sourcing strategies across municipal and industrial waste channels.
Growth Catalysts
- EPR scheme expansion:Germany's dual-system compliance fees reward thinner-gauge, higher-stretch formulations, accelerating specification upgrades across Rhine-Ruhr waste-to-energy facilities.
- Biodegradable copolymer maturation:Composting infrastructure investments in France and Benelux create viable end-of-life pathways for certified biodegradable wraps in organic waste streams.
- Bale stability engineering:Industrial waste contractors demand puncture-resistant containment films for hazardous material transport, pulling technical specifications toward multi-layer coextrusion.
Market Restraints
- LLDPE resin concentration:European ethylene supply tightness and naphtha feedstock volatility transmit directly to film converter cost structures with limited pass-through elasticity.
- Mechanical recycling contamination thresholds:EU-wide resin certification schemes exclude conventional multilayer constructions from circular economy subsidies, stranding legacy capacity.
- Alternative containment systems:Rigid IBC totes and bulk containers capture high-value industrial waste segments where hermetic sealing exceeds film performance limits.
Strategic Opportunities
- Odour-suppression chemistry:Ammonia and hydrogen sulfide barrier additives open premium positioning in food waste and agricultural manure segments where community proximity drives specification.
- Film-to-film closed loops:Extended producer responsibility mandates in France create collection infrastructure for post-industrial stretch film reprocessing into municipal bale covers.
- Digital inventory integration:RFID-embedded waste tracking films align with smart landfill and waste-to-plant digitalization investments in Nordic markets.
Industry Challenges
- Blown film extrusion expertise:The shift from cast to blown processes for high-stretch formulations requires retraining technician cohorts concentrated in legacy packaging regions.
- Food-contact certification timelines:EFSA migration testing protocols for recycled content films extend product development cycles by 18-24 months versus virgin resin equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Wrap Film Market |
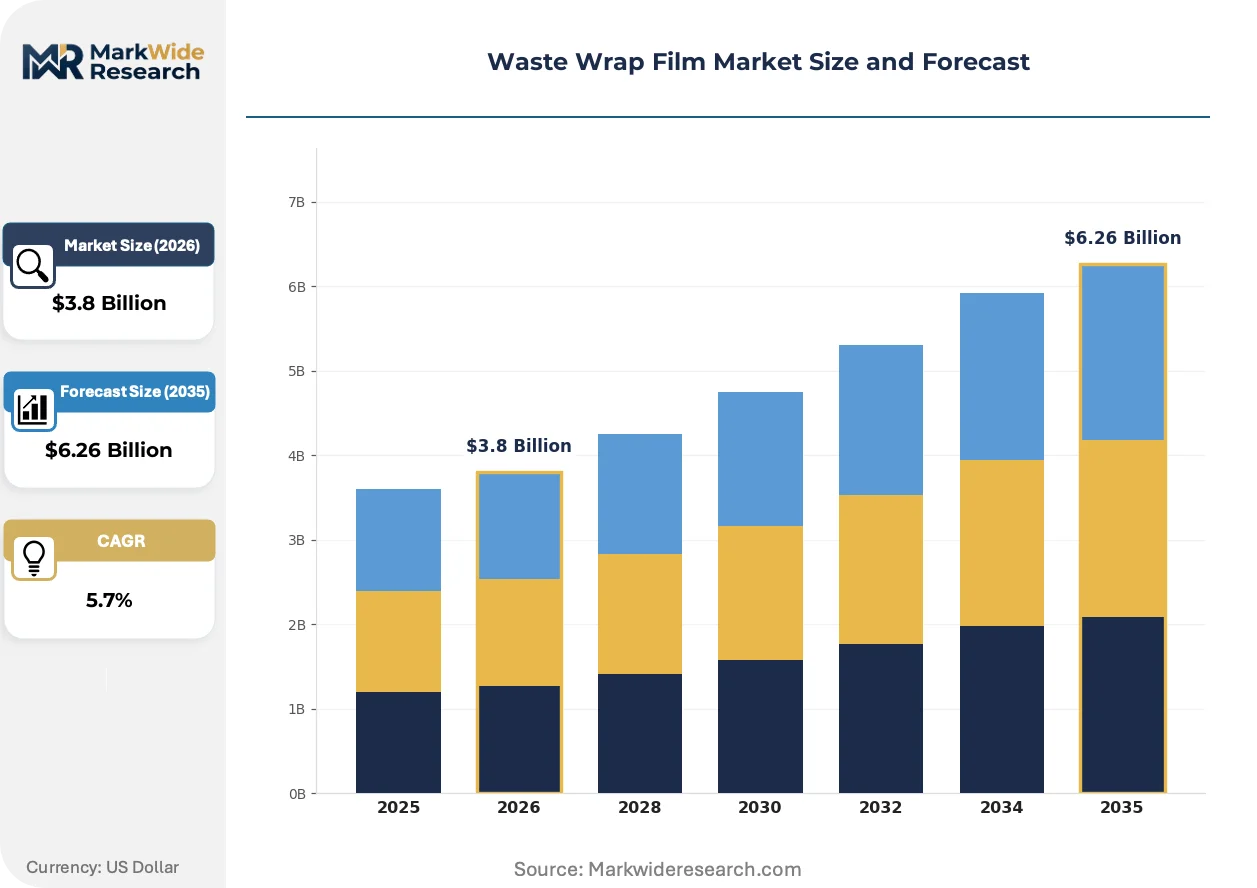
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, PVC, Biodegradable, Stretch Film Application: Industrial Packaging, Food Packaging, Medical, Retail Distribution Channel: Online Sales, Direct Sales, Retail Stores, Wholesalers End User: Manufacturers, Logistic Companies, Food Processors, Hospitals |
| Companies Covered | Trioplast, Coveris Holdings, Reo-Pack, Cross Wrap, BSK & Lakufol Kunststoffe, Berry Global, Polymax, AEP Industries, Intertape Polymer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Wrap Film Market Evolving Landscape
Active reformulation toward circular-compatible chemistries dominates converter R&D allocation, with mechanical recycling stream compatibility now treated as a design constraint rather than afterthought.
Metallocene-catalyzed polyethylene resins with enhanced puncture resistance and load retention properties are overtaking conventional Ziegler-Natta grades in heavy-duty industrial bale applications. German waste-to-energy contractors specify these materials for 5-layer coextruded constructions handling construction debris and shredded automotive waste. The technology is compressing gauge requirements by 15-20% while maintaining mechanical performance, directly reducing per-bale resin consumption.
REACH authorization requirements for phthalate plasticizers in PVC formulations are accelerating polyethylene displacement across European municipal tender specifications. The regulation forces converters serving French and Italian markets to abandon legacy calendered PVC lines in favor of LLDPE blown film alternatives. Food waste collection authorities in Paris and Milan now mandate non-PVC containment exclusively, reshaping supplier qualification criteria.
Consolidated procurement among pan-European waste management contractors is displacing fragmented municipal tendering. SUEZ, Veolia, and Remondis now negotiate multi-year film supply agreements directly with converters possessing captive resin supply and EPR scheme registration. The behavior concentrates volume with vertically integrated producers while marginalizing regional distributors, most visible in Benelux and German industrial corridor contracts where specification harmonization reduces supplier count by half.
Waste Wrap Film Market Segmentation
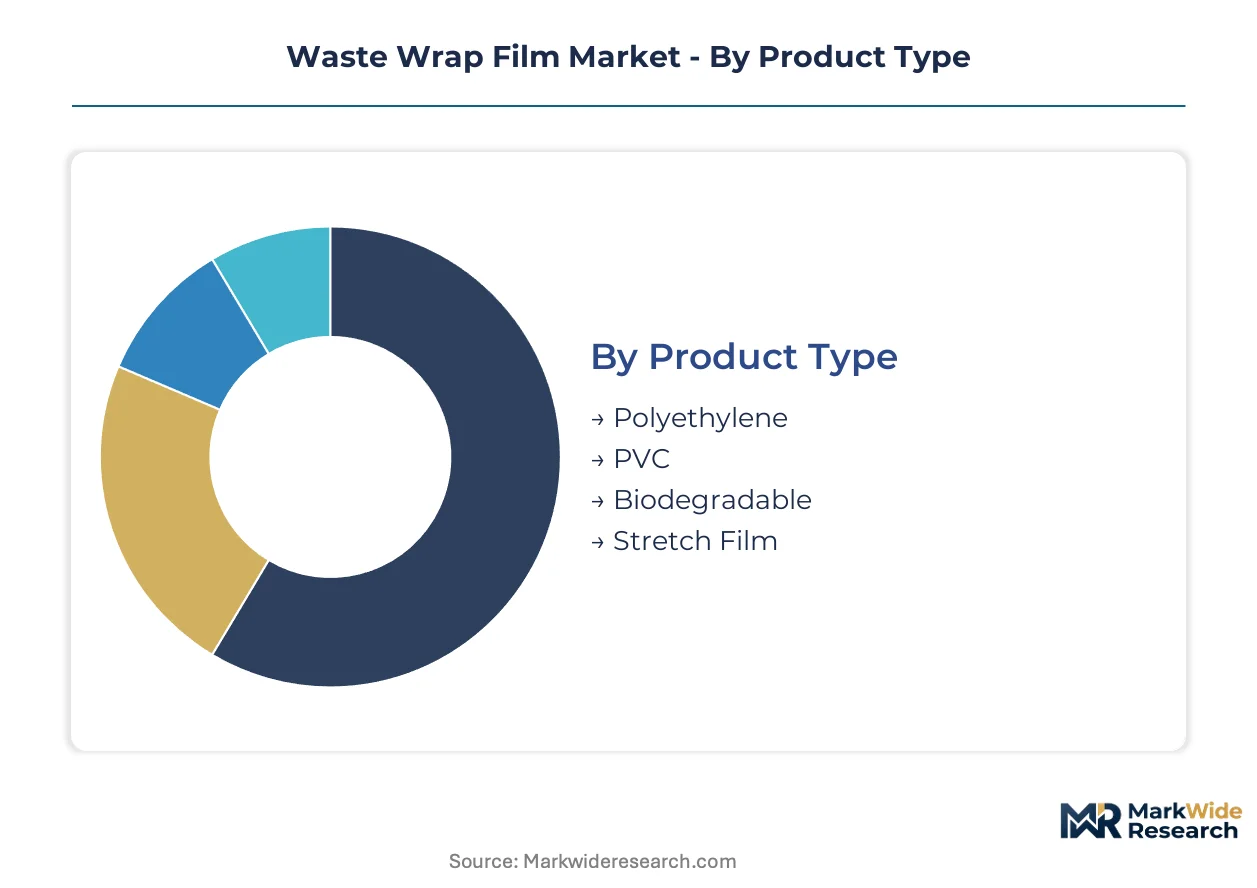
Waste wrap film segmentation reveals how regulatory pressure and end-use performance requirements split demand across material chemistries and application contexts. Specification divergence between municipal containment and industrial unitization creates distinct margin structures that converters must navigate simultaneously.
Product Type:
Certification burdens vary sharply across polymer platforms, with REACH authorization timelines for PVC plasticizers stretching 18-24 months versus streamlined polyethylene food-contact approvals under EFSA protocols.
- Polyethylene:LLDPE and mLLDPE formulations dominate heavy-duty bale containment through blown film extrusion. German waste-to-energy contractors in the Rhine-Ruhr corridor specify 5-layer coextruded constructions for construction debris handling, where puncture resistance and load retention determine tender qualification.
- Stretch Film:Cast and blown processes produce 20-50 micron gauges for pallet unitization and bale compression. Logistic operators in France favor thinner high-stretch formulations that reduce per-bale resin consumption while maintaining EPR scheme compliance.
- Biodegradable:Certified compostable copolymers serve organic waste streams in Benelux and French composting infrastructure, though limited thermal stability restricts adoption in energy-recovery channels.
- PVC:Calendered formulations face accelerating displacement as Paris and Milan municipal authorities mandate non-PVC containment for food waste collection, stranding legacy capacity dependent on phthalate plasticizer chemistries.
Polyethylene sits at the top of the volume ranking, with biodegradable grades climbing the fastest as composting infrastructure expands across Northern France.
Application:
Cost tier stratification separates specification-intensive municipal tenders from price-sensitive industrial procurement, with certification overhead driving 15-25% price premiums in regulated channels.
- Industrial Packaging:Hazardous material transport and shredded automotive waste handling demand multi-layer coextrusion with puncture resistance exceeding 500g dart drop values. Contractors specify metallocene-catalyzed resins for bale stability in long-haul logistics.
- Food Packaging:Hermetic sealing requirements for odor suppression in community-proximate facilities pull specification toward ammonia-barrier additives and EFSA-certified migration limits.
- Retail:Standard-gauge stretch film for pallet wrapping operates on thin margins with limited differentiation, serving distribution centers where cost-per-bale dominates procurement criteria.
- Medical:Sterile containment for hospital waste streams requires specialized formulations with limited overlap to mainstream converter capabilities, creating niche supply concentration.
Industrial packaging commands the largest revenue pool, with food packaging gaining share fastest as EPR scheme expansion tightens material recovery targets.
Distribution Channel:
Volume concentration favors direct supply relationships where converters integrate inventory management with waste contractor digitalization investments.
- Direct Sales:Multi-year agreements between SUEZ, Veolia, and vertically integrated producers eliminate distributor margins while enabling specification harmonization across pan-European operations.
- Wholesalers:Regional distributors serve fragmented municipal tendering in Southern Europe, though consolidation is compressing their role to logistics-only functions.
- Online Sales:Digital procurement platforms capture standard-gauge retail and light industrial demand, with limited penetration in certified food-contact segments requiring technical consultation.
- Retail Stores:Hardware and packaging supply outlets address emergency replenishment and small-volume users outside consolidated contractor networks.
Direct sales anchor volume leadership, with online channels expanding most quickly in standardized industrial grades.
End User:
Customer type determines specification complexity, with food processors and hospitals driving the steepest certification requirements and margin premiums.
- Logistic Companies:Pallet unitization and cross-dock operations prioritize load retention force and puncture resistance over regulatory certification, enabling thinner-gauge substitution.
- Food Processors:Organic waste containment for anaerobic digestion and composting demands odor-suppression chemistry and biodegradable certification where infrastructure supports end-of-life pathways.
- Manufacturers:Industrial waste streams from automotive and electronics production require hazardous material compatibility and multi-layer barrier performance.
- Hospitals:Clinical waste containment operates under strict national health regulations with limited supplier qualification, creating captive relationships with certified converters.
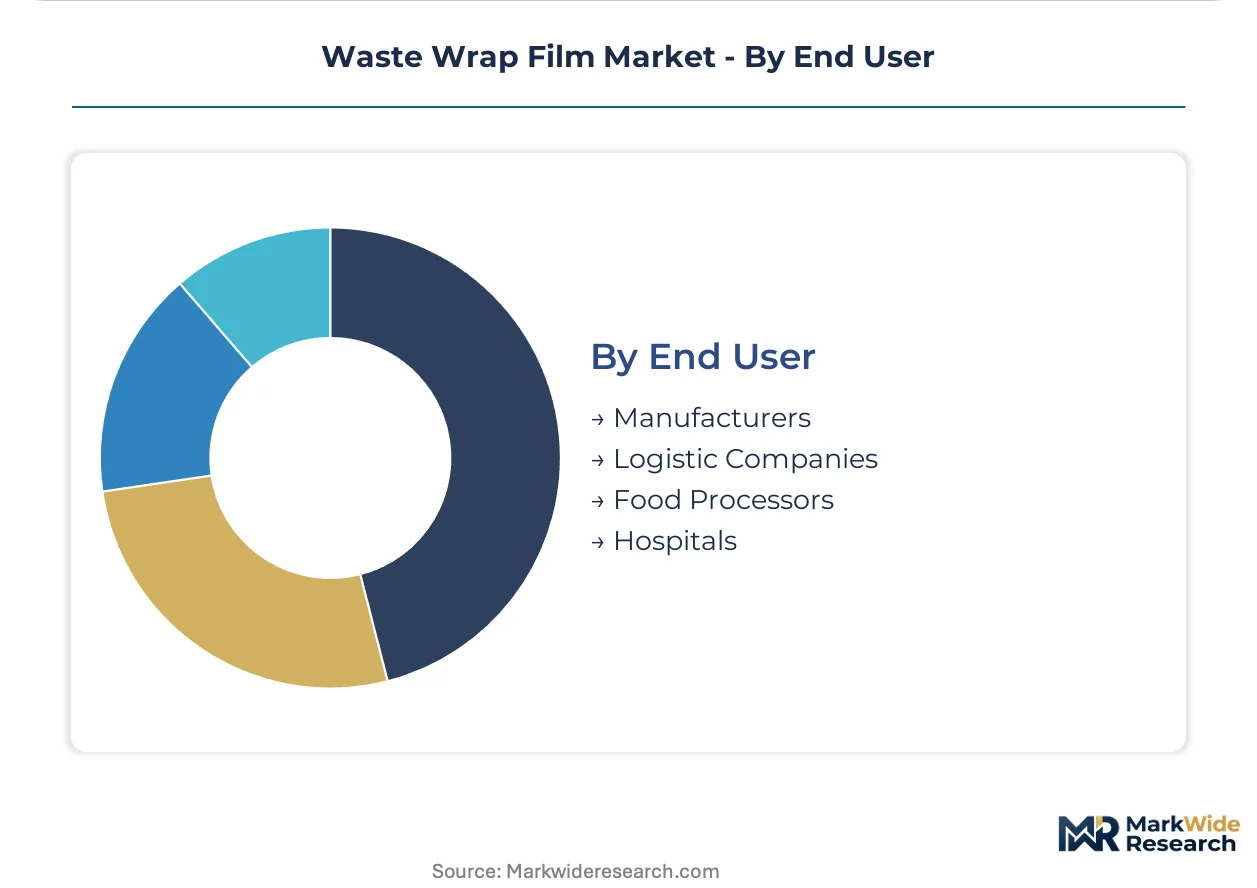
Logistic companies generate the highest volume throughput, with food processors showing the steepest expansion trajectory as separate organic waste collection mandates spread across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European demand for high-performance waste containment films, with waste-to-energy facilities driving specification upgrades across Germany's densest logistics network.
Germany
Municipal waste management authorities in North Rhine-Westphalia are expanding procurement of metallocene-catalyzed polyethylene films for landfill operations. The national packaging regulator enforces dual-system compliance fees that incentivize thinner-gauge, higher-stretch formulations. Contractors in the Rhine-Ruhr corridor specify 5-layer coextruded constructions for construction debris handling at energy-recovery facilities.
France
Food waste collection mandates in Paris and Lyon are accelerating demand for odor-suppression barrier films in community-proximate facilities. Extended producer responsibility schemes under the EU Packaging and Packaging Waste Directive reshape converter material choices toward post-consumer recycled content. Composting infrastructure investments in Northern France create viable end-of-life pathways for certified biodegradable wraps.
Italy
Milan municipal authorities now mandate non-PVC containment exclusively for organic waste streams, displacing legacy calendered formulations. REACH authorization requirements for phthalate plasticizers accelerate polyethylene substitution across tender specifications. Northern Italian industrial districts see specification harmonization as pan-European contractors consolidate procurement.
United States
The EPA regulates landfill cover materials under Subtitle D criteria, shaping resin selection for municipal containment applications. Industrial waste contractors in the Gulf Coast petrochemical corridor demand puncture-resistant films for hazardous material transport. Berry Global sustains North American capacity across multiple resin platforms to serve consolidated waste management networks.
Benelux
Composting infrastructure in the Netherlands and Belgium supports certified biodegradable copolymers for organic waste streams, though thermal stability limits energy-recovery adoption. SUEZ and Veolia negotiate multi-year film supply agreements directly with converters possessing EPR scheme registration. The region concentrates volume with vertically integrated producers while marginalizing regional distributors.
Waste Wrap Film Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and odor-suppression chemistry as differentiation vectors. The market structures around three archetypes: vertically integrated resin-to-film converters with captive supply chains, specialized regional fabricators serving municipal tender specifications, and diversified packaging conglomerates leveraging cross-sector extrusion expertise. Consolidated procurement among pan-European waste management contractors is compressing supplier counts by half in core industrial corridors. Capacity expansion and backward integration into blown film extrusion represent the dominant competitive moves as converters seek margin defense against resin volatility.
Among Nordic supply anchors, Trioplast exemplifies the integrated converter archetype through in-house production of blown film extrusion. Coveris Holdings occupies a position within the certified-grade specialist tier, competing on food-contact and industrial grades for European municipal tenders. Berry Global represents the diversified packaging conglomerate model, sustaining multi-platform capacity across distinct resin chemistries. These three entities collectively illustrate how geographic concentration, certification depth, and supply chain control define competitive positioning in procurement environments tightening material recovery targets.
| Leading Market Players |
|---|
| Trioplast |
| Coveris Holdings |
| Reo-Pack |
| Cross Wrap |
| BSK & Lakufol Kunststoffe |
| Berry Global |
| Polymax |
| AEP Industries |
| Intertape Polymer Group |
| Others |
Value Network & Pricing Analysis
Backward integration into blown film extrusion anchors both supply security and pricing power for converters serving Rhine-Ruhr waste-to-energy facilities. Trioplast's captive resin production and Berry Global's multi-platform capacity demonstrate how upstream control insulates margins against LLDPE volatility while enabling thinner-gauge premium formulations.
Pricing Analysis
LLDPE resin pass-through mechanics dominate converter cost structures, with European ethylene tightness and naphtha feedstock volatility transmitting directly to film pricing. Three-tier pricing structure across premium metallocene grades, standard Ziegler-Natta formulations, and economy cast films separates tender-qualified municipal supply from price-sensitive retail pallet wrap. Cost compression in standard grades is intensifying because consolidated procurement by SUEZ and Veolia extracts volume discounts. Retail distribution centers show highest price sensitivity, while food-contact certified grades for Paris municipal tenders command 15-25% premiums.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation domestic-content mandates reshape sourcing toward post-consumer recycled resin streams. Supply concentrates in Germany, France, and Benelux, where blown film extrusion capacity clusters around Rhine-Ruhr petrochemical infrastructure. Raw material dependencies rest on ethylene feedstock from naphtha crackers, metallocene catalyst supply, and post-industrial reprocessing streams. Single-source vulnerability runs through concentrated LLDPE resin production. Distribution runs through direct multi-year agreements between vertically integrated converters and pan-European waste management contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in waste wrap film hinges on metallocene-catalyzed premium tier migration and resin-efficient thinner-gauge formulations compressing per-bale material consumption.
For Market Incumbents: Deepen backward integration into post-consumer recycled resin reprocessing to defend against EPR scheme compliance cost escalation. Secure captive supply of food-contact certified recycled content to offset EFSA migration testing timeline disadvantages versus virgin resin competitors. Expand 5-layer coextrusion capacity in North Rhine-Westphalia to capture Rhine-Ruhr waste-to-energy specification upgrades.
For New Entrants and Emerging Players: Municipal distributors in Southern Europe represent the most penetrable channel partner type for bypassing consolidated direct procurement. Target odor-suppression additive formulations for French food waste collection mandates where infrastructure proximity drives premium specification. Pursue biodegradable certification for Benelux composting infrastructure as a qualification wedge against legacy polyethylene incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with municipal tender qualifications because pan-European contractor consolidation compresses supplier counts by half in core corridors. Five-to-ten year viability favors converters with EPR scheme registration and captive blown film expertise. Watch REACH authorization timelines for phthalate plasticizers as inflection signal accelerating PVC displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin | Captive post-consumer supply secures EPR compliance margins against virgin LLDPE volatility. |
| Metallocene Grade Capacity Expansion | Thinner-gauge 5-layer coextrusion captures Rhine-Ruhr waste-to-energy specification premiums. |
| Biodegradable Certification Investment | Compostable copolymer approval unlocks Northern France organic waste stream tenders. |
| Odor-Suppression Chemistry R&D | Ammonia barrier additives command 15-25% premiums in Paris community-proximate facilities. |
| Direct Contractor Supply Agreements | Multi-year SUEZ and Veolia contracts eliminate distributor margins and lock volume. |
Research Methodology
Direct dialogue with blown film extrusion plant managers, municipal waste procurement officers at SUEZ and Veolia, EPR scheme administrators, and technical R&D directors at resin suppliers grounded qualitative findings. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, EFSA migration testing protocols, German dual-system compliance fee schedules, and SEC disclosures from diversified packaging conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulated market sizing.
Segment-level value and volume trajectories across the analysis window reflect polymer platform splits, application-grade tiers, and regional regulatory clusters. Modeled dimensions encompass polyethylene resin type, stretch versus shrink process technology, municipal versus industrial end-use, and direct versus wholesale channel structure. CAGRs derive from elasticity-adjusted demand curves incorporating EPR scheme expansion timelines and REACH authorization phase-outs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mechanical recycling contamination threshold revisions and composting infrastructure buildout pace. Projections assume continued LLDPE resin concentration and consolidated procurement behavior among pan-European contractors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
North America Plastic Film Packaging Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Bopet Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Vinyl Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
PET Lidding Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Light Reflective Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Stretch Films Packs Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Poly Coated Paper Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
China Plastic Packaging Film Market