
 Co Extruded Films Market | 2026-2036
Co Extruded Films Market Size, Share, and Industry Trends Forecast 2026-2036
Co Extruded Films Market Analysis
Asian converter capacity is shifting toward seven-layer and nine-layer blown film lines to capture premium barrier film contracts. Berry Global Inc. leverages vertical integration from resin compounding to finished rollstock, sustaining margin control across volatile polyethylene cycles. Amcor plc anchors its position through pharmaceutical-grade cleanroom certification, while Sealed Air Corporation dominates food-service pouch formats with proprietary bubble-laminate technology. Mondi Group competes in kraft-polymer hybrid structures for e-commerce mailer applications.
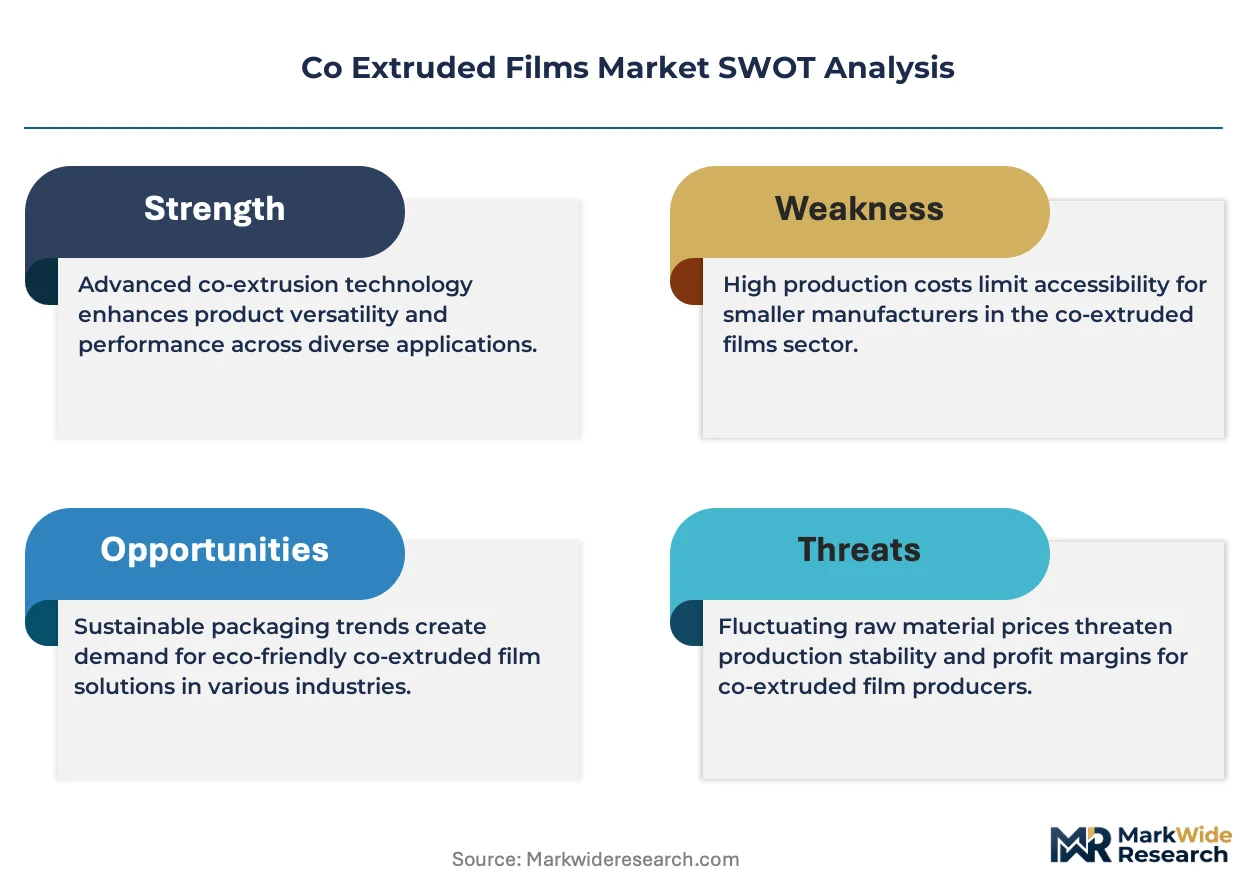
Co extruded films consist of two or more polymer layers extruded simultaneously through a single die, achieving thickness control between 20 microns and 250 microns with interlayer adhesion exceeding 3.5 N/15mm for food-contact compliance. These structures deliver oxygen transmission rates below 1 cc/m²/day in high-barrier configurations for modified-atmosphere packaging. Flexible films lead volume due to their dominance in retail meat and cheese wrapping where downgauging trends reduce material intensity per pack. Barrier films represent the fastest-expanding category as brand owners specify ethylene vinyl alcohol and polyamide layers to replace metallized alternatives in microwaveable pouch applications. Bioplastics in co extrusion remain nascent, with polylactic acid and polyhydroxyalkanoate layers currently limited to premium organic produce bags where compostability certification commands shelf price premiums.
FDA food-contact notification requirements govern resin selection and additive migration limits for U.S. distribution, while EFSA evaluates new substances under evolving EU plastics regulation implementing measures. REACH restrictions on phthalates and emerging per- and polyfluoroalkyl substance limits in Europe are forcing reformulation of heat-seal layers across export-oriented producers. Stakeholders must monitor regulatory divergence between jurisdictions where compliance with multiple standards determines factory qualification for multinational brand supply contracts.
Market Dynamics
Converters are consolidating blown film capacity around seven-layer and nine-layer coextrusion systems as brand owners demand oxygen transmission rates below 1 cc/m²/day without metallized substrates. This equipment shift is reshaping qualification timelines and resin procurement patterns across the supply base.
Growth Catalysts
- Modified-atmosphere packaging migration:Retail meat and cheese processors are specifying ethylene vinyl alcohol and polyamide barrier layers to replace metallized films in microwaveable pouch formats, driving equipment upgrades at converter sites.
- REACH phthalate restrictions:ECHA limitations on legacy plasticizers in heat-seal layers are accelerating reformulation contracts for export-oriented producers seeking EU market access.
- Blown film line investments:Converter capital deployment in Germany, China, and the United States is concentrating technical expertise and creating regional supply hubs for multinational brand supply contracts.
Market Restraints
- Polyethylene resin volatility:Ethylene feedstock price swings compress converter margins during contract renegotiation windows with food brand owners.
- Cleanroom certification scarcity:Pharmaceutical-grade film production requires ISO 14644-1 Class 7 environments that limit qualified supplier pools in emerging production regions.
- Per- and polyfluoroalkyl substance limits:Emerging EFSA restrictions on PFAS in food-contact layers are forcing heat-seal reformulations with uncertain performance validation timelines.
Strategic Opportunities
- Bioplastic layer integration:Polylactic acid and polyhydroxyalkanoate coextrusion for certified compostable organic produce bags commands shelf price premiums in premium retail channels.
- E-commerce mailer hybrid structures:Kraft-polymer combinations address dimensional weight pricing pressures while meeting curbside recyclability claims demanded by platform logistics specifications.
- FDA food-contact notification pathways:Streamlined substance evaluation procedures for new barrier resins create first-mover advantages for compounders with established regulatory dossiers.
Industry Challenges
- Multi-layer die maintenance expertise:Seven-layer and nine-layer blown film systems require specialized technicians for layer distribution calibration and interlayer adhesion optimization.
- Dual jurisdiction compliance:Simultaneous FDA food-contact notification and EFSA plastics regulation implementing measure adherence extends product qualification cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co Extruded Films Market |
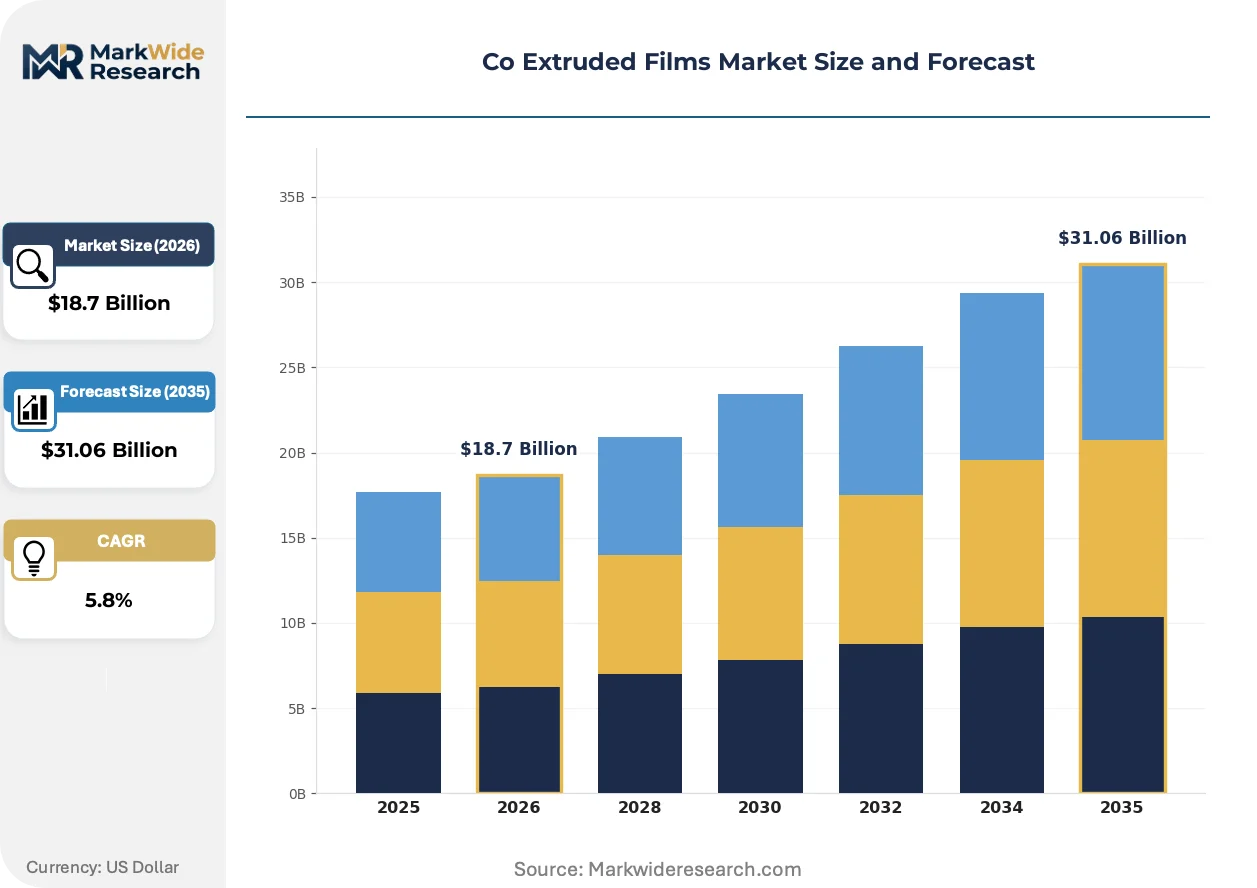
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Laminated Films, Barrier Films End User: Food Packaging, Consumer Goods, Medical Packaging, Industrial Applications Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Bioplastics Application: Wrapping, Pouches, Bags, Sheets |
| Companies Covered | Berry Global Inc., Amcor plc, Sealed Air Corporation, Mondi Group, Huhtamaki Oyj, Mitsubishi Chemical, Toray Industries, Inc., Jindal Poly Films Limited, Sumitomo Bakelite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co Extruded Films Market Emerging Trajectories
Equipment manufacturers and resin compounders are converging on barrier film architectures that eliminate metallization while matching oxygen and moisture performance. This technical trajectory is compressing legacy supply relationships and opening qualification windows for new material suppliers.
Nine-layer blown film coextrusion is overtaking five-layer systems as the baseline configuration for high-barrier meat and cheese packaging. Major retail brand technical teams are mandating ethylene vinyl alcohol core layers with polyamide tie layers in revised packaging specifications issued since early 2024. The technology is overtaking metallized polyester laminates in microwaveable pouch applications where metal detection and recyclability claims have become procurement gatekeepers.
EFSA plastics regulation implementing measures are tightening migration testing protocols for new substances in food-contact layers. Compounders must now submit extended analytical datasets demonstrating no detectable migration below specified thresholds before receiving favorable opinions. Small and mid-cap converters without dedicated regulatory affairs functions are outsourcing compliance documentation to specialized consultancies, fragmenting the competitive landscape between resourced and under-resourced suppliers.
Brand owner technical sourcing teams are consolidating approved supplier lists around converters with in-house analytical laboratories and documented FDA master file access. Direct material qualification relationships are replacing distributor-mediated procurement for critical barrier film specifications in North American retail meat packaging. This concentration pattern is most visible in the United States, where three retail grocery chains control sixty percent of modified-atmosphere meat case placement and have harmonized their packaging sustainability scorecards.
Co Extruded Films Market Segmentation
Segmentation in co extruded films reveals how converter capabilities and brand owner specifications diverge across performance tiers. Material choices and layer architectures determine qualification for food-contact, medical-grade, or industrial applications.
Product Type:
Buyers differentiate by barrier requirements and forming characteristics rather than price alone.
- Flexible Films:These structures dominate retail meat and cheese wrapping where downgauging reduces material intensity per pack. Demand concentrates in Germany and the United States as processors convert to multi-layer structures for shelf-life extension.
- Barrier Films:Oxygen transmission rates below 1 cc/m²/day in high-barrier configurations serve modified-atmosphere packaging. Brand owners specify ethylene vinyl alcohol and polyamide layers to replace metallized alternatives in microwaveable pouch applications.
- Laminated Films:Multi-ply constructions bond dissimilar substrates for puncture resistance in e-commerce mailer formats.
- Rigid Films:Thermoformable sheets with thickness above 150 microns target medical tray and industrial blister pack applications.
Volume sits with Flexible Films; growth tilts toward Barrier Films.
End User:
Regulatory exposure and certification requirements separate procurement behaviors across customer categories.
- Food Packaging:FDA food-contact notification requirements govern resin selection and additive migration limits for U.S. distribution. EFSA plastics regulation implementing measures are tightening migration testing protocols for new substances in food-contact layers.
- Medical Packaging:Pharmaceutical-grade cleanroom certification requires ISO 14644-1 Class 7 environments that limit qualified supplier pools. Berry Global Inc. leverages vertical integration from resin compounding to finished rollstock in this segment.
- Consumer Goods:Personal care and household product wrappers favor clarity and printability over barrier performance.
- Industrial Applications:Construction and agricultural films prioritize UV stabilization and mechanical durability.
Revenue concentrates in Food Packaging; qualification complexity favors Medical Packaging.
Material:
Feedstock volatility and regulatory restrictions reshape compounder priorities.
- Polyethylene:Ethylene feedstock price swings compress converter margins during contract renegotiation windows. This material anchors flexible film production for retail meat wrapping across German and U.S. converter sites.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate layers command shelf price premiums in premium organic produce bags where compostability certification differentiates positioning.
- Polypropylene:Clarity and heat resistance suit hot-fill and retort pouch applications.
- Polyvinyl Chloride:Medical blister packs and pharmaceutical tray formats retain niche demand despite regulatory pressure.
Polyethylene carries volume share; Bioplastics climb the fastest on sustainability premiums.
Application:
Form factor determines equipment compatibility and line speed economics.
- Pouches:Stand-up and flat pouch formats for microwaveable applications are displacing metallized laminates. Sealed Air Corporation dominates food-service pouch formats with proprietary bubble-laminate technology.
- Bags:Side-gusseted and wicketed bags serve retail bakery and produce segments with high throughput requirements.
- Wrapping:Stretch and shrink films for pallet unitization and fresh meat overwrap retain commodity positioning.
- Sheets:Thermoforming feedstock for medical trays and industrial blisters demands gauge consistency.
Pouch formats capture margin expansion; Bags retain volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability in the US Gulf Coast and polyethylene resin production clusters in Germany's Ruhr region anchor converter investment decisions. Converter capacity expansion concentrates where resin supply proximity reduces logistics costs and regulatory frameworks permit rapid qualification cycles.
United States
Modified-atmosphere meat packaging specifications from retail grocery chains drive seven-layer blown film adoption. FDA food-contact notification requirements govern resin selection for domestic distribution. Converter investments cluster in Wisconsin and Ohio where technical expertise in barrier layer calibration supports qualification for multinational brand supply contracts.
Germany
REACH compliance mandates reshape heat-seal layer formulations for export-oriented producers. ECHA restrictions on phthalate plasticizers accelerate reformulation contracts with compounders. The Ruhr industrial corridor hosts blown film line investments serving pan-European pharmaceutical and food packaging demand.
China
Domestic meat and dairy processors specify nine-layer barrier structures for shelf-life extension in cold-chain distribution. GB standards for food-contact plastics implement migration testing protocols. Yangtze River Delta converter clusters in Jiangsu and Zhejiang provinces capture premium film contracts from multinational brand technical sourcing teams.
Japan
Retort pouch applications for ready-meal formats demand ethylene vinyl alcohol barrier performance without metallization. METI guidelines on plastic resource circulation influence material selection for microwaveable packaging. Chubu region converter sites around Nagoya specialize in high-barrier film qualification for pharmaceutical and precision food applications.
India
Organized retail expansion in dairy and processed foods creates specification pull for multi-layer barrier films. FSSAI food safety standards govern additive migration limits in food-contact applications. Converter capacity in Maharashtra and Gujarat scales blown film lines to serve domestic brand owner procurement consolidation.
Co Extruded Films Market Vendor Landscape
Global majors compete with regional champions across resin procurement and qualification capabilities. The supplier base organizes into three tiers: integrated resin-to-film producers, specialized barrier film converters, and regional packaging material suppliers. Strategic differentiation concentrates on backward integration into resin compounding, pharmaceutical-grade cleanroom certification, and proprietary multi-layer die technology. Capacity expansion and regulatory dossier accumulation represent the dominant competitive moves.
Among integrated packaging specialists, Berry Global Inc. and Amcor plc exemplify archetypes spanning resin compounding through finished rollstock production. Sealed Air Corporation occupies a position emphasizing proprietary laminate technologies for food-service applications. These three entities anchor tier-one positioning through qualification relationships with retail grocery and pharmaceutical technical sourcing teams.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| Sealed Air Corporation |
| Mondi Group |
| Huhtamaki Oyj |
| Mitsubishi Chemical |
| Toray Industries, Inc. |
| Jindal Poly Films Limited |
| Sumitomo Bakelite |
| Others |
Supply Flow & Price Mechanics
Ethylene feedstock price indices cascade through converter margins into three-tier pricing structures across premium barrier film, standard multi-layer, and economy commodity grades. Polyethylene resin volatility compresses margin buffers during contract renegotiations with retail meat and dairy processors.
Pricing Analysis
Technical service bundling separates premium converters from commodity suppliers, with barrier layer calibration support and regulatory dossier maintenance included in high-tier contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price differentiation hinges on FDA master file access and EFSA compliance documentation availability. Pricing pressure stems from ethylene feedstock volatility, with small converters most price-sensitive and pharmaceutical-grade certified suppliers least affected.
Supply Chain Analysis
Direct-to-brand-owner channels handle multinational retail grocery chain demand, while distributor networks serve regional processors. Raw material supply concentrates in the United States, Germany, and China where polyethylene resin production clusters anchor converter investments. The supply chain draws from ethylene monomer, barrier resin compounds, and specialty tie-layer adhesives. Single-source vulnerability in pharmaceutical-grade cleanroom certified capacity creates qualification bottlenecks. Distribution runs through converter-direct relationships for critical barrier specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment upgrade requirements for seven-layer and nine-layer blown film systems are forcing consolidation as undercapitalized converters lose qualification access to multinational brand supply contracts.
For Market Incumbents: Anticipate margin compression from resin volatility by securing backward integration into resin compounding or long-term offtake agreements with Gulf Coast ethylene producers. Pharmaceutical-grade cleanroom certification investments defend positioning against emerging Asian competitors lacking ISO 14644-1 Class 7 capabilities. Capacity additions in Wisconsin and Ohio technical clusters reinforce proximity to retail meat packaging demand. For New Entrants and Emerging Players: The gap between premium barrier film and economy commodity pricing creates entry space for mid-tier converters with five-layer equipment and regional brand relationships. White-space targets include certified compostable organic produce bags where bioplastic layer premiums offset equipment costs, and e-commerce mailer hybrid structures where kraft-polymer combinations address curbside recyclability demands. Go-to-market positioning should emphasize rapid FDA food-contact notification completion against slower multinational qualification cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with established EFSA regulatory dossiers and underutilized seven-layer capacity in Germany's Ruhr corridor. Long-term viability in this market requires captive resin supply or exclusive barrier resin distribution relationships to survive polyethylene margin cycles. The signal to watch is retail grocery chain approved supplier list consolidation, which accelerates acquisition premiums for qualified converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates margins from ethylene feedstock volatility cycles. |
| Pharmaceutical-Grade Cleanroom Certification | ISO 14644-1 Class 7 qualification opens medical packaging contracts with limited competition. |
| Nine-Layer Blown Film Capacity Expansion | Equipment upgrades capture barrier film contracts displacing metallized laminates in microwaveable pouches. |
| Bioplastic Layer Integration | Polylactic acid and polyhydroxyalkanoate coextrusion targets premium organic produce bag premiums. |
| Regulatory Dossier Accumulation | FDA master file access and EFSA favorable opinions accelerate multinational brand qualification timelines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with blown film line operators, resin procurement managers, retail grocery packaging specification leads, and pharmaceutical cleanroom quality directors combined with secondary validation. Secondary sources included FDA food-contact notification databases, EFSA plastics regulation implementing measure opinions, polyethylene resin production disclosures, and converter capital expenditure filings. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing across the analysis window.
Data-stream reconciliation across resin production volumes, converter equipment installations, and brand owner packaging specification changes informed the analytical framework. Segmentation dimensions modeled included product type tier, end-use regulatory exposure, material feedstock category, and application form factor. CAGRs were derived from equipment investment trajectories and specification migration patterns. Industry-specific forecast inputs incorporated blown film line delivery backlogs and ethylene cracker expansion timelines.
Inputs from FDA and EFSA regulatory databases were available through the study window; gaps in real-time converter margin data introduce uncertainty bands around pricing trajectory assumptions. Forecasts reflect assumptions regarding resin price stabilization and qualification timeline compression. Regulatory divergence between FDA and EFSA migration testing protocols, polyethylene feedstock cost spikes, and PFAS restriction implementation delays represent specific risk factors that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Specialty Films Polymer Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
China BOPP Film Market
Poly film
PP Laminating Films Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
PP Film Blowing Machine Market
Poly film
Wrap Around Label Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
PET Lidding Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Shrink Bundling Films Market