
 Japan Flexible Plastic Packaging Market | 2026-2036
Japan Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Flexible Plastic Packaging Market Insights
Japanese converter capacity is shifting toward mono-material and recyclable film structures. Toyo Seikan Group Holdings Ltd anchors domestic supply through its integrated converting and filling equipment portfolio. Dai Nippon Printing Co., Ltd. leverages advanced gravure and digital printing capabilities to differentiate high-value pharmaceutical and food-grade packaging. Toppan Package Products Co., Ltd. specializes in barrier-coated films that compete on shelf-life extension for sensitive products.
Flexible plastic packaging comprises pliable polymer-based materials—typically polyethylene, polypropylene, or laminated films under 250 microns—that conform to contents during filling, transport, and storage, manufactured through blown film extrusion, cast extrusion, or adhesive lamination processes. Its primary purpose is to protect perishables from moisture, oxygen, and contamination while minimizing material weight versus rigid alternatives. Stand-up pouches capture premium margin pools in liquid and semi-solid food applications where convenience and retail differentiation command price premiums. Polyethylene dominates volume across bags and wraps for fresh produce and frozen goods, though laminated films retain structural importance in pharmaceutical blister and sachet formats where barrier performance is non-negotiable.
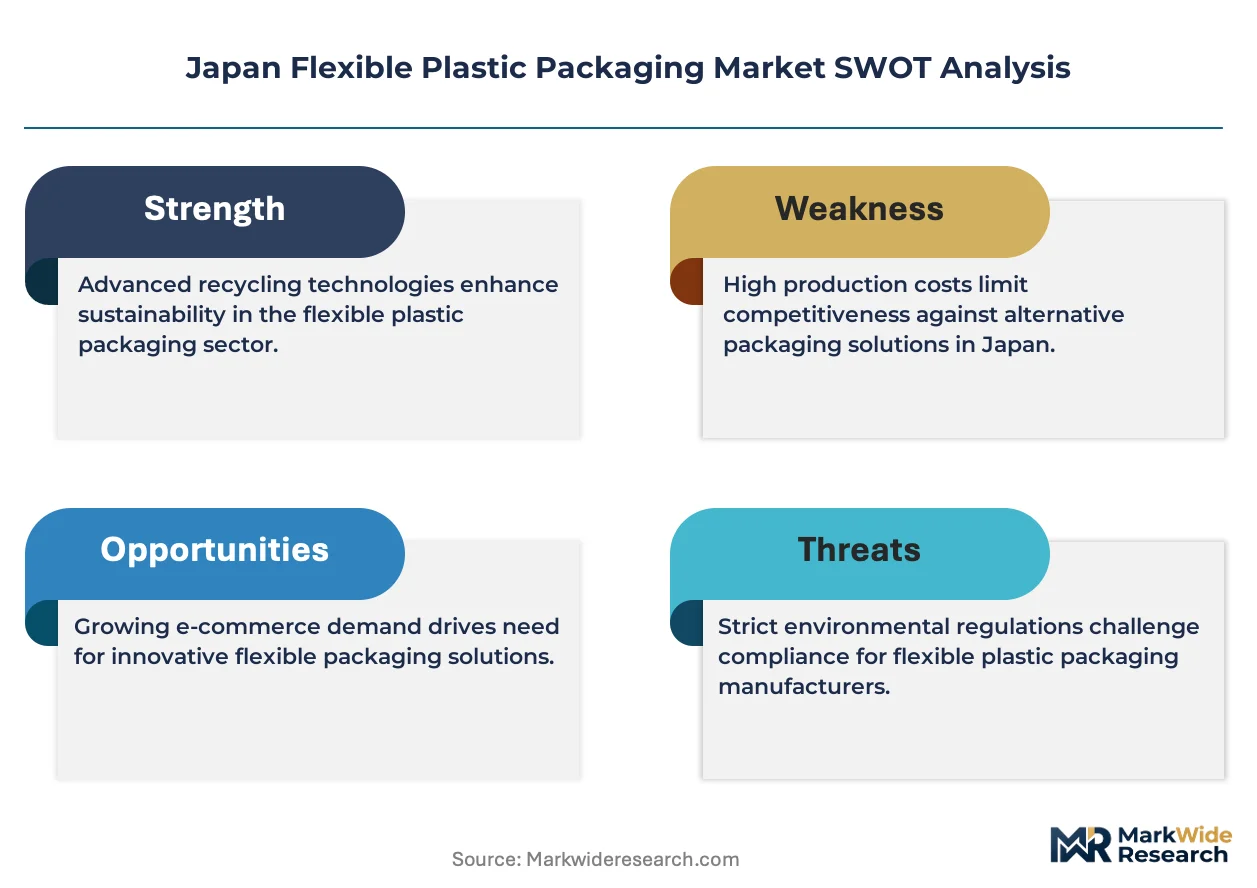
METI's resource circulation policies, JIS standards for recycled content, and the Ministry of the Environment's plastic smart campaign collectively mandate design-for-recycling protocols and extended producer responsibility frameworks. These regulations reshape procurement specifications, forcing converters to validate mono-material compatibility and recycled feedstock traceability. Stakeholders must monitor enforcement timelines and recycling infrastructure investments to align capacity commitments with compliance thresholds.
Market Dynamics
METI's resource circulation strategy is forcing Japanese converters to abandon multi-layer laminates in favor of mono-material designs that satisfy mechanical recycling infrastructure while maintaining barrier performance for oxygen-sensitive food and pharmaceuticals.
Growth Catalysts
- High-barrier pouch technology:Japanese food manufacturers are expanding adoption for ready-to-eat meals requiring extended shelf life without refrigeration. This format captures premium positioning in convenience store channels.
- METI plastic resource circulation strategy:Regulatory mandates for design-for-recycling protocols accelerate mono-material film development. Compliance deadlines create procurement urgency among brand owners.
- Kanto industrial corridor concentration:Converter capacity clusters around Tokyo and Yokohama enable just-in-time supply to beverage and processed food headquarters. Proximity reduces logistics friction for perishable formats.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin costs fluctuate with naphtha cracking economics. Margin compression hits commodity-grade bag converters hardest.
- Barrier performance trade-offs:Mono-material structures sacrifice oxygen transmission rates versus legacy aluminum-laminate formats. Pharmaceutical blister packs retain multi-layer dependence.
- Recycling infrastructure gaps:Japan's mechanical reprocessing capacity lags mono-material output growth. Collection-sorting economics in rural prefectures remain unfavorable.
Strategic Opportunities
- Chemical recycling integration:Pyrolysis partnerships with petrochemical complexes in Chiba and Kanagawa enable food-grade recycled polyethylene feedstock. This closes the loop for flexible film circularity.
- Pharmaceutical serialization mandates:PMDA track-and-trace requirements create demand for printed flexible packaging with integrated authentication features. High-margin sachet and strip formats benefit.
- Stand-up pouch penetration in sauces:Traditional glass and rigid plastic bottles face displacement in soy sauce and dressing categories. Shelf differentiation drives format switching.
Industry Challenges
- Gravure-to-digital press retraining:Converter workforces require reskilling for shorter-run pharmaceutical and premium food jobs. Talent scarcity extends commissioning timelines for new equipment.
- Recycled content verification protocols:JIS standards for post-consumer feedstock traceability demand laboratory documentation. Smaller converters lack in-house testing infrastructure.
- Legacy lamination asset stranding:Multi-layer adhesive and extrusion lines face accelerated depreciation. Capital recovery timelines compress as brand owners specify mono-material alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Flexible Plastic Packaging Market |
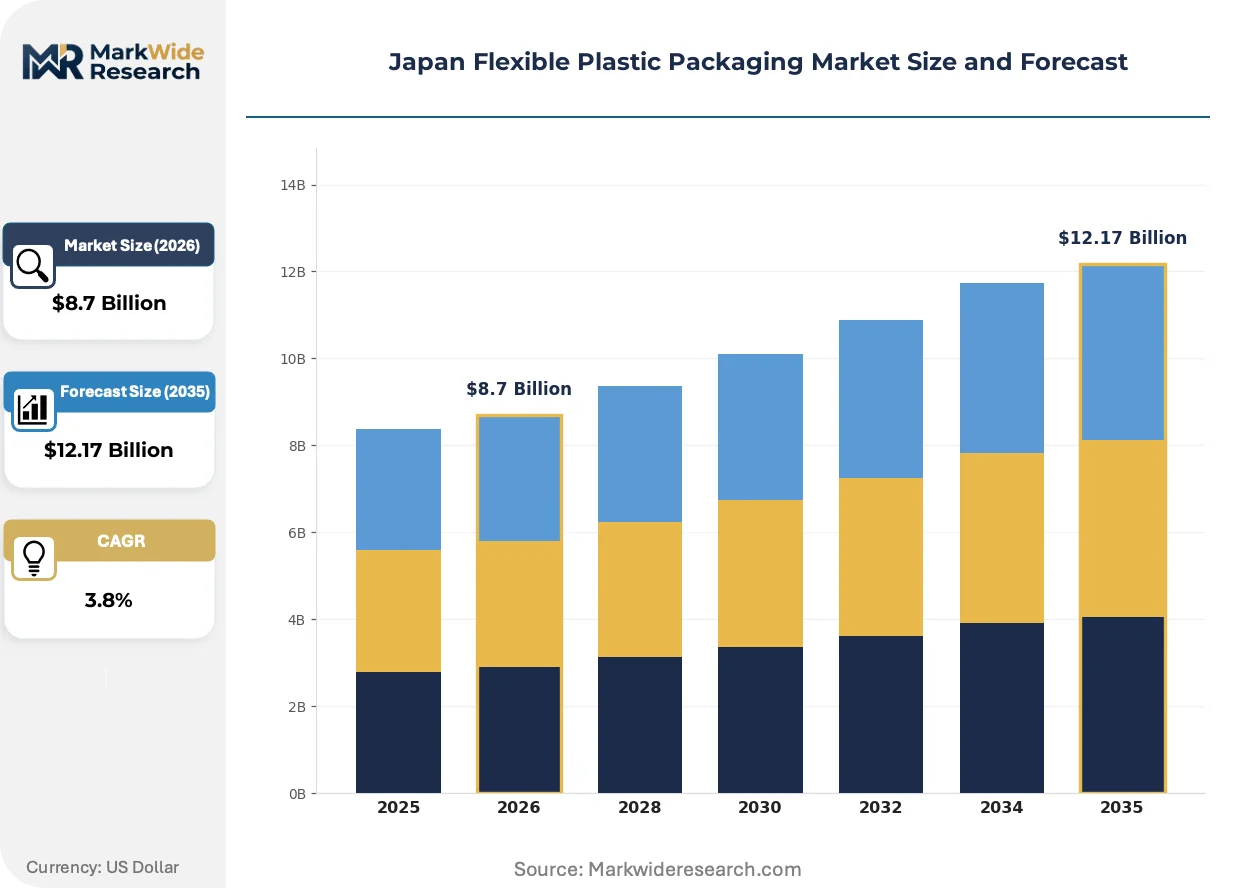
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Bags, Wraps, Films End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Laminated Films Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Amcor Plc, Sonoco Products Company, Toyo Seikan Group Holdings Ltd, Rengo Co., Ltd., Toppan Package Products Co., Ltd., Uflex Limited, Howa Sangyo Co., Ltd., Takigawa Corporation, Dai Nippon Printing Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Flexible Plastic Packaging Market Trends and Innovations
Active and intelligent packaging functionalities are migrating from premium pharmaceutical applications into mass-market food formats as Japanese retailers demand real-time shelf-life monitoring and consumer engagement features.
Barrier-coated polyethylene films are electrifying competitive positioning in retort pouch applications where aluminum foil laminates previously dominated. Major Japanese curry and stew manufacturers are validating silicon oxide and aluminum oxide coatings at commercial scale. This technology is electrifying margin structures by eliminating foil delamination risks while maintaining twelve-month shelf stability.
METI's 2030 plastic resource circulation targets are rewriting procurement specifications across the packaged goods sector. Brand owners must now validate mono-material compatibility and recycled content percentages under extended producer responsibility frameworks. Pharmaceutical and fresh-protein segments face the steepest compliance ramps as they balance barrier requirements against recyclability mandates.
Retailer consolidation around Aeon, Seven & I Holdings, and Lawson is compressing supplier negotiation cycles and unbundling historical packaging specification autonomy. National account procurement teams now mandate centralized sustainability scorecards that penalize multi-material formats. This concentration is most visible in Tokyo-Osaka corridor distribution where three retail groups control sixty percent of packaged food velocity.
Japan Flexible Plastic Packaging Market Segmentation
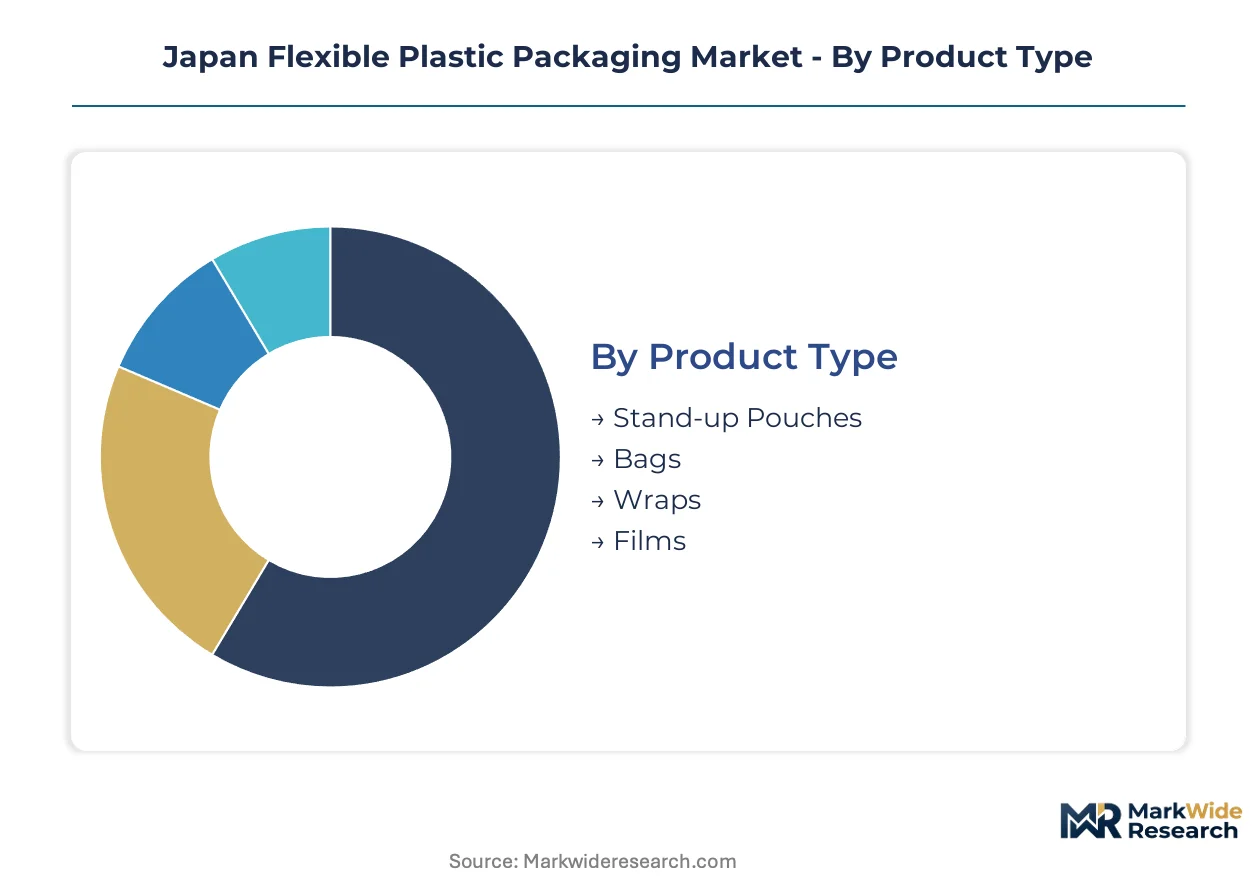
Segmentation in the Japan flexible plastic packaging market reveals how METI's circularity mandates and Kanto corridor logistics reshape procurement patterns across buyer tiers. Each dimension exposes distinct pressure points where compliance costs, barrier specifications, and channel economics collide.
Product Type:
Buyers in this category differentiate by shelf-life requirements and retail format compatibility, with convenience store channels demanding resealability and vertical display stability.
- Stand-up Pouches:Structured bottom gussets enable vertical merchandising in Lawson and Seven-Eleven refrigerated cases. Japanese curry and stew manufacturers validate silicon oxide-coated polyethylene variants at commercial scale in Yokohama processing facilities, replacing aluminum laminates to satisfy METI recyclability protocols.
- Bags:Side-sealed polyethylene formats dominate fresh produce and frozen seafood applications where cost-per-unit governs procurement. Kanto corridor converters supply just-in-time to Tsukiji Outer Market wholesalers and Aeon distribution centers, with mono-material specifications now mandatory for national account contracts.
- Wraps:Cling film for household and foodservice use concentrates in polyvinylidene chloride and polyethylene variants.
- Films:Rollstock for form-fill-seal equipment serves high-volume processed meat and snack lines in Gunma and Saitama prefectures.
Bags lead volumes today; stand-up pouches are gaining share fastest.
End Use Industry:
Application-specific barrier demands create divergent compliance timelines, with oxygen-sensitive segments facing steeper mono-material transitions.
- Food & Beverage:Retort pouches for ready-to-eat meals and high-barrier formats for fresh proteins command premium positioning. METI's extended producer responsibility deadlines force immediate specification rewrites for national brands supplying Aeon and Seven & I Holdings.
- Pharmaceuticals:Blister packs and sachets retain multi-layer aluminum laminates where PMDA stability requirements override recyclability mandates. Serialization track-and-trace rules create demand for printed flexible formats with integrated authentication in Osaka-Kobe pharmaceutical corridors.
- Personal Care:Single-use sachets for cosmetics and toiletries face pressure to eliminate non-recyclable laminates.
- Household Products:Refill pouches for detergents and cleaners concentrate in Chiba petrochemical corridor supply chains.
Food and beverage dominates absolute consumption; pharmaceuticals maintains the steepest margin structure.
Material:
Resin selection now pivots on mechanical recycling compatibility rather than legacy barrier performance hierarchies.
- Polyethylene:Linear low-density and high-density variants anchor mono-material film development for METI-compliant circulation. Chiba and Kanagawa pyrolysis partnerships enable food-grade recycled feedstock validation for major beverage converters.
- Polypropylene:Cast and oriented films serve retort and microwave applications where thermal resistance is non-negotiable. Biaxially oriented variants retain importance in snack packaging despite slower recycling infrastructure development in rural prefectures.
- Polyvinyl Chloride:Shrink film for secondary bundling faces substitution pressure from polyethylene alternatives.
- Laminated Films:Multi-layer adhesive and extrusion laminates face accelerated depreciation as brand owners specify mono-material alternatives.
Polyethylene leads volumes today; polypropylene is climbing the fastest as barrier coating technology matures.
Distribution Channel:
Channel concentration around three retail groups compresses supplier negotiation cycles and unifies sustainability scorecard requirements.
- Supermarkets:Aeon, Ito-Yokado, and Life Corporation centralize procurement through Tokyo-Osaka corridor distribution centers. National account teams mandate mono-material compatibility and recycled content verification under JIS standards, with compliance deadlines synchronized to METI enforcement timelines.
- Online Retail:Amazon Japan and Rakuten Ichiba demand damage-resistant formats for last-mile delivery, driving padded mailer and stand-up pouch specifications. E-commerce velocity concentrates in Kanto fulfillment centers where packaging automation favors standardized pouch dimensions.
- Specialty Stores:Premium food halls in Ginza and Nihonbashi prioritize aesthetic differentiation through gravure-printed films.
- Distributors:Regional wholesalers in Tohoku and Kyushu face collection-sorting economics that lag Kanto recycling infrastructure.
Supermarkets lead volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor converters locating in prefectures with advanced mechanical recycling infrastructure, where METI compliance costs prove lower than in regions lacking collection-sorting scale. Production gravitates toward industrial corridors offering proximity to both petrochemical feedstock and brand-owner headquarters.
Kanto/Tokyo
Ready-to-eat meal manufacturers in Saitama and Chiba prefectures drive high-barrier pouch demand for convenience store distribution. METI's extended producer responsibility deadlines force immediate specification rewrites for suppliers to Aeon and Seven & I Holdings. Converter capacity clusters in Kawasaki and Yokohama enable just-in-time delivery to beverage headquarters in central Tokyo.
Kansai/Osaka
Pharmaceutical blister pack demand concentrates in Osaka-Kobe corridors where PMDA serialization mandates create specialized printed flexible packaging requirements. The Ministry of the Environment's plastic smart campaign accelerates mono-material transitions for personal care sachets manufactured in Kyoto prefecture. Osaka-based converters supply strip formats with integrated authentication features to drug manufacturers.
Chubu/Nagoya
Automotive parts packaging and industrial film applications anchor demand in Aichi prefecture's manufacturing belt. Toyota Motor Corporation's supply chain specifications increasingly mandate recycled content verification under JIS standards. Nagoya converters serve tier-one suppliers with polyethylene formats that satisfy both impact resistance and recyclability protocols.
Kyushu
Seafood processing in Fukuoka and Saga prefectures generates polyethylene bag demand for frozen export markets. Rural collection-sorting economics lag Kanto infrastructure, creating compliance cost premiums for local converters. METI resource circulation targets force smaller operators to partner with regional recyclers or face procurement exclusion from national retail accounts.
Hokkaido
Dairy and agricultural packaging demand concentrates around Sapporo, with fresh produce exporters requiring modified atmosphere films for air shipment to Tokyo markets. Limited local recycling infrastructure elevates logistics costs for mono-material compliance. Brand owners specify prefabricated pouches from Honshu suppliers rather than invest in island-based converting capacity.
Japan Flexible Plastic Packaging Market Competitive Landscape
Kanto-based producers anchor the domestic supply tier; Osaka-area specialists hold pharmaceutical and premium food positioning. The market exhibits moderate consolidation with three integrated conglomerates controlling significant share alongside numerous mid-tier converters. Two strategic archetypes dominate: integrated packaging-to-filling conglomerates and specialized barrier-coating technology houses. Capacity expansion and mono-material R&D partnerships represent the prevailing competitive vectors as compliance deadlines approach.
Within the integrated conglomerate tier, Toyo Seikan Group Holdings Ltd and Dai Nippon Printing Co., Ltd. exemplify scale-driven positioning through combined converting and advanced printing capabilities. Toppan Package Products Co., Ltd. occupies a specialist position focused on barrier-coated film architectures. These three entities represent distinct strategic postures: full vertical integration, gravure-to-digital technology breadth, and coating-based barrier performance respectively.
| Leading Market Players |
|---|
| Amcor Plc |
| Sonoco Products Company |
| Toyo Seikan Group Holdings Ltd |
| Rengo Co., Ltd. |
| Toppan Package Products Co., Ltd. |
| Uflex Limited |
| Howa Sangyo Co., Ltd. |
| Takigawa Corporation |
| Dai Nippon Printing Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Convenience store chain procurement teams anchor pricing power in the Japan flexible plastic packaging market, compressing supplier margins through centralized national account contracts that mandate mono-material compliance under METI's extended producer responsibility framework.
Pricing Analysis
Retailer markup layers dominate the pricing architecture, with Aeon and Seven & I Holdings extracting sustainability compliance investments from converters through specification rewrites. Price differentiation rests on barrier coating certification tiers and JIS recycled content verification levels. Cost compression in commodity-grade polyethylene bags is intensifying because naphtha feedstock volatility transfers directly to resin contract renegotiations. Regional wholesalers in Kyushu and Hokkaido exhibit the highest price sensitivity due to logistics premiums, while pharmaceutical blister pack buyers accept premium positioning for PMDA stability compliance.
Supply Chain Analysis
METI's domestic-content mandates for recycled feedstock traceability are reshaping sourcing patterns toward Chiba and Kanagawa pyrolysis partnerships. Geographic supply concentration centers on Japan's Kanto industrial corridor, with South Korean resin suppliers and domestic petrochemical complexes in Chiba feeding converter networks. Raw material dependencies include naphtha-derived polyethylene, polypropylene homopolymer, and silicon oxide coating precursors. Single-source vulnerability runs through the Kanto mechanical recycling infrastructure bottleneck. Distribution runs through Tokyo-Osaka corridor consolidation centers serving Aeon, Seven & I Holdings, and Lawson national account contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan flexible plastic packaging market functions as a regulatory compounder where METI's 2030 plastic resource circulation targets force continuous compliance investment and procurement specification churn across the packaged goods sector.
For Market Incumbents: Cement barrier-coated film capabilities through silicon oxide and aluminum oxide deposition partnerships with Yokohama equipment suppliers. Accelerate mono-material R&D pipelines to preempt brand owner specification shifts. Vertical integration into Chiba pyrolysis feedstock partnerships secures JIS-compliant recycled content verification against emerging chemical recycling entrants.
For New Entrants and Emerging Players: E-commerce fulfillment packaging offers the most penetrable white-space target, with Amazon Japan and Rakuten Ichiba demanding damage-resistant formats for Kanto distribution centers. Specialty food halls in Ginza and Nihonbashi present premium gravure-printed film opportunities where aesthetic differentiation commands margin premiums. A direct-to-converter digital platform targeting regional Kyushu and Hokkaido operators bypasses established Tokyo-Osaka corridor gatekeepers.
For Investors and Strategic Acquirers: Integrated packaging-to-filling conglomerates are the most active acquirers in this space, consolidating mid-tier converters to capture METI compliance scale advantages. Long-term viability hinges on mono-material technology maturation and chemical recycling infrastructure buildout. Monitor PMDA serialization mandate enforcement timelines as the inflection indicator for pharmaceutical flexible packaging authentication feature demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Development | METI compliance deadlines force immediate specification rewrites for Aeon and Seven & I Holdings contracts. |
| Chemical Recycling Partnership | Pyrolysis integration with Chiba petrochemical complexes closes the loop for food-grade polyethylene circularity. |
| Barrier Coating Scale-Up | Silicon oxide deposition replaces aluminum laminates in Yokohama curry and stew processing facilities. |
| Digital Printing Conversion | Gravure-to-digital press migration captures shorter-run pharmaceutical serialization jobs in Osaka-Kobe corridors. |
| Recycled Content Verification | JIS laboratory documentation capabilities differentiate compliant converters from excluded regional operators. |
Research Methodology
Direct dialogue with converter operations managers, brand owner procurement leads, METI policy officers, and recycling facility engineers grounded the qualitative foundation. Secondary validation drew from customs trade data, METI plastic resource circulation strategy documents, JIS standard filings, and SEC disclosures from listed packaging conglomerates. Bottom-up capacity modeling triangulated against top-down consumption estimates from supermarket and convenience store distribution data.
Segment-level value outputs emerged from product type, end-use industry, material, and distribution channel dimensions across the projection horizon. CAGRs derived from historical resin price elasticity, converter capacity expansion announcements, and regulatory enforcement timeline assumptions. Industry-specific inputs included PMDA serialization mandate adoption curves and METI extended producer responsibility compliance cost modeling.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling scale-up would alter the outlook for mechanical recycling infrastructure investment. Forecasts incorporate assumptions about naphtha cracking economics and retailer consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Thailand Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Europe Flexible Plastic Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market