
 Easy Peel Film Packaging Market | 2026-2036
Easy Peel Film Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Easy Peel Film Packaging Market Analysis
Asset-light leasing models for coextrusion lines are narrowing the capital barrier for mid-sized converters entering easy peel film production. Berry Global Inc. leverages its North American blown film footprint to supply lidded tray formats for protein packs. Amcor sustains technology leadership through proprietary sealant formulations that perform across temperature extremes. Mondi Group anchors European supply with integrated kraft paper-film hybrid structures for recyclable ready-meal applications.
Easy peel film packaging denotes multi-layer polymeric lidding or pouch structures engineered with controlled cohesive or adhesive failure interfaces, typically incorporating sealant layers between 15 and 50 micrometers thick to achieve peel forces of 3–15 N/25mm for consumer-friendly opening. These structures serve primarily to preserve shelf stability while eliminating the need for cutting tools or excessive force at point of use. Polypropylene dominates value contribution due to its compatibility with retort and microwave applications where thermal resistance commands premium positioning. Coextrusion technology leads volume output by enabling precise layer distribution without solvent-based adhesives, aligning with regulatory pressure to reduce volatile organic compound emissions in converting operations.
The FDA regulates direct food-contact layers under 21 CFR 177.1520 for olefin polymers, while the EPA enforces Clean Air Act standards on solvent emissions from laminating processes that still persist in legacy pharmaceutical packaging lines. The EU F-Gas Regulation and REACH restrictions on perfluorinated substances are accelerating converter migration toward non-fluorinated easy peel sealants, particularly for medical and pharmaceutical applications where barrier integrity remains non-negotiable. Stakeholders must monitor evolving Extended Producer Responsibility frameworks across multiple jurisdictions, as fee structures based on recyclability certification will increasingly determine which material platforms and sealing technologies achieve scalable commercial adoption.
Market Dynamics
Mono-material polypropylene structures are displacing multi-layer laminates as the EU Packaging and Packaging Waste Regulation tightens recyclability mandates, forcing converters to reengineer sealant formulations without sacrificing peel performance.
Growth Catalysts
- Ready-to-eat meal proliferation:Food manufacturers in Germany and France are standardizing lidded tray specifications to reduce SKU complexity and accelerate line changeovers.
- REACH restrictions on perfluorinated substances:Medical device packagers are accelerating qualification of non-fluorinated easy peel sealants for sterile barrier applications.
- Retort compatibility requirements:Polypropylene sealant layers capable of withstanding 121°C sterilization cycles are capturing premium positioning in shelf-stable protein packaging.
Market Restraints
- Specialty resin supply concentration:Metallocene polypropylene feedstock for controlled peel force engineering concentrates among three global polymer suppliers.
- Coextrusion equipment lead times:Seven-layer blown film lines from European machinery builders currently quote 14-18 month delivery windows.
- Aluminum foil substitution ceiling:High-barrier pharmaceutical applications still require metalized structures that complicate mono-material recyclability claims.
Strategic Opportunities
- Paper-film hybrid structures:Kraft paper-laminated lidding films qualify for fiber recycling streams in France's extended producer responsibility framework.
- Home-compostable certification pathways:TUV Austria OK Compost HOME qualification is opening premium positioning for polylactic acid-based easy peel sealants in organic food segments.
- Direct-to-consumer meal kit channels:E-commerce fulfillment specifications for puncture-resistant, consumer-friendly opening are driving customized peel force engineering.
Industry Challenges
- Multi-layer coextrusion technician scarcity:Operating precision layer distribution systems requires skills that outpace vocational training program output in converting hubs.
- Migration testing protocol fragmentation:Divergent FDA 21 CFR 177.1520 and EU 10/2011 compliance timelines delay simultaneous North American and European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Easy Peel Film Packaging Market |
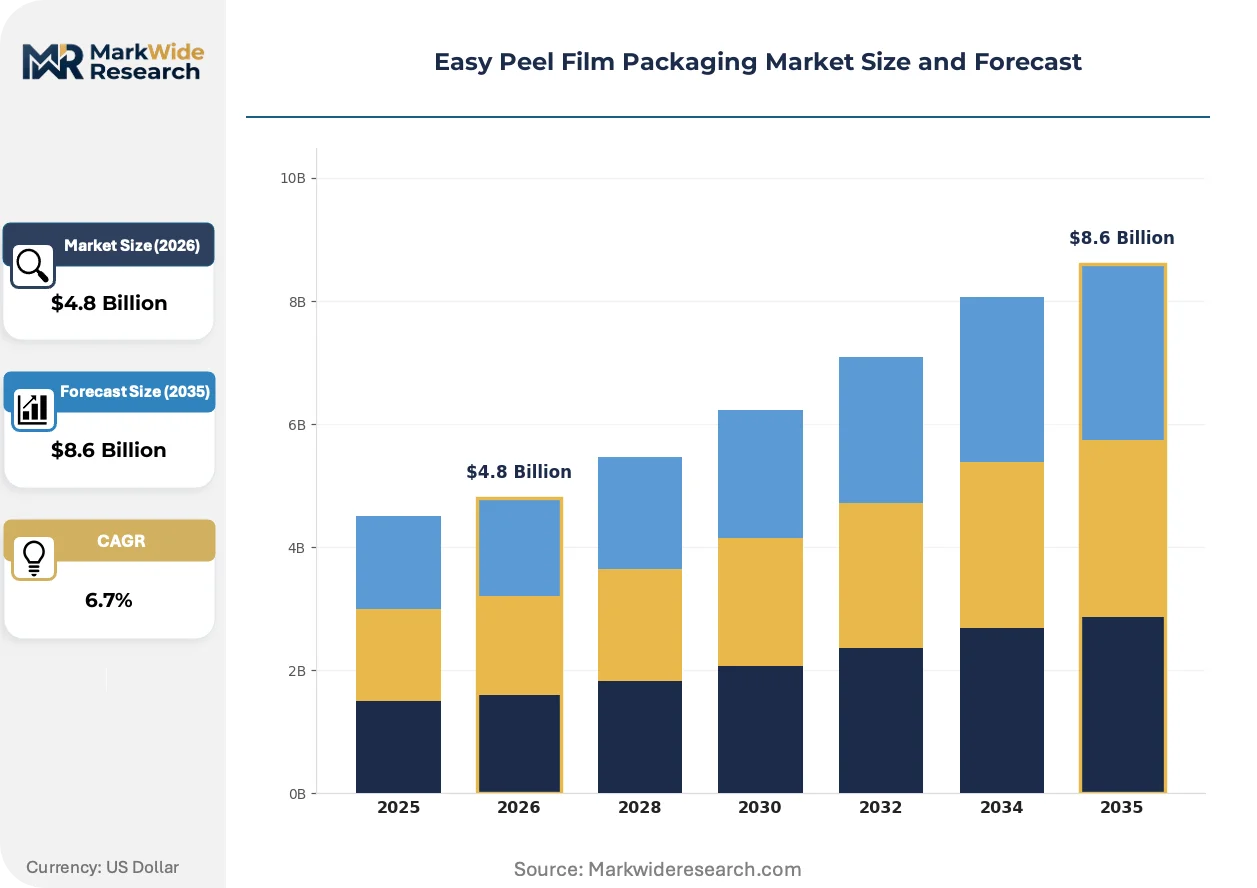
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, PVC, Others Application: Food Packaging, Medical Packaging, Cosmetic Packaging, Pharmaceutical Packaging End User: Food Manufacturers, Healthcare Providers, Cosmetics Brands, Retailers Technology: Coextrusion, Laminating, Printing, Sealing |
| Companies Covered | Berry Global Inc., Amcor, Sealed Air, Mondi Group, J-Film Corporation, Winpak Ltd., Toray Plastics (America), Inc., SÜDPACK, Coveris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Easy Peel Film Packaging Market Emerging Trajectories
Solvent-free adhesive lamination is compressing the technology stack while digital print integration enables batch-level customization without plate costs, fundamentally altering converter economics and brand owner procurement patterns.
Water-based acrylic pressure-sensitive adhesive coatings for easy peel lidding are rendering obsolete solvent-borne polyurethane systems in European converting operations. Mid-sized tray seal converters in the Netherlands and Belgium are completing line conversions within 18-month cycles. The shift eliminates volatile organic compound recovery equipment capex and aligns with EPA Clean Air Act enforcement patterns that now target mid-cap facilities.
The EU F-Gas Regulation phase-down schedule is forcing medical packaging engineers to redesign sterile barrier systems around non-fluorinated copolyester sealants. Barrier performance validation cycles have extended from 12 to 24 months for Class II device applications. German and Swiss pharmaceutical contract packagers are consolidating supplier panels to share qualification costs across multiple brand owners.
Brand owners are consolidating film specifications across regional manufacturing networks to capture volume pricing and simplify supplier audits. Single-source agreements now span 3-5 year terms with performance-based renewal clauses replacing annual spot negotiations. This concentration is most visible in North American dairy and fresh produce segments where private label consolidation has reduced distinct SKU counts by 30-40% at major retailers.
Easy Peel Film Packaging Market Segmentation
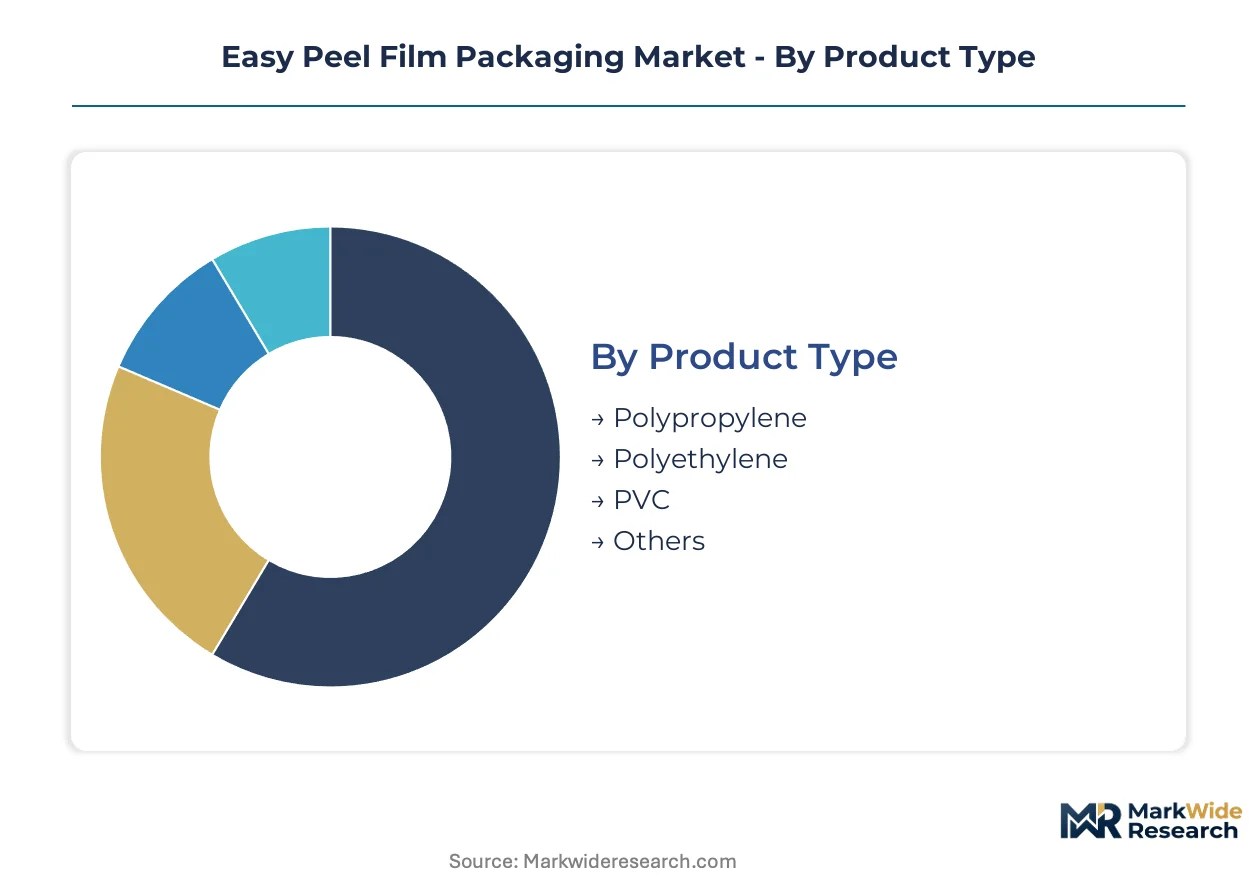
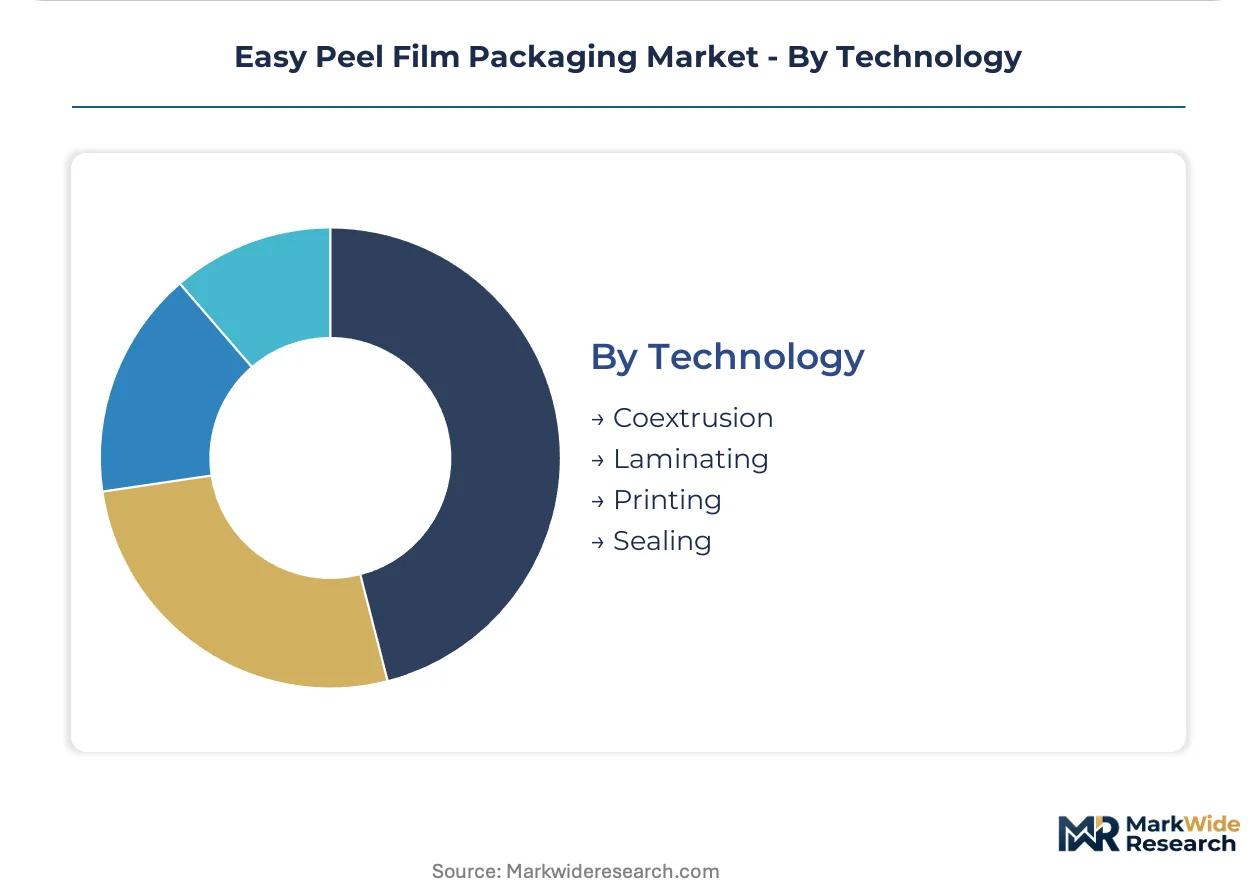
Easy peel film packaging segmentation reveals how material chemistry, application requirements, and converting technology intersect to determine commercial viability. Understanding these dimensions exposes where converters can capture premium positioning versus commodity competition.
Product Type:
Material cost tier and thermal performance requirements dictate substrate selection across end-use applications.
- Polypropylene:Multi-layer cast and blown structures dominate retort and microwave applications where 121°C thermal resistance commands specification. German ready-meal manufacturers and US protein packagers standardize on metallocene-grade sealant layers for controlled 3–15 N/25mm peel force engineering.
- Polyethylene:Linear low-density formulations serve chilled dairy and fresh produce lidding where puncture resistance and cold-temperature seal integrity matter more than thermal endurance. French retail consolidation drives specification standardization across private-label dairy networks.
- PVC:Remains entrenched in legacy pharmaceutical blister formats where European medical device regulations permit continued use; REACH migration testing requirements complicate new qualification.
- Others:Polylactic acid and bio-based alternatives qualify for TUV Austria OK Compost HOME certification in organic food segments; polystyrene persists in Japanese convenience store bento tray applications.
Polypropylene commands the established base. The steepest expansion runs through bio-based alternatives as compostability certification opens premium positioning.
Application:
End-use performance specifications determine barrier requirements, sterilization compatibility, and regulatory compliance burden.
- Food Packaging:Lidded tray formats for ready-to-eat meals and single-serve dairy represent volume concentration. EU Packaging and Packaging Waste Regulation recyclability mandates push converters toward mono-material polypropylene structures that qualify for existing mechanical recycling streams.
- Medical Packaging:Sterile barrier systems for Class II devices require 24-month validation cycles under EU MDR. Non-fluorinated copolyester sealants are displacing legacy fluoropolymer coatings as F-Gas Regulation phase-down accelerates.
- Cosmetic Packaging:Premium skincare sachets and sheet mask pouches prioritize aesthetic haptics and tear initiation control; Korean and Japanese beauty brands drive specification innovation.
- Pharmaceutical Packaging:Child-resistant and senior-friendly dual requirements complicate peel force engineering; aluminum foil laminates persist where oxygen barrier below 0.1 cc/m²/day remains non-negotiable.
Food packaging anchors volume concentration. Medical packaging shows the steepest margin expansion as qualification barriers limit supplier pool.
End User:
Customer procurement sophistication and volume scale determine converter engagement models and contract structures.
- Food Manufacturers:Multinational ready-meal producers in Germany and France consolidate film specifications across regional networks to capture three-to-five-year volume pricing agreements.
- Healthcare Providers:Hospital and clinic networks prioritize sterile barrier integrity and supply assurance over unit cost; Swiss and German contract packagers consolidate supplier panels to share qualification costs.
- Cosmetics Brands:Premium positioning demands batch-level customization enabled by digital print integration without plate costs.
- Retailers:Private-label consolidation at major North American and European retailers has reduced distinct SKU counts by 30–40%, favoring standardized, multi-application film platforms.
Food manufacturers drive standardization pressure. Healthcare providers offer the most durable contract terms once qualification is achieved.
Technology:
Converting process selection determines capital intensity, regulatory compliance burden, and layer precision capabilities.
- Coextrusion:Seven-layer blown film lines enable precise sealant distribution without solvent-based adhesives, aligning with EPA Clean Air Act enforcement on volatile organic compound emissions. European machinery builders currently quote 14–18 month delivery windows.
- Laminating:Solvent-free adhesive systems are compressing the technology stack in European converting operations; water-based acrylic pressure-sensitive coatings displace solvent-borne polyurethane in Netherlands and Belgium tray seal lines.
- Printing:Digital integration enables batch-level customization and variable data printing for traceability requirements; gravure persists in high-volume food applications.
- Sealing:Heat-seal bar and ultrasonic welding systems for tray sealing lines determine peel force consistency; precision control within ±0.5 N/25mm separates premium from commodity supply.
Coextrusion holds the installed capacity base. Digital print integration is climbing fastest as brand owners demand customization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation is tightening recyclability mandates across member states. Germany anchors European specification standardization for mono-material polypropylene structures.
Germany
Food retail consolidation and sustainability mandates favor standardized, recyclable film specifications. The EU Packaging and Packaging Waste Regulation drives converter migration toward mono-material structures. The Rhine-Ruhr industrial corridor hosts major coextrusion capacity serving ready-meal manufacturers.
United States
Protein packagers and dairy processors standardize lidded tray formats for retail distribution. FDA 21 CFR 177.1520 governs direct food-contact olefin polymer layers. The Midwest converting belt around Chicago supplies blown film structures for national retail networks.
France
Private-label consolidation at major retailers reduces distinct SKU counts by 30-40%. Extended producer responsibility frameworks favor kraft paper-laminated lidding films qualifying for fiber recycling streams. The Lyon-Toulouse corridor concentrates tray seal converting operations serving organic food segments.
Japan
Convenience store bento tray applications sustain polystyrene-based easy peel demand alongside emerging mono-material alternatives. METI guidelines on plastic resource circulation push converters toward recyclable structures. The Kanto region around Tokyo hosts precision film converting for beauty and food applications.
Netherlands
Mid-sized tray seal converters complete water-based acrylic coating line conversions within 18-month cycles. EPA Clean Air Act enforcement patterns on volatile organic compounds accelerate solvent-free system adoption. The Eindhoven-Rotterdam logistics corridor enables rapid distribution across Benelux retail networks.
Easy Peel Film Packaging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure concentrates around integrated film converters with captive resin relationships and independent specialists with formulation expertise. Three archetypes dominate: multinational packaging conglomerates with global converting footprints, regional film specialists with deep customer relationships, and machinery-integrated converters with asset-light leasing models. Competitive moves center on coextrusion capacity expansion and strategic partnerships for sealant formulation access.
Within the multinational tier, Berry Global Inc. and Amcor occupy positions defined by geographic coverage and technology breadth. Berry Global Inc. exemplifies the North American blown film specialist archetype with protein pack supply relationships. Amcor represents the formulation-integrated global player with proprietary sealant development capabilities. Mondi Group anchors the European kraft paper-film hybrid segment with integrated structures for ready-meal recyclability claims.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor |
| Sealed Air |
| Mondi Group |
| J-Film Corporation |
| Winpak Ltd. |
| Toray Plastics (America), Inc. |
| SÜDPACK |
| Coveris |
| Others |
Supply Flow & Price Mechanics
Blown film overcapacity in the US Midwest is compressing spot pricing for commodity-grade polyethylene lidding while tightening supply for metallocene-grade polypropylene sealants. This utilization divergence rewards converters with captive resin relationships and squeezes mid-tier players dependent on merchant feedstock.
Pricing Analysis
Certification level creates the primary spread between medical-grade and food-contact tiers. Three-tier pricing structure across premium, standard, and economy levels reflects TUV Austria OK Compost HOME qualification, FDA 21 CFR 177.1520 compliance, and uncertified commodity supply. Cost compression in standard-tier polypropylene is intensifying because German retailers are consolidating specifications across private-label networks. Food manufacturers exhibit the highest price sensitivity due to volume scale and specification standardization, while pharmaceutical contract packers accept premium positioning for validated sterile barrier systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material sourcing risk for specialty sealant additives. Feedstock concentration rests on Saudi Arabia, South Korea, and the US Gulf Coast for metallocene polypropylene and ethylene copolymers. Coextrusion equipment draws from Germany, Italy, and Japan, creating single-source vulnerability for seven-layer blown film line components. Distribution runs through converter hubs in the Rhine-Ruhr corridor, Chicago-Milwaukee belt, and Kanto region for just-in-time delivery to tray seal operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU recyclability mandates splinter demand across mono-material polypropylene, paper-film hybrids, and emerging compostable alternatives. Brand owner specification divergence creates defendable niches for formulation specialists.
For Market Incumbents: Build captive resin relationships as the primary moat against merchant feedstock volatility. Secure long-term offtake agreements with Saudi and South Korean polymer suppliers to lock in metallocene polypropylene access. Add coextrusion capacity in Germany to serve consolidating ready-meal manufacturers with localized supply. Counter the threat of asset-light leasing models by embedding technical service teams at major tray seal converter accounts. For New Entrants and Emerging Players: Establish a beachhead in medical packaging sterile barrier systems where qualification barriers limit incumbent aggression. Target Swiss and German pharmaceutical contract packagers seeking shared qualification cost structures for non-fluorinated copolyester sealants. Penetrate the organic food segment through TUV Austria OK Compost HOME certification for polylactic acid-based alternatives. Lead with digital print integration capabilities to capture cosmetics brand batch-customization demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mid-sized tray seal converting as machinery leasing models proliferate. Five-to-ten year viability favors converters with integrated formulation development rather than pure toll manufacturing. Target acquisition archetype: regional film specialists with deep relationships in consolidating German and French retail networks. Monitor EU Extended Producer Responsibility fee structure announcements as the inflection signal for which material platforms achieve scalable adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Migration | EU Packaging and Packaging Waste Regulation recyclability mandates force converter reengineering of sealant formulations. |
| Non-Fluorinated Sealant Qualification | F-Gas Regulation phase-down extends medical packaging validation cycles and consolidates supplier panels. |
| Digital Print Integration | Batch-level customization without plate costs alters converter economics for cosmetics and organic food segments. |
| Asset-Light Leasing Expansion | Coextrusion line leasing narrows capital barriers for mid-sized converters entering easy peel film production. |
| Extended Producer Responsibility Alignment | Fee structures based on recyclability certification determine which sealing technologies achieve commercial scale. |
Methodological Framework
Desk research of trade association filings, customs records, and machinery shipment data preceded structured interviews with coextrusion line operators, sealant formulation chemists, tray seal converter procurement leads, and retail private-label category managers. Primary fieldwork with European and North American film converters was cross-referenced against secondary validation from FDA 21 CFR submissions, EU F-Gas Regulation impact assessments, and TUV Austria certification databases. Bottom-up capacity modeling and top-down demand estimation were triangulated to establish volume benchmarks.
Assumptions held fixed include current EU Packaging and Packaging Waste Regulation enforcement timelines, existing REACH perfluorinated substance restrictions, and prevailing metallocene polypropylene supply concentration. Variables modeled across the analysis window encompass resin price volatility, machinery delivery lead times, and brand owner specification consolidation rates. Segmentation dimensions included material chemistry, application thermal requirements, converting technology, and end-user procurement sophistication. CAGRs were derived from installed capacity expansion trajectories and substitution elasticity between mono-material and multi-layer structures.
Stress conditions across resin supply disruption, regulatory acceleration, and machinery delivery delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about sustained EU recyclability mandate enforcement and continued pharmaceutical qualification cost sharing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
North America Polyimide Films Market
Poly film
Multi-Layer Blown Films Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Polypropylene Film Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Global Fluoropolymer Films Market
Poly film
Automotive Wrap Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Polycarbonate Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Tube Laminating Films Market
Poly film
High Density Polyethylene Film Market
Poly film
PCR Lidding Films Market
Poly film
PVC Films Market