
 Bottled Water Packaging Market | 2026-2036
Bottled Water Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bottled Water Packaging Market Analysis
Multi-source resin procurement is pivoting toward vertically integrated PET producers as volatility in virgin plastic feedstocks pressures converters. Amcor plc leverages its global preform manufacturing network to secure resin allocations across multiple geographies. Berry Global Inc. anchors North American volume through dedicated blow-molding facilities serving private-label bottled water brands. Sidel Group competes on equipment-led packaging lightweighting technology that reduces PET gram weight per bottle.
Bottled water packaging encompasses the primary and secondary containment systems engineered to preserve water quality, prevent contamination, and enable distribution. PET resin dominates the packaging type segment due to its clarity, shatter resistance, and established recycling infrastructure; the material typically constitutes 20-25 gram weight for a 500ml still water bottle. Glass packaging occupies premium positioning in hospitality and gifting channels where perceived purity justifies higher unit economics. The 500ml volume size leads retail velocity, while aluminum formats are gaining traction in on-the-go and sports channels as brands seek differentiation beyond PET.
The FDA governs bottled water as a packaged food product under 21 CFR 165.110, mandating quality standards that directly influence packaging material selection and migration testing protocols. The EPA regulates source water protection, while state-level bottle deposit laws in California, New York, and Michigan create fragmented compliance obligations that shape regional packaging strategies. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates that will determine which material technologies and geographic production footprints remain viable.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing virgin PET demand while forcing converters to revalidate entire material streams against migration limits and recycled-content thresholds.
Growth Catalysts
- Hospitality procurement expansion:Hotel chains and fitness centers are scaling premium-format bottled water programs that command higher unit margins and justify specialized packaging investments.
- REACH-compliant rPET scaling:European converters are securing EFSA-approved recycled resin allocations ahead of mandatory recycled-content floors taking effect across member states.
- Lightweighting technology diffusion:Sidel's preform design software is enabling 500ml bottle weights below 8 grams without compromising top-load strength or barrier performance.
Market Restraints
- Feedstock cost volatility:Paraxylene and PTA pricing swings tied to crude oil movements compress converter margins on fixed-price private-label contracts.
- rPET supply concentration:European mechanical recycling capacity clusters in Germany and Italy, creating allocation bottlenecks for converters in peripheral markets.
- Glass substitution ceiling:Premium hospitality channels retain glass preference for perceived purity, limiting PET penetration in high-margin gifting segments.
Strategic Opportunities
- Aluminum format white space:Sports and on-the-go channels in Germany and France show receptivity to aluminum bottles as PET differentiation fatigue sets in.
- Deposit-return scheme optimization:Germany's DPG system and California's CRV framework reward packaging designs that maximize sorting yield and material recovery rates.
- Bio-based PET pilot scaling:Coca-Cola and Danone are trialing plant-derived MEG in European production lines, creating offtake agreements for packaging converters.
Industry Challenges
- Migration testing backlog:EFSA's novel food approval queue for recycled-content packaging delays time-to-market for rPET-heavy formats by 12-18 months.
- Blow-molding retooling cycles:Lightweight preform designs require capital-intensive mold modifications and line revalidation that strain mid-tier converter balance sheets.
- Multi-jurisdictional compliance:California's Proposition 65, New York's bottle bill, and EU REACH create conflicting substance restrictions that complicate unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottled Water Packaging Market |
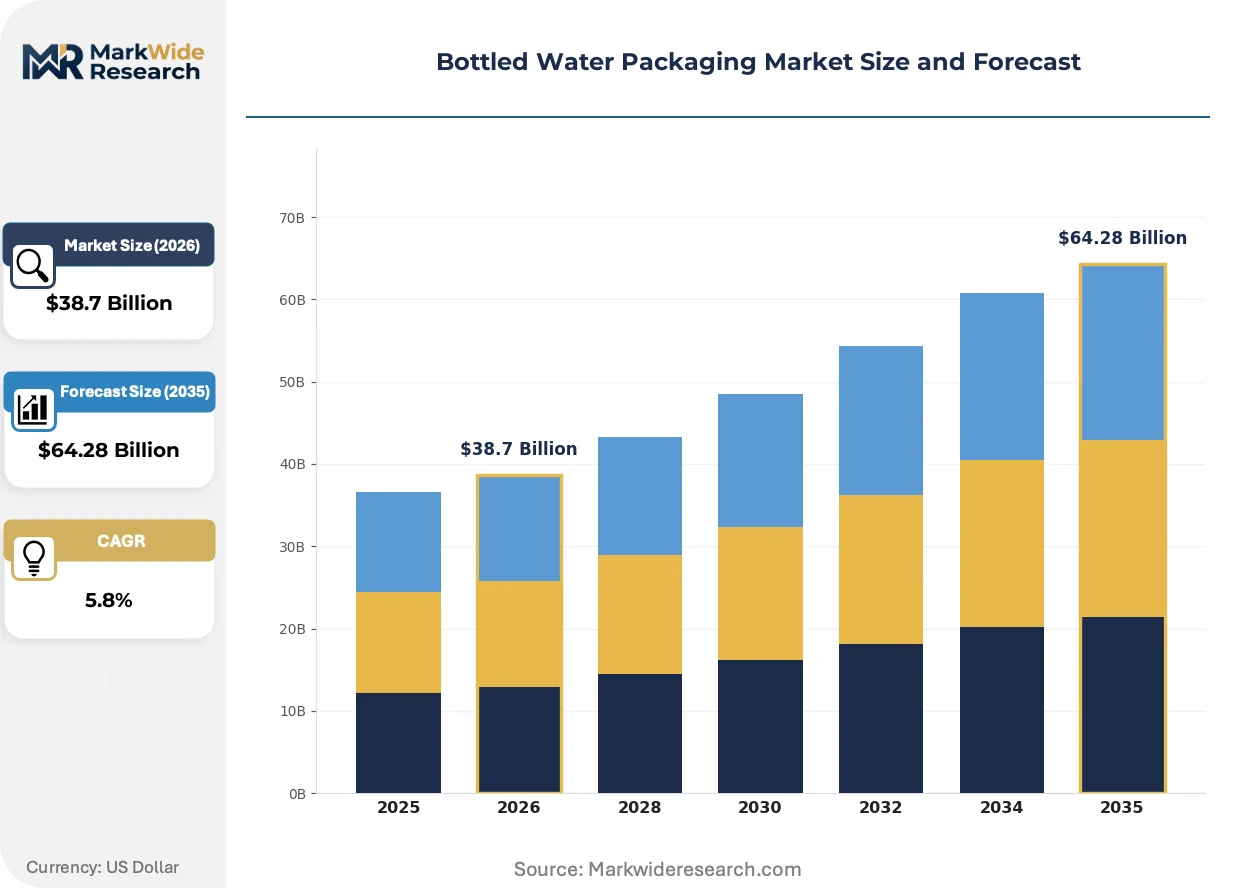
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: PET, Glass, Carton, Aluminum Closure Type: Screw Cap, Sport Cap, Flip Top, Cork Volume Size: 330ml, 500ml, 1L, 2L Distribution Channel: Retail, E-commerce, Wholesale, Vending |
| Companies Covered | Plastipak Holdings, Inc., Greif, Inc., Amcor plc, Graham Packaging Company, Sidel Group, Berry Global Inc., Silgan Holdings Inc., ALPLA, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottled Water Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory compliance automation are compressing development cycles while fragmenting competitive advantage across specialized technology niches.
Mono-material barrier coatings are electrifying conventional PET performance limits. Solvay's high-gas-barrier oxide deposition technology enables 12-month shelf life for sensitive water categories without multilayer structures. Premium sparkling water brands in Germany and Switzerland are piloting these formats to eliminate aluminum foil laminates and simplify recycling streams.
REACH Article 33 disclosure requirements are forcing upstream chemical transparency through packaging supply chains. Converters must now document SVHC content above 0.1% w/w for every resin batch and additive package. Mineral water producers in France and Italy are responding by consolidating supplier bases to reduce documentation complexity and audit exposure.
Direct-to-hotel procurement platforms are disintermediating traditional beverage distributors in European hospitality channels. Accor and Marriott properties are negotiating packaging specifications directly with converters, specifying custom embossing and closure designs that bypass standard retail SKUs. This pattern concentrates most visibly in German business-travel corridors where property-level sustainability scorecards drive supplier selection criteria.
Bottled Water Packaging Market Segmentation
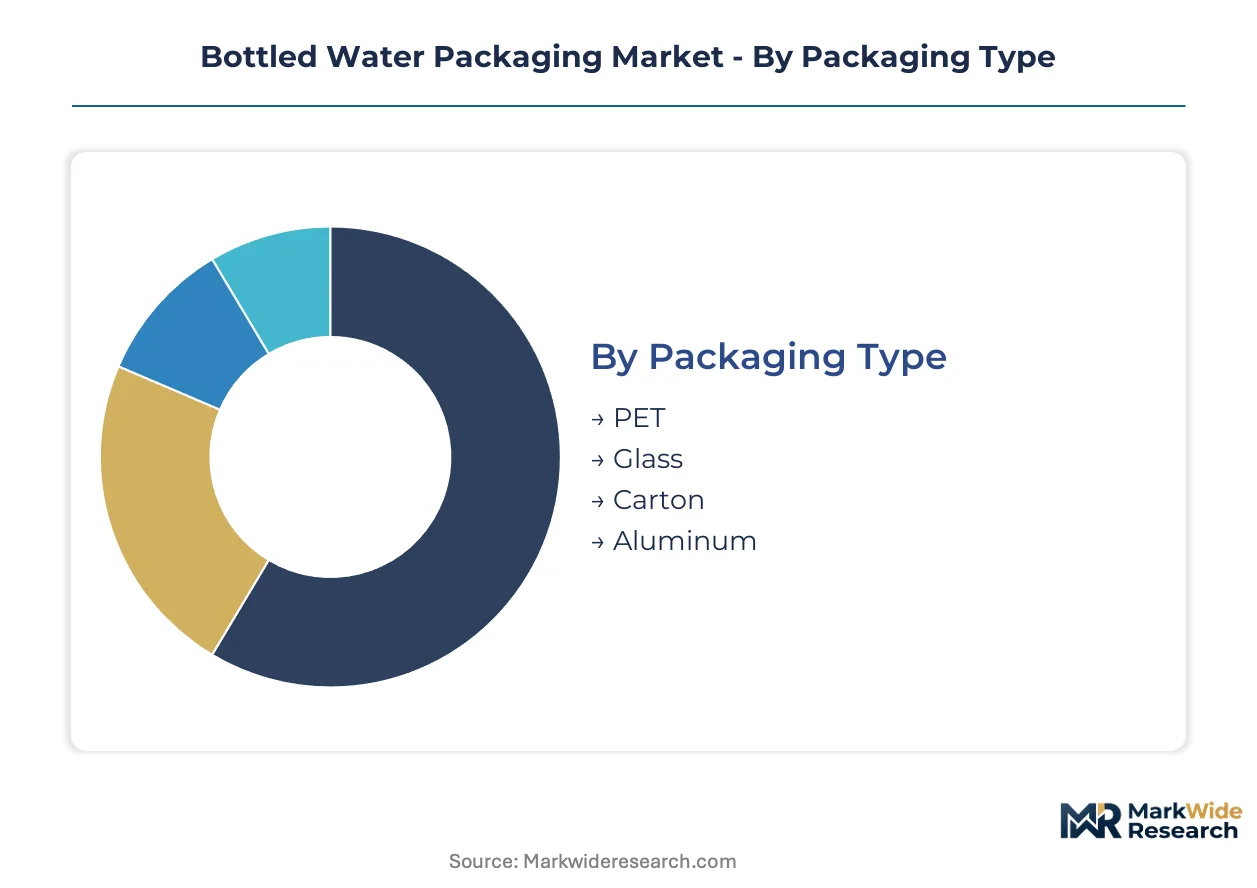
Material selection and format specifications in bottled water packaging determine compliance pathways, shelf-life performance, and recovery economics across divergent regulatory environments. Segmentation reveals where converters capture margin through specialized barrier technologies versus commodity scale.
Packaging Type:
Standalone packaging formats operate independently of dispensing equipment, while embedded systems require integration with filling lines and retail infrastructure.
- PET:Thermoplastic polyester resin delivers clarity, shatter resistance, and established mechanical recycling streams. Demand concentrates in German retail and hospitality channels where EFSA-approved rPET sourcing meets EU Single-Use Plastics Directive thresholds.
- Glass:Silica-based container provides inert barrier properties and premium aesthetic positioning. French and Italian mineral water producers favor glass for gifting segments where perceived purity justifies higher unit economics and deposit-return logistics.
- Carton:Paperboard laminate with polyethylene barrier layers serves institutional and family-format volumes. Swedish and Finnish converters pilot fiber-based alternatives to reduce plastic dependency in Nordic markets.
- Aluminum:Rolled metal sheet offers infinite recyclability and rapid chilling properties. German sports and on-the-go channels show expanding uptake as brands differentiate beyond conventional PET offerings.
PET leads volumes today; aluminum is gaining share fastest in premium mobility segments.
Closure Type:
Cost tier stratification separates commodity dispensing from engineered drinking experiences, with price points scaling from standard screw mechanisms to specialized sport and premium formats.
- Screw Cap:Standard threaded polyethylene closure dominates high-velocity retail SKUs. California's CRV deposit scheme and Germany's DPG system incentivize tethered designs that remain attached to bottles through consumption.
- Sport Cap:Pull-spout mechanism with flow control enables single-handed drinking during activity. French fitness center procurement and German cycling event sponsorships drive specification for this format.
- Flip Top:Hinged lid design provides resealability for intermittent consumption patterns. Italian family-format volumes and workplace hydration stations specify this closure for convenience positioning.
- Cork:Natural or synthetic stopper serves premium sparkling water and gifting applications. Swiss and Belgian producers deploy cork for restaurant and hotel table service where ritual opening enhances perceived value.
Screw cap configurations anchor mass-market economics; sport cap specifications are expanding most quickly in fitness and outdoor channels.
Volume Size:
Application context determines format selection, with consumption occasion and portability requirements dictating dimensional specifications across retail and away-from-home environments.
- 500ml:Single-serve dimension balances portability with adequate hydration for standard consumption occasions. German convenience retail and commuter rail vending represent core demand concentration for this specification.
- 330ml:Compact format suits airline hospitality, premium hotel minibars, and portion-controlled settings. British Airways and Lufthansa procurement specifications drive converter capacity allocation for this segment.
- 1L:Family and fitness-oriented volume serves home refrigeration and gym bag applications. French hypermarket chains and German discount retailers push this format for value-positioned still water.
- 2L:Bulk household format minimizes per-liter packaging cost for pantry stocking and meal preparation. Italian and Spanish domestic consumption patterns sustain demand despite declining per-capita soda volumes.
500ml specifications dominate retail velocity; 330ml formats are climbing the fastest in travel and hospitality procurement.
Distribution Channel:
Customer type fragmentation separates direct institutional negotiation from layered wholesale and retail intermediation, with margin capture varying by channel control and specification influence.
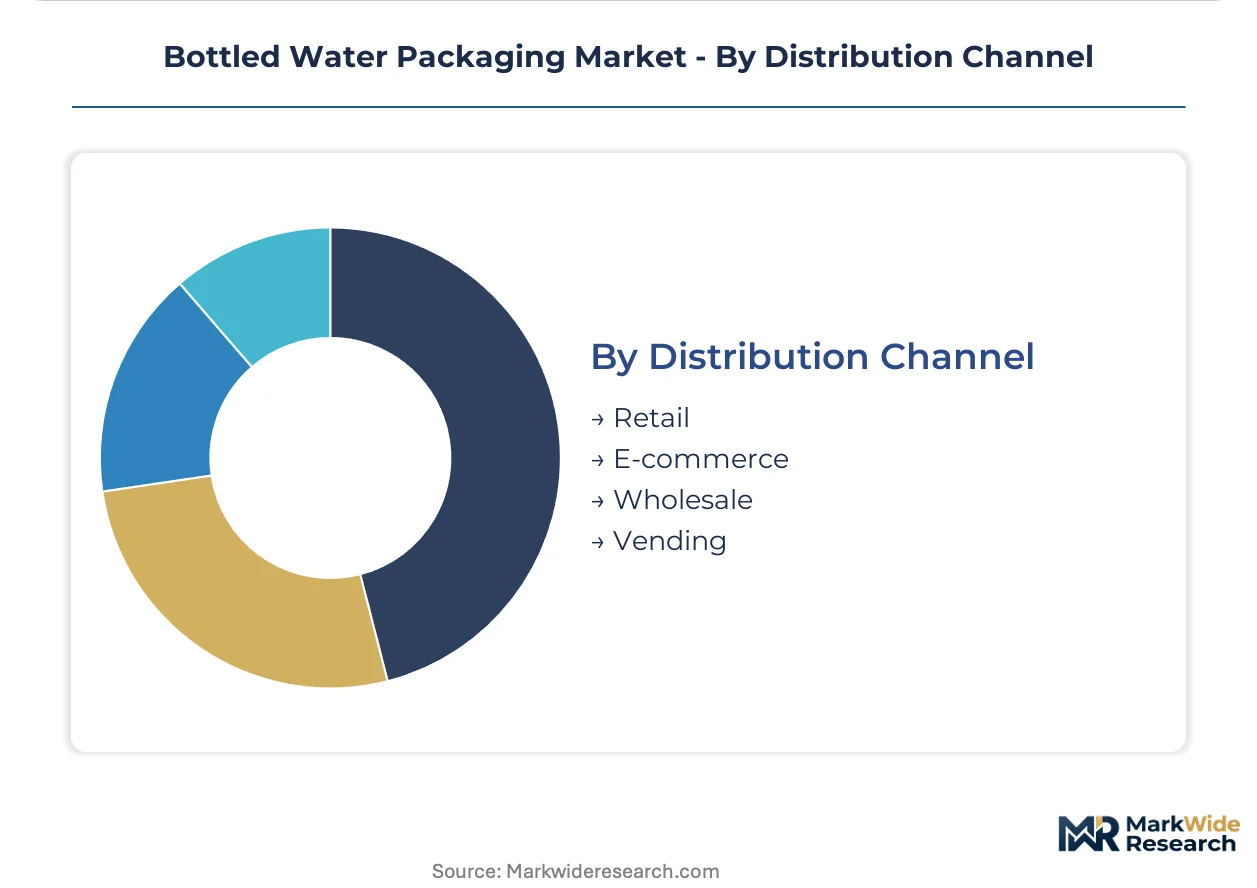
- Retail:Supermarket, convenience, and drugstore shelf placement requires case-ready packaging and pallet optimization. REWE, Carrefour, and Edeka buying power in Germany and France dictates converter pricing and promotional pack configurations.
- E-commerce:Direct-to-consumer and platform-fulfilled delivery demands enhanced secondary packaging for parcel transit. Amazon Fresh and Zalando Logistics specifications in Germany are forcing bottle-to-tray redesigns for dimensional weight efficiency.
- Wholesale:Foodservice and institutional bulk procurement concentrates volume through distributor networks. Sysco and Bidfood specifications in the UK and Netherlands influence regional converter product platforms.
- Vending:Automated dispensing equipment requires specialized bottle geometry and label adhesion for mechanical handling. Selecta and Pelican Rouge machine networks across Belgian and Swiss transport hubs sustain dedicated format demand.
Retail channels command current volume concentration; e-commerce fulfillment specifications are expanding most steeply in urban German markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are relocating blow-molding capacity toward jurisdictions with streamlined EFSA approval pathways and established mechanical recycling infrastructure, arbitraging the twelve-to-eighteen-month migration testing backlog that delays rPET-heavy format launches in peripheral markets.
Germany
Mineral water consumption traditions and the DPG deposit-return scheme sustain premium-format demand across hospitality and retail channels. ECHA REACH compliance mandates SVHC disclosure above 0.1% w/w, forcing upstream chemical transparency through resin supply chains. The Rhineland-Palatinate and Bavaria clusters host dedicated preform manufacturing serving private-label bottled water brands.
France
Hypermarket chains and restaurant table-service specifications drive glass retention in gifting and premium sparkling segments. ANSM enforces packaging material migration limits for sensitive water categories, influencing converter selection of mono-material barrier coatings. The Auvergne-Rhône-Alpes region concentrates blow-molding capacity for sport-cap formats targeting fitness center procurement.
United States
State-level bottle deposit laws in California, New York, and Michigan fragment compliance obligations and shape regional packaging strategies. FDA 21 CFR 165.110 governs bottled water as packaged food, mandating quality standards that influence material selection and testing protocols. The Great Lakes industrial corridor anchors North American volume through dedicated facilities serving private-label brands.
Italy
Domestic consumption patterns sustain 2L family-format demand despite declining per-capita soda volumes. EFSA novel food approval queues delay time-to-market for recycled-content packaging, compressing converter margins on fixed-price contracts. The Lombardy and Emilia-Romagna clusters concentrate mechanical recycling capacity and EFSA-approved rPET sourcing.
Switzerland
Premium sparkling water brands pilot high-gas-barrier oxide deposition technology to eliminate aluminum foil laminates and simplify recycling streams. Swissmedic-aligned quality expectations exceed baseline EU requirements, creating a high-value market for specialized barrier solutions. The Zurich-Geneva corridor hosts equipment-led lightweighting technology providers serving German and French export markets.
Bottled Water Packaging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue aluminum format differentiation and bio-based resin pilot programs. The vendor base stratifies across integrated resin-to-preform operators, dedicated blow-molding specialists, and equipment-technology licensors. Three archetypes dominate: vertically integrated PET producers securing allocation priority, mid-tier converters anchoring regional private-label volume, and technology licensors capturing value through lightweighting software and barrier coating patents. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with converters securing EFSA-approved rPET allocations ahead of mandatory recycled-content floors.
Among Switzerland-based equipment specialists, Sidel Group exemplifies the technology-licensor archetype through preform design software enabling sub-8-gram bottle weights. Amcor plc and Berry Global Inc. represent the integrated and regional-anchor archetypes respectively, with the former leveraging global manufacturing networks and the latter concentrating North American volume through dedicated facilities. These three entities illustrate how competitive positioning fragments across technology specialization, geographic scale, and vertical integration depth.
| Leading Market Players |
|---|
| Plastipak Holdings, Inc. |
| Greif, Inc. |
| Amcor plc |
| Graham Packaging Company |
| Sidel Group |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| ALPLA |
| Ball Corporation |
| Others |
Supply Flow & Price Mechanics
Paraxylene and PTA feedstock costs cascade through PET resin pricing tiers, with German converters absorbing volatility through indexed contracts while North American private-label suppliers face margin compression on fixed-price agreements. Hospitality procurement teams in Germany and France negotiate specification premiums that offset raw material swings, whereas discount retail channels in Italy and Spain transmit cost pressure directly to blow-molding specialists.
Pricing Analysis
Input-cost pass-through operates asymmetrically across contract structures, with indexed resin agreements dominating German hospitality supply and fixed-price terms anchoring North American private-label volume. Price differentiation separates EFSA-certified rPET formats from virgin PET commodity grades, with migration-testing backlog creating scarcity premiums for approved recycled content. Pricing pressure stems from mechanical recycling capacity concentration in Germany and Italy, which constrains allocation for peripheral market converters. Discount retail buyers in Spain and Poland exhibit highest price sensitivity, while Swiss hotel chains and French restaurant groups accept specification premiums for barrier-coated and lightweight formats.
Supply Chain Analysis
EU Single-Use Plastics Directive recycled-content mandates reshape sourcing patterns, forcing converters to secure EFSA-approved rPET allocations ahead of mandatory thresholds. Geographic supply concentration clusters in Germany, Italy, and the United States, with Rhineland-Palatinate and Lombardy hosting dedicated preform manufacturing and mechanical recycling infrastructure. Raw material dependencies center on paraxylene and PTA from petrochemical complexes, plus imported MEG for bio-based PET pilot programs. Single-source vulnerability runs through European mechanical recycling capacity, where German and Italian facility outages disrupt allocation across peripheral markets. Distribution runs through dedicated blow-molding facilities serving private-label brands, with direct-to-hotel procurement platforms disintermediating traditional beverage distributors in German business-travel corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with hospitality procurement expansion toward premium specifications justifying specialized packaging investments despite feedstock volatility. Fitness center and hotel chain buyers prioritize sustainability scorecards and custom embossing over per-unit cost minimization.
For Market Incumbents: Deploy EFSA-approved rPET allocation securing as the priority lever. Amcor plc and Berry Global Inc. should anchor German and Italian recycling cluster relationships to preempt peripheral market competitors. Backward integration into mechanical recycling capacity in Lombardy and Emilia-Romagna defends margin position against feedstock volatility and rPET supply concentration. Certification investment in REACH Article 33 compliance automation reduces audit exposure as mineral water producers consolidate supplier bases.
For New Entrants and Emerging Players: Enter via aluminum format white space in German and French sports channels, where PET differentiation fatigue creates receptivity for rapid-chilling metal alternatives. Target fitness center procurement specifications in the Auvergne-Rhône-Alpes region and German cycling event sponsorships for sport-cap format entry. Direct-to-hotel procurement platforms in German business-travel corridors offer disintermediation angles that bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack capital for lightweighting mold modifications and EFSA migration testing queues. Long-term viability favors equipment-technology licensors with barrier coating patents and preform design software, or integrated operators with captive rPET sourcing. The signal to watch is EFSA novel food approval velocity for recycled-content formats, which determines which converter portfolios capture mandatory recycled-content floor premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Approved rPET Allocation Securing | Converters with pre-approved recycled resin access capture EU Single-Use Plastics Directive compliance premiums ahead of competitors. |
| Lightweighting Technology Licensing | Sidel Group's sub-8-gram preform software enables PET gram reduction without top-load strength compromise. |
| Direct-to-Hotel Procurement Platform Development | Accor and Marriott property-level sustainability scorecards favor converters with custom embossing capabilities. |
| Mono-Material Barrier Coating Pilot Scaling | Solvay's oxide deposition technology eliminates aluminum foil laminates for German sparkling water brands. |
| Mechanical Recycling Capacity Backward Integration | Lombardy and Emilia-Romagna cluster proximity secures rPET allocation priority for Italian mineral water producers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with PET resin procurement managers, blow-molding plant engineers, hospitality sustainability officers, and beverage distributor category buyers with secondary validation. Customs and trade data, EFSA novel food approval databases, SEC 10-K filings from packaging converters, and EU Single-Use Plastics Directive implementation trackers supplied foundational inputs. Bottom-up volume modeling across material type, closure specification, and volume format triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed value and volume across packaging type, closure mechanism, volume size, and distribution channel dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating hospitality procurement expansion rates, fitness center specification shifts, and regulatory compliance cost pass-through. Industry-specific forecast inputs included EFSA migration testing queue lengths, mechanical recycling capacity utilization in Germany and Italy, and deposit-return scheme participation rates across California, New York, and Michigan.
Inputs from primary interviews and regulatory filing databases were available through the study window; gaps in real-time rPET spot pricing and confidential contract terms introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding EFSA approval velocity, paraxylene-PTA price correlation stability, and EU member state transposition timing for recycled-content mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Drink Can Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Bottle Pourers Market