
 Polyester Film Market | 2026-2036
Polyester Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polyester Film Market Analysis
Thinner gauge specifications in electronics-grade films is narrowing the viable supplier base to those with precision coating capabilities. Toray Industries anchors Japanese demand through captive supply of optical-grade BOPET for display laminates. SKC Co., Ltd. dominates Korean electronics supply chains with vertically integrated resin-to-film production. Kolon Industries differentiates through specialty M-PET formulations for battery separator applications.
Polyester film is a thermoplastic polymer sheet extruded from polyethylene terephthalate (PET) resin, typically manufactured via biaxial orientation (BOPET) or amorphous extrusion (A-PET) to achieve thicknesses from 1.2 microns to 350 microns for barrier, insulation, or structural functions. BOPET commands the largest value pool due to its balanced tensile strength and optical clarity in packaging and electronics, while M-PET grows fastest as lithium-ion battery separators and electromagnetic shielding expand. A-PET retains mature share in thermoformed food trays where clarity and recyclability meet FDA and EFSA food-contact requirements.
US EPA regulations on per- and polyfluoroalkyl substances (PFAS) in food packaging redirect demand toward silicone- and clay-coated PET barriers, while EU REACH restrictions on antimony catalyst residues reshape resin sourcing for European converters. China's GB standards for food-contact plastics and MEE enforcement of VOC emissions at coating lines add compliance layers for export-oriented producers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in multiple geographies, as recycled-content mandates threaten cost structures for virgin-PET-dependent film operations.
Market Dynamics
Thin-gauge film specifications in electronics applications are compressing the viable supplier base toward precision coating specialists, while China's MEE emissions enforcement and dual carbon goals restructure resin sourcing for export-oriented converters.
Growth Catalysts
- Flexible PCB demand:Electronics manufacturers in South Korea and Japan are pulling ultra-thin BOPET films into high-density interconnect boards for foldable display modules.
- REACH antimony restrictions:ECHA limits on catalyst residues are redirecting European converters toward specialized resin grades with alternative polymerization chemistries.
- Battery separator expansion:M-PET formulations are capturing share in lithium-ion cell manufacturing as dry-process separator lines scale across East Asian cell plants.
Market Restraints
- Petrochemical feedstock volatility:Purified terephthalic acid and ethylene glycol pricing swings compress margin predictability for non-integrated film extruders.
- Optical-grade supply concentration:Japanese and Korean producers control the majority of display-laminate-grade BOPET capacity, creating procurement bottlenecks for secondary electronics assemblers.
- PFAS barrier substitution:US EPA restrictions on fluorinated coatings in food-contact applications are forcing rapid reformulation of high-barrier PET structures before proven alternatives achieve scale.
Strategic Opportunities
- Recycled-content mandates:EU Extended Producer Responsibility frameworks and China's circular economy action plans are creating premium price tiers for rPET-based films with verified chain-of-custody documentation.
- Electromagnetic shielding films:Convergence of metallized PET with conductive polymer coatings is opening defense and aerospace applications previously served by heavier metal foils.
- Direct-to-converter digital platforms:Specialty film distributors are bypassing traditional regional stocking points to serve mid-volume electronics assemblers in Vietnam and India with customized slit-width deliveries.
Industry Challenges
- Precision coating talent scarcity:Vacuum metallization and solventless adhesive lamination require technicians with rare combinations of polymer chemistry and roll-to-roll process control expertise.
- Cleanroom certification timelines:FDA and EFSA food-contact approvals for new coextruded structures extend 18-24 months, delaying revenue recognition for reformulated barrier films.
- Legacy extrusion asset retrofitting:Converting older BOPET lines to handle bio-based or recycled-content resins requires substantial capital outlay without guaranteed offtake commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyester Film Market |
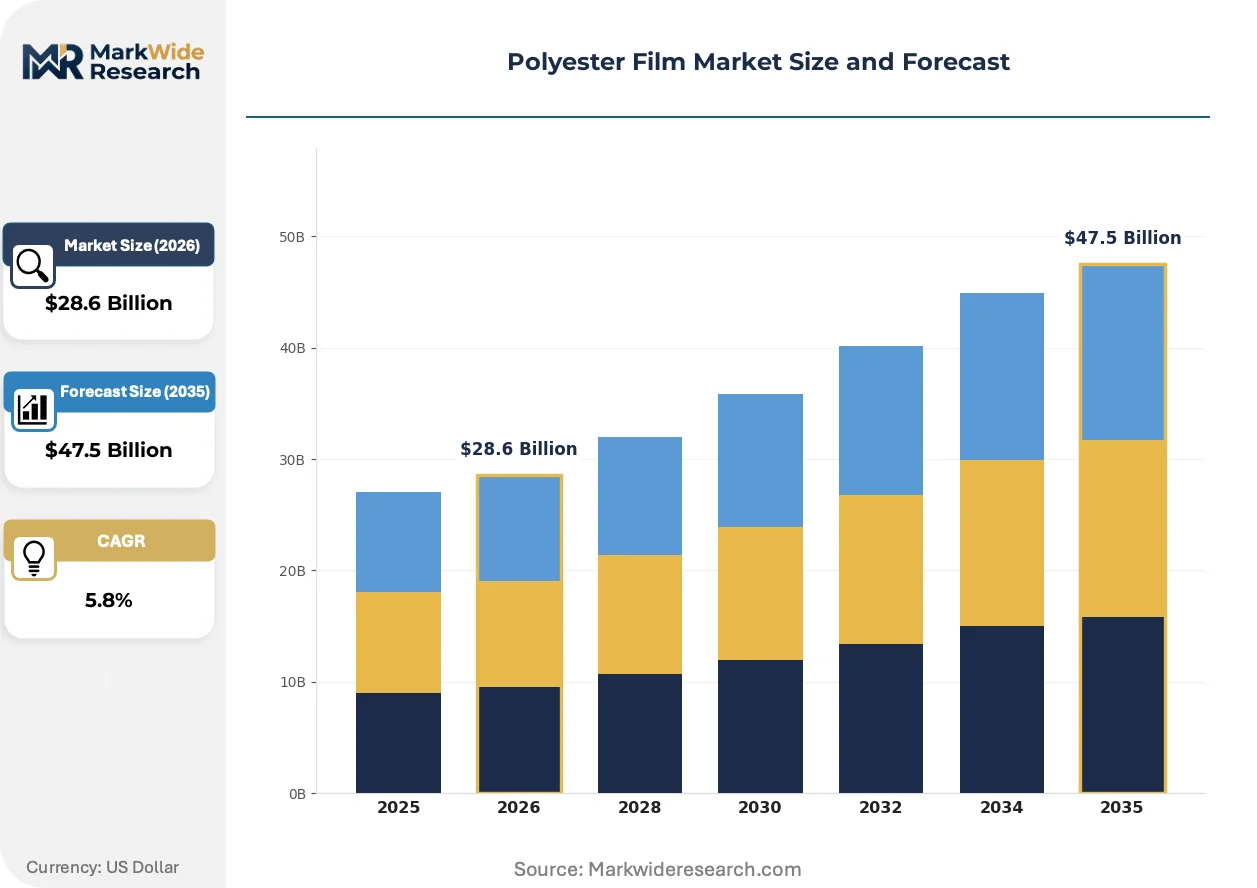
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester BOPET, Polyester A-PET, Polyester C-PET, Polyester M-PET Application: Packaging, Electrical Insulation, Labeling, Durables End User: Food & Beverage, Electronics, Automotive, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | SKC Co., Ltd., Kolon Industries, Inc., Toray Industries, Inc., Jindal Poly Films Limited, Uflex Limited, Teijin Limited, Mitsubishi Polyester Film, Inc., Polyplex Corporation Ltd., DuPont Teijin Films U.S. Limited Partnership, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyester Film Market Emerging Trajectories
Coating technology convergence and regulatory chemistry restrictions are restructuring how barrier properties get engineered into PET substrates, with sustainability verification becoming a parallel specification layer alongside optical and mechanical performance.
Nano-clay and graphene-loaded PET composites are hybridizing conventional barrier performance with electromagnetic functionality. Defense contractors and automotive sensor suppliers are qualifying these materials for weight-critical shielding applications. The technology is hybridizing what were previously separate material procurement streams for packaging engineers and electronics designers.
EU REACH restrictions on antimony trioxide catalyst residues are compelling resin producers to accelerate titanium-based and germanium-based polymerization alternatives. European converters face reformulation costs and re-qualification timelines for existing food-contact film grades. German and Italian packaging film specialists are responding by locking in multi-year supply agreements with certified low-antimony resin sources.
Electronics assemblers are consolidating film procurement around vertically integrated resin-to-film suppliers capable of lot-level traceability documentation. Samsung and LG supply chain audits now require sub-lot tracking from polymerization through metallization. South Korean display material clusters exhibit the most advanced supplier consolidation, with tier-2 assemblers in Vietnam and Mexico following similar qualification patterns under customer mandate pressure.
Polyester Film Market Segmentation
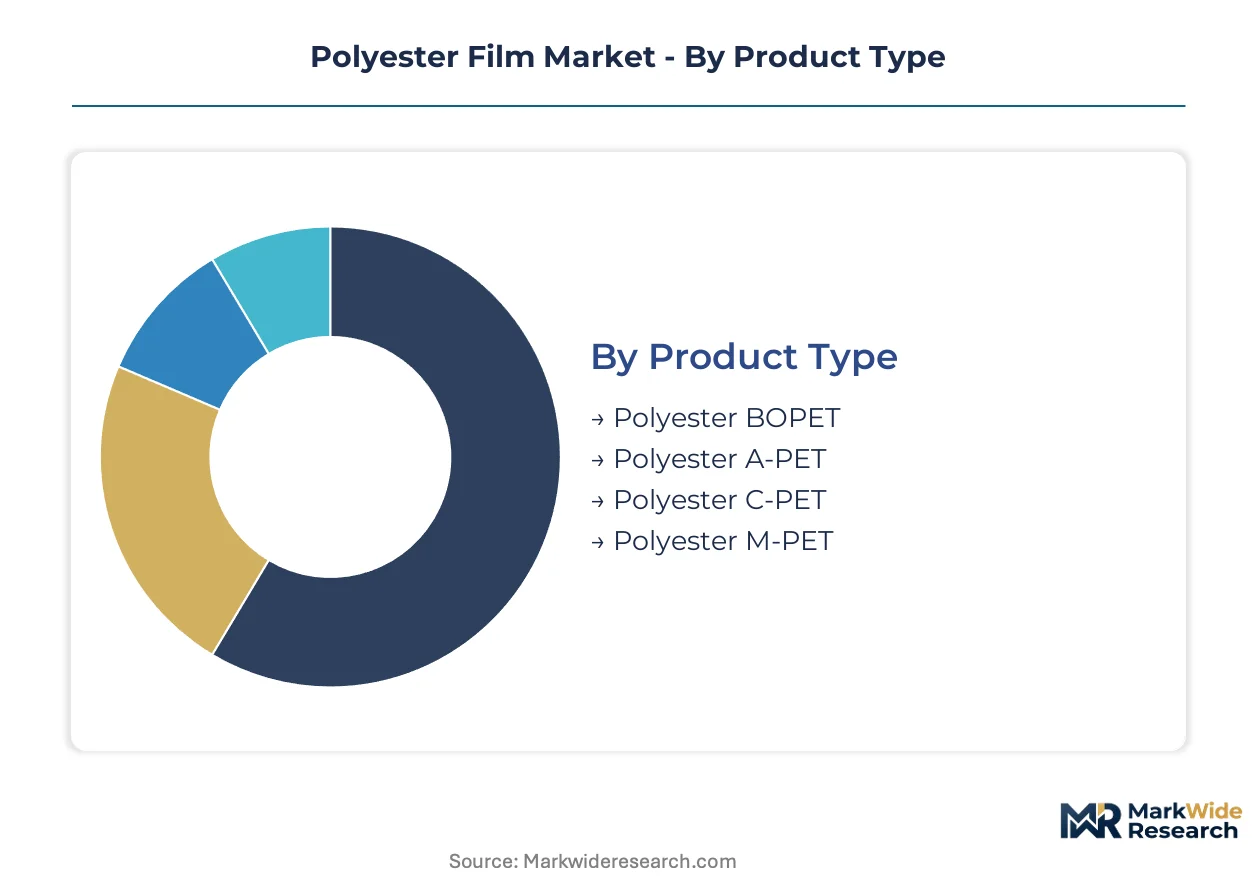
Polyester film segmentation reveals divergent margin profiles across manufacturing processes and end-use specifications. Cycle times vary dramatically from commodity packaging grades with rapid inventory turns to electronics-grade films requiring extended qualification periods.
Product Type:
Biaxially oriented films command extended production cycles due to stretching and heat-setting stages, while amorphous extrusion offers faster throughput at lower capital intensity.
- Polyester BOPET:Biaxial orientation yields balanced mechanical properties and optical clarity through sequential longitudinal and transverse stretching. Samsung and LG supply chains in South Korea anchor premium demand for display-laminate grades where sub-12 micron specifications dominate.
- Polyester M-PET:Metallized variants receive vacuum-deposited aluminum layers for barrier and electromagnetic shielding. Battery separator applications in East Asian cell plants drive the steepest specification evolution as dry-process electrode manufacturing scales.
- Polyester A-PET:Amorphous extrusion prioritizes thermoformability and clarity for food-contact trays. FDA and EFSA compliance requirements extend qualification timelines for new formulations.
- Polyester C-PET:Crystallized grades withstand higher thermal loads for ovenable packaging. European converters favor C-PET for ready-meal applications under EFSA temperature-exposure guidelines.
BOPET anchors the volume base while M-PET gains share at the steepest rate.
Application:
Margin structures stratify sharply between specification-driven electronics applications and price-sensitive commodity packaging.
- Packaging:Flexible and rigid formats span food, beverage, and consumer goods with thicknesses from 6 to 250 microns. China's GB standards for food-contact plastics and MEE emissions enforcement at coating lines reshape supplier compliance costs.
- Electrical Insulation:Dielectric films for motors, capacitors, and transformers require controlled dissipation factors. Japanese industrial motor manufacturers specify ultra-clean grades with particle counts below 50 per square meter.
- Labeling:Pressure-sensitive and in-mold labels demand printability and dimensional stability. European label converters face REACH antimony restrictions that redirect resin sourcing toward titanium-catalyzed alternatives.
- Durables:Industrial tapes, graphic films, and solar backsheet substrates emphasize weathering resistance. US solar module assemblers specify 25-year degradation warranties for backsheet PET layers.
Packaging absorbs the highest absolute tonnage while electrical insulation captures the most favorable unit economics.
End User:
Procurement sophistication varies from consolidated electronics assemblers with vendor-managed inventory to fragmented food processors spot-buying commodity grades.
- Food & Beverage:Barrier requirements for oxygen and moisture transmission drive coating specifications. US EPA PFAS restrictions in food packaging force rapid reformulation toward silicone and clay-based barrier alternatives.
- Electronics:Flexible PCB and display laminate applications specify thickness tolerances within 3% and surface roughness below 0.05 microns. South Korean display material clusters enforce lot-level traceability from polymerization through metallization.
- Automotive:Interior trim, safety labels, and battery component films must survive thermal cycling and chemical exposure. German automakers specify low-VOC emissions for cabin-grade PET films under KBA guidelines.
- Pharmaceuticals:Blister packs and medical device packaging demand particulate control and sterilization compatibility. MFDS in South Korea enforces accelerated aging protocols for pharmaceutical-grade barrier structures.
Food and beverage provides the broadest demand foundation while electronics commands the tightest specification premiums.
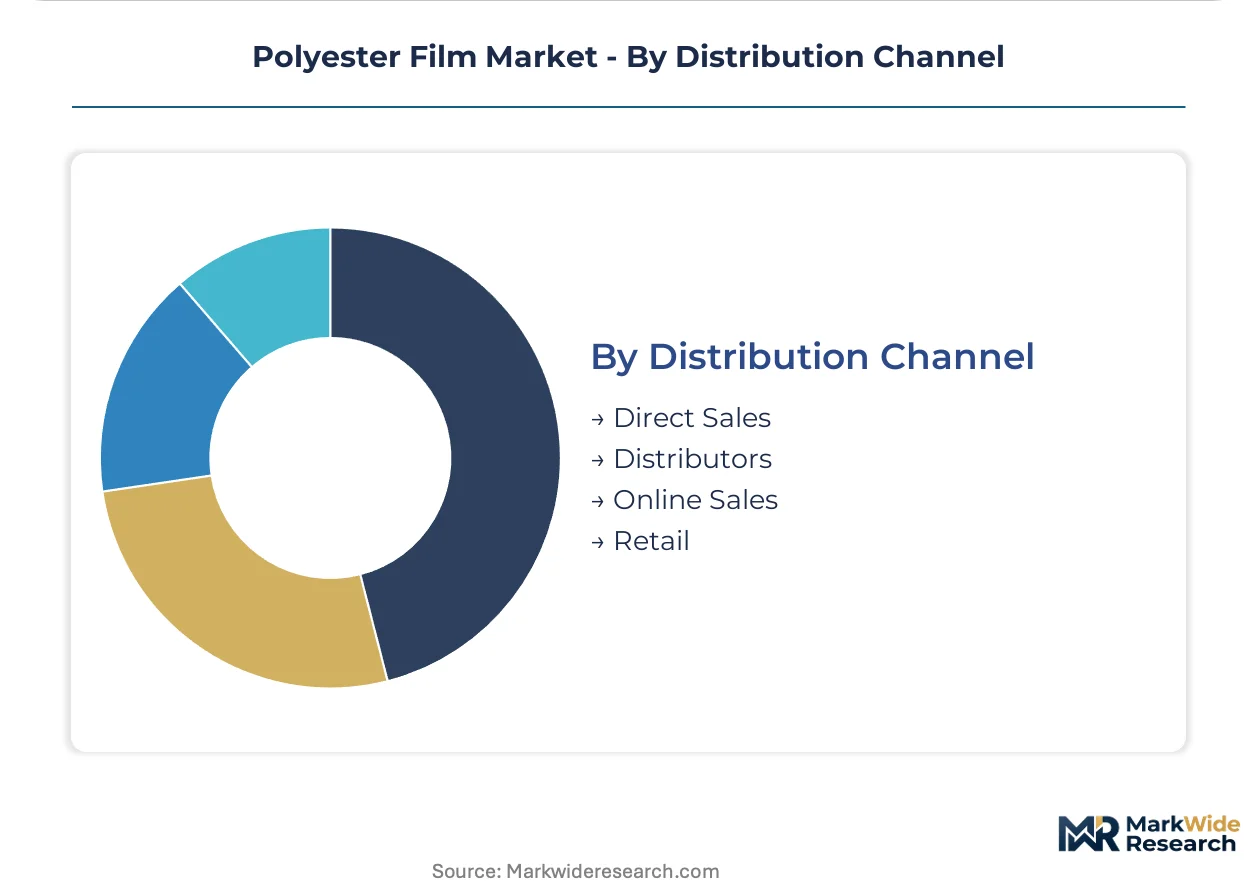
Distribution Channel:
Channel economics reflect working capital intensity and technical service requirements across customer segments.
- Direct Sales:Large-volume electronics and automotive assemblers negotiate mill-direct contracts with customized slit-width and surface-treatment specifications. Japanese and Korean producers maintain dedicated technical service teams for display-grade accounts.
- Distributors:Regional stocking points serve mid-volume converters with standard thickness inventories. Specialty film distributors increasingly bypass traditional hubs to reach Vietnam and India electronics assemblers with direct-to-converter digital platforms.
- Online Sales:E-procurement portals gain traction for standardized A-PET sheet and commodity BOPET rolls. Chinese resin-to-film producers leverage cross-border e-commerce for Southeast Asian packaging converters.
- Retail:Small-format sales of craft and hobby-grade films persist through specialty plastics retailers. This channel carries the highest per-unit logistics cost and lowest customer lifetime value.
Direct sales lock in the largest committed volumes while distributor relationships expand geographic reach most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese polyester film producers export precision-coated electronics grades to South Korean display manufacturers, while German converters ship barrier films to French food processors under harmonized EU standards.
China
Domestic display panel and battery cell manufacturers consume ultra-thin BOPET for flexible substrates and separator applications. MEE enforcement of VOC emissions at coating lines and dual carbon goals push producers toward recycled-content formulations. The Yangtze River Delta hosts the densest concentration of resin-to-film extruders serving export-oriented electronics assemblers.
South Korea
Samsung and LG supply chains anchor regional demand for optical-grade films with sub-12 micron specifications and lot-level traceability requirements. MFDS pharmaceutical-grade certifications create secondary demand for blister-pack barrier structures. The Seoul Capital Area concentrates precision metallization and coating capacity for display laminate integration.
Japan
Industrial motor manufacturers and capacitor producers specify ultra-clean dielectric grades with particle counts below 50 per square meter. METI guidelines on sustainable manufacturing incentivize energy-efficient stretching line retrofits. The Kanto region around Tokyo maintains captive optical film production integrated with downstream electronics assembly.
Germany
Automotive OEMs specify low-VOC cabin-grade films under KBA guidelines, while packaging converters face ECHA antimony catalyst restrictions that redirect resin sourcing. REACH compliance costs favor converters with established titanium-catalyzed supply agreements. Bavaria and Baden-Württemberg host the majority of specialty film slitting and metallization operations.
United States
Solar module assemblers specify 25-year degradation warranties for backsheet PET layers, while food packaging converters reformulate barrier structures around EPA PFAS restrictions. FDA food-contact approval timelines extend qualification periods for new coextruded grades. The Midwest and Southeast concentrate extrusion capacity serving domestic appliance and automotive Tier 1 suppliers.
Polyester Film Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base stratifies between vertically integrated resin-to-film operators and independent converters dependent on merchant resin supply. Three archetypes dominate: integrated petrochemical-film producers, precision coating specialists, and regional commodity extruders. Capacity expansion and strategic partnerships constitute the primary competitive moves, with backward integration into resin production and forward integration into metallization both observable.
Among East Asian integrated producers, Toray Industries, SKC Co., Ltd., and Kolon Industries exemplify the resin-to-film archetype with captive polymerization and stretching capabilities. These companies occupy positions supplying electronics assemblers with lot-traceable optical and battery-grade specifications. Their geographic concentration in Japan and South Korea reflects the historical development of display materials clusters and the qualification barriers that protect incumbent positions in precision coating segments.
| Leading Market Players |
|---|
| SKC Co., Ltd. |
| Kolon Industries, Inc. |
| Toray Industries, Inc. |
| Jindal Poly Films Limited |
| Uflex Limited |
| Teijin Limited |
| Mitsubishi Polyester Film, Inc. |
| Polyplex Corporation Ltd. |
| DuPont Teijin Films U.S. Limited Partnership |
| Others |
Supply Flow & Price Mechanics
Shanghai-Pusan container freight corridors transmit cost volatility from Chinese resin producers to South Korean display assemblers, amplifying price differentiation between lot-traceable electronics grades and commodity packaging films. This logistics dynamic concentrates procurement leverage among vertically integrated suppliers while squeezing independent converters dependent on merchant PTA and ethylene glycol supply.
Pricing Analysis
Sub-12 micron optical-grade specifications command substantial premiums over 25-50 micron packaging standards, while next-generation M-PET battery separator grades price at intermediate tiers reflecting qualification barriers. Three-tier pricing structure across premium, standard, and economy levels stratifies by lot-traceability certification and cleanroom production protocols. Cost compression in commodity A-PET sheet runs through spot ethylene glycol purchasing and non-integrated extrusion economics. Food processors exhibit the highest price sensitivity due to reformulation mandates, whereas Samsung and LG supply chains absorb premiums for sub-micron thickness tolerance guarantees.
Supply Chain Analysis
Purified terephthalic acid and ethylene glycol feedstock economics in China, South Korea, and Japan anchor global resin cost structures for film extrusion. M-PET production draws from vacuum metallization equipment concentrated in the Seoul Capital Area and Kanto region, with aluminum deposition chambers representing single-source bottlenecks. Tariff exposure on Chinese BOPET exports to North American solar backsheet assemblers threatens margin stability for non-integrated distributors. Distribution runs through mill-direct contracts for electronics-grade volumes and regional stocking points for mid-volume packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyester film procurement is consolidating around platform-style supplier ecosystems where lot-level traceability APIs interoperate with customer ERP systems, mirroring the qualification data exchange protocols Samsung and LG now mandate across tier-2 assemblers.
For Market Incumbents: Harden captive resin supply positions through backward integration into PTA polymerization or long-term offtake agreements with catalyst-certified resin producers. Lock in multi-year metallization capacity reservations before vacuum deposition equipment lead times extend further. Antimony-free catalyst transitions under ECHA REACH restrictions threaten reformulation costs for European converter customers. For New Entrants and Emerging Players: Pursue direct-to-converter digital platforms serving Vietnam and India electronics assemblers with customized slit-width deliveries, bypassing traditional regional distributor markups. Battery separator M-PET for dry-process electrode manufacturing represents the most penetrable specification tier due to capacity shortages among incumbent producers. Qualify under MFDS pharmaceutical-grade protocols to access blister-pack barrier demand with lower customer concentration risk than display supply chains. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates seeking to divest non-core film extrusion assets amid feedstock volatility and carbon-transition capital reallocation. Precision coating specialists with cleanroom certifications and existing electronics customer relationships offer the strongest long-term viability through the next decade. Watch for inflection signals in rPET food-contact approval timelines at FDA and EFSA, as recycled-content mandates accelerate qualified supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Polymerization | Captive resin supply locks in margin stability against ethylene glycol price swings. |
| Vacuum Metallization Capacity Expansion | Additional aluminum deposition chambers relieve bottlenecks for battery separator M-PET demand. |
| Antimony-Free Catalyst Transition | Titanium-based polymerization chemistry secures EFSA food-contact approval for European converters. |
| rPET Food-Contact Certification Investment | Verified chain-of-custody documentation captures premium tiers under EU Extended Producer Responsibility frameworks. |
| Direct-to-Converter Digital Platform Launch | Bypassing regional distributors reduces working capital intensity for Vietnam and India electronics assemblers. |
Methodological Framework
Cross-validation between primary interviews with film extrusion plant managers, electronics procurement leads at display assemblers, and distribution channel partners anchors the qualitative findings against secondary validation from customs trade data, SEC 10-K filings of petrochemical producers, and MEE emissions enforcement records. Bottom-up capacity modeling triangulates against top-down consumption estimates derived from downstream electronics and packaging production indices.
Calibration against historical price spreads between optical-grade and commodity BOPET specifications informs elasticity assumptions across the projection horizon. Segmentation dimensions include manufacturing process type, thickness specification tier, end-use application, and regional regulatory cluster. CAGRs derive from installed capacity expansion announcements, customer qualification timeline data, and substitution elasticity estimates for barrier coating technologies.
Sensitivities concentrate around rPET food-contact approval delays, PFAS barrier substitution timelines, and East Asian electronics production volatility. Forecasts reflect documented assumptions regarding catalyst chemistry transitions and metallization equipment delivery schedules. Cross-checking against IHS Markit polymer trade flow data and Cefic plastics production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Poly Coated Kraft Paper Market
Poly film
North America Polyimide Films Market
Poly film
Polyethylene Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Polycarbonate Films Market
Poly film
Polysaccharide Films Market
Poly film
PCR Bubble Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
North America BOPP Films Market
Poly film
Soft Touch Film Market
Poly film
Surface Printed Film Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Polystyrene Films Market
Poly film
China Plastic Packaging Film Market