
 MMA Film & Sheet Market | 2026-2036
MMA Film & Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
MMA Film & Sheet Market Insights
Buyer concentration in the electronics display supply chain is shifting as panel makers consolidate procurement around fewer qualified substrate vendors. Mitsubishi Chemical Corporation leverages captive methyl methacrylate supply to anchor its film operations in Japan. Chi Mei Corporation competes through specialized optical-grade formulations serving Taiwanese display foundries. Evonik Industries AG differentiates via high-purity PMMA extrusion technology for European automotive glazing applications.
MMA film and sheet denotes cast or extruded polymethyl methacrylate substrates ranging from 0.05 mm films to 10 mm sheets, valued for 92% light transmission, UV stability, and surface hardness exceeding 2H pencil grade. Transparent film dominates packaging and display stack applications where optical clarity commands premium positioning. Coated sheet variants are gaining fastest in automotive interior trim as OEMs replace glass with weight-saving polymers. Electronics application demand leads volume growth, while construction-grade laminated sheet retains mature, price-sensitive positioning across distributor channels.
REACH registration requirements in Europe and China's GB standards under SAMR enforce monomer residual limits below 0.1% in food-contact grades. The EPA and OSHA jointly govern volatile organic compound emissions during MMA sheet casting operations in the United States. FDA compliance for indirect food contact remains mandatory for packaging film sold into North American consumer goods channels. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode margin pools in standardized product lines.
Market Dynamics
Electronics display manufacturers are consolidating substrate procurement around qualified vendors capable of meeting tightening optical purity specifications, compressing supplier margins while rewarding scale and certification depth.
Growth Catalysts
- Optical-grade specification tightening:Panel makers in South Korea's Seoul cluster now mandate sub-0.05% haze coefficients for cover substrates, pulling premium film volumes from qualified extruders.
- Automotive weight-reduction mandates:OEM glazing specifications in Germany and Japan explicitly permit PMMA substitution for tempered glass in non-structural interior applications.
- Methyl methacrylate supply security:Captive monomer integration among Japanese chemical conglomerates insulates film operations from feedstock volatility affecting merchant purchasers.
Market Restraints
- Acetone cyanohydrin cost volatility:The dominant MMA synthesis route exposes producers to hydrogen cyanide and acetone price swings that compress extrusion margins unpredictably.
- East Asian supply concentration:Over 60% of optical-grade sheet capacity sits within 200 kilometers of Seoul, creating single-point vulnerability to regional logistics disruptions.
- Polycarbonate substitution in automotive:Bayer and SABIC formulations now achieve comparable light transmission at lower unit cost for non-premium vehicle interior segments.
Strategic Opportunities
- Indian electronics manufacturing incentives:PLI scheme subsidies for display module assembly in Tamil Nadu and Karnataka create first-mover substrate qualification windows.
- UV-curable hardcoat convergence:Combination of nanoceramic surface treatment with cast PMMA substrates enables 3H pencil hardness without thermal curing bottlenecks.
- SAMR food-contact pathway expansion:China's revised GB 4806 standards for indirect food contact open packaging film applications previously restricted to PET and PP.
Industry Challenges
- Optical metrology talent scarcity:Qualified technicians capable of operating interferometric haze measurement equipment command 40% wage premiums in East Asian manufacturing zones.
- REACH SVHC screening timelines:European substance of very high concern notifications now require 18-month reformulation cycles that freeze product development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MMA Film & Sheet Market |
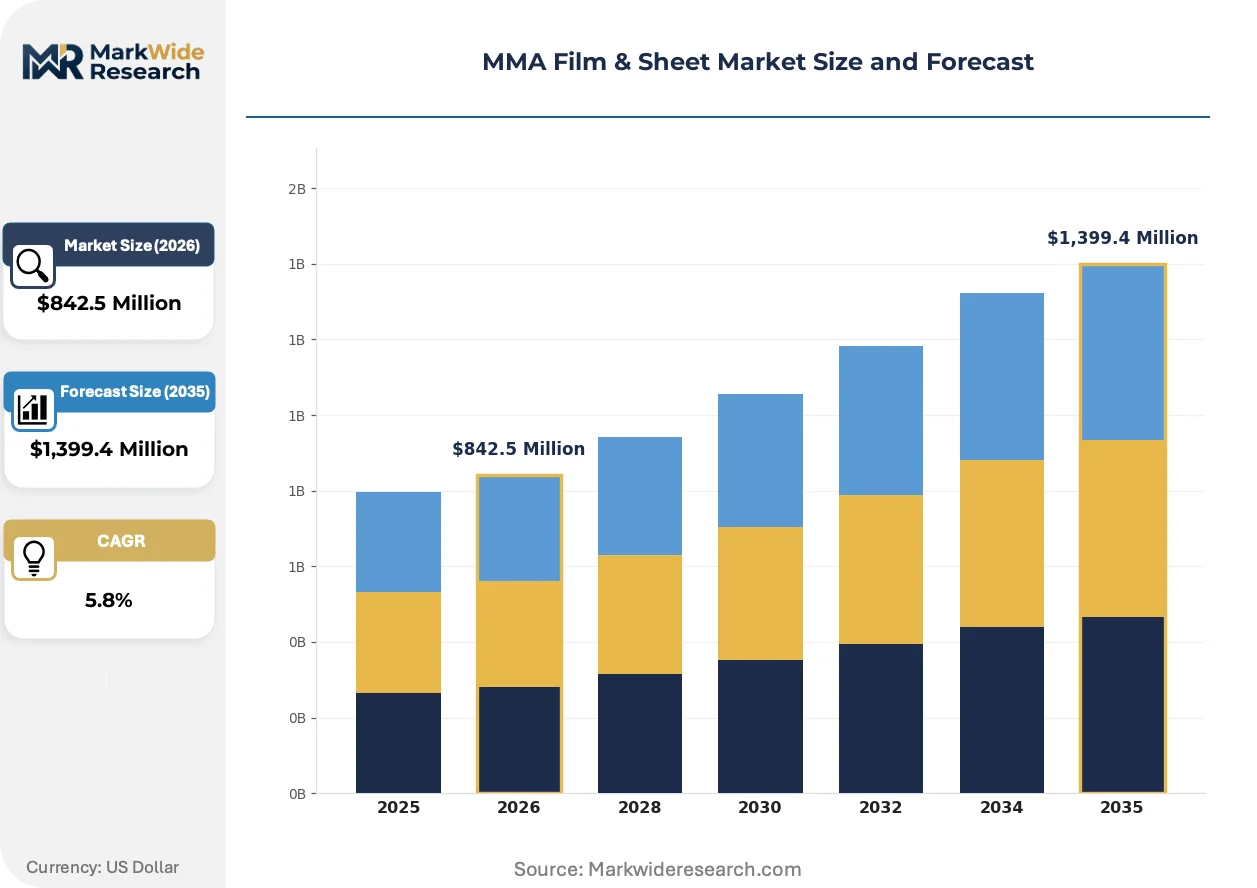
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,399.4 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Film, Colored Film, Coated Sheet, Laminated Sheet Application: Packaging, Construction, Automotive, Electronics End User: Food Industry, Consumer Goods, Healthcare, Industrial Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Sumitomo Chemical Co., Ltd., LG Chem Ltd., Mitsubishi Chemical Corporation, Formosa Plastics Corporation, LOTTE Chemical Corporation, Arkema Group, Chi Mei Corporation, BASF, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MMA Film & Sheet Market Trends and Innovations
Cast and extrusion process control systems are integrating real-time spectroscopic monitoring, collapsing defect detection latency from batch sampling to continuous feedback loops that reshape quality assurance economics.
Multi-layer coextrusion die technology is automating thickness uniformity control across 2-meter web widths, enabling Korean display substrate manufacturers to reduce optical compensation film stack complexity. Samsung Display and LG Display procurement specifications now prioritize suppliers with closed-loop gauge control. The technology is automating manual inspection headcount reduction while tightening thickness tolerance bands to ±1.5 micrometers.
REACH Annex XVII restrictions on monomer residuals are tightening enforcement across German and French conversion facilities, forcing reformulation of legacy casting formulations. ECHA compliance audits now target residual MMA levels in food-contact sheet below 50 parts per million. European automotive glazing suppliers are accelerating migration to high-purity extrusion grades to preempt regulatory disqualification.
Panel makers are unbundling substrate procurement from finished module contracts, creating direct vendor relationships that bypass traditional distributor markups. Korean and Taiwanese display foundries now negotiate annual volume commitments directly with Mitsubishi Chemical and Chi Mei extrusion divisions. This disintermediation concentrates price leverage with buyers possessing qualified vendor lists shorter than five approved sources.
MMA Film & Sheet Market Segmentation
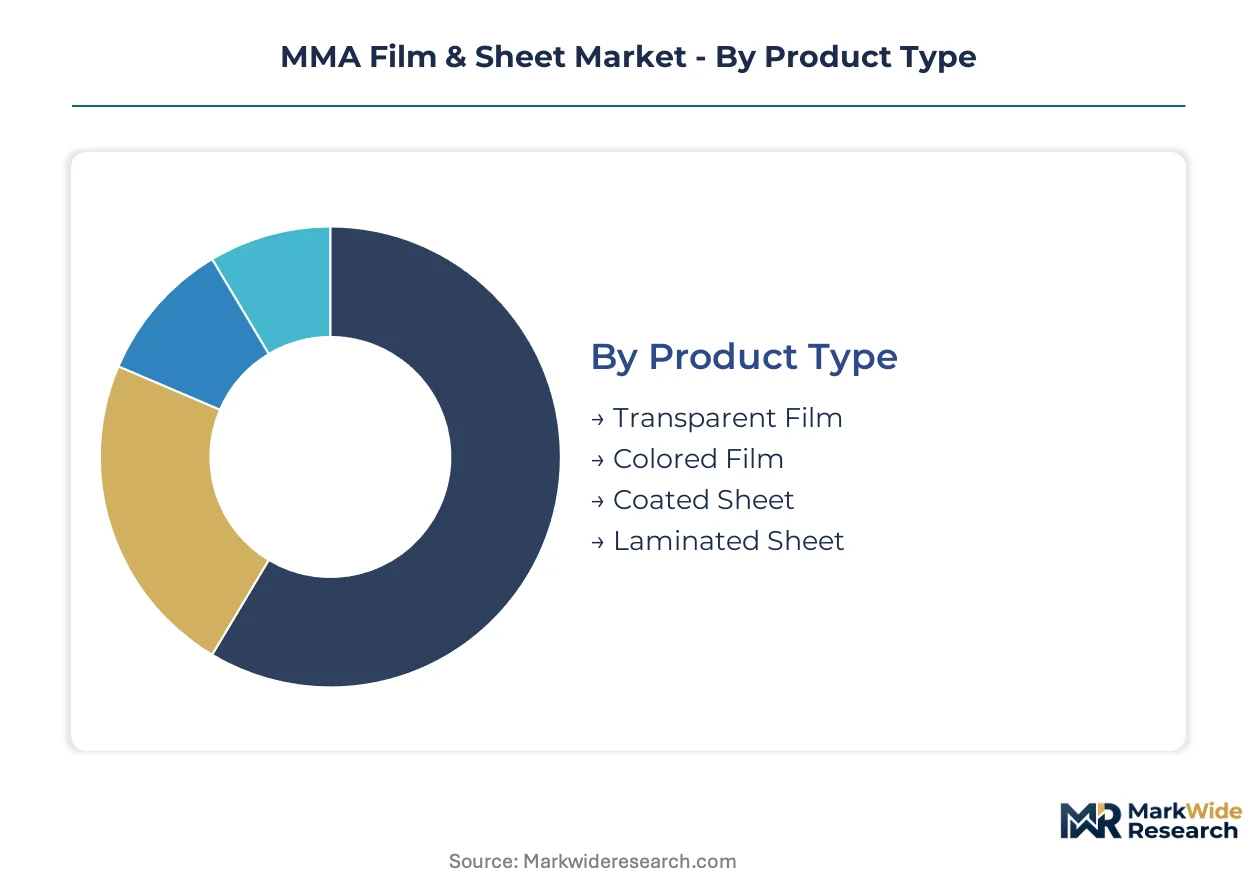
Segmentation in MMA film and sheet markets tracks how optical performance requirements, regulatory compliance tiers, and channel economics split demand across distinct specification bands. Each category reveals where margin pools concentrate and where substitution threats loom.
Product Type:
Upgrade cycles in display and automotive glazing are pushing buyers toward higher-specification substrates with embedded surface functionality.
- Transparent Film:Cast or extruded PMMA substrates with 92% light transmission and sub-0.05% haze coefficients serve as cover layers for Korean and Taiwanese display stacks. Samsung Display and LG Display procurement mandates now require qualified vendors to maintain thickness tolerances within ±1.5 micrometers.
- Coated Sheet:UV-curable hardcoat surfaces achieving 3H pencil hardness enable automotive interior trim substitution for tempered glass under German and Japanese OEM specifications. Weight-reduction mandates in non-structural glazing applications are accelerating migration from uncoated grades.
- Colored Film:Pigmented PMMA films carry decorative and light-diffusion functions in consumer electronics housings and signage applications.
- Laminated Sheet:Multi-layer constructions with interlayers for impact resistance serve construction glazing and safety barrier applications where building codes mandate fragmentation retention.
Transparent film sits at the top of the volume ranking, with coated sheet climbing the fastest.
Application:
Cost tier differentiation separates premium optical grades from commodity construction sheet, with certification depth determining supplier access.
- Electronics:Optically clear substrates for display cover layers and touch sensor stacks command premium positioning through sub-0.1% monomer residual requirements under REACH and China's GB standards. Panel maker consolidation around Seoul-area qualified vendors is compressing merchant supplier margins.
- Automotive:Interior trim glazing and light-guide applications exploit PMMA's weight advantage over glass, with German KBA and Japanese METI specifications explicitly permitting polymer substitution in non-structural roles. Bayer and SABIC polycarbonate formulations compete on unit cost in mass-market vehicle segments.
- Packaging:Food-contact film applications face tightening SAMR GB 4806 standards in China and FDA compliance requirements in the United States, restricting qualified supplier pools.
- Construction:Laminated safety sheet and architectural glazing operate through distributor channels with mature, price-sensitive positioning and limited specification differentiation.
Electronics commands the premium tier, with automotive expanding most quickly.
End User:
Customer type segmentation tracks how regulatory exposure and volume scale reshape procurement relationships across direct and channel sales.
- Consumer Goods:Electronics manufacturers and appliance OEMs drive optical-grade film demand with direct vendor qualification requirements that bypass traditional distribution markups.
- Food Industry:Packaging converters face dual jurisdiction compliance under FDA and SAMR GB standards, with residual monomer limits below 50 parts per million in European REACH enforcement zones.
- Healthcare:Medical device housings and diagnostic equipment panels require sterilization-stable substrates with biocompatibility documentation.
- Industrial:Machinery guarding and process equipment glazing prioritize impact resistance and chemical stability over optical clarity.
Consumer goods generates the largest revenue concentration, with food industry qualification windows tightening fastest.
Distribution Channel:
Supply concentration in East Asian manufacturing clusters is reshaping how substrate flows reach end-users across direct and intermediated paths.
- Direct Sales:Korean and Taiwanese display foundries negotiate annual volume commitments directly with extrusion divisions of Japanese and Taiwanese chemical conglomerates, eliminating distributor margins and concentrating price leverage with buyers.
- Distributors:Construction-grade laminated sheet and standard film products move through regional distributor networks serving fragmented building materials and signage customers.
- Online Retail:Small-format sheet and film for prototyping, hobbyist, and light commercial applications carry higher per-unit logistics costs.
- Wholesalers:Volume aggregation for commodity grades serves mid-scale converters without direct mill relationships.
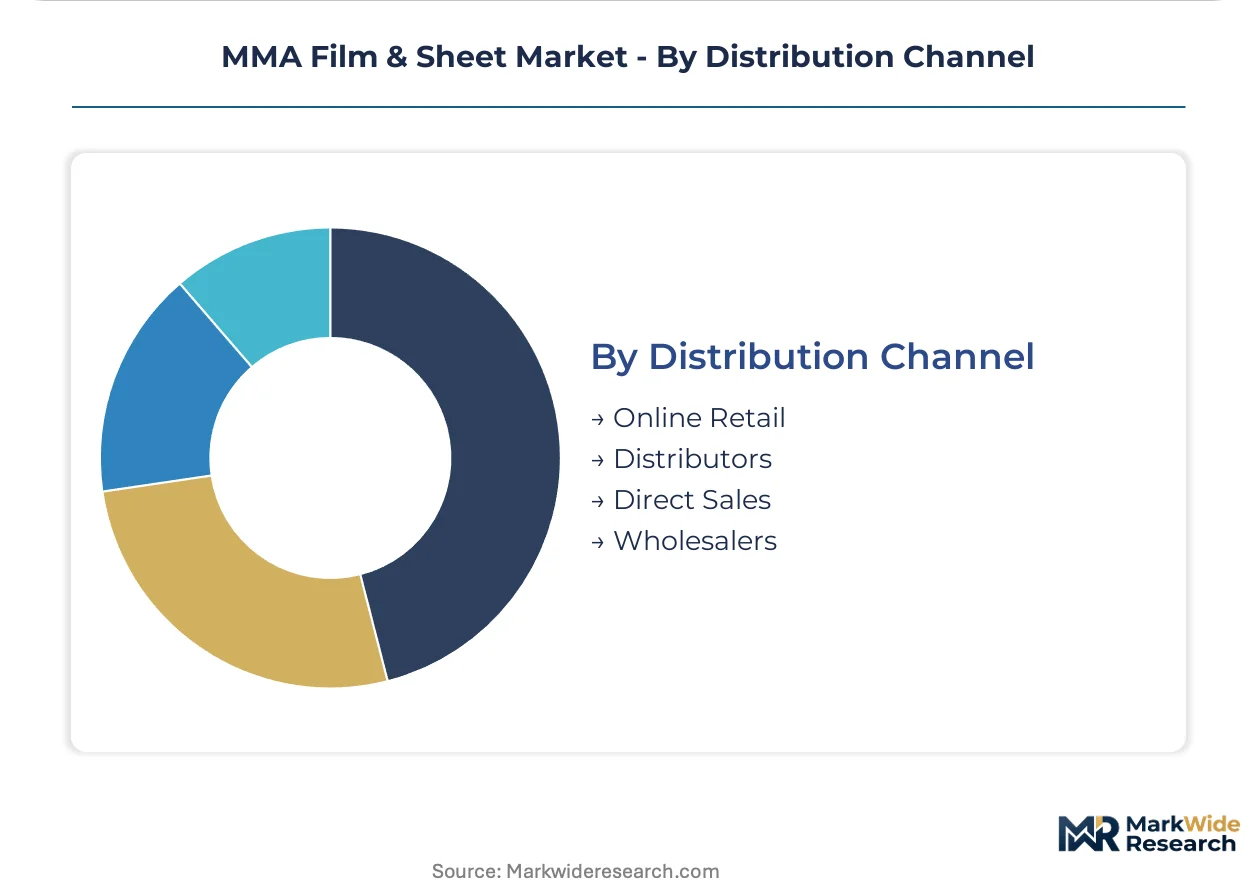
Direct sales captures the highest-value transactions, with distributor channels facing margin compression from upstream disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical metrology talent pools concentrate in East Asian manufacturing corridors, with qualified technicians commanding wage premiums that reshape regional investment decisions. German and Japanese automotive glazing clusters compete for polymer substrate volumes through divergent certification pathways. Indian electronics assembly incentives are redrawing procurement geography for display stack materials.
South Korea
Samsung Display and LG Display procurement mandates drive sub-0.05% haze coefficient requirements for cover substrates. MFDS enforces residual monomer limits below 50 parts per million in food-contact applications. The Seoul Capital Area hosts over 60% of qualified optical-grade sheet capacity within 200 kilometers, creating logistics-dependent supply vulnerability.
China
SAMR's revised GB 4806 standards for indirect food contact open packaging film applications previously restricted to PET and PP. MIIT dual carbon goals pressure casting facilities to reduce volatile organic compound emissions. The Yangtze River Delta and Pearl River Delta clusters house expanding extrusion capacity serving domestic display module assembly.
Japan
METI specifications explicitly permit PMMA substitution for tempered glass in non-structural automotive interior applications. JIS standards govern surface hardness certification for coated sheet variants. The Chubu region around Nagoya anchors captive methyl methacrylate integration among chemical conglomerates, insulating film operations from feedstock volatility.
Germany
KBA automotive glazing specifications accelerate migration from glass to polymer substrates in weight-reduction mandates. ECHA REACH Annex XVII enforcement targets residual MMA levels below 50 parts per million in food-contact sheet. The North Rhine-Westphalia corridor concentrates European extrusion capacity serving automotive OEM qualification programs.
United States
FDA compliance for indirect food contact remains mandatory for packaging film sold into North American consumer goods channels. EPA and OSHA jointly govern volatile organic compound emissions during MMA sheet casting operations. The Southeast manufacturing belt attracts automotive interior trim converters seeking proximity to OEM assembly plants.
MMA Film & Sheet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. Japanese and Korean chemical conglomerates leverage captive monomer supply to anchor film operations against feedstock volatility. Three archetypes dominate: integrated petrochemical majors with backward control over methyl methacrylate, specialized optical-grade extruders serving display foundries, and diversified materials suppliers spanning multiple polymer classes. Competitive moves concentrate on capacity expansion in East Asian manufacturing clusters and strategic partnerships for UV-curable hardcoat technology licensing.
Among Japanese chemical conglomerates, Mitsubishi Chemical Corporation exemplifies the integrated archetype through captive methyl methacrylate supply. Chi Mei Corporation occupies a specialist position serving Taiwanese display foundries with optical-grade formulations. Evonik Industries AG anchors the European premium tier through high-purity extrusion technology for automotive glazing applications. These three represent divergent strategic postures: upstream integration, customer-proximate specialization, and technology-driven differentiation.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd. |
| LG Chem Ltd. |
| Mitsubishi Chemical Corporation |
| Formosa Plastics Corporation |
| LOTTE Chemical Corporation |
| Arkema Group |
| Chi Mei Corporation |
| BASF |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Captive methyl methacrylate integration among Japanese chemical conglomerates anchors supply security and pricing power against feedstock volatility affecting merchant purchasers. This upstream control insulates optical-grade film operations from acetone cyanohydrin cost swings while compressing margins for extruders lacking backward integration into monomer production.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade construction sheet while premium optical film retains margin insulation. Three-tier pricing structure across optical-grade, automotive-certified, and construction-standard levels separates qualified display substrate vendors from commodity extruders. Pricing pressure stems from polycarbonate substitution in mass-market automotive interiors where Bayer and SABIC formulations undercut PMMA on unit cost. Construction distributors exhibit highest price sensitivity due to fragmented demand and limited specification differentiation.
Supply Chain Analysis
Optical metrology technician shortages in South Korea's Seoul Capital Area and Japan's Chubu region constrain qualified extrusion capacity expansion. Manufacturing concentrates in South Korea, Japan, and China where over sixty percent of optical-grade sheet capacity sits within two hundred kilometers of Seoul. Feedstock dependencies center on acetone cyanohydrin, hydrogen cyanide, and methyl methacrylate monomer with hydrogen cyanide price volatility as persistent structural risk. Distribution runs through direct mill relationships for display foundries and regional distributor networks for construction-grade products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MMA film and sheet functions as a stable compounder where electronics display procurement consolidation drives predictable premium-tier volume growth. Optical specification tightening across Korean and Taiwanese panel makers sustains qualified vendor margin pools despite commodity-grade price erosion.
For Market Incumbents: Cement captive monomer supply positions through selective upstream investments or long-term offtake agreements with methyl methacrylate producers. Deepen certification depth for REACH Annex XVII and SAMR GB 4806 compliance to preempt regulatory disqualification of legacy formulations. Polycarbonate substitution in automotive interiors and East Asian supply concentration represent primary threats requiring geographic diversification into Indian PLI scheme zones.
For New Entrants and Emerging Players: The price-point gap between premium optical-grade and economy construction sheet creates entry space for mid-tier automotive-certified extruders lacking display foundry qualification. Target Indian electronics manufacturing incentives in Tamil Nadu and Karnataka where first-mover substrate qualification windows remain open. Pursue UV-curable hardcoat technology licensing partnerships to bypass thermal curing capital intensity.
For Investors and Strategic Acquirers: Consolidation pressure builds where optical metrology talent scarcity and eighteen-month REACH SVHC reformulation cycles freeze smaller competitors' product pipelines. Long-term viability favors integrated petrochemical majors with backward methyl methacrylate control and specialized optical-grade extruders serving consolidated display procurement. Monitor Korean panel maker unbundling of substrate procurement from module contracts as inflection signal for direct vendor relationship value capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methyl Methacrylate | Captive monomer supply insulates Japanese conglomerates from acetone cyanohydrin volatility. |
| UV-Curable Hardcoat Technology Licensing | Nanoceramic surface treatment enables 3H pencil hardness without thermal curing bottlenecks. |
| Capacity Expansion in Indian PLI Zones | Tamil Nadu and Karnataka assembly incentives create first-mover substrate qualification windows. |
| REACH Annex XVII Compliance Investment | ECHA audits targeting residual MMA below fifty ppm preempt food-contact disqualification. |
| Direct Sales Relationship Development | Annual volume commitments with Samsung Display and LG Display eliminate distributor margin capture. |
Research Methodology
Bottom-up electronics and automotive demand modeling reconciled against top-down methyl methacrylate supply tracking forms the analytical core of this study. Primary interviews with extrusion plant managers, procurement leads at Korean display foundries, distribution channel partners, and technical R&D directors combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and SAMR regulatory publications. Triangulation between consumption-side qualification requirements and production-side capacity announcements ensures statistical integrity.
Input-output matrices map MMA monomer availability through extrusion capacity to end-use demand across product type, application grade, and regional manufacturing hub segmentation. CAGRs derive from volume trajectory modeling throughout the forecast period incorporating optical specification tightening timelines, automotive weight-reduction mandate adoption curves, and regulatory compliance phase-in schedules. Forecast inputs include panel maker procurement consolidation patterns and PLI scheme subsidy disbursement rates.
Caveats apply where acetone cyanohydrin cost spikes, East Asian logistics disruptions, or REACH SVHC notification delays could materially shift the outlook. Forecasts reflect assumptions regarding stable methyl methacrylate supply integration and continued display substrate specification tightening without sudden polycarbonate technology breakthroughs. Material deviation in hydrogen cyanide pricing, Korean-Taiwanese panel maker procurement restructuring, or Indian electronics assembly incentive continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
China Paper Packaging Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Decal Paper Market
Paper & Paperboard Packaging
Cushioned Mailer Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Paper Boxes Market
Paper & Paperboard Packaging
China Corrugated Packaging Market