
 Twist Up Stick Container Market | 2026-2036
Twist Up Stick Container Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Up Stick Container Market Outlook
Aftermarket refill programs is reshaping margin distribution between virgin packaging and closed-loop supply systems. EASTAR COSMETICS PACKAGING leverages vertical integration across mold fabrication and finished assembly to capture value upstream. Wormser Corporation anchors its position through specialized pharmaceutical-grade production lines. Attop Packaging differentiates via bamboo and bio-based material portfolios targeting sustainability-minded beauty brands.
A twist up stick container is a cylindrical dispensing package with a helical-thread base mechanism that advances or retracts solid or semi-solid product through rotational force, typically manufactured through injection molding of polypropylene or polystyrene with tolerances of 0.1 mm for smooth actuation. The design serves cosmetic, pharmaceutical, and personal care applications requiring controlled dosage, portability, and product protection from contamination. Cosmetic and pharmaceutical product types command the deepest margin pools due to formulation compatibility demands and regulatory documentation requirements. Plastic material dominates unit volume but bamboo is accelerating fastest as beauty brands pursue plastic reduction commitments. Twist cap mechanisms lead in functional reliability while push-up cap variants occupy the artisan and small-batch segment where mechanical simplicity reduces tooling investment.
ISO 15378 standards for primary packaging materials and FDA 21 CFR regulations for pharmaceutical contact substances shape product design and qualification protocols in the United States, while REACH compliance in Europe governs substance restrictions in polymer formulations. EMA guidelines on packaging integrity for topical drug products further tighten validation requirements for pharmaceutical-grade stick containers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and bio-based content certification schemes as these will determine material qualification pathways and customer qualification access.
Market Dynamics
Beauty brands' plastic reduction commitments are forcing material qualification pathways to bifurcate between certified bio-based polymers and mechanically recycled feedstocks, reshaping supplier-customer contracting structures.
Growth Catalysts
- ISO 15378 pharmaceutical packaging standards:Tightened validation protocols in the United States and Europe are locking in demand for qualified primary packaging suppliers capable of documentation traceability.
- Bamboo fiber composite formulations:German and French beauty brands are accelerating material trials to meet corporate plastic-neutral targets ahead of regulatory mandates.
- Helical-thread precision molding:Advances in 0.1 mm tolerance injection molding are expanding application scope from color cosmetics into pharmaceutical stick formats requiring dose consistency.
Market Restraints
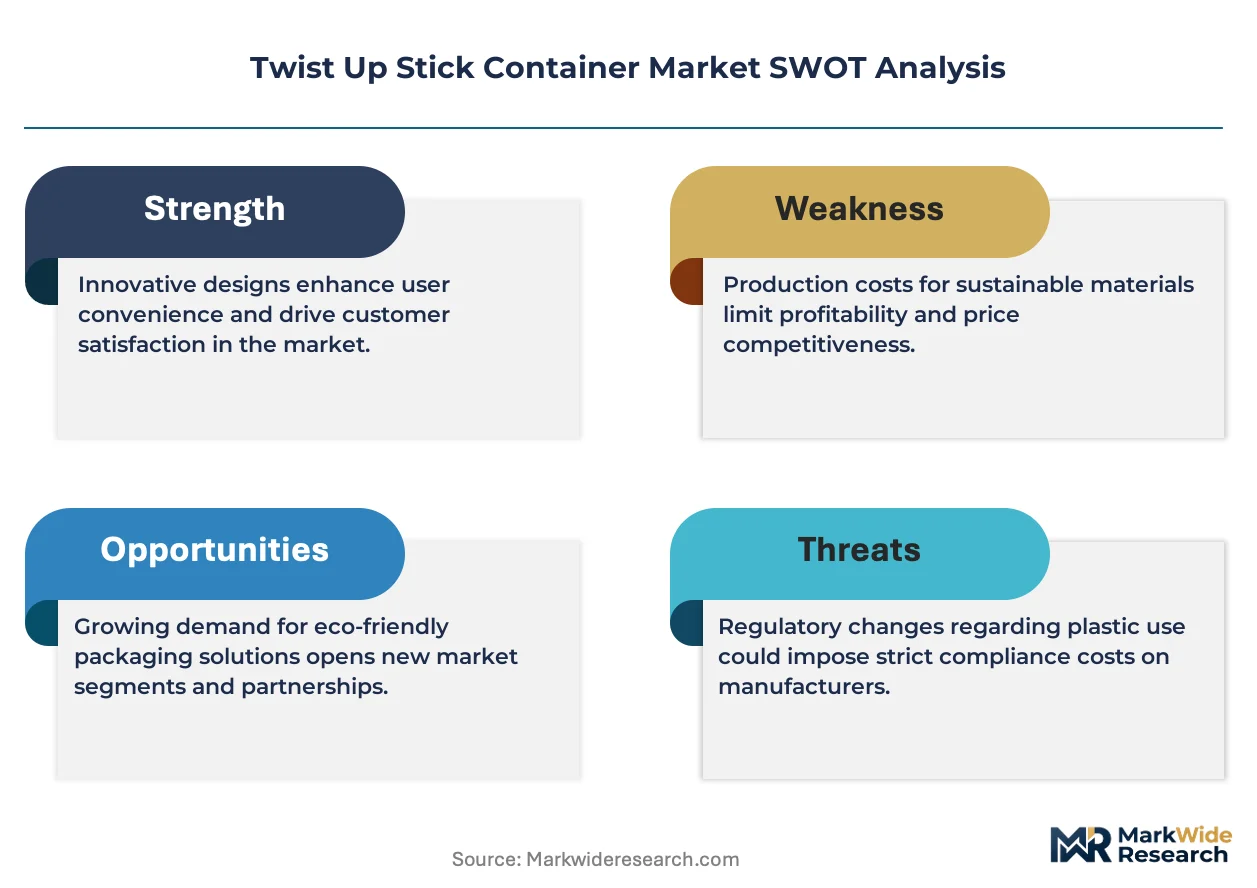
- Polypropylene feedstock volatility:Propylene monomer price swings tied to naphtha-cracking economics compress margin predictability for virgin plastic converters.
- Single-source bamboo supply concentration:Sourcing of Moso bamboo fiber concentrates in Zhejiang and Anhui provinces, exposing buyers to regional climate and harvest variability.
- REACH substance restriction complexity:ECHA's evolving SVHC candidate list creates formulation reformulation cycles that delay product qualification timelines.
Strategic Opportunities
- United States refill infrastructure buildout:Aftermarket stick refill programs remain underdeveloped relative to European loops, creating first-mover positioning for closed-loop system designers.
- Pharmaceutical topical drug expansion:EMA guidelines on packaging integrity for dermatological actives are opening qualified supplier access to prescription stick formats.
- Extended Producer Responsibility frameworks:Emerging state-level EPR legislation in California and New York will mandate minimum recycled content, advantaging early certified recyclate adopters.
Industry Challenges
- Bio-based polymer processing expertise gap:PLA and PHA blends require modified screw designs and cooling profiles that legacy polypropylene mold technicians rarely command.
- Dual certification timeline compression:Simultaneous FDA 21 CFR pharmaceutical contact qualification and ISO 9001 quality management audits strain smaller converter resource allocation.
- Legacy ERP integration with traceability platforms:Blockchain-enabled batch tracking systems demanded by beauty brand supply chain transparency programs conflict with decades-old MRP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Up Stick Container Market |
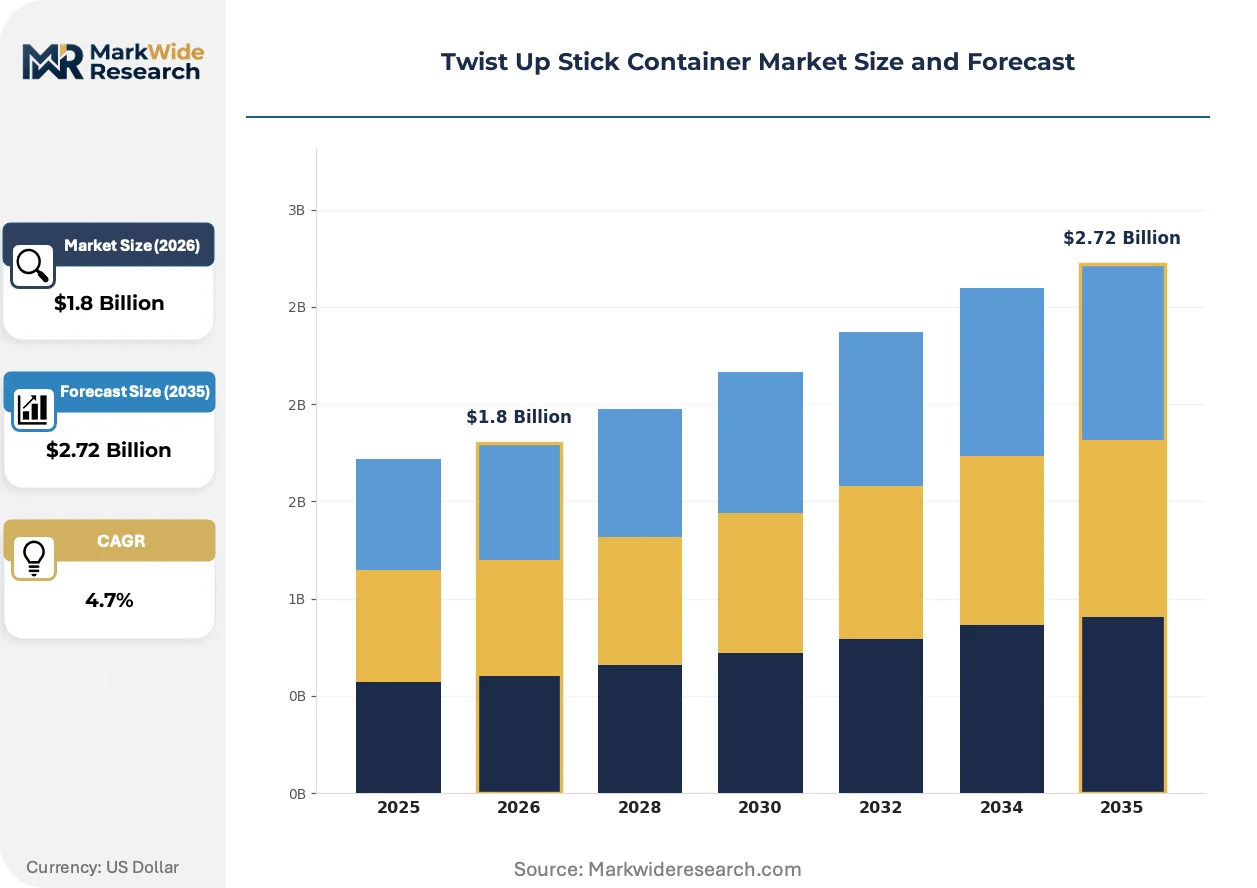
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic, Pharmaceutical, Deodorant, Sunscreen Material: Plastic, Glass, Metal, Bamboo Cap Type: Twist Cap, Push-Up Cap, Snap Cap, Flip Cap End User: Beauty Brands, Pharmaceutical Companies, Retailers, Manufacturers |
| Companies Covered | EASTAR COSMETICS PACKAGING, Wormser Corporation, Voyageur Soap & Candle Company, Majestic Mountain Sage, Sheer Treasures Company, Dormex Containers, Bramble Berry, Plant Therapy Essential Oils, Attop Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Up Stick Container Market Strategic Shifts
Material science breakthroughs and regulatory stringency are converging to compress traditional qualification timelines while fragmenting the supplier base into specialty-certified tiers.
Single-material polypropylene designs with integrated living hinges are rendering obsolete multi-component assemblies requiring separate cap and base molding operations. Mid-tier beauty brands in South Korea and Japan are adopting these simplified formats at pilot scale ahead of full portfolio transitions. The structural consequence is collapsing tooling amortization periods and shifting margin capture toward mold fabrication specialists with rapid prototyping capabilities.
EMA guidelines on packaging integrity for topical drug products are tightening validation requirements for pharmaceutical-grade stick containers across European manufacturing sites. The industrial consequence is forcing converters to maintain dedicated clean-room production lines with segregated quality systems. Dermatological and hemorrhoidal therapeutic categories face the steepest compliance burden, with German and Swiss contract manufacturers accelerating third-party audit frequencies.
Direct-to-brand procurement models are displacing traditional distribution through packaging intermediaries as beauty companies build in-house sustainability compliance teams. This channel compression is most visible among indie beauty brands in California and New York that previously relied on West Coast packaging distributors for material sourcing. The shift forces converters to maintain customer-facing technical sales functions that legacy regional broker networks previously performed.
Twist Up Stick Container Market Segmentation
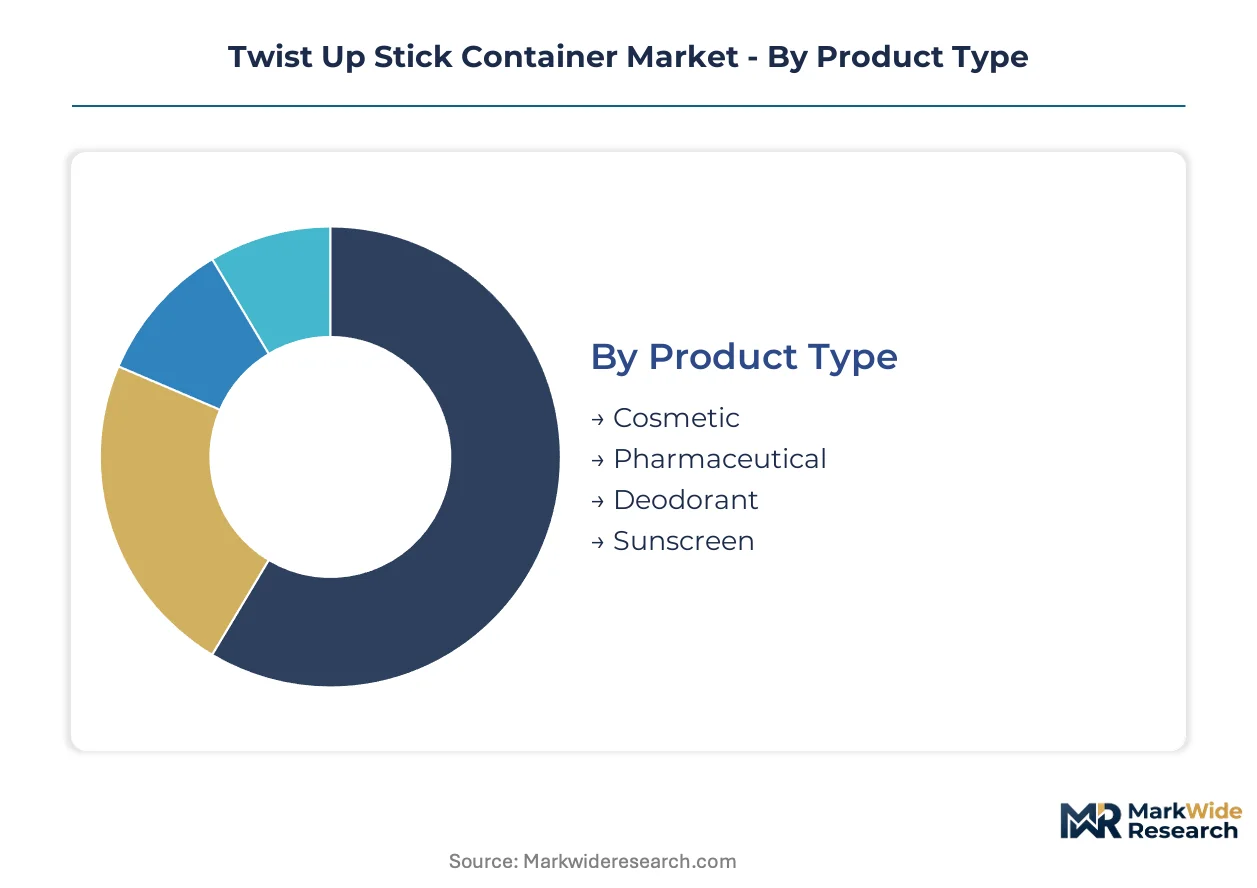
Segmentation in twist up stick containers reveals how formulation compatibility, regulatory burden, and sustainability positioning fragment supplier capabilities. Each dimension reshapes margin capture and qualification barriers differently.
Product Type:
Application determines regulatory documentation depth and formulation compatibility requirements, creating tiered supplier qualification pools.
- Cosmetic:Color cosmetics and skincare sticks demand seamless helical-thread actuation for creamy textures. Beauty brands in South Korea and Japan prioritize single-material polypropylene designs with integrated living hinges to reduce tooling costs.
- Pharmaceutical:Dermatological and hemorrhoidal therapeutic formats require FDA 21 CFR compliance and EMA packaging integrity validation. German contract manufacturers maintain segregated clean-room production lines with accelerated third-party audit frequencies.
- Deodorant:High-volume antiperspirant sticks favor polypropylene construction with twist cap mechanisms for functional reliability under humid storage conditions.
- Sunscreen:UV-filter compatibility testing narrows material selection to photostable polymers, with California-based indie brands driving bio-based polymer trials.
Cosmetic commands the established base. The steepest expansion runs through Pharmaceutical.
Material:
Cost tier stratification separates virgin polymer converters from certified bio-based specialists, with feedstock volatility compressing margin predictability at the commodity end.
- Plastic:Polypropylene dominates unit volume through injection molding at 0.1 mm tolerances. Propylene monomer price swings tied to naphtha-cracking economics strain margin forecasting for virgin converters.
- Bamboo:Moso fiber composite formulations accelerate fastest as French and German beauty brands pursue plastic-neutral targets. Sourcing concentrates in Zhejiang and Anhui provinces, exposing buyers to regional harvest variability.
- Glass:Premium fragrance and solid perfume applications favor glass for perceived luxury, though weight and fragility limit portable formats.
- Metal:Aluminum sleeves serve high-end color cosmetics with magnetic closure integration, commanding tooling premiums for small-batch artisan brands.
Plastic retains volume leadership. Bamboo gains share fastest on sustainability commitments.
Cap Type:
Mechanical complexity separates mass-market reliability requirements from artisan simplicity preferences, reshaping tooling investment recovery periods.
- Twist Cap:Helical-thread precision mechanisms deliver dose consistency for pharmaceutical and cosmetic applications. Advances in tolerance control expand use into prescription stick formats requiring exact dosage.
- Push-Up Cap:Mechanical simplicity reduces tooling investment for small-batch producers. Artisan brands in California and New York favor this format for limited-run product launches.
- Snap Cap:Audible closure feedback serves child-resistant packaging mandates for certain pharmaceutical categories.
- Flip Cap:One-handed operation suits deodorant and sunscreen applications where convenience drives repurchase intent.
Twist Cap anchors functional reliability standards. Push-Up Cap climbs fastest in indie brand procurement.
End User:
Customer type determines procurement channel structure, with direct-to-brand models displacing traditional distribution intermediaries among sustainability-focused buyers.
- Beauty Brands:Corporate plastic reduction commitments force material qualification bifurcation between certified bio-based polymers and mechanically recycled feedstocks. In-house sustainability compliance teams now handle direct converter relationships.
- Pharmaceutical Companies:ISO 15378 validation protocols and FDA 21 CFR documentation requirements lock in qualified primary packaging suppliers. Dual certification timelines strain smaller converter resource allocation.
- Retailers:Private-label stick formats prioritize cost-engineered polypropylene with standardized twist cap mechanisms for inventory efficiency.
- Manufacturers:Contract manufacturing organizations in Germany and Switzerland integrate packaging procurement into turnkey formulation services.
Beauty Brands drive material innovation agendas. Pharmaceutical Companies impose the steepest qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene injection molding capacity clusters in Zhejiang and Guangdong provinces, while pharmaceutical-grade clean-room production concentrates in Germany and Switzerland. Bamboo fiber sourcing ties converters to specific harvest regions in eastern China. Regulatory divergence between FDA pharmaceutical contact standards and EMA packaging integrity protocols forces dual-track qualification investments.
United States
California and New York indie beauty brands drive direct-to-brand procurement models, bypassing traditional packaging distributors. FDA 21 CFR pharmaceutical contact substance regulations govern dermatological stick formats. Greater Los Angeles hosts contract manufacturers accelerating bio-based polymer trials for sunscreen applications.
Germany
French and German beauty brands accelerate Moso bamboo fiber composite trials to meet corporate plastic-neutral commitments. EMA guidelines on packaging integrity for topical drug products tighten validation protocols for pharmaceutical-grade containers. Swiss and German contract manufacturers in the Baden-Württemberg region maintain segregated clean-room production lines with accelerated third-party audit frequencies.
China
Zhejiang and Anhui provinces concentrate Moso bamboo fiber supply for composite formulation converters. The country's national pharmaceutical regulator enforces Good Manufacturing Practice standards for primary packaging materials. Guangdong injection molders supply helical-thread precision components at 0.1 mm tolerances for South Korean and Japanese beauty brand procurement.
Japan
South Korean and Japanese beauty brands pilot single-material polypropylene designs with integrated living hinges to reduce tooling amortization periods. METI circular economy guidelines encourage material reduction in cosmetic packaging. Osaka-area mold fabrication specialists capture margin shifts through rapid prototyping capabilities for simplified formats.
South Korea
Domestic beauty brands adopt pilot-scale single-material designs ahead of full portfolio transitions. MFDS pharmaceutical packaging standards align with international harmonization efforts for topical drug formats. Seoul Capital Area converters serve as technology intermediaries between Chinese mold fabrication and Japanese brand qualification requirements.
Twist Up Stick Container Market Competitive Environment
Specialized pharmaceutical-grade producers and sustainability-focused material innovators split the market into distinct capability tiers. The supplier base organizes around certification depth rather than scale, with ISO 15378 validation separating qualified primary packaging suppliers from generalist converters. Three archetypes dominate: vertically integrated mold-to-assembly operators, dedicated pharmaceutical clean-room specialists, and bio-based material portfolio builders. Competitive moves center on backward integration into mold fabrication and accelerated certification timeline compression for dual FDA-EMA qualification.
Within the pharmaceutical-grade tier, Wormser Corporation anchors specialized production line positioning. Among sustainability-focused fabricators, Attop Packaging exemplifies bamboo and bio-based material portfolio development. EASTAR COSMETICS PACKAGING occupies a position representing vertical integration across mold fabrication and finished assembly capabilities. These three entities collectively illustrate the strategic bifurcation between regulatory compliance depth and sustainability material innovation.
| Leading Market Players |
|---|
| EASTAR COSMETICS PACKAGING |
| Wormser Corporation |
| Voyageur Soap & Candle Company |
| Majestic Mountain Sage |
| Sheer Treasures Company |
| Dormex Containers |
| Bramble Berry |
| Plant Therapy Essential Oils |
| Attop Packaging |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province injection molders dominate helical-thread precision component capacity, and their 0.1 mm tolerance capabilities translate directly into pricing power over beauty brands seeking seamless actuation. Propylene monomer volatility tied to naphtha-cracking economics compresses margin predictability for virgin polypropylene converters, while Moso bamboo fiber sourcing concentration in Anhui province exposes buyers to regional harvest variability that ripples through bio-based material premiums.
Pricing Analysis
Aftermarket refill program revenue streams drive lifetime value capture as closed-loop systems displace virgin packaging margins. Three-tier pricing structure across pharmaceutical-grade, certified bio-based, and commodity polypropylene tiers reflects certification depth and formulation compatibility requirements. Cost compression in virgin plastic tiers intensifies because propylene feedstock swings strain converter forecasting, with retailer private-label procurement showing highest price sensitivity and pharmaceutical contract manufacturers exhibiting lowest.
Supply Chain Analysis
REACH substance restriction protocols on polymer formulations limit feedstock flows into European manufacturing sites, constraining qualified supplier pools. Production gravity centers on China for injection molding, Germany for pharmaceutical-grade clean-room assembly, and Switzerland for dermatological contract manufacturing. Raw material dependencies include Moso bamboo fiber from Zhejiang and Anhui, propylene monomer from naphtha crackers, and bio-based polymer resins from certified fermentation facilities. Single-source bamboo concentration creates harvest variability exposure. Distribution runs through direct-to-brand procurement channels displacing traditional West Coast packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The twist up stick container market sits in early-cycle expansion as refill infrastructure buildout and pharmaceutical topical drug format adoption accelerate penetration beyond traditional cosmetic applications.
For Market Incumbents: Harden pharmaceutical-grade clean-room certification moats against emerging bio-based specialists by accelerating dual FDA-EMA qualification timelines. Deepen backward integration into mold fabrication to capture margin shifts from simplified single-material designs with integrated living hinges. Threats include indie beauty brands' direct procurement bypassing traditional distributor networks. For New Entrants and Emerging Players: Establish a beachhead in aftermarket refill program design for California and New York indie beauty brands where closed-loop infrastructure remains underdeveloped relative to European loops. Target pharmaceutical topical drug formats as EMA packaging integrity guidelines open qualified supplier access. Go-to-market angle: blockchain-enabled batch tracking systems that resolve legacy ERP integration conflicts for supply chain transparency programs. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory divergence between FDA pharmaceutical contact standards and EMA packaging integrity protocols forces dual-track qualification investments that smaller converters cannot resource. Acquisition target archetype: mid-tier converters with ISO 15378 validation but limited bio-based material portfolios. Signal to watch: state-level Extended Producer Responsibility legislation mandating minimum recycled content thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Clean-Room Certification | EMA packaging integrity guidelines tighten validation protocols for dermatological stick formats in German manufacturing sites. |
| Bio-Based Material Portfolio Expansion | French and German beauty brands accelerate Moso bamboo fiber trials to meet corporate plastic-neutral commitments ahead of mandates. |
| Backward Integration into Mold Fabrication | Osaka-area rapid prototyping specialists capture margin shifts as South Korean and Japanese brands adopt simplified single-material designs. |
| Aftermarket Refill Infrastructure Buildout | Closed-loop system designers gain first-mover positioning in United States markets where refill programs remain underdeveloped. |
| Blockchain-Enabled Traceability Platform Integration | Beauty brand supply chain transparency programs demand batch tracking systems that conflict with legacy MRP architectures. |
Study Parameters
Initial hypotheses were tested against primary input from packaging procurement managers at beauty brands, pharmaceutical contract manufacturing executives, mold fabrication specialists, sustainability compliance officers, and distribution channel partners and refined through secondary validation against FDA 21 CFR filings, EMA packaging integrity guidelines, ISO 15378 certification databases, REACH SVHC candidate lists, and customs trade data for polypropylene and bamboo fiber imports. Bottom-up unit economics triangulated against top-down market sizing across material and application segments.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions including product type, material grade, cap mechanism, and end-user procurement channel. CAGRs were derived from trajectory modeling of adoption curves for refill infrastructure and pharmaceutical format expansion, incorporating propylene monomer price elasticity and bio-based polymer qualification timeline compression as industry-specific inputs.
Sensitivities concentrate around propylene feedstock volatility, Moso bamboo harvest variability, and EMA guideline evolution on topical drug packaging integrity. Forecasts reflect documented assumptions on certification timeline compression and refill program adoption rates. Material shifts in Extended Producer Responsibility legislative timelines or bio-based polymer processing breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pocket Containers Market
Containers
Stack and Nest Containers Market
Containers
PP Container Liner Market
Containers
Snap-Lock Container Market
Containers
Conipack Pails Market
Containers
HDPE Bottles Market
Containers
Flexible Water Tanks Market
Containers
Bulk Container Packaging Market
Containers
Food Grade Stainless Steel Container Market
Containers
Packer Bottle Market
Containers
Mini Spray Bottles Market
Containers
PS Containers Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Screw Top Jar Market
Containers
Cups and Lids Market