
 Polycarbonate Films Market | 2026-2036
Polycarbonate Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarbonate Films Market Analysis
Asian resin producers is shifting polycarbonate film capacity toward optical-grade and flame-retardant variants. Covestro AG leverages its integrated bisphenol A-to-film pipeline to sustain cost leadership across European and Asian markets. SABIC anchors its position through high-volume supply to automotive glazing programs in the Middle East and North America. Teijin Limited differentiates via specialized transparent conductive films for foldable electronics.
Polycarbonate films are thermoplastic polymer sheets manufactured through extrusion or calendering of bisphenol A-derived resin, typically offering impact resistance up to 250 times that of glass alongside optical clarity exceeding 90% light transmission. These properties position the material as a lightweight substitute for glass and acrylic across safety, display, and architectural applications. Optical film commands the dominant revenue share due to its irreplaceable role in LCD backlighting and touch-panel stacks, while protective film segments are expanding fastest as OEMs specify thicker, multi-layer coatings for automotive interior surfaces. Electrical insulation applications occupy stable margin pools within industrial motor and battery housing markets where thermal endurance requirements are tightening.
REACH in Europe, RoHS for electronics sold across EU member states, and FDA 21 CFR compliance for medical device films collectively shape formulation choices, testing burdens, and market access timelines for suppliers. China's GB standards for flame retardancy and Japan's JIS optical specifications add further layering to regional product differentiation. Stakeholders must monitor how evolving automotive interior air-quality standards and circular-economy mandates for recycled content reshape specification sheets and supplier qualification cycles.
Market Dynamics
Optical-grade polycarbonate film capacity is concentrating in China's eastern manufacturing corridor as East Asian electronics manufacturers scale display component sourcing, tightening specifications under REACH and evolving North American flame-retardant standards.
Growth Catalysts
- REACH Compliance Pressures:European ECHA enforcement is accelerating substitution of legacy substrates with polycarbonate films in medical device housings and automotive interiors, forcing formulation upgrades across the supply base.
- Foldable Electronics Proliferation:Transparent conductive film stacks for foldable smartphones and tablets are pulling optical-grade capacity expansion from Korean and Japanese display panel makers.
- Automotive Glazing Programs:Weight-reduction mandates in electric vehicle architectures are displacing tempered glass with impact-resistant polycarbonate laminates for panoramic roof systems.
Market Restraints
- Bisphenol A Feedstock Volatility:Crude oil price swings and phenol-acetone supply tightness transmit directly into polycarbonate resin cost structures, compressing extrusion margins during energy market dislocations.
- Acrylic Substitution in Cost-Sensitive Applications:PMMA films retain price advantage in signage and non-impact protective layers, limiting polycarbonate penetration in commodity-grade optical markets.
- Optical-Grade Capacity Concentration:Three integrated resin-to-film producers control the majority of high-clarity extrusion capacity, creating bottleneck risks for qualified automotive and display supply chains.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for smartphone and component production are attracting polycarbonate film qualification programs from optical and flame-retardant grade suppliers.
- Battery Housing Thermal Barriers:EV battery pack designs are specifying multi-layer polycarbonate insulation films as thermal runaway containment layers, opening industrial-grade volume pools.
- EU Circular Economy Mandates:Recycled content thresholds in packaging and automotive applications are creating first-mover advantage for film producers with mechanical recycling integration.
Industry Challenges
- Optical Metrology Talent Scarcity:Haze and light transmission testing for display-grade films requires specialized spectrophotometry expertise that outpaces current technical training pipeline output.
- Multi-Regulatory Certification Overlap:Simultaneous RoHS, REACH, FDA 21 CFR, and GB flame-retardant qualification cycles extend product launch timelines by 18-24 months for cross-border suppliers.
- Legacy Extrusion Asset Retrofit Costs:Converting standard-grade lines to optical-grade cleanroom specifications demands capital outlays that strain mid-cap producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarbonate Films Market |
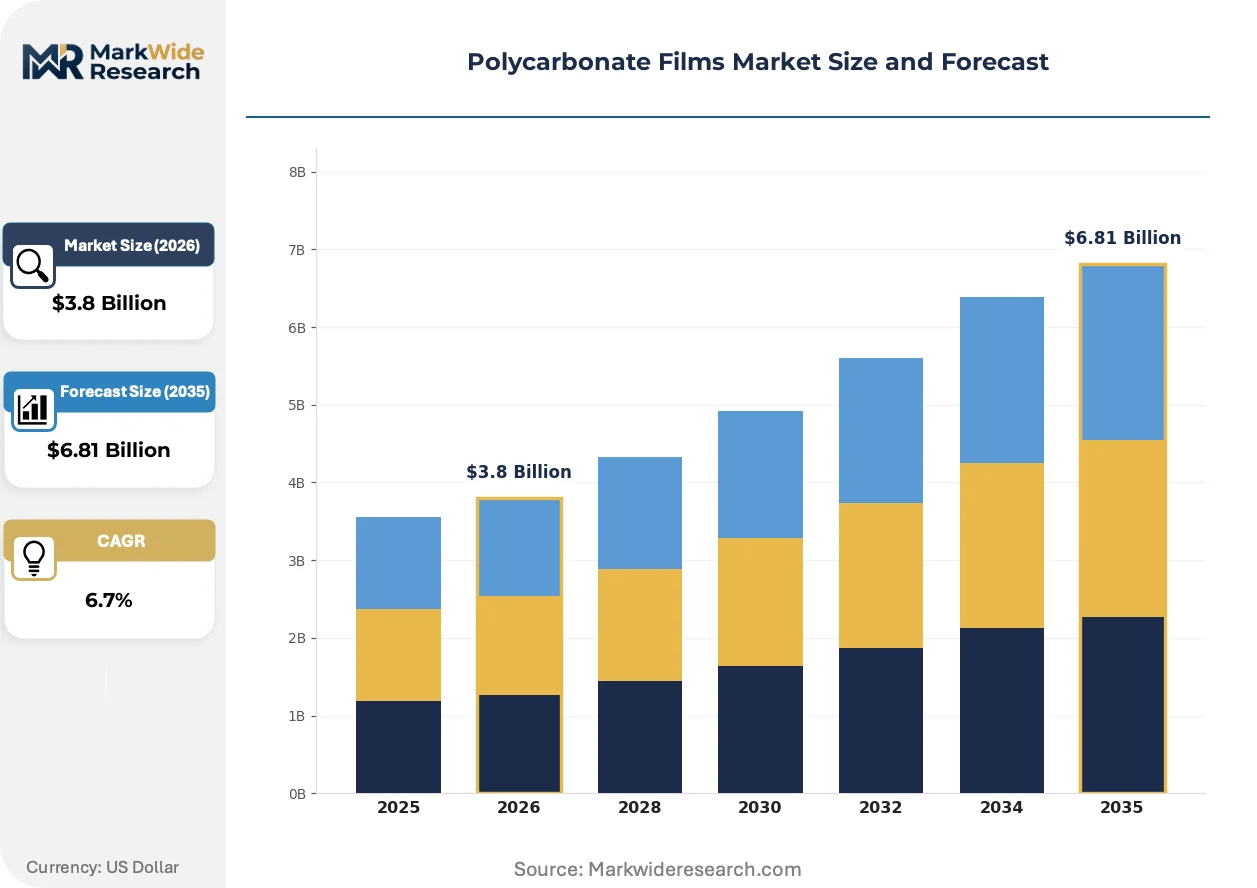
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Film, Protective Film, Electrical Insulation, Lenses End User: Automotive, Electronics, Construction, Medical Devices Application: Safety Glasses, Greenhouses, Signage, Dashboards Distribution Channel: Direct Sales, E-commerce, Distributors, Retailers |
| Companies Covered | Covestro AG, SABIC, Teijin Limited, Mitsubishi Chemical Corporation, 3M Company, Mitsubishi Gas Chemical Company, Suzhou Omay Optical Materials, DuPont, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarbonate Films Market Emerging Trajectories
Multi-layer co-extrusion architectures and surface functionalization chemistries are compressing the traditional stack-up of separate substrate, hardcoat, and adhesive films into integrated single-source supply.
Hardcoated polycarbonate film is consolidating the display cover lens market by integrating scratch-resistant siloxane layers directly during extrusion, eliminating secondary coating steps. Korean and Chinese panel makers are adopting these integrated films for tablet and automotive center-stack displays. This consolidation is compressing margins for standalone hardcoat applicators and shifting procurement toward resin-integrated film suppliers.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption in foam-core polycarbonate laminates for thermal insulation applications. Industrial refrigeration and cold-chain packaging OEMs are reformulating around lower-GWP blowing agents to maintain CE marking eligibility. German and French appliance manufacturers are driving qualification volumes for these next-generation foam structures.
Specification-driven vendor consolidation is concentrating procurement authority at tier-one automotive and electronics OEMs, displacing fragmented distributor networks with direct mill relationships. Tier-one suppliers in Germany and Japan are mandating resin traceability and lot-level optical certification that only integrated producers can satisfy. This shift is most visible in Bavaria's automotive supply cluster and Tokyo's precision electronics corridor.
Polycarbonate Films Market Segmentation
Polycarbonate film specifications diverge sharply across end-use requirements, with optical clarity, flame retardancy, and impact resistance commanding distinct formulation investments. Supply chain configuration for each segment determines qualification timelines and margin capture potential.
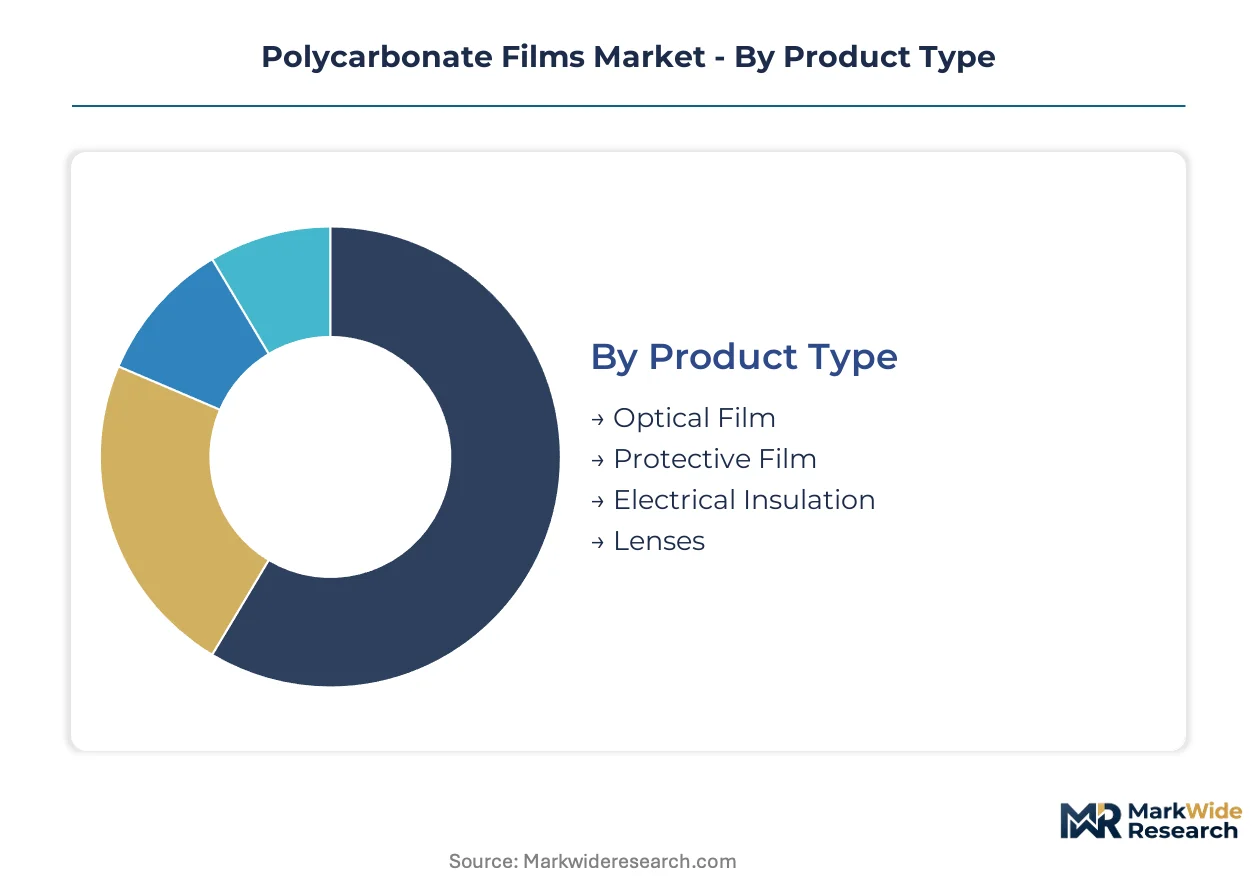
Product Type:
Optical-grade capacity concentrates among integrated resin-to-film producers in East Asia, while protective and insulation grades sustain broader supplier participation.
- Optical Film:High-transmission extrusions exceeding 90% light clarity serve LCD backlighting and touch-panel stacks. Korean and Chinese display panel makers are pulling capacity expansion for foldable electronics applications. REACH and RoHS compliance tightens formulation specifications for EU-bound supply.
- Protective Film:Multi-layer constructions with UV-stable hardcoats shield automotive interior surfaces and electronic device housings. Thickness specifications are climbing as OEMs mandate longer service-life warranties. This segment is gaining share fastest in automotive glazing programs.
- Electrical Insulation:Flame-retardant grades with thermal endurance ratings serve motor windings and battery housing markets. Industrial automation and EV architectures are stabilizing volume demand.
- Lenses:Precision-molded or thermoformed optical components for safety eyewear and lighting fixtures. Medical device and industrial PPE qualification cycles extend supplier onboarding timelines.
Today's leader: Optical Film. Tomorrow's challenger: Protective Film.
End User:
Customer procurement authority concentrates at tier-one OEMs, with direct mill relationships displacing fragmented distributor networks.
- Automotive:Panoramic roof laminates and center-stack displays specify impact-resistant polycarbonate over tempered glass. German and Japanese tier-one suppliers mandate resin traceability and lot-level optical certification.
- Electronics:Foldable smartphone and tablet manufacturers drive transparent conductive film qualification. East Asian panel makers dominate sourcing concentration.
- Construction:Architectural glazing and greenhouses balance light transmission against weathering resistance. Regional building codes vary in impact-resistance requirements.
- Medical Devices:FDA 21 CFR and EMA MDR compliance shapes housing and lens specifications for diagnostic equipment. Sterilization compatibility narrows qualified supplier pools.
Automotive procurement sets the tightest specifications; electronics offers the steepest expansion trajectory.
Application:
Functional performance requirements stratify pricing tiers, with safety-critical applications commanding premium qualification investments.
- Safety Glasses:Impact-rated optical clarity meets ANSI Z87.1 and EN 166 standards for industrial and consumer PPE. Prescription lens compatibility expands addressable demand.
- Greenhouses:UV-blocking co-extrusions balance light diffusion against thermal retention for agricultural yield optimization. EU F-Gas Regulation is accelerating hydrofluoroolefin adoption in insulated panel structures.
- Signage:Weatherable grades compete against PMMA on cost in non-impact outdoor applications. Graphic overlay films require scratch-resistant surface treatments.
- Dashboards:Soft-touch laminates with anti-glare properties integrate into automotive interior design language. VOC emission standards tighten material selection in European and North American markets.
Dashboard applications concentrate value per square meter; greenhouses present volume scale in emerging agricultural automation markets.
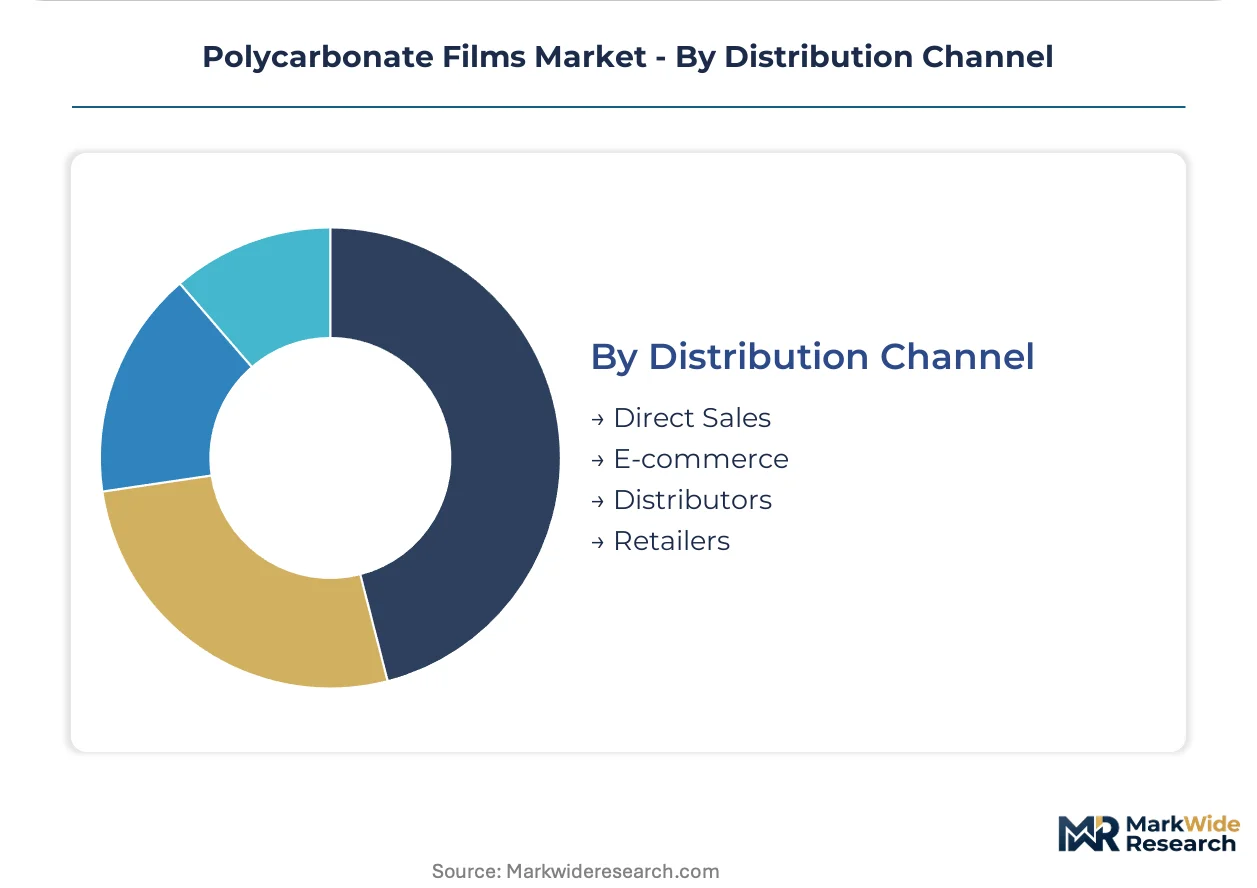
Distribution Channel:
Channel economics reflect order fragmentation and technical support intensity, with specification-driven sales favoring direct engagement.
- Direct Sales:Integrated producers serve tier-one automotive and electronics OEMs with resin traceability and customized formulation development. Long-term supply agreements lock in volume commitments.
- E-commerce:Standard-grade films for prototyping and small-batch industrial applications flow through specialized polymer marketplaces. Lead time compression competes with technical consultation depth.
- Distributors:Regional stockholding and slitting services address mid-cap manufacturers with irregular demand patterns. Inventory carrying costs pressure margin structures.
- Retailers:Consumer-facing channels for DIY safety equipment and hobbyist applications represent minimal revenue share. Brand recognition drives selection in this tier.
Direct sales capture the highest margin pool; e-commerce is climbing fastest in prototyping and small-batch segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting polycarbonate film investment toward jurisdictions where REACH-equivalent compliance costs remain lower while technical capabilities mature. Production qualification timelines stretch longest in Europe, where ECHA enforcement tightens formulation specifications, while East Asian manufacturing corridors capture volume growth through integrated resin-to-film capacity.
China
Display panel makers in Suzhou and Shenzhen are scaling optical-grade polycarbonate consumption for foldable electronics and automotive center-stack applications. GB standards for flame retardancy and MIIT industrial guidance shape local formulation requirements. The Yangtze River Delta manufacturing corridor concentrates extrusion capacity expansion as Korean and Japanese OEMs qualify Chinese suppliers for backlighting film supply.
Germany
Automotive tier-one suppliers in Bavaria mandate resin traceability and lot-level optical certification for panoramic roof laminates and interior glazing. ECHA REACH enforcement and EU F-Gas Regulation phase-down schedules drive substitution toward lower-GWP foam-core polycarbonate structures. The Stuttgart-Munich automotive supply cluster anchors European demand for high-clarity, impact-resistant film grades.
United States
Electric vehicle manufacturers specify polycarbonate laminates for weight-reduction in panoramic roof systems, displacing tempered glass across Detroit and Austin production lines. NHTSA safety standards and evolving EPA flame-retardant specifications tighten material qualification protocols. The Southeast automotive manufacturing corridor attracts film supplier qualification programs from integrated resin producers.
Japan
Transparent conductive film stacks for foldable smartphones pull specialized polycarbonate capacity from Nagoya and Osaka-area converters. METI industrial policy and JIS optical specifications maintain premium-tier entry barriers for foreign suppliers. The Kanto precision electronics corridor concentrates demand for haze-controlled extrusions in touch-panel and display cover applications.
India
Smartphone assembly under the PLI scheme is attracting polycarbonate film qualification from optical and flame-retardant grade suppliers targeting Noida and Chennai manufacturing zones. BIS standards for electronics materials and CDSCO medical device regulations shape import substitution strategies. The Maharashtra-Gujarat industrial belt is emerging as a qualification hub for display component supply to domestic OEMs.
Polycarbonate Films Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized optical and flame-retardant variants through cleanroom extrusion investments. Three integrated resin-to-film producers control the majority of high-clarity capacity, creating qualification bottlenecks for automotive and display supply chains. Strategic archetypes include integrated petrochemical conglomerates with captive bisphenol A supply, regional extrusion specialists with slitting and distribution networks, and niche converters focused on hardcoated or conductive surface functionalization. Dominant competitive moves center on backward integration into resin production and geographic expansion through joint venture extrusion assets in high-growth manufacturing corridors.
Among German-headquartered chemical conglomerates, Covestro AG exemplifies the integrated archetype through its bisphenol A-to-film pipeline control. Saudi Basic Industries Corporation represents the scale-driven petrochemical model with high-volume supply positioning. Teijin Limited occupies a specialization tier focused on advanced optical variants. These three anchors illustrate how competitive positioning stratifies across cost leadership, volume scale, and technical differentiation vectors.
| Leading Market Players |
|---|
| Covestro AG |
| SABIC |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| 3M Company |
| Mitsubishi Gas Chemical Company |
| Suzhou Omay Optical Materials |
| DuPont |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Bisphenol A feedstock costs cascade through polycarbonate film pricing tiers, with phenol-acetone supply tightness in East Asian markets compressing margins for extrusion specialists while integrated resin-to-film producers capture cost advantages in optical-grade segments. REACH compliance investments and flame-retardant certification burdens layer additional differentiation between premium qualified supply and commodity-grade alternatives.
Pricing Analysis
Distributor margins in polycarbonate film distribution typically absorb 12-18 percentage points before reaching mid-cap manufacturers, while direct-to-OEM contracts for automotive and electronics tier-one suppliers trade volume commitments against formulation development services. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade cleanroom extrusions with lot-level certification from protective films with UV-stable hardcoats and commodity signage grades. Pricing pressure stems from acrylic substitution in non-impact optical applications where PMMA retains cost advantage. Electronics panel makers exhibit highest price sensitivity due to display stack cost targets, while medical device OEMs prioritize sterilization compatibility over unit economics.
Supply Chain Analysis
Scrap reclamation and edge-trim recycling flows are gaining strategic importance as EU circular economy mandates tighten recycled content thresholds for automotive and packaging applications. Resin production concentrates in Germany, Saudi Arabia, and China, with extrusion capacity clustering in China's Yangtze River Delta and Japan's Kanto corridor. Feedstock supply draws from phenol-acetone crackers tethered to crude oil refining economics, creating margin volatility during energy market dislocations. Single-source vulnerability persists for optical-grade cleanroom extrusion lines qualified under JIS and GB standards. Distribution runs through integrated producers serving tier-one OEMs directly, supplemented by regional slitting operations for mid-cap industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycarbonate films market functions as a regulatory compounder where ECHA REACH enforcement and evolving flame-retardant standards continuously reshape formulation specifications and supplier qualification barriers. EU F-Gas Regulation phase-down schedules are accelerating demand substitution toward lower-GWP foam-core structures in thermal insulation applications.
For Market Incumbents: Hedge against acrylic substitution in commodity optical segments by deepening captive bisphenol A supply integration and accelerating hardcoated film co-extrusion investments that eliminate secondary coating steps. Capacity addition in India's PLI-corridor manufacturing zones addresses emerging smartphone assembly demand before local qualification cycles mature. Certification investment in FDA 21 CFR and EMA MDR medical device tiers defends margin pools against emerging Asian entrants.
For New Entrants and Emerging Players: Specialized distributors serving mid-cap automotive and industrial OEMs represent the most accessible channel entry point, offering technical consultation depth that e-commerce marketplaces cannot match. Battery housing thermal barrier films for EV architectures present the most penetrable white-space segment, with industrial-grade volume pools expanding faster than optical-grade capacity concentration. Target flame-retardant electrical insulation grades where qualification timelines remain shorter than medical or automotive tiers.
For Investors and Strategic Acquirers: Consolidation pressure builds where optical metrology expertise scarcity constrains cleanroom extrusion expansion and three integrated producers control majority high-clarity capacity. Mid-cap specialists with mechanical recycling integration and EU circular economy compliance positioning offer viable acquisition profiles against tightening recycled content mandates. Watch NHTSA safety standard evolution and EPA flame-retardant specification shifts as inflection indicators for automotive glazing program acceleration or deceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol A | Covestro's captive phenol-acetone supply insulates margin structures from feedstock volatility. |
| Cleanroom Extrusion Capacity Expansion | Optical-grade film qualification for foldable electronics requires JIS-compliant haze control infrastructure. |
| Mechanical Recycling Integration | EU circular economy mandates create first-mover advantage for producers with scrap-to-pellet capabilities. |
| Hardcoated Film Co-Extrusion Investment | Korean panel makers adopt integrated siloxane-layer extrusions for automotive center-stack displays. |
| Joint Venture in India PLI Corridor | Smartphone assembly incentives in Noida and Chennai attract optical-grade film qualification programs. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion plant managers, procurement leads at Korean and Chinese display panel makers, automotive tier-one supplier quality directors, and distribution channel partners with secondary validation. Secondary sources included customs and trade flow databases, SEC 10-K filings from integrated chemical conglomerates, ECHA substance volume tracking, and MIIT industrial guidance documents. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting approaches distributed projections across optical, protective, electrical insulation, and lens product types, further stratified by automotive, electronics, construction, and medical device end-use categories. CAGRs were derived from regression analysis of historical capacity expansion announcements and qualification timeline data across the projection horizon. Industry-specific forecast inputs incorporated EV battery pack thermal barrier adoption curves and foldable electronics panel production schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bisphenol A feedstock cost volatility, regulatory timeline slippage in flame-retardant standard harmonization, and optical-grade capacity concentration bottlenecks. Forecasts reflect documented assumptions regarding PLI scheme continuation and REACH enforcement intensity. Practitioners should monitor ECHA substance restriction proposals, NHTSA panoramic roof safety standard revisions, and Chinese MIIT industrial policy updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Twist Wrap Film Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
North America BOPP Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
India Plastic Packaging Film Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Global Specialty Films Polymer Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Shrink Bundling Films Market
Poly film
Japan Polypropylene Packaging Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Forming Films Market
Poly film
Printed Plastic Films Market
Poly film
Thermoforming Films Market
Poly film
PCR Bubble Films Market