
 Polystyrene Films Market | 2026-2036
Polystyrene Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polystyrene Films Market Analytics
Project finance tied to circular-economy infrastructure is narrowing the competitive field for capital-intensive film extrusion capacity. Dow Chemical Company leverages backward integration into styrene monomer supply to sustain margin stability across volatile feedstock cycles. Ohishi Sangyo Co. Ltd. anchors its position through specialized antistatic film grades for Japanese electronics OEMs. Transcendia competes via coated and laminated form factors that command premium positioning in healthcare barrier applications.
Polystyrene films are thermoplastic polymer sheets or rolls manufactured through extrusion or calendering of general-purpose or high-impact polystyrene resins, typically ranging from 12 to 500 microns in thickness and valued for dimensional stability, optical clarity, and thermoformability. These films serve primarily as substrates for printing, protective packaging layers, and dielectric insulators in electronic assemblies. General Purpose polystyrene dominates volume production due to its cost efficiency in food packaging trays and blister packs, while Antistatic formulations capture disproportionate margin pools from semiconductor and display manufacturing cleanrooms. The Roll form sustains growth through continuous-processing efficiencies in high-speed printing and lamination lines, whereas Coated variants lead value expansion as functional barriers gain traction in pharmaceutical serialization.
The EPA regulates volatile organic compound emissions from solvent-based coating operations, pushing converters toward waterborne or extrusion-coated alternatives that alter equipment investment thresholds. REACH restrictions on styrene monomer classifications shape formulation strategies for European exporters, while FDA compliance requirements for food-contact substances dictate migration testing protocols that filter supplier qualification. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to build in-house recycling capabilities or secure offtake partnerships with post-consumer polystyrene processors.
Market Dynamics
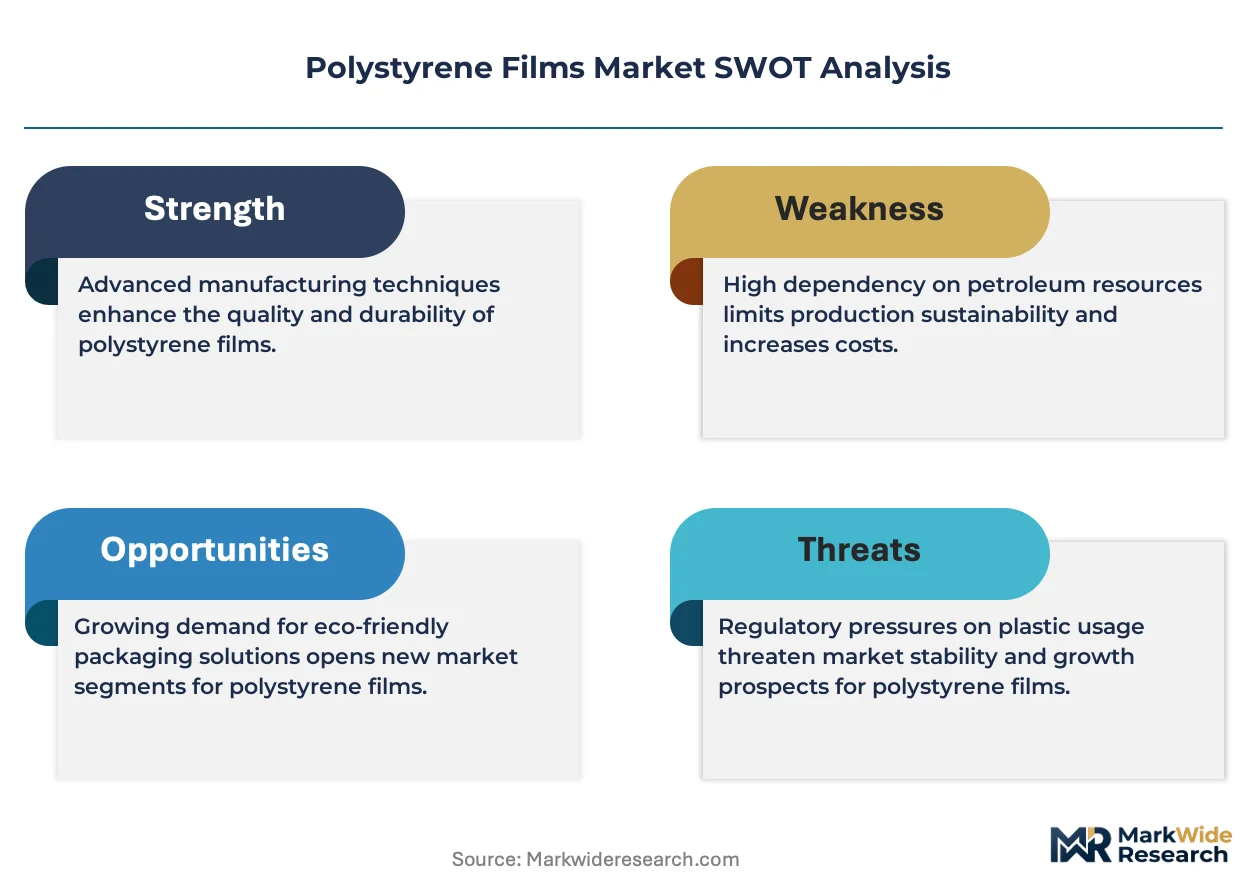
EU Green Deal packaging waste directives are forcing converters to requalify entire film formulations, compressing the supplier base as only capitalized extruders can absorb the capex for recyclable-grade production lines.
Growth Catalysts
- Food Industry barrier demand:Processors in Germany and Japan are specifying expanded polystyrene films for moisture-sensitive protein packaging, locking in volume commitments with qualified converters.
- REACH styrene reclassification:ECHA's updated monomer hazard ratings are accelerating substitution toward copolymer formulations that maintain clarity while reducing regulatory exposure.
- Automotive electronics clustering:Cleanroom-grade antistatic films are capturing expanded share from Bavarian and Baden-Württemberg OEMs as EV power electronics production concentrates in southern Germany.
Market Restraints
- Styrene feedstock volatility:Benzene-naphtha price spreads are compressing extrusion margins, particularly for non-integrated processors lacking captive monomer supply.
- Mechanical recycling limitations:Contamination sensitivity in post-consumer polystyrene streams constrains circular-economy offtake, limiting closed-loop claims in EU markets.
- Polypropylene substitution:Oriented PP films are displacing general-purpose polystyrene in cold-form blister applications where impact resistance requirements have relaxed.
Strategic Opportunities
- Pharmaceutical serialization coatings:Coated polystyrene substrates for tamper-evident packaging are penetrating serialization mandates in FDA-regulated markets.
- India food-contact expansion:FSSAI compliance investments by converters in Gujarat and Maharashtra are opening qualified supply positions for export-oriented processed food brands.
- Waterborne coating conversion:EPA VOC regulations are creating first-mover advantages for extruders with installed electron-beam or extrusion-coating capacity.
Industry Challenges
- Migration testing bottlenecks:FDA food-contact notification timelines are extending supplier qualification cycles, freezing capacity allocation decisions for 18-24 months.
- Extrusion line reconfiguration:Multi-layer barrier film investments require simultaneous coating and metallization upgrades, straining mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polystyrene Films Market |
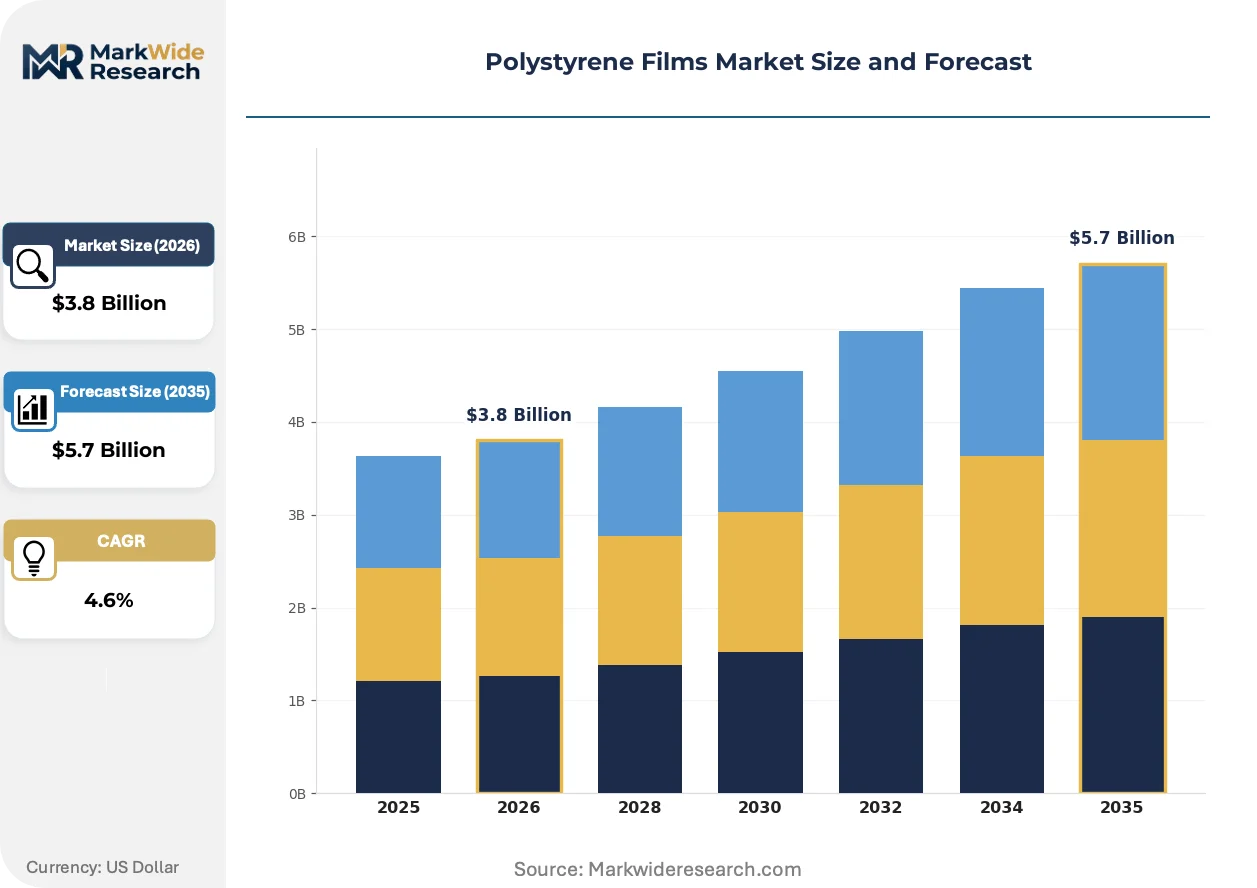
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, High Impact, Expandable, Antistatic Application: Packaging, Printing, Electronics, Household Goods Form: Sheet, Roll, Coated, Laminated End User: Food Industry, Consumer Electronics, Healthcare, Retail |
| Companies Covered | Multi-Plastics, Inc., Transcendia, TEKRA (A Division of EIS, Inc.), Cheever Specialty Paper & Film, LAIWELL GROUP INT'L, Dow Chemical Company, Norflex, Ohishi Sangyo Co. Ltd., Senoplast Klepsch & Co GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polystyrene Films Market Evolving Landscape
Digital process controls and inline quality systems are compressing specification drift in high-speed film production, enabling tighter tolerance bands that were previously unattainable at commercial throughputs.
Inline spectroscopic thickness monitoring is digitizing real-time gauge control across cast and blown polystyrene lines. Japanese electronics OEMs in Aichi and Osaka prefectures are mandating sub-micron uniformity certificates for antistatic film deliveries. The technology is digitizing quality assurance workflows, collapsing the traditional offline lab testing interval from hours to seconds.
REACH Annex XVII restrictions on intentionally added microplastics are reshaping additive strategies for European film exporters. ECHA's 2023 guidance on polymer fragmentation is forcing reformulation of traditional impact modifiers and slip agents. Medical packaging converters in Ireland and the Netherlands are accelerating qualification of bio-based alternatives ahead of 2027 enforcement windows.
Consolidated buying by pan-European food retailers is compressing supplier panels and demanding standardized sustainability certifications. Aldi and Lidl procurement teams in Germany are requiring ISCC PLUS chain-of-custody documentation for all polystyrene packaging films. The shift is most visible in fresh produce tray applications, where qualified supplier lists have contracted from twelve to four converters since 2022.
Polystyrene Films Market Segmentation
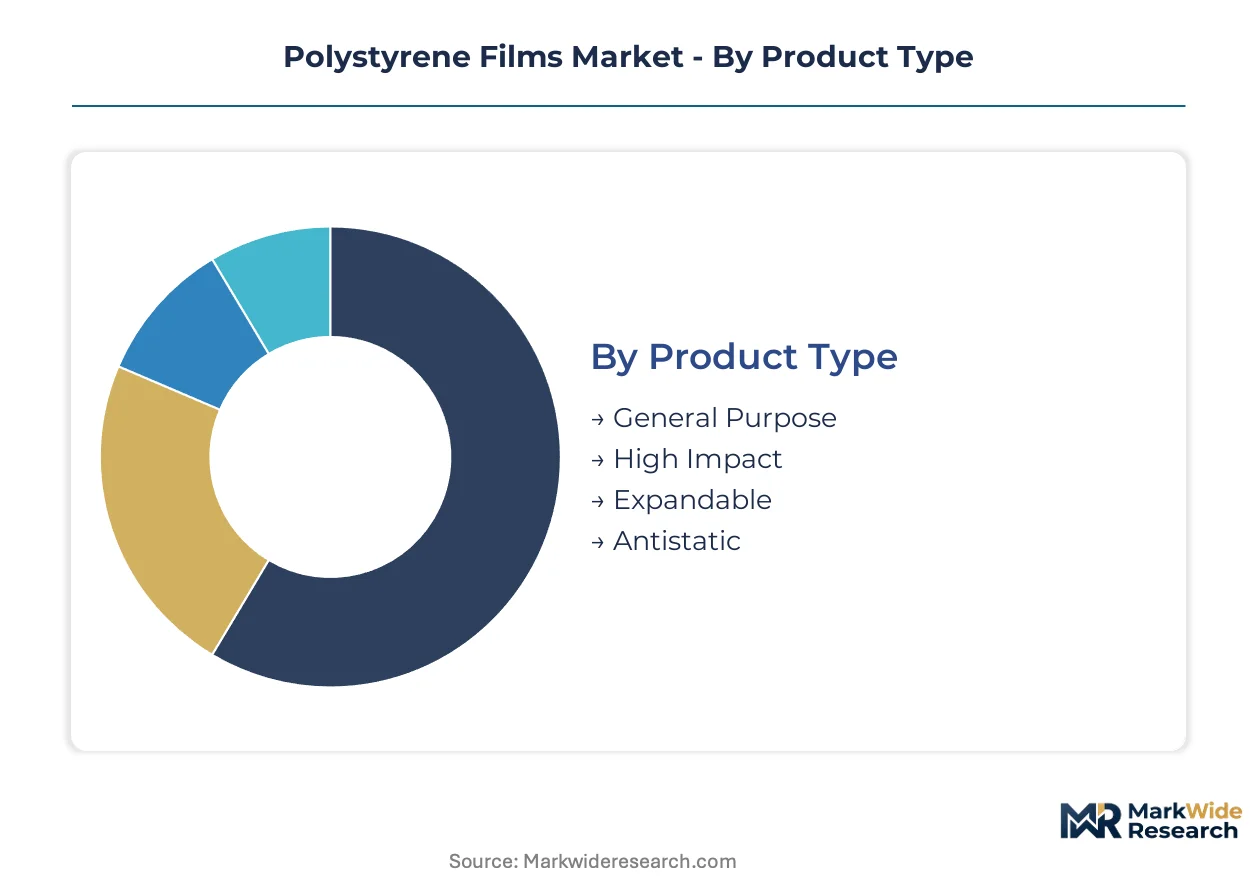
Segmentation in polystyrene films separates commodity-grade extruders from specialized coating houses. Technical service intensity varies dramatically across antistatic electronics grades versus standard packaging films, reshaping supplier qualification requirements and margin structures.
Product Type:
After-sales technical support intensity scales with formulation complexity — antistatic and expandable grades demand ongoing conductivity testing assistance and thermoforming parameter guidance that general-purpose films rarely require.
- General Purpose:Unmodified polystyrene resin extruded into clear, rigid films for cost-sensitive applications. German food processors in Lower Saxony and Bavaria specify these grades for thermoformed protein trays where moisture barrier requirements dominate over impact resistance.
- Antistatic:Surface-resistivity-controlled formulations incorporating quaternary ammonium compounds or carbon-based additives. Japanese electronics OEMs in Aichi Prefecture mandate sub-micron uniformity certificates and cleanroom-compatible packaging for semiconductor wafer shipping applications.
- High Impact:Rubber-modified polystyrene delivering enhanced toughness for deep-draw thermoforming. Medical device manufacturers in Ireland specify these grades for sterile barrier trays requiring drop-test compliance.
- Expandable:Bead-containing formulations that expand during heating to create cellular structures. Cold-chain logistics providers in the Netherlands specify expanded polystyrene films for temperature-sensitive pharmaceutical distribution.
General Purpose holds the largest share; momentum sits with Antistatic.
Application:
Application selection correlates directly with coating and metallization investment thresholds — barrier packaging commands multi-layer extrusion lines while printing applications prioritize gauge uniformity over functional additives.
- Packaging:Primary film consumption in food-contact trays, blister packs, and protective overwrap. Aldi and Lidl procurement teams in Germany have consolidated qualified supplier lists from twelve to four converters since 2022, demanding ISCC PLUS chain-of-custody documentation.
- Electronics:Dielectric substrates and cleanroom-compatible protective layers. Bavarian and Baden-Württemberg automotive OEMs are expanding antistatic film specifications as EV power electronics production concentrates in southern Germany.
- Printing:Substrates for labels, signage, and point-of-sale displays. High-speed flexographic lines in Maharashtra, India require roll-form consistency for continuous-feed operations.
- Household Goods:Decorative laminates and furniture surface films. Italian furniture manufacturers in Lombardy specify coated variants for scratch-resistant surface applications.
Packaging dominates volume; Electronics is climbing the fastest.
Form:
Form factor selection determines downstream processing economics — continuous rolls enable high-speed automation while sheets accommodate short-run thermoforming operations.
- Roll:Continuous wound film for automated printing and packaging lines. Japanese converters in Osaka Prefecture specify roll-form antistatic films for inline lamination with polyethylene barrier layers.
- Sheet:Cut-to-size panels for thermoforming and die-cutting operations. German automotive suppliers in Stuttgart source sheet-form high-impact grades for deep-draw instrument panel components.
- Coated:Surface-functionalized films with barrier or adhesive properties. Pharmaceutical serialization mandates in FDA-regulated markets are driving coated substrate adoption for tamper-evident packaging applications.
- Laminated:Multi-layer constructions combining polystyrene with aluminum or polymer films. Healthcare converters in the Netherlands specify laminated structures for oxygen-sensitive medical device packaging.
Roll holds the largest share; Coated is gaining share fastest.
End User:
End-user concentration patterns reflect regional industrial clustering — food processing anchors European demand while electronics manufacturing drives Asian specifications.
- Food Industry:Moisture-resistant barrier solutions for protein, dairy, and produce packaging. Processors in Germany and Japan are locking in volume commitments with qualified converters for expanded polystyrene films in cold-chain applications.
- Consumer Electronics:Cleanroom-grade protective films and dielectric substrates. Semiconductor manufacturers in Aichi and Osaka prefectures mandate sub-micron uniformity certificates and antistatic surface treatments.
- Healthcare:Sterile barrier systems and pharmaceutical packaging. Medical packaging converters in Ireland and the Netherlands are accelerating qualification of bio-based alternatives ahead of ECHA microplastics enforcement windows.
- Retail:Point-of-sale displays and protective overwrap for consumer goods. Pan-European retailers are compressing supplier panels and demanding standardized sustainability certifications across all packaging films.
Food Industry holds the largest share; Healthcare shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in polystyrene films tilt toward net imports in packaging-heavy economies while integrated chemical clusters sustain surplus positions. Germany and Japan anchor qualified converter capacity, drawing cross-border sourcing from processors seeking FDA and EFSA-compliant supply chains.
Germany
Food processing clusters in Lower Saxony and Bavaria drive moisture-resistant barrier specifications for protein packaging applications. The EU Green Deal packaging waste directives force converters toward recyclable-grade production lines, compressing supplier panels. Automotive electronics manufacturers in Baden-Württemberg anchor antistatic film consumption for EV power electronics assembly.
United States
FDA-regulated pharmaceutical serialization mandates create coated substrate demand for tamper-evident packaging applications. EPA volatile organic compound regulations push converters toward waterborne coating alternatives, altering equipment investment thresholds. Midwestern converters around Chicago sustain roll-form supply for high-speed flexographic printing operations.
Japan
Semiconductor and display manufacturing cleanrooms in Aichi and Osaka prefectures mandate sub-micron uniformity certificates for antistatic film deliveries. METI industrial standards shape surface-resistivity specifications for electronics OEM procurement. Osaka-based converters specialize in inline lamination with polyethylene barrier layers for precision packaging.
India
FSSAI compliance investments by converters in Gujarat and Maharashtra open qualified supply positions for export-oriented processed food brands. Central government PLI scheme incentives for packaging materials attract extrusion capacity toward western industrial corridors. Maharashtra-based high-speed printing lines require roll-form consistency for continuous-feed label production.
Netherlands
Medical packaging converters in Ireland and the Netherlands accelerate bio-based alternative qualification ahead of ECHA microplastics enforcement windows. REACH Annex XVII restrictions on intentionally added microplastics reshape additive strategies for film exporters. Cold-chain logistics providers specify expanded polystyrene films for temperature-sensitive pharmaceutical distribution.
Polystyrene Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation and substrate engineering. The supplier base compresses around capitalized extruders capable of multi-layer barrier investments, while mid-cap converters face balance-sheet strain from simultaneous coating and metallization upgrades. Three archetypes dominate: backward-integrated chemical majors with captive styrene supply, specialized coating houses serving healthcare serialization mandates, and regional extruders qualified for pan-E retailer sustainability certifications. Competitive moves center on circular-economy infrastructure partnerships and electron-beam coating capacity expansion.
Among North American fabricators, Multi-Plastics, Inc. and Transcendia occupy positions across coated and laminated form factors. TEKRA exemplifies the precision-film specialist archetype within the EIS corporate structure. Dow Chemical Company anchors the integrated chemical major tier with upstream styrene monomer control. Ohishi Sangyo Co. Ltd. represents Japanese specialization in electronics-grade antistatic formulations.
| Leading Market Players |
|---|
| Multi-Plastics, Inc. |
| Transcendia |
| TEKRA (A Division of EIS, Inc.) |
| Cheever Specialty Paper & Film |
| LAIWELL GROUP INT'L |
| Dow Chemical Company |
| Norflex |
| Ohishi Sangyo Co. Ltd. |
| Senoplast Klepsch & Co GmbH |
| Others |
Value Network & Pricing Analysis
Styrene monomer concentration in the US Gulf Coast and Northeast Asian chemical clusters directly shapes where extrusion margin pools accumulate downstream. Benzene-naphtha spread volatility feeds through to non-integrated converters, while backward-integrated majors capture pricing power through captive supply.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium, standard, and economy tiers. Price differentiation hinges on FDA food-contact certification grade and volume scale commitments. Cost compression in general-purpose grades is intensifying because polypropylene substitution in cold-form blister applications relaxes performance requirements. Food processors in Germany demonstrate lowest price sensitivity due to qualification lock-in, while commodity tray converters in India face acute margin pressure.
Supply Chain Analysis
Extended payment terms from pan-European retailers are straining mid-cap converter working capital, accelerating supply-chain finance facility adoption. Raw material sourcing draws from Saudi Arabian benzene derivatives, South Korean styrene monomer, and German specialty additive houses. Single-source vulnerability concentrates in electronics-grade antistatic formulations where Japanese suppliers dominate cleanroom-compatible certifications. Distribution runs through qualified converter networks that maintain ISCC PLUS chain-of-custody documentation for EU retailer compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against oriented polypropylene films displacing general-purpose polystyrene in relaxed impact-resistance applications.
For Market Incumbents: Harden qualification lock-in with German food processors through multi-year volume commitments for expanded polystyrene cold-chain specifications. Deepen upstream control over styrene monomer supply to insulate margins from benzene-naphtha spread compression. Accelerate electron-beam coating capacity expansion ahead of EPA VOC enforcement windows. For New Entrants and Emerging Players: Pursue pharmaceutical serialization coating substrates in FDA-regulated markets where qualified supplier lists remain unconcentrated. Target Gujarat and Maharashtra converter partnerships for FSSAI-compliant food-contact expansion serving export-oriented processed food brands. Lead with waterborne coating conversion capabilities to capture first-mover advantage under EPA regulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating houses serving healthcare serialization mandates with installed barrier film capacity. Long-term viability hinges on circular-economy infrastructure partnerships that secure post-consumer polystyrene offtake. Monitor ECHA microplastics enforcement preparation as the inflection signal for bio-based alternative qualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive styrene monomer supply insulates Dow Chemical from benzene-naphtha volatility. |
| Green Manufacturing Transition | Waterborne coating conversion aligns Transcendia with EPA VOC regulatory trajectories. |
| Long-term Supply Agreement | Volume commitments with Lower Saxony protein processors lock in Ohishi Sangyo capacity. |
| Capacity Expansion | Multi-layer barrier investments strain mid-cap balance sheets, favoring capitalized extruders. |
| Joint Venture | Circular-economy partnerships with post-consumer processors enable closed-loop claims in EU markets. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and ECHA regulatory guidance preceded structured interviews with extrusion plant managers, food processor procurement leads, electronics OEM technical directors, and pharmaceutical packaging converters. Primary fieldwork combined with secondary validation through Cefic industry reports and FDA food-contact notification databases. Bottom-up capacity assessments and top-down demand triangulation anchored volume estimates.
Assumptions held feedstock price spreads within historical bands while varying EU Green Deal implementation intensity across regulatory scenarios. Segmentation modeling incorporated product type tiers, application end-uses, form factors, and regional production hub clusters. CAGRs derived from slope-log regression across annualized volume outputs, with sensitivity testing against automotive electronics clustering patterns and pharmaceutical serialization mandate adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Middle Eastern chemical majors would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Packaging Film Market
Poly film
Tube Laminating Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
Polyethylene Cast Film Market
Poly film
Stretch Films Packs Market
Poly film
Polyethylene Film Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Embossed Film Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Global BOPP Films Market
Poly film
Resealable Films Market
Poly film
Japan Plastic Packaging Film Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Bio-PET Film Market