
 Polysaccharide Films Market | 2026-2036
Polysaccharide Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polysaccharide Films Market Analytics
The polysaccharide films market is decoupling into two distinct tiers: high-performance biomedical and pharmaceutical grades commanding technical premiums versus commodity food-wrap films competing on cost per square meter. Cargill leverages its agricultural supply chain to anchor starch-based film production at scale across North American processing hubs. DuPont differentiates through cellulose derivative expertise sustained by decades of polymer science investment. Novamont specializes in compostable formulations that navigate Italy's stringent packaging waste regulations.
Polysaccharide films are thin, continuous matrices formed from renewable carbohydrate polymers such as starch, cellulose, chitosan, or agar, typically cast from aqueous solutions and plasticized with polyols to achieve tensile strengths of 20–80 MPa and oxygen permeability below 10 cm³ µm/m² day kPa for barrier applications. These films serve as edible coatings, biodegradable packaging layers, and controlled-release substrates that replace synthetic plastics in applications demanding end-of-life compostability or biocompatibility. Cellulose-based films lead in commercial volume due to mature manufacturing infrastructure and broad regulatory acceptance, while chitosan-based formulations represent the fastest-expanding margin pool as antimicrobial properties unlock premium biomedical and active food packaging segments. Starch-based films occupy the cost-sensitive bulk packaging tier where agricultural feedstock proximity determines manufacturing economics.
The EU Green Deal and REACH frameworks in Europe mandate reductions in persistent plastic packaging, directly expanding addressable demand for certified compostable alternatives. FDA food contact substance notifications and USDA bio-preferred procurement standards shape product qualification pathways and federal purchasing eligibility in the United States. Stakeholders must monitor evolving compostability certification requirements across multiple jurisdictions, as divergence in home versus industrial composting standards threatens to fragment market access and force parallel product development tracks.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's packaging waste mandates are compressing substitution timelines for petroleum-based films, forcing converters to requalify entire product lines around compostable polysaccharide substrates before 2030.
Growth Catalysts
- EU Green Deal packaging mandates:Binding reduction targets for persistent plastics are redirecting food brand R&D budgets toward certified compostable film qualification programs.
- Active packaging integration:Antimicrobial chitosan formulations are capturing premium shelf-life extension contracts from protein processors seeking clean-label preservation.
- German converter clustering:Packaging technology institutes in Baden-Württemberg and Bavaria are accelerating pilot-to-commercial scale-up timelines for starch-based barrier films.
Market Restraints
- Agricultural feedstock volatility:Corn and potato starch prices fluctuate with commodity crop yields, compressing margin predictability for film extruders.
- Industrial composting infrastructure gaps:Home compostability certification (OK Compost HOME) lacks parallel waste stream access in most municipalities, limiting end-of-life value proposition clarity.
- Performance ceiling against synthetic barriers:Moisture vapor transmission rates in unmodified starch films remain 10-100x higher than oriented polypropylene, restricting high-humidity applications.
Strategic Opportunities
- Wound care substrate expansion:Chitosan-based films with hemostatic properties are penetrating advanced dressing segments previously served by synthetic hydrogels.
- USDA BioPreferred procurement:Federal purchasing preference points for biobased content are opening institutional foodservice packaging contracts.
- Cellulose nanofibril hybridization:Combining regenerated cellulose with CNF reinforcement is unlocking thin-gauge high-strength applications in flexible electronics substrates.
Industry Challenges
- Multijurisdictional certification fragmentation:Divergent home versus industrial composting standards across EU member states, US states, and Asian markets force parallel testing tracks.
- Plasticizer migration control:Glycerol and sorbitol loading optimization requires precise humidity-controlled casting environments that legacy extrusion lines cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysaccharide Films Market |
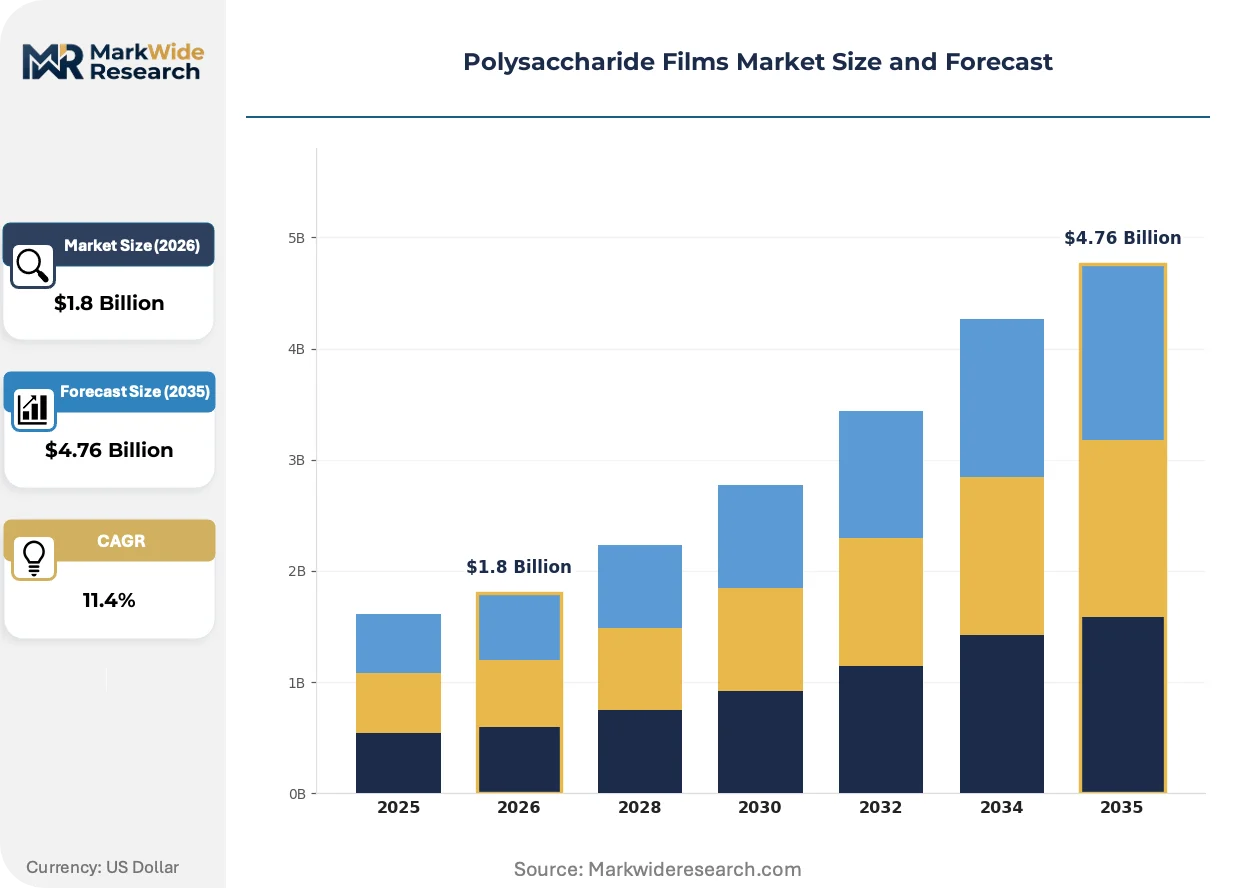
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Cellulose-Based, Chitosan-Based, Agar-Based Application: Food Packaging, Biomedical Applications, Agriculture, Coatings Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers End User: Food Industry, Healthcare Sector, Agricultural Sector, Pharmaceutical Companies |
| Companies Covered | Cargill, DuPont, Ingredion Incorporated, Archer Daniels Midland, Tate & Lyle, BASF SE, Dow Inc., Novamont, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysaccharide Films Market Evolving Landscape
Film manufacturing is splitting between commodity aqueous casting for food wrap and precision electrospinning for biomedical matrices, with equipment suppliers now offering modular platform designs that bridge both process regimes.
Layer-by-layer deposition of oppositely charged polyelectrolytes is modularizing barrier engineering for oxygen-sensitive pharmaceuticals. Contract manufacturers in Switzerland and Germany are installing pilot lines for 50-200 nanometer bilayer stacks. This architecture compresses oxygen permeability below 1 cm³ µm/m² day kPa without petrochemical coextrusion.
EMA's revised medical device regulation guidance on absorbable implants is requiring extended biodegradation documentation for chitosan and alginate films. European wound care OEMs are restructuring supplier qualification protocols. German notified bodies are experiencing 14-18 month backlog for novel polysaccharide substrate approvals.
Brand technical buyers now specify compostability certification tier before price negotiation, reversing traditional commodity purchasing sequences. Food packaging procurement teams in Nordic markets are disqualifying uncertified substrates at RFP stage. This preference compression is visible in Danish retail private label conversion timelines accelerating 40% versus southern European counterparts.
Polysaccharide Films Market Segmentation
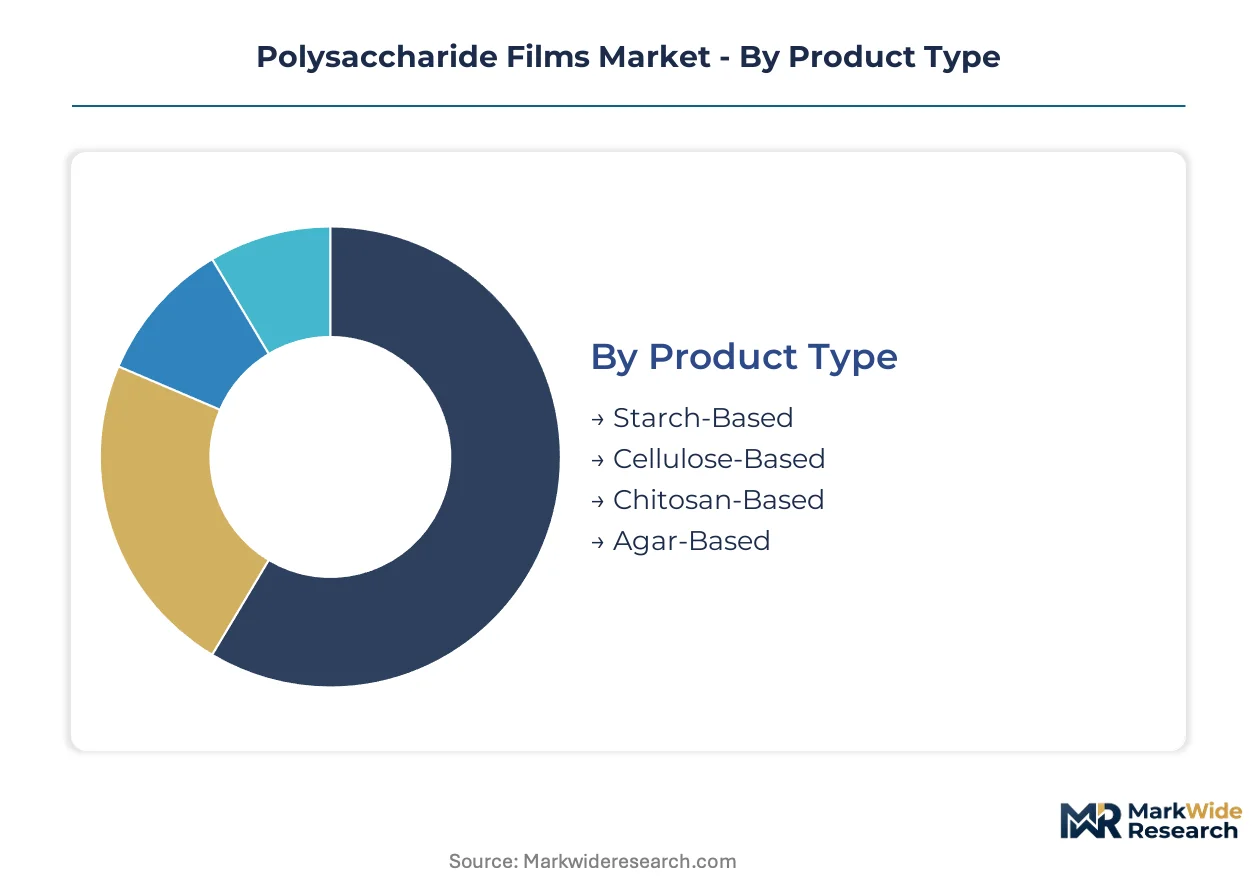
Segmentation in polysaccharide films reveals how technical performance requirements and end-of-life certification standards fragment addressable markets. Buyers sort by barrier specifications, compostability tier, and regulatory qualification burden rather than commodity polymer pricing alone.
Product Type:
Cost sensitivity and performance ceiling separate buyers in this category, with agricultural feedstock proximity determining manufacturing economics for volume purchasers.
- Starch-Based:Derived from corn, potato, or tapioca starches plasticized with glycerol or sorbitol, these films achieve tensile strengths of 20-40 MPa with oxygen permeability suitable for dry food barriers. Demand clusters in Germany's Baden-Württemberg packaging corridor where converters source from regional starch processing hubs to minimize feedstock transport costs.
- Cellulose-Based:Regenerated cellulose and cellulose ether films leverage mature viscose and solvent-casting infrastructure to deliver the broadest regulatory acceptance and moisture barrier range. Volume concentrates in food wrap applications where EU Green Deal compliance deadlines force rapid substitution of petroleum-based clarity films.
- Chitosan-Based:Extracted from crustacean shells, these films carry inherent antimicrobial properties that unlock premium biomedical and active food packaging segments requiring biocompatibility certification.
- Agar-Based:Seaweed-derived polysaccharide films offer vegan-compliant edible coatings with gel strength tunable through extraction temperature control, serving niche confectionery and pharmaceutical capsule applications.
Volume sits with cellulose-based formulations; growth tilts toward chitosan-based grades.
Application:
End-use qualification protocols create distinct margin tiers, with biomedical applications demanding extended biodegradation documentation that pharmaceutical OEMs structure supplier contracts around.
- Food Packaging:Primary demand driver encompassing fresh produce wraps, snack pouches, and tray liners requiring home or industrial compostability certification. Nordic retail procurement teams now specify certification tier before price negotiation, compressing qualification timelines.
- Biomedical Applications:Wound dressings, drug delivery matrices, and tissue engineering scaffolds exploit chitosan's hemostatic and antimicrobial properties. EMA's revised medical device regulation guidance is forcing European wound care OEMs to restructure supplier protocols around extended biodegradation documentation.
- Agriculture:Mulch films and seed coatings that eliminate retrieval labor through soil biodegradation, with performance constrained by moisture vapor transmission rates in high-humidity cultivation environments.
- Coatings:Edible and functional barrier layers applied to paperboard or fresh produce surfaces, where layer-by-layer polyelectrolyte deposition enables sub-micrometer oxygen barriers without synthetic coextrusion.
Food packaging commands current volume; biomedical applications are climbing the fastest on technical premium capture.
Distribution Channel:
Customer scale and technical support requirements determine channel selection, with large converters bypassing intermediaries to secure formulation customization and volume pricing.
- Direct Sales:Film manufacturers maintain technical service teams for multinational food brands and pharmaceutical OEMs requiring joint development programs for compostability certification and barrier optimization.
- Distributors:Regional warehousing networks serve mid-tier packaging converters with standardized film grades and shorter lead times than mill-direct procurement.
- Online Retail:E-commerce platforms capture small-volume researchers, artisan food producers, and agricultural trial users seeking sample quantities without minimum order constraints.
- Wholesalers:Bulk aggregators supply commodity starch-based films to price-sensitive agricultural mulch and secondary packaging applications where technical specifications remain generic.
Direct sales anchor pharmaceutical and large food accounts; distributor networks are expanding most quickly among mid-tier European converters.
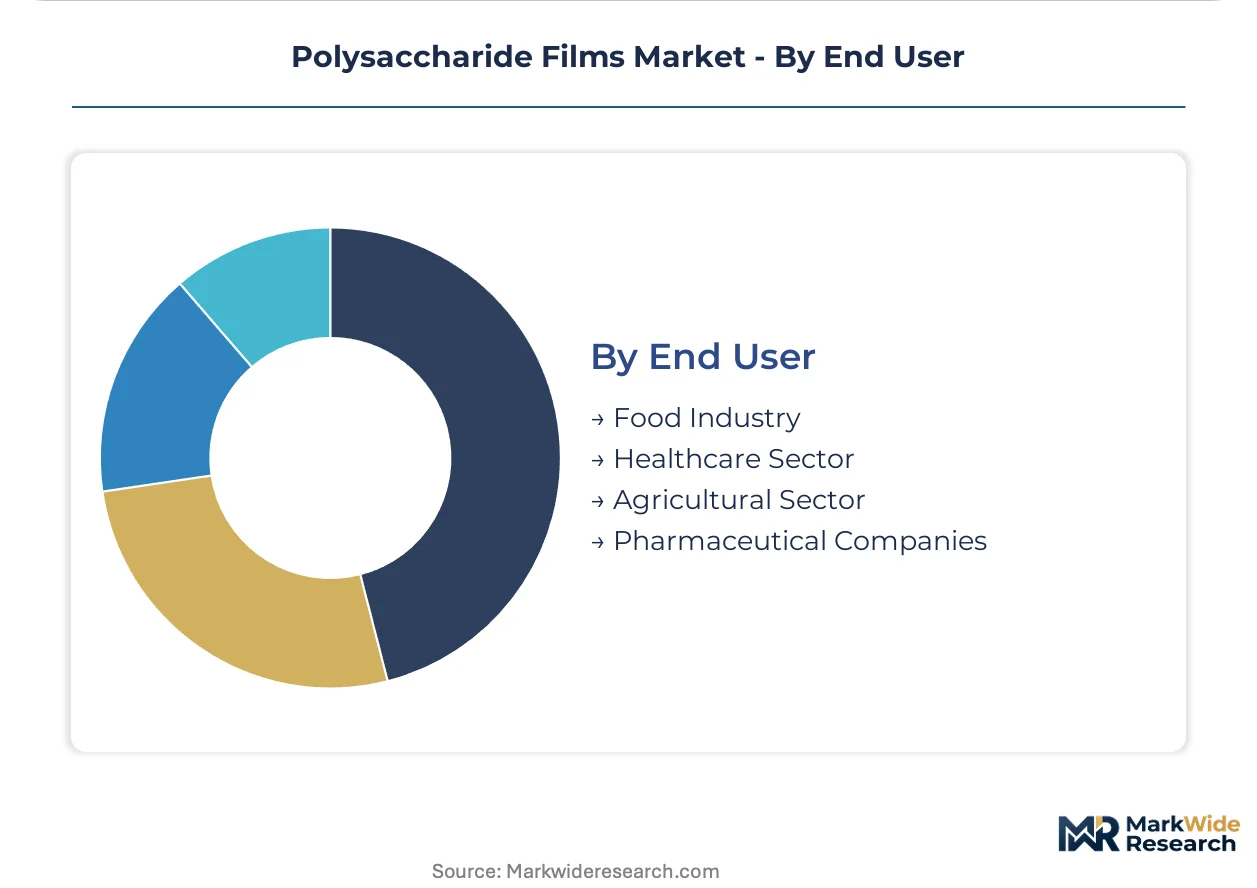
End User:
Regulatory jurisdiction and procurement standards segment this category, with federal purchasing preferences opening institutional contracts that commodity suppliers cannot access without biobased content certification.
- Food Industry:Brand owners and private label retailers drive compostable packaging conversion under EU Green Deal and REACH compliance deadlines, with Danish and Swedish procurement teams accelerating qualification versus southern European counterparts.
- Healthcare Sector:Hospitals, clinics, and wound care centers absorb advanced chitosan dressings where hemostatic performance displaces synthetic hydrogels in surgical applications.
- Pharmaceutical Companies:Drug manufacturers specify polysaccharide films for controlled-release coatings and absorbable implant substrates, with German notified bodies experiencing 14-18 month backlogs for novel substrate approvals.
- Agricultural Sector:Large-scale growers and cooperative extensions adopt soil-biodegradable mulch films where retrieval labor costs exceed premium material pricing, though industrial composting infrastructure gaps limit value proposition clarity in many municipalities.
Food industry procurement dominates current volume; pharmaceutical companies represent the steepest expansion trajectory on regulatory-driven material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's packaging technology corridor anchors European polysaccharide film commercialization, with Stuttgart-area converters clustering around regional starch processing infrastructure. The EU Green Deal and REACH compliance deadlines compress substitution timelines across multiple jurisdictions simultaneously.
Germany
Food packaging converters in Bavaria and Baden-Württemberg drive industrial demand for certified compostable films. ECHA's REACH enforcement mandates eliminate persistent plastic alternatives from supermarket shelves by 2030. Fraunhofer institutes in Stuttgart accelerate pilot-to-commercial scale-up for starch-based barrier formulations.
United States
USDA BioPreferred procurement standards redirect federal foodservice packaging contracts toward biobased substrates. FDA food contact substance notifications shape qualification pathways for edible coating applications. Midwest agricultural processors in Iowa and Illinois leverage corn starch proximity to anchor commodity film extrusion economics.
Italy
Novamont's headquarters in Novara anchors national compostable formulation expertise navigating stringent packaging waste regulations. The country's extended producer responsibility framework mandates industrial compostability certification for single-use food service items. Northern Italian converters in Lombardy and Piedmont cluster around biopolymer research institutes.
France
Paris-based retail procurement teams specify home compostability certification tiers before price negotiation, reversing traditional purchasing sequences. ANSM's medical device oversight extends to absorbable wound dressing substrates. The Grand Est region's agricultural cooperatives trial soil-biodegradable mulch films for vegetable cultivation.
Japan
METI's bioplastics deployment roadmap targets packaging sector substitution by 2030. Chitosan film developers in Kyushu exploit regional crustacean processing waste streams for biopolymer extraction. Osaka-area pharmaceutical OEMs qualify polysaccharide substrates for controlled-release drug delivery matrices.
Polysaccharide Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and barrier performance dimensions, with biomedical-grade chitosan formulations commanding technical premiums against cost-sensitive starch-based food wraps. The vendor base stratifies between agricultural conglomerates with captive feedstock supply and specialty chemical houses with polymer science depth. Three archetypes dominate: diversified agribusinesses leveraging starch supply chains, cellulose derivative specialists with decades of solvent-casting expertise, and dedicated biopolymer pioneers focused exclusively on compostable formulations. Competitive intensity centers on M&A activity consolidating regional feedstock access and strategic partnerships bridging certification gaps across divergent national composting standards.
Within the agribusiness archetype, Cargill and Archer Daniels Midland exemplify scale-driven players anchoring North American starch-based film production through captive agricultural supply chains. DuPont represents the cellulose derivative specialist tier, occupying a position sustained by long polymer science investment cycles. Novamont sits within the dedicated biopolymer pioneer category, exemplifying European compostable formulation expertise shaped by Italy's regulatory environment.
| Leading Market Players |
|---|
| Cargill |
| DuPont |
| Ingredion Incorporated |
| Archer Daniels Midland |
| Tate & Lyle |
| BASF SE |
| Dow Inc. |
| Novamont |
| DSM |
| Others |
Value Network & Pricing Analysis
EU Green Deal packaging mandates are forcing food brand procurement teams to specify compostability certification tiers before price negotiation, compelling starch and cellulose suppliers to restructure production lines around dual-track home and industrial certification pathways that inflate unit economics.
Pricing Analysis
Outcome-based pricing anchored to shelf-life extension performance dominates active packaging segments, where chitosan films command premiums tied to measured protein preservation yields. Three-tier pricing structure across biomedical-grade, food-contact-certified, and uncertified commodity tiers separates buyers by documentation burden. Pricing pressure stems from agricultural feedstock volatility compressing margin predictability for starch extruders. Agricultural mulch film buyers exhibit highest price sensitivity, while pharmaceutical OEMs absorb technical premiums for extended biodegradation documentation.
Supply Chain Analysis
Corn and potato starch supply rests on Midwest US and German agricultural processing hubs, with tapioca feedstock drawing from Southeast Asian extraction facilities. Chitosan raw material hinges on crustacean processing waste streams concentrated in Kyushu and Vietnam coastal operations. Single-source vulnerability runs through glycerol plasticizer supply anchored in biodiesel byproduct channels. Distribution runs through converter-direct relationships for large food brands, with regional distributors serving mid-tier packaging operations requiring shorter lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostability certification capacity bottlenecks prop pricing power for qualified suppliers, as ECHA enforcement timelines compress qualification windows ahead of 2030 mandates.
For Market Incumbents: Cement feedstock security through backward integration into regional starch processing or long-term offtake agreements with Iowa and Baden-Württemberg agricultural cooperatives. Prioritize dual-certification capacity expansion to capture food brand R&D budgets before REACH deadlines eliminate unqualified competitors. Defend against cellulose nanofibril hybrid substitutes by locking pharmaceutical OEMs into extended biodegradation documentation contracts. For New Entrants and Emerging Players: The premium-to-economy price-point gap in active food packaging invites mid-tier positioning around antimicrobial chitosan formulations with clean-label preservation claims. Target Nordic retail private label conversion timelines accelerating 40% faster than southern European counterparts. Enter through contract manufacturing partnerships with German Fraunhofer-affiliated pilot lines to bypass 14-18 month notified body backlogs. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated biopolymer pioneers given EU Green Deal enforcement accelerating substitution timelines. Long-term viability favors archetypes with captive compostability certification expertise and pharmaceutical qualification track records. Watch industrial composting infrastructure buildout rates as inflection indicator for home compostability certification value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Capacity Expansion | Captures EU food brand procurement mandates ahead of REACH enforcement deadlines. |
| Backward Integration into Feedstock | Secures margin stability against corn and potato starch commodity volatility. |
| Pharmaceutical OEM Partnership | Locks extended biodegradation documentation contracts under revised EMA guidance. |
| Cellulose Nanofibril Hybridization | Unlocks thin-gauge high-strength applications in flexible electronics substrates. |
| Nordic Retail Channel Penetration | Accelerates conversion timelines through procurement teams specifying certification first. |
Research Methodology
Document review covered EMA medical device guidance, EU Green Deal packaging mandates, FDA food contact substance notifications, and REACH compliance frameworks, complemented by interviews with packaging converter technical directors, pharmaceutical procurement managers, agricultural cooperative supply planners, and compostability certification body auditors. Secondary validation drew from customs trade data, SEC filings of agricultural processors, notified body approval databases, and Fraunhofer institute pilot line disclosures. Bottom-up demand modeling and top-down supply capacity assessments were triangulated for convergence.
Segment-level outputs across product type, application, and end-user dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from installed capacity trajectories, substitution elasticity against petroleum-based films, and certification adoption curves. Industry-specific inputs included composting infrastructure buildout rates by municipality and pharmaceutical OEM supplier qualification pipeline data.
Underlying measurement precision varies by segment; biomedical-grade chitosan formulations carry tighter precision than commodity starch films given documented notified body approval timelines. Forecasts reflect assumptions around EU enforcement consistency and feedstock price stability. Agricultural yield volatility, divergent national composting standards, and plasticizer migration control technical failures warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Global PVDC Coated Films Market
Poly film
France Plastic Packaging Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
North America Polyimide Films Market
Poly film
Twist Wrap Film Market
Poly film
Polylaminate Capsules Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Vinyl Films Market
Poly film
Polyethylene Cast Film Market
Poly film
Easy Peel Film Packaging Market
Poly film
Canada Plastic Packaging Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Japan Polypropylene Packaging Films Market