
 China Plastic Packaging Film Market | 2026-2036
China Plastic Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
China Plastic Packaging Film Market Insights
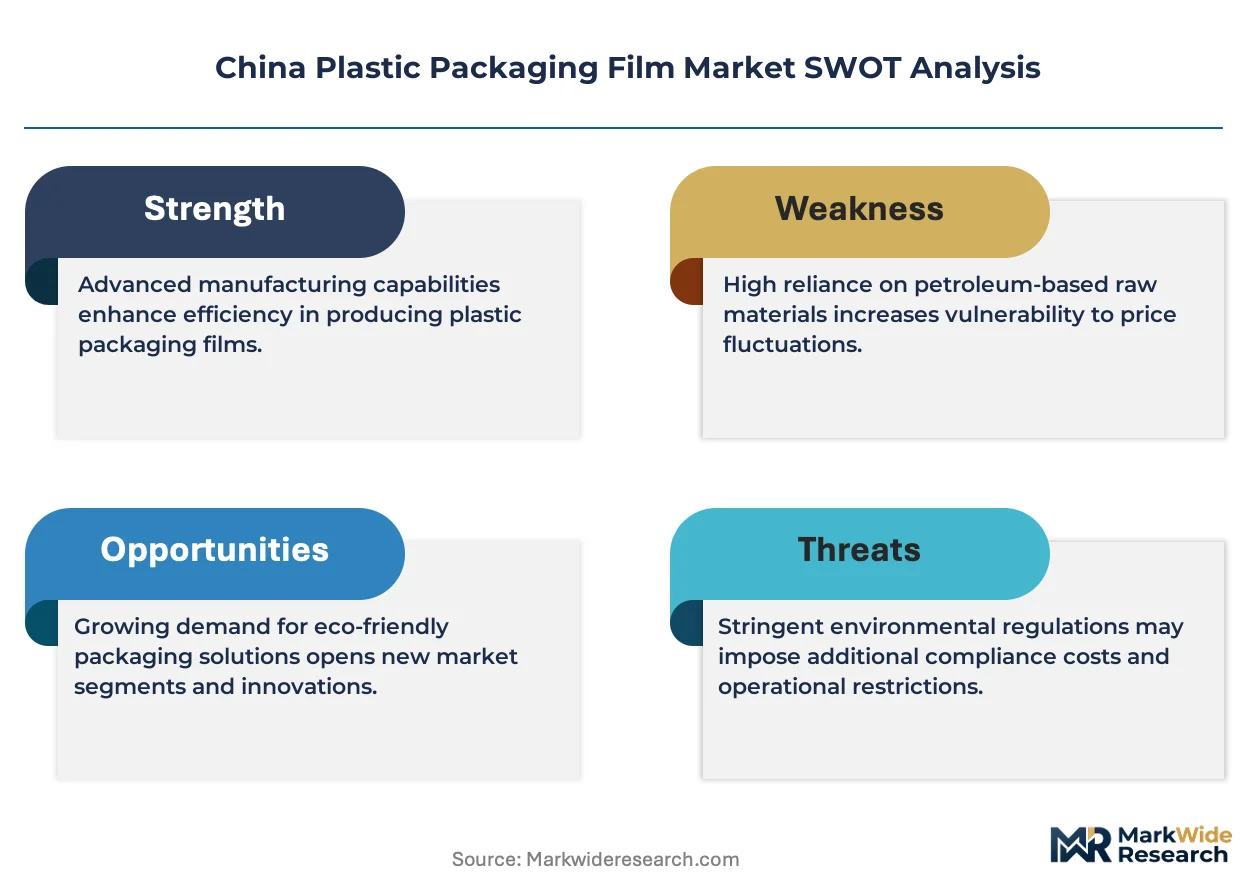
The gap between premium multilayer barrier films and commodity monolayer grades is shifting from a price spread into a capability divide. Xiamen Changsu Industrial Co., Ltd leverages vertical integration across resin compounding and film extrusion to control cost positions in commodity polyethylene. Toray Advanced Film Co., Ltd differentiates through biaxially oriented polypropylene technology leadership for high-clarity food packaging. Zhejiang Kinlead Innovative Materials Co., Ltd anchors its position in specialty films for pharmaceutical blister packs.
China plastic packaging film encompasses extruded and cast polymer sheets, typically ranging from below 20 microns to above 60 microns in thickness, engineered for moisture barrier, oxygen resistance, and mechanical protection in product containment and distribution. Polyethylene dominates volume production for flexible packaging of fresh produce and frozen foods, while polypropylene commands premium pricing in rigid packaging applications requiring thermal stability and optical clarity. The above 60 microns segment serves industrial stretch film and heavy-duty shrink wrapping where puncture resistance determines specification, whereas sub-20 micron films are displacing thicker alternatives in lightweight consumer goods wrapping as converters pursue material reduction targets.
China's SAMR enforces GB standards for food-contact plastics that mandate migration testing and additive disclosure, compelling domestic converters to reformulate recipes or source certified raw materials. The MEE implements dual carbon goals through emissions intensity benchmarks that disadvantage coal-powered resin producers and favor film manufacturers with captive renewable energy or circular feedstock partnerships. Stakeholders must monitor how provincial carbon allowance trading schemes reshape the cost structure of virgin resin relative to chemically recycled alternatives.
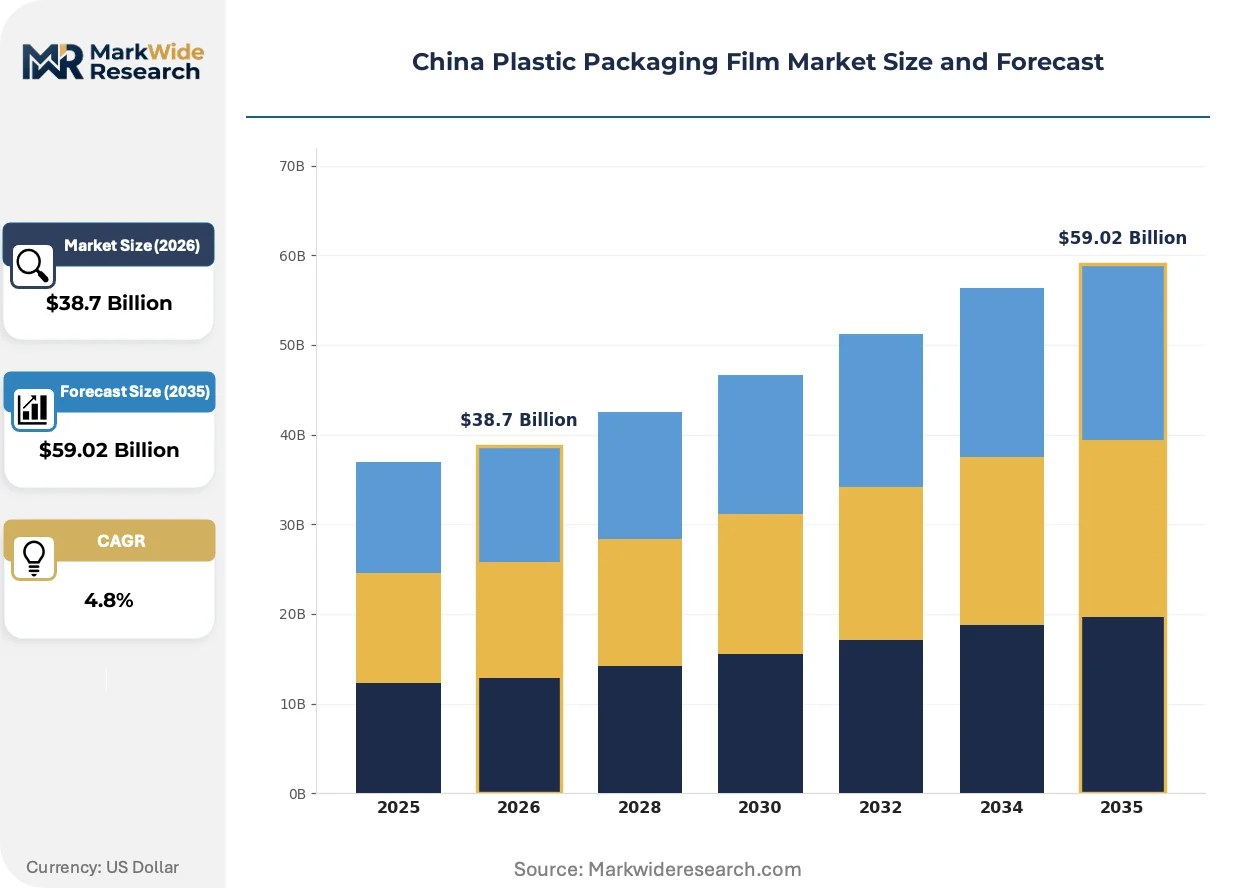
Market Dynamics
China's dual carbon goals are compressing the cost advantage of coal-powered resin supply, forcing converters to reconfigure feedstock sourcing and energy procurement around MEE emissions benchmarks and provincial carbon allowance trading schemes.
Growth Catalysts
- High-barrier film specifications:Food and beverage brands are scaling orders for multilayer structures that extend shelf life in ambient distribution, pulling converter capacity toward oxygen and moisture barrier specialization.
- GB standards harmonization:SAMR mandates on migration testing and additive disclosure are consolidating demand toward certified domestic converters with in-house testing laboratories.
- Coastal manufacturing concentration:Zhejiang and Guangdong clusters concentrate extrusion capacity, logistics infrastructure, and technical labor pools within 200 kilometers of major ports.
Market Restraints
- Resin input cost volatility:Naphtha-linked polyethylene pricing exposes margin stability to crude oil fluctuations and coal-to-olefins capacity curtailments under carbon intensity benchmarks.
- Monolayer commoditization:Technical parity among domestic producers in below-20-micron polyethylene has collapsed price premiums and compressed return on capital in volume segments.
- Chemical recycling feedstock scarcity:Pyrolysis oil and depolymerized monomer supply remains insufficient to displace virgin resin at scale for food-contact compliance.
Strategic Opportunities
- Pharmaceutical blister pack specialization:Domestic drug manufacturers are qualifying local film suppliers to reduce import dependency on European and Japanese specialty film sources.
- Renewable energy captive supply:Converters with photovoltaic or wind power purchase agreements gain cost positioning under provincial carbon allowance schemes that penalize coal-dependent competitors.
- Thinner gauge substitution:Sub-20-micron films are capturing applications previously served by 30-40 micron structures in lightweight consumer goods wrapping.
Industry Challenges
- Migration testing capability gaps:Smaller converters lack in-house analytical laboratories to validate GB compliance, forcing reliance on third-party testing that extends qualification timelines.
- Multilayer equipment retrofit requirements:Transitioning from monolayer to coextrusion or oriented film production demands capital outlays for die and line control systems that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Plastic Packaging Film Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Others End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Cosmetics Thickness: Below 20 Microns, 20-40 Microns, 40-60 Microns, Above 60 Microns Application: Flexible Packaging, Rigid Packaging, Shrink Packaging, Stretch Film |
| Companies Covered | Xiamen Changsu Industrial Co., Ltd, Toray Advanced Film Co., Ltd, Berry Global Inc., Kingchuan Packaging, Zhejiang Kinlead Innovative Materials Co., Ltd, Cosmo Films Limited, Zhejiang Jiuteng Packaging Co., Ltd, Fengjiang, Dadongnan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Plastic Packaging Film Market Trends and Innovations
Active materials and process architectures are redefining performance benchmarks in China's packaging film sector, with converter investment prioritizing barrier enhancement, energy efficiency, and circular feedstock integration over capacity expansion.
Coextrusion barrier technology is modularizing the architecture of high-performance films, enabling converters to substitute adhesive lamination with in-line multilayer extrusion that reduces solvent use and layer count. Pharmaceutical and fresh-protein packagers are adopting these structures fastest, compressing equipment payback periods and flattening the capability gap between specialty and commodity producers.
MEE enforcement of dual carbon goals through emissions intensity benchmarks is disadvantaging coal-powered resin producers and favoring film manufacturers with renewable energy offtake agreements or circular feedstock partnerships. Provincial carbon allowance trading schemes in Zhejiang and Guangdong are reshaping the cost structure of virgin resin relative to chemically recycled alternatives, with coastal converters best positioned to arbitrage these differentials.
Brand-led specification tightening is compressing supplier qualification cycles and unbundling technical service from material supply. Food and beverage multinationals operating in China are consolidating purchase orders toward converters with documented GB compliance and renewable energy certificates, concentrating volume among qualified suppliers and fragmenting residual demand across uncertified competitors.
China Plastic Packaging Film Market Segmentation
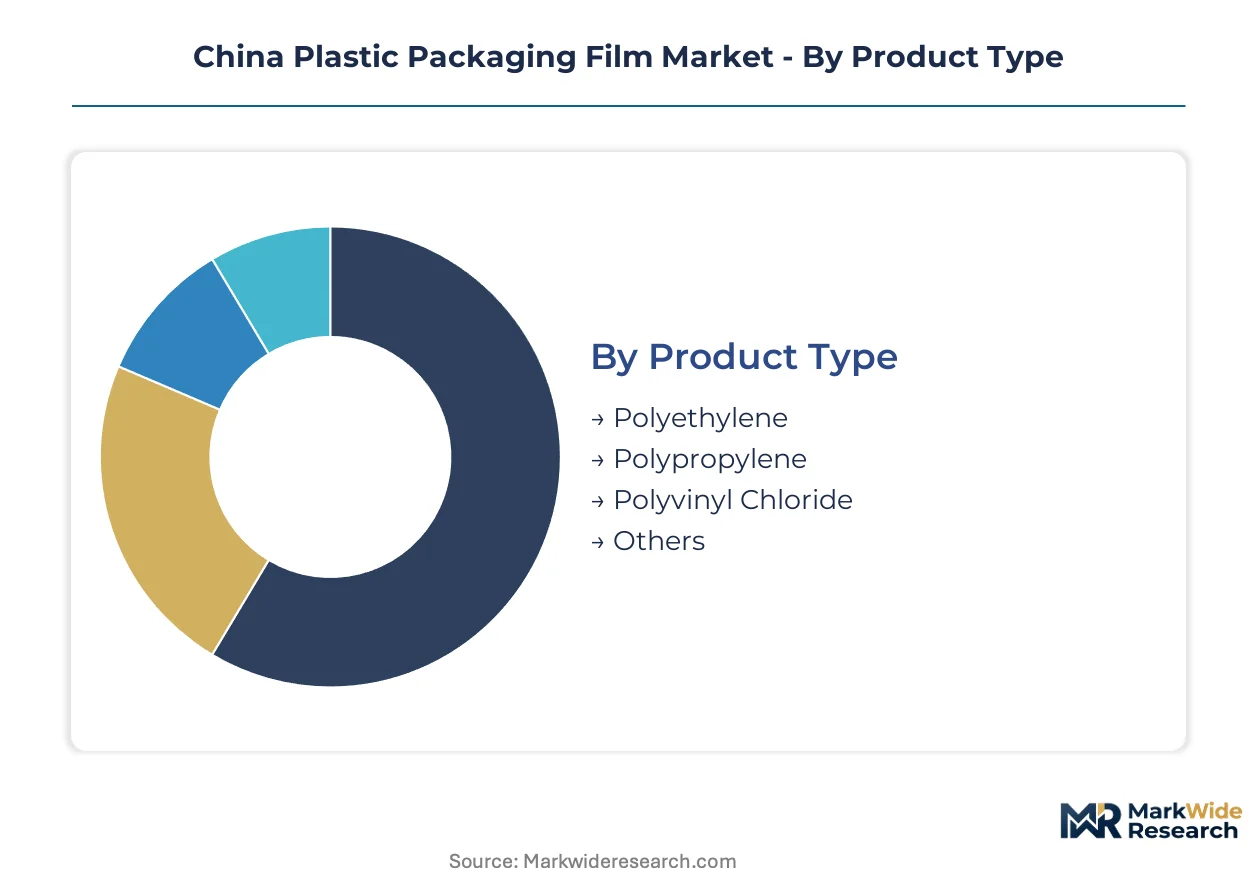
Converters in China configure extrusion lines around resin rheology and end-use barrier requirements, with product type and thickness specifications determining equipment investment and margin structure. Segmentation reveals where technical differentiation commands premium pricing versus commodity competition.
Product Type:
Polyethylene dominates standalone flexible packaging applications, while polypropylene embeds into rigid formats requiring thermal stability and optical performance.
- Polyethylene:Linear low-density and high-density grades constitute the volume foundation for fresh produce bags, frozen food pouches, and industrial liners. Demand concentrates in Zhejiang extrusion clusters serving domestic food brands, though coal-to-olefins capacity curtailments under MEE benchmarks are compressing margin stability for commodity producers.
- Polypropylene:Biaxially oriented films deliver the clarity and dimensional stability required for snack food lamination and cigarette overwrap. Guangdong converters with metallization capabilities capture premium specifications from multinational food manufacturers seeking oxygen barrier performance without aluminum foil.
- Polyvinyl Chloride:Shrink sleeve and blister pack applications persist in pharmaceutical and battery packaging despite regulatory pressure on plasticizer migration under GB standards.
- Others:Polyamide and EVOH coextrusion layers enable high-barrier structures for vacuum-packed meats and retort pouches, typically sourced through import channels or licensed domestic production.
Volume placements concentrate in Polyethylene; the faster expansion belongs to Polypropylene.
End User:
Cost tiers separate qualification-intensive pharmaceutical specifications from price-sensitive consumer goods wrapping.
- Food & Beverage:Ambient shelf-life extension drives multilayer barrier adoption across dairy, processed meat, and ready-meal categories. SAMR migration testing mandates are consolidating orders toward certified converters with in-house analytical laboratories in coastal provinces.
- Pharmaceuticals:Blister pack and cold-form foil laminates require validated cleanroom extrusion and documented batch traceability. Domestic drug manufacturers are qualifying local film suppliers to reduce import dependency on European and Japanese sources.
- Consumer Goods:Lightweight wrapping for electronics, textiles, and household products prioritizes gauge reduction and printability over barrier performance.
- Cosmetics:Premium brand owners specify high-clarity films with holographic or soft-touch finishes, sourcing through specialized converters with metallization and coating capabilities.
Food & Beverage commands absolute volume; Pharmaceuticals is climbing the fastest as localization accelerates.
Thickness:
Application requirements and material reduction targets create divergent specification bands across the micron spectrum.
- Below 20 Microns:Ultra-thin gauges displace 30-40 micron alternatives in lightweight consumer goods wrapping, enabled by advances in melt strength and haul-off control. Zhejiang and Guangdong converters with nine-layer coextrusion lines capture specification tightening from brand-led sustainability programs.
- 20-40 Microns:The historical standard for flexible food pouches and retail bags faces compression as downstream customers qualify thinner substitutes or upgrade to barrier-enhanced structures.
- 40-60 Microns:Mid-gauge films serve industrial liner and agricultural mulch applications where puncture resistance balances material cost.
- Above 60 Microns:Heavy-duty stretch film for pallet unitization and shrink wrapping for beverage multipacks require high tensile strength and elastic recovery, typically formulated with metallocene polyethylene or ethylene-vinyl acetate copolymers.
Below 20 Microns is gaining share fastest as converters pursue material reduction targets; Above 60 Microns retains the highest absolute tonnage in industrial applications.
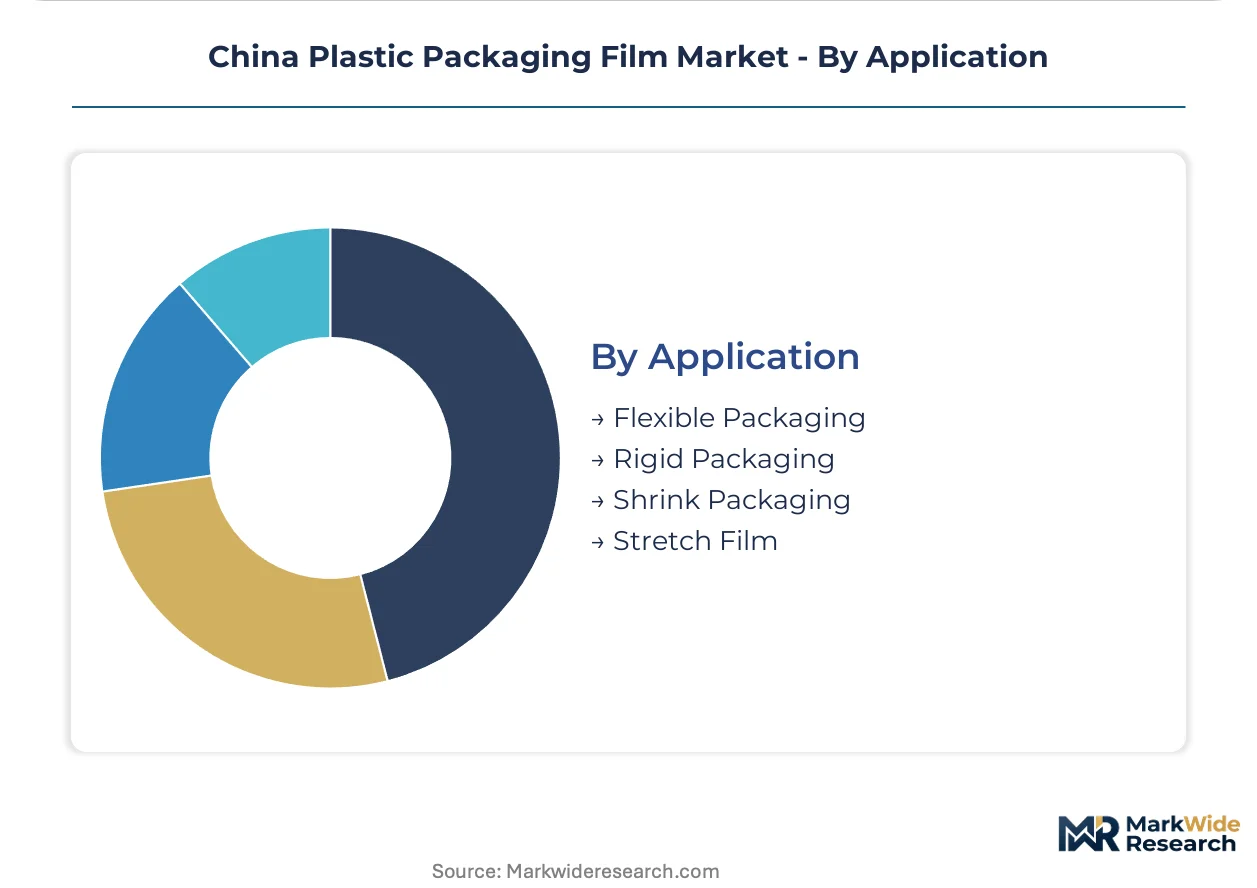
Application:
Supply concentration varies between format-agnostic commodity production and specialized equipment configurations.
- Flexible Packaging:Pouches, bags, and wraps constitute the dominant volume outlet, with converter margins bifurcating between monolayer commodity supply and multilayer barrier specialization.
- Rigid Packaging:Thermoformed trays and blister packs require oriented or cast films with controlled shrinkage and deep-draw formability, primarily serving pharmaceutical and fresh-protein segments.
- Shrink Packaging:Cross-linked and oriented films for beverage multipacks and printed labels demand precise shrink curve control and optical clarity.
- Stretch Film:Machine and hand-wrap grades for logistics unitization prioritize cling performance and load containment, with domestic producers achieving technical parity in cast lines but lagging in blown film premium grades.
Flexible Packaging holds volume concentration; Rigid Packaging shows steepest expansion trajectory as pharmaceutical localization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ningbo anchors China's plastic packaging film production, with extrusion clusters stretching across the Yangtze River Delta serving food brands and export channels through Shanghai and Ningbo-Zhoushan ports.
Zhejiang Province
Food and beverage brands in Hangzhou and Ningbo are scaling orders for multilayer barrier films to extend shelf life in ambient distribution. SAMR enforces GB standards on migration testing that consolidate demand toward certified converters with in-house laboratories. Wenzhou and Taizhou extrusion clusters concentrate nine-layer coextrusion capacity within 150 kilometers of Ningbo-Zhoushan port.
Guangdong Province
Snack food multinationals operating from Shenzhen and Guangzhou specify high-clarity biaxially oriented films for lamination and cigarette overwrap applications. Provincial carbon allowance trading schemes under MEE dual carbon goals reshape cost structures for coal-dependent resin inputs. Dongguan and Foshan house metallization capabilities that capture premium specifications from brand-led sustainability programs.
Jiangsu Province
Pharmaceutical manufacturers in Suzhou and Nanjing are qualifying local film suppliers for blister pack and cold-form foil laminates to reduce import dependency. SAMR mandates on additive disclosure compel reformulation of PVC shrink sleeve recipes for battery and pharmaceutical packaging. Changzhou extrusion corridors serve medical device clusters with validated cleanroom production.
Shandong Province
Industrial stretch film demand from Qingdao and Yantai logistics hubs drives above-60-micron gauge production for pallet unitization. MEE emissions intensity benchmarks disadvantage coal-powered resin producers in the province's chemical industrial parks. Weifang and Zibo converters pursue captive renewable energy partnerships to arbitrage provincial carbon allowance differentials.
Fujian Province
Xiamen-based converters leverage vertical integration across resin compounding and film extrusion to control cost positions in commodity polyethylene. GB standards harmonization on food-contact materials pushes mid-tier producers toward third-party testing dependencies that extend qualification timelines. Quanzhou packaging industrial zones serve textile and footwear export manufacturers with lightweight sub-20-micron wrapping films.
China Plastic Packaging Film Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology and certification depth, with the market structure bifurcating between multilayer coextrusion specialists and monolayer volume producers. Three archetypes dominate: vertically integrated resin-to-film operators controlling polyethylene cost positions, biaxially oriented technology leaders commanding optical clarity premiums, and pharmaceutical-grade specialists with validated cleanroom capabilities. Competitive moves concentrate on multilayer equipment retrofits for barrier enhancement and renewable energy offtake agreements to arbitrage provincial carbon allowance schemes.
Within the vertically integrated tier, Xiamen Changsu Industrial Co., Ltd exemplifies resin compounding and film extrusion control, while Toray Advanced Film Co., Ltd represents biaxially oriented polypropylene technology leadership. Zhejiang Kinlead Innovative Materials Co., Ltd anchors the pharmaceutical specialization archetype for blister pack applications.
| Leading Market Players |
|---|
| Xiamen Changsu Industrial Co., Ltd |
| Toray Advanced Film Co., Ltd |
| Berry Global Inc. |
| Kingchuan Packaging |
| Zhejiang Kinlead Innovative Materials Co., Ltd |
| Cosmo Films Limited |
| Zhejiang Jiuteng Packaging Co., Ltd |
| Fengjiang |
| Dadongnan |
| Others |
Pricing and Supply Chain Analysis
MEE dual carbon goals gate qualified supply and premium-tier pricing access, as converters with renewable energy certificates capture brand-led specifications while coal-dependent competitors face margin compression under provincial carbon allowance trading schemes.
Pricing Analysis
Barrier performance throughput anchors pricing tiers across the market. Three-tier pricing structure across premium, standard, and economy levels separates multilayer coextrusion films with validated GB compliance from monolayer commodity grades and uncertified imports. Cost compression in below-20-micron polyethylene is intensifying because technical parity has collapsed differentiation among domestic producers. Pharmaceutical blister pack specifications show least price sensitivity due to qualification barriers, while lightweight consumer goods wrapping exhibits highest sensitivity to per-kilogram resin costs.
Supply Chain Analysis
Post-consumer film collection and pyrolysis oil refining constitute emerging reverse-logistics flows, though chemically recycled feedstock volumes remain insufficient for food-contact compliance at scale. Resin supply concentrates in China, South Korea, and Saudi Arabia, with naphtha-linked polyethylene pricing tethered to crude oil volatility. The supply chain draws from coal-to-olefins and ethane-cracking feedstocks, with MEE emissions intensity benchmarks disadvantaging coal-powered producers. Single-source vulnerability runs through concentrated metallization equipment suppliers for barrier film production. Distribution runs through coastal extrusion clusters serving brand direct procurement and converter-to-converter resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive resin compounding and renewable energy offtake agreements determine cost positioning under provincial carbon allowance schemes.
For Market Incumbents: Anchor barrier technology leadership through nine-layer coextrusion equipment retrofits and in-house GB compliance laboratories. Consolidate position by acquiring mid-tier converters lacking migration testing capabilities, as SAMR enforcement extends qualification timelines for uncertified competitors. Defend against specialty film import substitution by qualifying pharmaceutical-grade cleanroom capacity. For New Entrants and Emerging Players: Enter via pharmaceutical blister pack localization, where domestic drug manufacturers are reducing European and Japanese import dependency. Target Jiangsu province medical device clusters with validated batch traceability capabilities. Pursue renewable energy captive supply partnerships to arbitrage carbon allowance differentials against coal-dependent incumbents. For Investors and Strategic Acquirers: Provincial carbon allowance price spikes are the leading indicator that renewable-energy-integrated converters will capture sustained margin premiums. Long-term viability favors specialty film producers with pharmaceutical certification depth and circular feedstock partnerships over commodity polyethylene volume players. Monitor MEE enforcement intensity on coal-to-olefins capacity curtailments as the inflection signal for resin input cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Xiamen Changsu's captive polyethylene supply controls cost volatility under naphtha price swings. |
| Multilayer Coextrusion Equipment Retrofit | Nine-layer lines enable oxygen barrier specialization for ambient shelf-life extension specifications. |
| Renewable Energy Captive Supply | Photovoltaic offtake agreements arbitrage Zhejiang carbon allowance penalties against coal-powered competitors. |
| Pharmaceutical Cleanroom Validation | GB-compliant batch traceability qualifies domestic converters for blister pack import substitution. |
| Circular Feedstock Partnership | Chemically recycled pyrolysis oil partnerships position converters for food-contact compliance ahead of virgin resin displacement. |
Research Methodology
Document review covered SAMR regulatory filings, MEE emissions benchmark disclosures, and customs trade data, complemented by interviews with extrusion plant managers, procurement leads at food and beverage brands, distribution channel partners, and technical R&D directors at resin suppliers. Secondary validation drew from GB standards documentation, provincial carbon allowance trading records, and SEC filings of multinational packaging companies. Bottom-up capacity estimates triangulated against top-down demand segmentation across product type, thickness, and end-use applications.
Cross-referencing historical capacity utilization patterns against panel input from converter executives shaped the analytical framework across the analysis window. Segmentation dimensions modeled include resin chemistry, thickness specification, barrier performance tier, end-use industry, and regional production cluster. CAGRs were derived from trend extrapolation moderated by regulatory inflection assumptions. Industry-specific forecast inputs incorporated coal-to-olefins capacity curtailment scenarios and pharmaceutical localization qualification timelines.
Revisions become necessary when MEE enforcement intensity on emissions benchmarks, SAMR migration testing mandate expansion, or coal-powered resin supply curtailments materialize differently than assumed. Forecasts reflect documented assumptions about carbon allowance price trajectories and brand-led sustainability specification tightening. Practitioners should monitor provincial carbon trading scheme liquidity and pharmaceutical qualification cycle durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Thermoforming Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
PP Laminating Films Market
Poly film
Polybag Mailers Market
Poly film
Co Extruded Films Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polysaccharide Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Easy Peel Film Packaging Market
Poly film
France Plastic Packaging Films Market
Poly film
Polycarbonate Films Market
Poly film
Bopet Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Silicone Release Films Market