
 Surface Printed Film Market | 2026-2036
Surface Printed Film Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Printed Film Market Analytics
ISO 22000 certification for food-contact materials is rotating supplier eligibility across the Surface Printed Film Market, locking out uncertified converters from premium food packaging contracts. Amcor Plc leverages its integrated film-to-package platform to sustain multi-region supply agreements. Mondi Group anchors European demand through kraft-paper hybrid printed structures. Constantia Flexibles Group GmbH specializes in pharmaceutical-grade printed lidding films with barrier precision.
Surface printed film denotes a polymeric substrate—typically PET, OPP, or PE ranging from 12 to 150 micrometers—bearing ink layers applied via continuous or discrete processes for branding, regulatory marking, or functional coding. These films serve as the primary visual and information interface between packaged goods and consumers across retail and industrial channels. Flexible Packaging dominates value contribution due to extended shelf-life demands and pouch format proliferation, while Shrink Sleeves represent the fastest-expanding product type driven by 360-degree decoration on contoured containers. Digital Printing is displacing conventional plate-based methods in short-run personalized campaigns, though Flexographic Printing retains margin concentration in high-volume food and beverage supply chains.
FDA food-contact substance notifications and EU REACH restrictions on aromatic amines in printing inks are tightening substrate-ink compatibility requirements, forcing reformulation investments across North American and European supply bases. BIS certification mandates in India and China's GB standards for food packaging plastics are fragmenting regional qualification pathways. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
ISO 22000 certification is rotating supplier eligibility across food-contact contracts, locking uncertified converters out of premium packaging procurement while redirecting formulation investments toward compliant ink and substrate systems.
Growth Catalysts
- PLI Scheme for Packaging Materials:India's production-linked incentive scheme accelerates domestic flexible packaging conversion, drawing investment toward surface printed film capacity expansion.
- FDA Food-Contact Substance Notifications:North American regulatory clarity on substrate-ink compatibility is channeling R&D spending toward pre-qualified material combinations.
- Shelf-Ready Format Proliferation:Food retail buyers are expanding printed film procurement for pre-decorated retail-ready packaging, compressing traditional label-to-shelf workflows.
Market Restraints
- Petrochemical Feedstock Volatility:PP and PE resin price swings compress converter margins and destabilize long-term contract pricing.
- REACH Aromatic Amine Restrictions:EU chemical regulations on printing ink constituents force costly reformulation cycles and supplier requalification.
- Digital Printing Plate Cost:Short-run personalization demands carry per-job setup penalties that offset volume flexibility gains.
Strategic Opportunities
- Pharmaceutical-Grade Lidding Films:Barrier-precision printed structures for blister packaging represent underpenetrated white space with premium pricing power.
- Kraft-Paper Hybrid Structures:Fiber-polymer laminate demand in European circular-economy frameworks creates substrate innovation openings.
- BIS Certification Pathways:India's mandatory quality standards for food packaging plastics reward early-compliant domestic producers with preferential public procurement access.
Industry Challenges
- Multi-Jurisdiction Qualification Overhead:Divergent FDA, REACH, BIS, and GB standards fragment compliance pathways and strand inventory across regional warehouses.
- Digital-Flexographic Skill Gap:Converter workforces trained on plate-based systems lack proficiency in color management for electrophotographic and inkjet workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Printed Film Market |
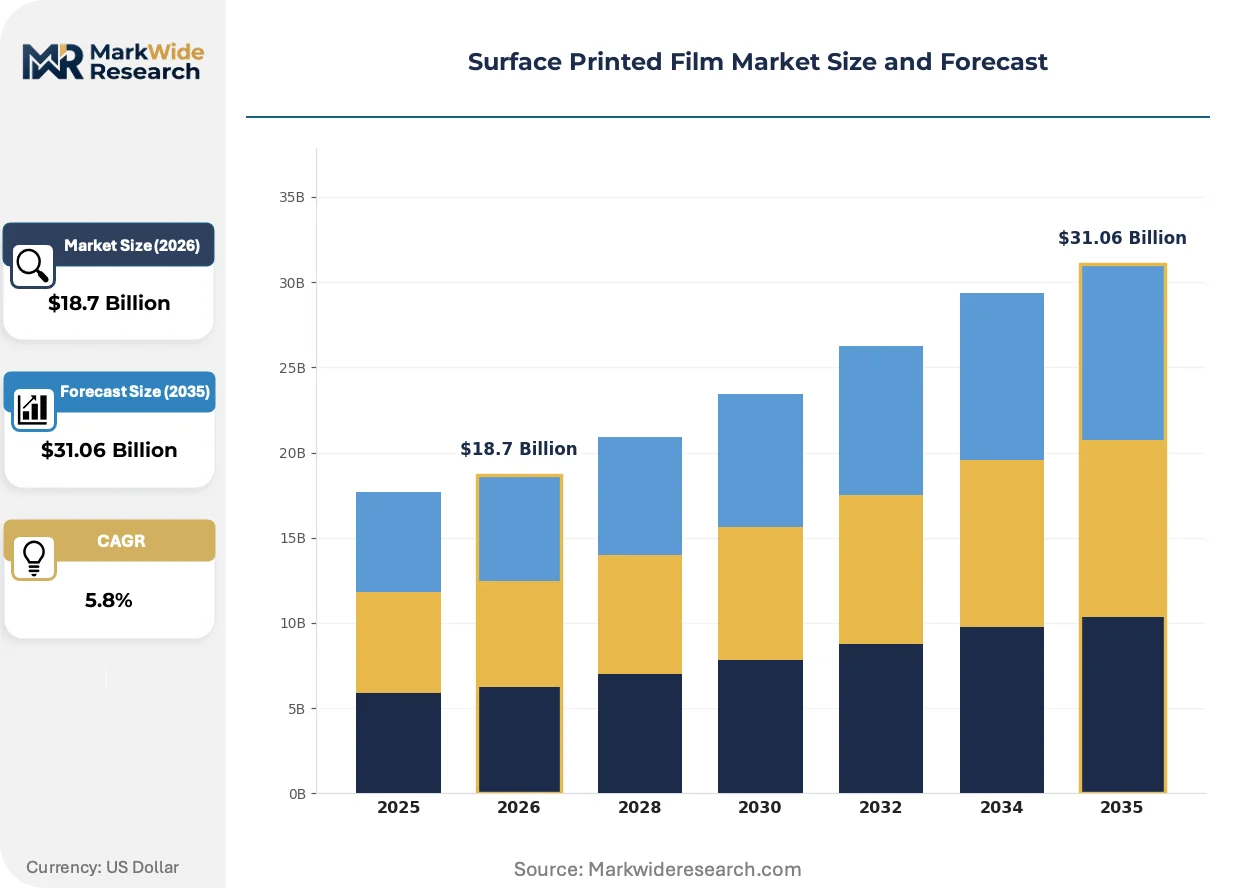
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive Labels, Flexible Packaging, Shrink Sleeves, In-Mold Labels Application: Food Packaging, Personal Care Products, Pharmaceuticals, Industrial Applications Technology: Digital Printing, Flexographic Printing, Gravure Printing, Offset Printing End User: Consumer Goods, Healthcare, Automotive, Home & Garden |
| Companies Covered | Sonoco Products Company, Mondi Group, Amcor Plc, Constantia Flexibles Group GmbH, DS Smith Plc, Berry Global Group, Inc., Sealed Air Corporation, Winpak Ltd, Huhtamaki oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Printed Film Market Evolving Landscape
Digital printing workflows, regulatory chemical restrictions, and procurement model compression are simultaneously reshaping how surface printed films are formulated, produced, and contracted across food, pharmaceutical, and industrial end-uses.
Electrophotographic and inkjet printing systems are decomposing the traditional plate-to-press workflow in short-run campaigns. Brand owners in personalized beverage and promotional cosmetics are adopting digital proofs within 48-hour windows. This technology is decomposing minimum order quantity thresholds that previously protected flexographic volume concentration.
REACH restrictions on aromatic amines in printing inks are tightening substrate-ink compatibility requirements across European supply bases. ECHA substance evaluations are forcing ink formulators toward pigment and binder substitutions with unproven migration profiles. Flexible food packaging converters in Germany and France are responding with accelerated laboratory screening partnerships to preempt regulatory non-conformity.
Retail buyers are consolidating printed film procurement through direct converter relationships, bypassing traditional label intermediaries. Major food and beverage chains are negotiating shelf-ready format specifications directly with film suppliers, compressing specification cycles from quarterly to monthly. This pattern is most visible in India's modern trade expansion and North American private-label proliferation.
Surface Printed Film Market Segmentation
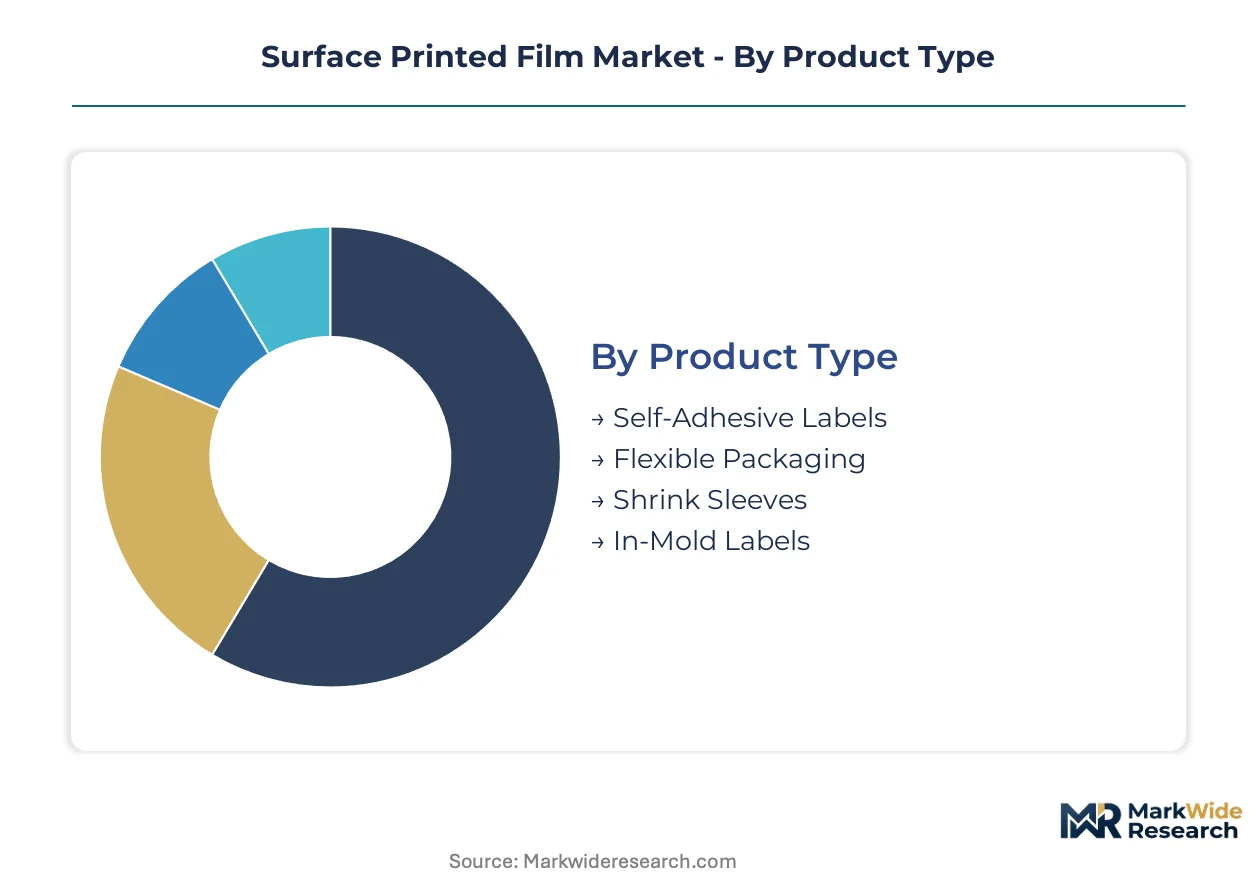
Surface printed film procurement patterns diverge sharply across substrate formats, regulatory exposure, and print run economics. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize qualification investments and capacity allocation.
Product Type:
Margin pools concentrate in barrier-precision formats where substrate engineering and ink chemistry must satisfy migration limits simultaneously.
- Flexible Packaging:Multi-layer laminates of PET, OPP, or PE substrates deliver oxygen and moisture barriers essential for shelf-stable foods. Demand concentrates in India's modern trade expansion and North American private-label proliferation, where pre-decorated pouch formats compress traditional label-to-shelf workflows.
- Shrink Sleeves:PETG or OPS substrates with 360-degree print coverage enable full-container decoration on contoured bottles and cans. Beverage and cosmetics brands in Germany and France are adopting these structures for promotional campaigns requiring rapid design turnaround.
- Self-Adhesive Labels:Pressure-sensitive facestocks with release liners serve secondary decoration and logistics marking across industrial and retail channels.
- In-Mold Labels:Polypropylene or polystyrene films fused directly into injection-molded containers during forming, eliminating post-mold labeling steps for durable goods packaging.
The dominant share belongs to Flexible Packaging, while Shrink Sleeves is closing the gap fastest.
Application:
Regulatory stringency varies dramatically across end-uses, with food-contact applications demanding the most exhaustive substrate-ink compatibility documentation.
- Food Packaging:Printed films must satisfy FDA food-contact substance notifications in the United States, EU REACH aromatic amine restrictions, and India's BIS certification mandates. Major retail chains in India and North America are negotiating shelf-ready specifications directly with converters.
- Pharmaceuticals:Blister lidding films and sachet structures require barrier precision against moisture, oxygen, and light. European demand anchors this segment through EMA-compliant packaging for solid-dose medications.
- Personal Care Products:Cosmetic and hygiene applications prioritize aesthetic differentiation through metallic effects and tactile coatings.
- Industrial Applications:Chemical-resistant labels and bulk packaging films serve logistics and manufacturing supply chains with less stringent migration testing requirements.
Food Packaging commands the largest revenue pool, though Pharmaceuticals delivers the highest margin per square meter.
Technology:
Capital intensity and run-length economics determine competitive positioning across print methods.
- Flexographic Printing:Rotary letterpress analog systems using photopolymer plates dominate high-volume food and beverage supply chains. The technology retains margin concentration in long-run contracts where plate amortization spreads across millions of impressions.
- Digital Printing:Electrophotographic and inkjet workflows eliminate plate costs and enable 48-hour proof cycles. Brand owners in promotional cosmetics and personalized beverages are adopting these systems for campaigns below ten thousand units.
- Gravure Printing:Engraved cylinder systems deliver unmatched ink laydown consistency for premium decorative applications in Asian markets.
- Offset Printing:Lithographic transfer methods serve paper-based label substrates with high-resolution graphics for wine and spirits packaging.
Flexographic Printing maintains volume leadership, while Digital Printing is expanding most quickly in short-run segments.
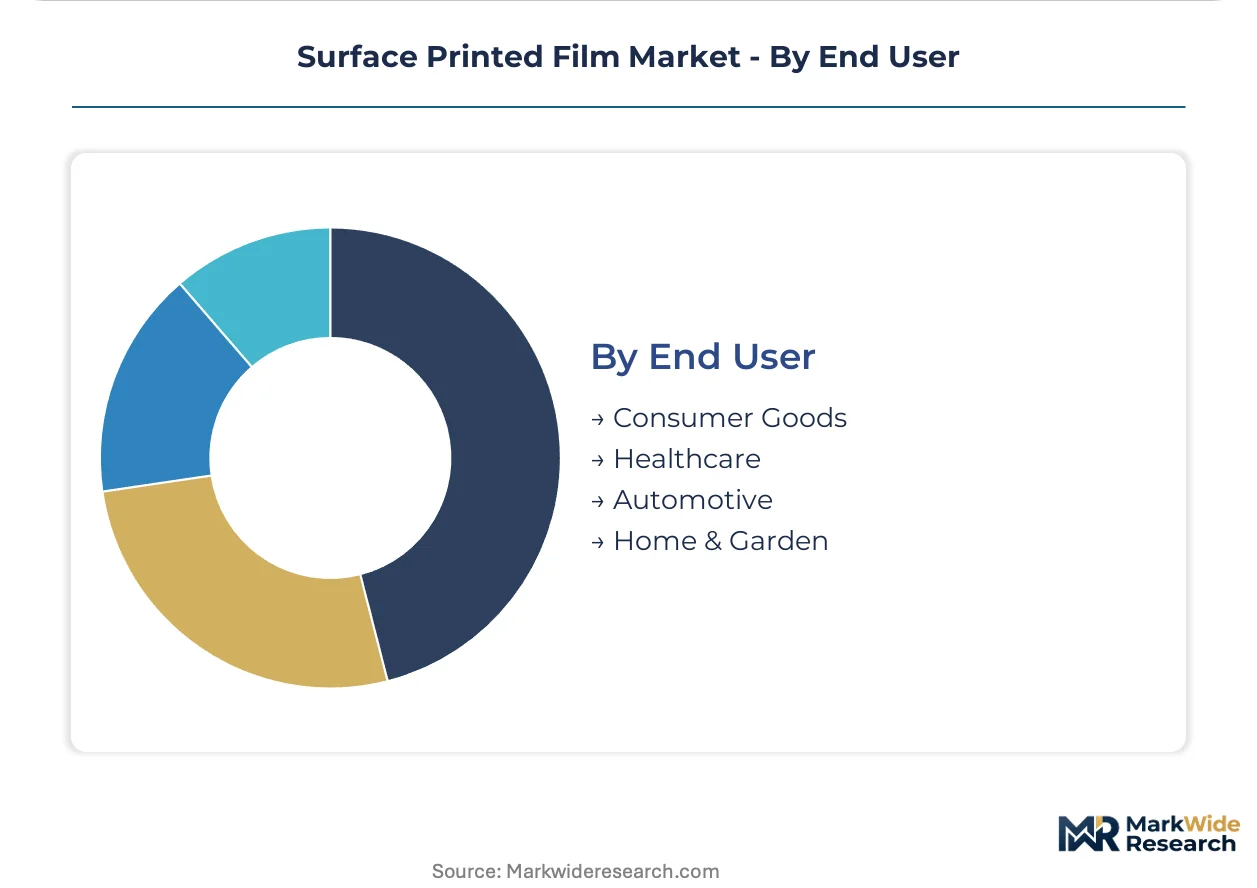
End User:
Customer concentration and contract duration shape supplier selection criteria across buyer categories.
- Consumer Goods:Food, beverage, and household product manufacturers represent the deepest procurement volume, with annual contract values sufficient to justify dedicated production lines.
- Healthcare:Pharmaceutical and medical device companies demand ISO 22000-certified converters with documented traceability from resin batch to finished film.
- Automotive:Under-hood labels and exterior decoration films must withstand thermal cycling and chemical exposure.
- Home & Garden:Seasonal demand patterns for lawn care and pest control products create volume spikes requiring flexible converter capacity.
Consumer Goods absorbs the majority of industry output, yet Healthcare offers the most stable multi-year contracting terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for packaging materials is redirecting investment toward domestic flexible film conversion, while REACH compliance in Europe and FDA notifications in North America fragment qualification pathways across major supply bases.
India
Modern trade expansion and shelf-ready format adoption are accelerating printed film procurement from domestic converters. BIS certification mandates for food packaging plastics reward early-compliant producers with preferential public procurement access. The Mumbai-Pune industrial corridor hosts concentrated flexible packaging capacity serving FMCG brands.
Germany
Pharmaceutical-grade lidding film demand and kraft-paper hybrid structures anchor European barrier-precision requirements. ECHA substance evaluations on aromatic amine restrictions force accelerated laboratory screening partnerships among ink formulators. The Düsseldorf-Cologne packaging cluster concentrates gravure and flexographic conversion expertise.
United States
Private-label proliferation and direct retailer-converter negotiations compress specification cycles for pre-decorated pouch formats. FDA food-contact substance notifications channel R&D toward pre-qualified substrate-ink combinations. Chicago and Wisconsin host multi-region supply agreements for food and beverage packaging films.
China
GB standards for food packaging plastics and dual carbon goals are reshaping substrate selection in domestic flexible packaging. Digital printing adoption in promotional cosmetics enables rapid design turnaround below traditional minimum order quantities. The Yangtze River Delta concentrates film extrusion and printing capacity for export and domestic markets.
Brazil
Consumer goods manufacturing expansion drives procurement volume for flexible packaging serving household and personal care segments. ANVISA pharmaceutical packaging regulations elevate documentation requirements for barrier-precision films. The São Paulo state industrial belt anchors South American conversion capacity for regional brand owners.
Surface Printed Film Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive film extrusion and print capabilities, creating tiered competition between global scale operators and regional specialists. Three strategic archetypes dominate: multi-region platform integrators, European kraft-paper hybrid innovators, and pharmaceutical-grade barrier specialists. Consolidation through acquisition and backward integration into resin and substrate production represent the primary competitive vectors.
Among integrated platform operators, Amcor Plc and Mondi Group exemplify archetypes spanning film-to-package vertical control. Constantia Flexibles Group GmbH occupies the specialist tier with pharmaceutical-grade precision positioning. These three anchors demonstrate how geographic footprint breadth and regulatory qualification depth separate premium-tier suppliers from commodity converters.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Mondi Group |
| Amcor Plc |
| Constantia Flexibles Group GmbH |
| DS Smith Plc |
| Berry Global Group, Inc. |
| Sealed Air Corporation |
| Winpak Ltd |
| Huhtamaki oyj |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day inventory cycles for resin-to-film conversion dominate converter balance sheets, compressing margin buffers when petrochemical feedstock volatility spikes and amplifying pricing power for integrated producers with captive substrate supply.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with ISO 22000-certified pharmaceutical-grade films commanding substantial premiums over standard food-contact grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by migration-testing documentation depth and barrier-performance specifications. Cost compression in standard-grade flexible packaging is intensifying because India's PLI scheme is accelerating domestic capacity addition. Small regional converters exhibit highest price sensitivity, while multinational FMCG procurement teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and Mumbai port congestion periodically strand resin shipments, forcing Indian converters to maintain elevated safety stock of PET and OPP substrates. Supply concentrates in China, India, and Germany, with film extrusion and gravure printing capacity clustering in the Yangtze River Delta, Mumbai-Pune corridor, and Düsseldorf-Cologne belt. Raw material dependencies rest on PP and PE resin from Gulf petrochemical complexes, photopolymer plates from Japanese suppliers, and specialty pigments from German chemical producers. Single-source vulnerability in pharmaceutical-grade barrier coatings creates qualification bottlenecks. Distribution runs through direct converter-retailer relationships that bypass traditional label distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through direct procurement relationships between major retail chains and film converters, fragmenting traditional distributor intermediaries and compressing specification cycles.
For Market Incumbents: Compound qualification depth across multi-jurisdiction regulatory pathways to lock out uncertified competitors from premium food and pharmaceutical contracts. Prioritize backward integration into resin compounding and captive ink formulation to insulate margins from petrochemical volatility. Defend against digital printing specialists by embedding flexographic volume commitments into multi-year supply agreements with penalty clauses for short-run diversion. For New Entrants and Emerging Players: Short-run personalization service gaps in promotional cosmetics and craft beverage segments offer immediate white-space penetration. Target India's BIS certification pathway acceleration, where early compliance unlocks preferential public procurement access before domestic capacity saturates. Pursue asset-light digital printing partnerships with established converters to bypass capital-intensive cylinder and plate infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-qualification compounder play because divergence between FDA, REACH, BIS, and GB standards creates durable moats for multi-certified operators. Acquisition targets should display ISO 22000 certification, pharmaceutical-grade barrier expertise, and established relationships with EMA or FDA submission pathways. Watch for inflection when India's PLI scheme triggers domestic overcapacity and compresses returns for late entrants without qualification differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PP and PE supply insulates converters from Gulf petrochemical price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, REACH, and BIS qualification opens premium pharmaceutical and food contracts. |
| Digital Printing Platform Partnership | Electrophotographic and inkjet alliances capture short-run promotional cosmetics volume. |
| Kraft-Paper Hybrid Structure Development | Fiber-polymer laminates align with EU circular-economy packaging mandates. |
| Direct Retailer Relationship Consolidation | Bypassing label distributors compresses specification cycles and locks in shelf-ready format demand. |
Research Methodology
Initial hypotheses were tested against primary input from flexible packaging procurement managers, ink formulation chemists, pharmaceutical packaging engineers, and retail category buyers, and refined through secondary validation against BIS certification databases, ECHA substance evaluation registers, FDA food-contact substance notifications, and customs trade flow records. Bottom-up triangulation across converter capacity utilization surveys and top-down reconciliation against resin consumption data anchored volume estimates.
Variance decomposition across substrate type, print technology, end-use regulatory exposure, and geographic production cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated PLI scheme disbursement trajectories, EMA packaging guideline revisions, and digital printing adoption curves in promotional segments.
Underlying assumptions cover sustained resin price volatility, regulatory divergence persistence, and digital-flexographic technology substitution rates, with deviation risk concentrated in abrupt REACH aromatic amine restriction tightening or India's BIS enforcement acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Colombia Plastic Packaging Films Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Global Reclosable Films Market
Poly film
Hexacomb Packaging Market
Poly film
Laminated Packaging Films Market
Poly film
PCR Bubble Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Shrink Bundling Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Resealable Films Market
Poly film
Twist Wrap Film Market
Poly film
Chocolate Wrapping Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Silicone Release Films Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
United States Polycarbonate Sheets and Films Market