
 GHS Labels Market | 2026-2036
GHS Labels Market Size, Share, and Industry Trends Forecast 2026-2036
GHS Labels Market Analysis
China is narrowing its reliance on imported GHS label substrates through expanded domestic film extrusion and adhesive coating lines in Jiangsu and Zhejiang provinces. Avery Dennison Corporation leverages its pressure-sensitive materials portfolio to anchor North American supply chains for chemical drum labeling. UPM Raflatac specializes in sustainable facestock alternatives that compete on regulatory compliance in European pharmaceutical applications. 3M Company controls distribution of high-performance polyester constructions for extreme-environment hazard communication.
GHS labels are pressure-sensitive or heat-transfer constructions combining durable facestocks with regulatory-compliant pictograms, signal words, and hazard statements printed to withstand chemical exposure, UV degradation, and abrasion across multi-year product lifecycles. Their primary purpose is to communicate substance hazards under standardized classification systems that OSHA, REACH, and transport regulations mandate. Hazard labels dominate volume within the label type dimension as chemical drum and bulk container marking requirements expand across manufacturing sectors. Polyester and polypropylene materials represent the fastest-growing material category due to superior solvent resistance and extended outdoor durability compared to paper alternatives. Chemical manufacturers anchor the end user segment, though pharmaceutical companies are deepening procurement of instruction labels for combination product packaging.
OSHA's Hazard Communication Standard enforces GHS-aligned labeling for workplace chemical containers in the United States, while ECHA administers CLP regulation that governs substance and mixture classification across European member states. China's MEE implements GB standards that incorporate GHS pictogram and precautionary statement requirements for domestic chemical production and import. Stakeholders must monitor divergence between national implementation schedules as regulatory authorities update hazard class criteria and digital labeling provisions.
Market Dynamics
Chemical drum labeling requirements are tightening across industrialized economies as OSHA, REACH, and China's GB standards enforce stricter hazard communication durability specifications, forcing substrate suppliers to upgrade solvent-resistant constructions.
Growth Catalysts
- OSHA Hazard Communication Standard alignment:United States chemical manufacturers must procure GHS-compliant labels for workplace containers, expanding demand for pressure-sensitive constructions that withstand chemical exposure.
- China's domestic chemical production scaling:Jiangsu and Zhejiang provinces are expanding film extrusion capacity to supply local label converters serving MEE-enforced GB standards.
- Polyester substrate adoption:Superior UV degradation resistance and extended outdoor lifecycles are displacing paper alternatives in bulk container marking applications.
Market Restraints
- Petrochemical feedstock volatility:Polyester and polypropylene resin prices fluctuate with crude oil markets, compressing converter margins on long-term supply contracts.
- Adhesive coating concentration:Specialized solvent-resistant formulations rely on a limited supplier base in Germany and Japan, creating single-source vulnerability.
- Regulatory divergence friction:ECHA's CLP updates and OSHA's implementation schedules misalign on hazard class criteria, forcing dual-sku inventory strategies.
Strategic Opportunities
- India's chemical sector expansion:BIS standards adoption and domestic manufacturing incentives under PLI schemes are opening procurement channels for compliant label substrates.
- Digital labeling provisions:ECHA's exploration of QR-code hazard communication creates white space for smart label integration with traditional pictogram constructions.
- Pharmaceutical combination products:Instruction label demand for drug-device packaging exceeds current converter capacity in European markets.
Industry Challenges
- Multi-jurisdiction certification timelines:Separate testing protocols for OSHA, CLP, and GB compliance extend product launch cycles by 8-14 months.
- Legacy print infrastructure retrofitting:Converters must integrate UV-curable ink systems to meet abrasion resistance specifications without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GHS Labels Market |
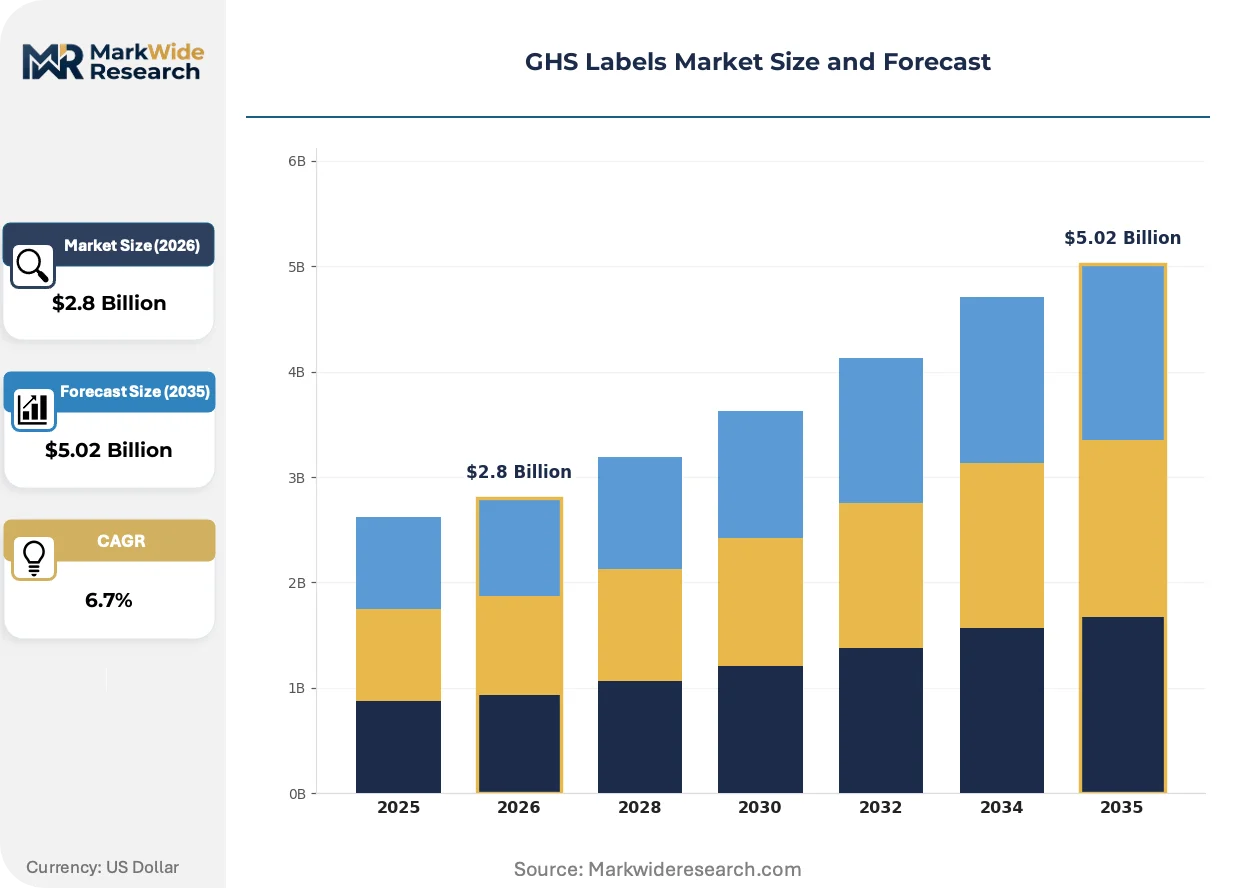
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Workplace Labels, Shipping Labels, Hazard Labels, Instruction Labels Material: Paper, Vinyl, Polyester, Polypropylene End User: Chemical Manufacturers, Pharmaceutical Companies, Transportation Services, Retailers Application Sector: Pharmaceutical, Chemicals, Logistics, Manufacturing |
| Companies Covered | UPM Raflatac, Lintec Corporation, Avery Dennison Corporation, Multi Color Corporation, Constantia Flexibles, 3M Company, CCL Industries Inc., Schreiner Group, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GHS Labels Market Emerging Trajectories
Substrate engineering and regulatory digitization are converging to redefine durability benchmarks and information delivery methods in hazard communication materials.
Multi-layer laminate constructions are hybridizing pressure-sensitive adhesives with heat-transfer activation capabilities. Chemical manufacturers in the United States and Germany are piloting these dual-mode labels to streamline drum relabeling during substance reclassification events. This technology is hybridizing procurement categories that previously required separate inventory stocks for initial marking and retrofit applications.
REACH subsidiary regulation updates are expanding substance restriction lists that affect adhesive chemistries. Industrial label converters in the European Union are reformulating solvent-based coatings to meet SVHC thresholds without sacrificing peel adhesion on low-surface-energy plastics. Pharmaceutical packaging lines in Belgium and the Netherlands are experiencing the steepest compliance cost increases as they migrate to water-based alternatives.
Consolidated procurement frameworks are compressing supplier rosters at major chemical producers. BASF and Dow facilities in Texas and Louisiana are mandating single-source label contracts with integrated design-to-delivery accountability, displacing fragmented converter relationships. This concentration is most visible in Gulf Coast petrochemical corridors where enterprise resource planning integration now outweighs unit price in vendor selection criteria.
GHS Labels Market Segmentation
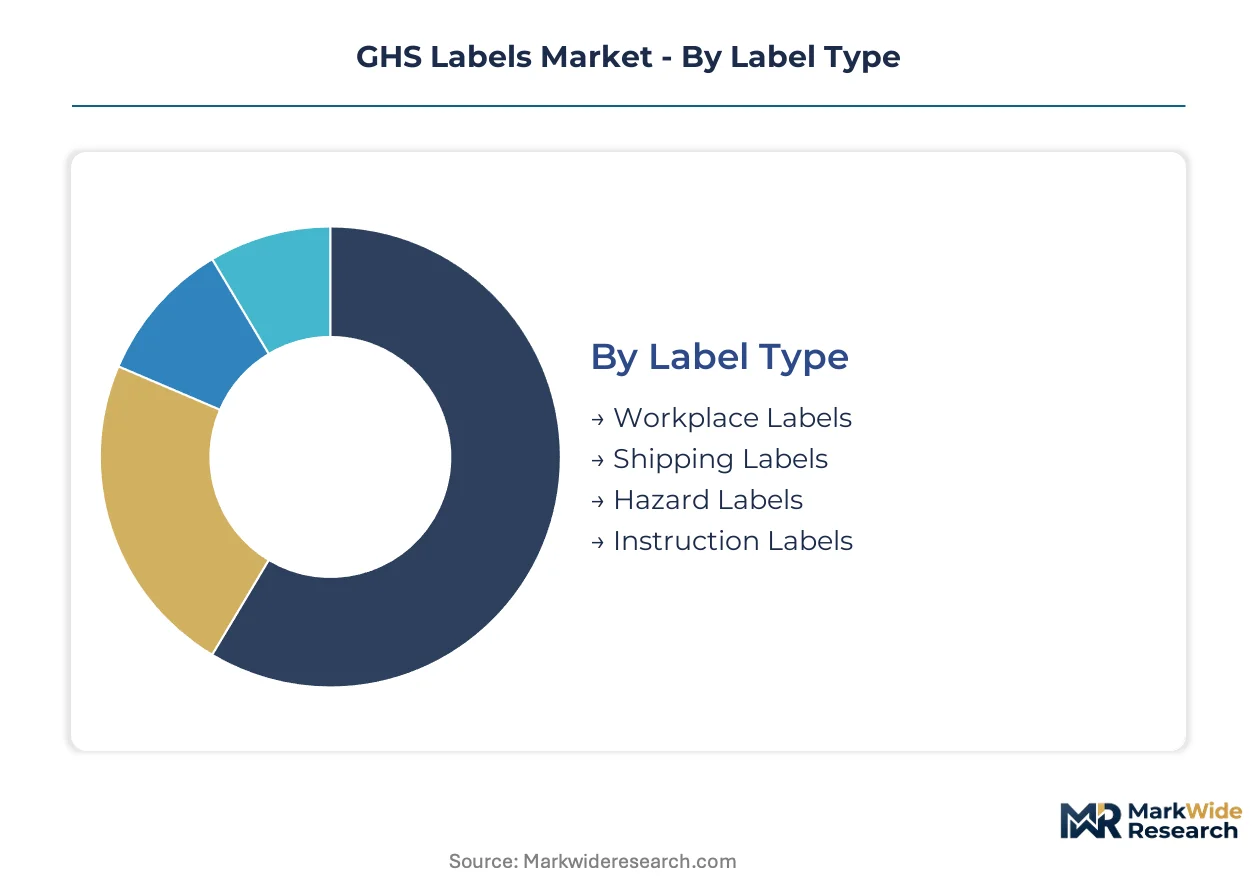
GHS label procurement varies sharply across use cases, from bulk chemical drum marking to precision pharmaceutical instruction inserts. Substrate selection and regulatory durability requirements create distinct technical specifications that segment converter capabilities and end-user sourcing strategies.
Label Type:
The use-case spectrum spans workplace safety communication, transport documentation, hazard pictogram display, and product instruction delivery.
- Hazard Labels:Pressure-sensitive constructions featuring standardized pictograms, signal words, and hazard statements printed to withstand chemical exposure and UV degradation. OSHA-enforced workplace container marking in the United States and ECHA-administered CLP compliance across European member states concentrate procurement volume here. Solvent-resistant polyester facestocks are displacing paper alternatives as durability specifications tighten.
- Instruction Labels:Multi-panel foldout or booklet constructions combining precautionary statements with handling procedures for pharmaceutical combination products. Demand concentrates in Belgian and Dutch packaging corridors where REACH subsidiary regulations on adhesive chemistries are forcing water-based coating migrations.
- Workplace Labels:Secondary container markings for laboratory and manufacturing floor chemical transfers.
- Shipping Labels:Transport documentation overlays combining hazard class diamonds with UN number and proper shipping name fields.
Established volume favors Hazard Labels; emerging adoption favors Instruction Labels.
Material:
Cost tiers separate commodity paper stocks from engineered film constructions with certified chemical resistance.
- Polyester:High-performance thermoplastic facestock with superior dimensional stability and extended outdoor lifecycles. China's Jiangsu and Zhejiang film extrusion expansions are narrowing import dependence for domestic chemical producers under MEE-enforced GB standards. UV-curable ink compatibility and abrasion resistance specifications favor this substrate in bulk container applications.
- Polypropylene:Lightweight olefin film with balanced chemical resistance and conformability to curved drum surfaces. German and Japanese adhesive coating specialists control solvent-resistant formulation supply, creating single-source vulnerability for converters serving ECHA CLP requirements.
- Vinyl:Flexible calendered constructions for short-term outdoor exposure and temporary hazard marking.
- Paper:Uncoated and coated stocks for indoor, low-exposure applications with limited durability requirements.
Polyester and polypropylene are climbing the fastest as chemical drum specifications harden; paper retains position only in cost-constrained indoor workflows.
End User:
Customer type determines batch size, certification burden, and integration depth with enterprise resource planning systems.
- Chemical Manufacturers:High-volume drum and IBC marking programs with integrated design-to-delivery accountability requirements. BASF and Dow facilities in Texas and Louisiana are consolidating supplier rosters to single-source contracts, displacing fragmented converter relationships. Gulf Coast petrochemical corridors anchor procurement concentration.
- Pharmaceutical Companies:Instruction label demand for drug-device combination products exceeds current European converter capacity. REACH SVHC thresholds on adhesive chemistries are driving reformulation costs in Belgian and Netherlands packaging lines.
- Transportation Services:Multi-modal carriers requiring harmonized hazard communication across air, sea, and road freight.
- Retailers:Downstream distributors managing secondary labeling for consumer chemical repackaging.
Chemical Manufacturers dominate procurement scale; Pharmaceutical Companies represent the steepest compliance cost trajectory.
Application Sector:
Geography and margin profiles vary across regulated industrial verticals with distinct hazard classification protocols.
- Chemicals:Primary demand anchor spanning basic and specialty chemical production with OSHA, ECHA CLP, and China GB standard compliance requirements. Drum relabeling during substance reclassification events is piloting dual-mode pressure-sensitive and heat-transfer hybrid constructions in the United States and Germany.
- Pharmaceutical:Combination product packaging with instruction label complexity exceeding standard hazard communication. ECHA exploration of QR-code provisions creates smart label integration potential alongside traditional pictogram constructions.
- Logistics:Freight forwarding and warehousing operations managing transport documentation and temporary hazard marking.
- Manufacturing:Industrial facilities integrating GHS-aligned labeling with broader workplace safety management systems.
Chemicals sector commands substrate innovation investment; Pharmaceutical sector is gaining share fastest on regulatory digitization tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA anchors the dominant geography through its Hazard Communication Standard alignment with GHS pictogram and signal word requirements. Chemical drum procurement in Texas and Louisiana petrochemical corridors drives substrate demand for solvent-resistant polyester constructions. Regulatory divergence between OSHA, ECHA, and China's MEE creates multi-jurisdiction compliance complexity for converters serving multinational chemical manufacturers.
United States
Gulf Coast chemical producers are consolidating supplier rosters to single-source contracts with design-to-delivery accountability. OSHA enforces workplace container marking durability specifications that favor UV-curable ink systems on polyester facestocks. BASF and Dow facilities in Texas and Louisiana anchor procurement concentration for pressure-sensitive drum labels.
Germany
ECHA-administered CLP regulation governs substance classification with subsidiary REACH updates expanding SVHC restrictions on adhesive chemistries. Industrial label converters in the Ruhr region are reformulating solvent-based coatings to maintain peel adhesion on low-surface-energy plastics. Heat-transfer and pressure-sensitive hybrid constructions are piloting in Ludwigshafen and Leverkusen chemical clusters.
China
Domestic chemical production scaling in Jiangsu and Zhejiang provinces is narrowing import dependence for GHS label substrates. MEE implements GB standards incorporating GHS pictogram requirements with intensifying enforcement on domestic producers. Film extrusion and adhesive coating line expansions in Yangtze River Delta manufacturing corridors supply local converter networks.
India
BIS standards adoption and PLI scheme manufacturing incentives are opening procurement channels for compliant label substrates. The national chemical regulator is aligning hazard communication requirements with GHS classification systems. Gujarat and Maharashtra industrial corridors are attracting pressure-sensitive material investments to serve domestic pharmaceutical and agrochemical packaging.
Belgium
Pharmaceutical combination product packaging is driving instruction label demand that exceeds current European converter capacity. ECHA exploration of QR-code hazard communication provisions creates smart label integration potential. Antwerp and Ghent packaging lines are experiencing steepest compliance cost increases from water-based adhesive migrations.
GHS Labels Market Vendor Landscape
Capability concentration sits with specialized adhesive coating and film extrusion tiers; scale advantage sits with integrated pressure-sensitive materials portfolios. The market structure reflects dual-tier dynamics where substrate engineering expertise and regulatory certification depth separate premium positioning from commodity supply. Strategic archetypes include integrated materials-science conglomerates, specialized label converters with vertical film control, and regional adhesive formulators. Competitive moves center on backward integration into resin compounding and captive supply of solvent-resistant coating chemistries.
Within the integrated materials tier, Avery Dennison Corporation and 3M Company exemplify scale-driven positioning through pressure-sensitive technology portfolios and distribution infrastructure. UPM Raflatac occupies a specialist position representing sustainable facestock alternatives that compete on regulatory compliance. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic emphasis: the US-based conglomerates leverage materials science breadth, while the Finnish limited company concentrates on environmental differentiation in European pharmaceutical applications.
| Leading Market Players |
|---|
| UPM Raflatac |
| Lintec Corporation |
| Avery Dennison Corporation |
| Multi Color Corporation |
| Constantia Flexibles |
| 3M Company |
| CCL Industries Inc. |
| Schreiner Group |
| Brady Corporation |
| Others |
Supply Flow & Price Mechanics
German and Japanese adhesive coating specialists control solvent-resistant formulation supply, concentrating margin capture upstream while converters downstream face compressed pricing power on long-term chemical drum contracts.
Pricing Analysis
North American polyester facestocks command 15-25% premiums over Asian-sourced alternatives due to OSHA durability certification and Gulf Coast petrochemical corridor proximity. Pricing stratifies across premium certified grades, standard commercial constructions, and economy paper-based alternatives. Cost compression in the economy tier is intensifying as Chinese film extrusion capacity expands in Jiangsu and Zhejiang. Small-batch pharmaceutical converters exhibit highest price sensitivity; integrated chemical manufacturers like BASF and Dow prioritize design-to-delivery accountability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for polyester resin and pressure-sensitive adhesive imports. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, German specialty coating chemistries, and Chinese film extrusion outputs. Single-source vulnerability concentrates in solvent-resistant adhesive formulations from German and Japanese suppliers. Distribution runs through converter networks serving regional chemical manufacturing clusters with direct ERP integration at major accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GHS label demand is accelerating on regulatory digitization tailwinds as ECHA explores QR-code hazard communication provisions, creating technology disruption vectors for substrate and smart label integration.
For Market Incumbents: Harden solvent-resistant coating capabilities through captive supply of adhesive chemistries or exclusive partnerships with German and Japanese formulators. Defend against Chinese film extrusion expansion by embedding deeper into BASF and Dow enterprise resource planning systems with integrated design-to-delivery contracts. Prioritize UV-curable ink system investments to maintain abrasion resistance specifications without full line replacement costs. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical and agrochemical packaging corridors where BIS standards adoption and PLI scheme incentives are opening procurement channels before incumbent consolidation. Target instruction label demand for drug-device combination products in Belgian and Dutch packaging lines where current European converter capacity falls short. Lead with water-based adhesive formulations that anticipate REACH SVHC threshold compliance. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with vertical film extrusion control and established OSHA-ECHA-GB triple-certification capabilities that multinational chemical manufacturers increasingly mandate. Long-term viability hinges on regulatory digitization readiness as smart label integration transitions from pilot to procurement requirement. Watch ECHA's QR-code hazard communication implementation timeline as the definitive inflection signal for technology-enabled positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Coating | Captive supply of solvent-resistant formulations reduces single-source dependency on German and Japanese specialists. |
| Dual-Mode Label Technology Launch | Pressure-sensitive and heat-transfer hybrid constructions streamline drum relabeling for substance reclassification events at BASF and Dow facilities. |
| Water-Based Coating Migration | REACH SVHC compliance in Belgian and Dutch pharmaceutical packaging lines ahead of regulatory enforcement curves. |
| ERP Integration Partnership | Direct system connectivity with Gulf Coast petrochemical corridors displaces fragmented converter relationships. |
| Smart Label Capability Buildout | QR-code integration positions for ECHA digital labeling provisions alongside traditional pictogram constructions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association publications. Primary interviews engaged label converter operations managers, chemical manufacturer procurement leads, adhesive formulation R&D directors, and pharmaceutical packaging engineers. Secondary validation drew from OSHA Hazard Communication Standard updates, ECHA CLP regulation amendments, China MEE GB standard enforcement notices, and SEC 10-K disclosures from listed materials companies. Bottom-up demand modeling triangulated against top-down market sizing across substrate material categories.
Forecast inputs incorporate label type segmentation by hazard, instruction, workplace, and shipping constructions; material tiers spanning polyester, polypropylene, vinyl, and paper stocks; end-user categories from chemical manufacturers through pharmaceutical companies; and application sectors across chemicals, pharmaceuticals, logistics, and manufacturing. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window. Industry-specific modeling integrated regulatory implementation schedules for OSHA, ECHA, and China MEE alongside domestic chemical production scaling trajectories in Jiangsu, Zhejiang, Gujarat, and Maharashtra.
Sensitivities concentrate around petrochemical feedstock volatility, regulatory divergence between OSHA-ECHA-GB implementation timelines, and adhesive coating supply concentration in Germany and Japan. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Indicative Seals Market
Labels
High Gloss Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Variable Data Printing Labels Market
Labels
Primary Packaging Labels Market
Labels
Warning Labels and Stickers Market
Labels
Global Industrial Labels Market
Labels
Global Security Labels Market
Labels
Barcode Label Market
Labels
GCC Labels and Release Liners Market
Labels
Self-Laminating Labels Market
Labels
Laser Markable Labels Market
Labels
Global in-Mold Labels Market
Labels
BOPP Labels Market
Labels
Direct Thermal Linerless Labels Market
Labels
Pre-Gummed Labels Market