
 United States Polycarbonate Sheets and Films Market | 2026-2036
United States Polycarbonate Sheets and Films Market Size, Share, and Industry Trends Forecast 2026-2036
United States Polycarbonate Sheets and Films Market Analytics
Single-source resin procurement is rebalancing toward diversified supply agreements across the US polycarbonate value chain. Covestro AG leverages its Baytown, Texas production complex to sustain domestic resin availability for sheet extruders. Trinseo anchors its position through specialized optical-grade formulations serving electronics and medical end users. SABIC competes via high-performance Lexan resin technology leadership in safety and glazing applications.
Polycarbonate sheets and films are thermoplastic polymer products manufactured through extrusion or calendering of bisphenol-A derived resin, offering light transmission rates exceeding 85% alongside impact resistance 250 times that of glass. These properties serve primary purposes in architectural glazing, protective barriers, and electronic display substrates. Clear sheets dominate commercial glazing installations where optical clarity and UV stability command premium positioning. Multiwall sheets capture fastest growth in agricultural and industrial roofing where thermal insulation properties reduce HVAC loads. Films occupy specialized margin pools in medical device packaging and automotive instrument cluster overlays where precision thickness control matters.
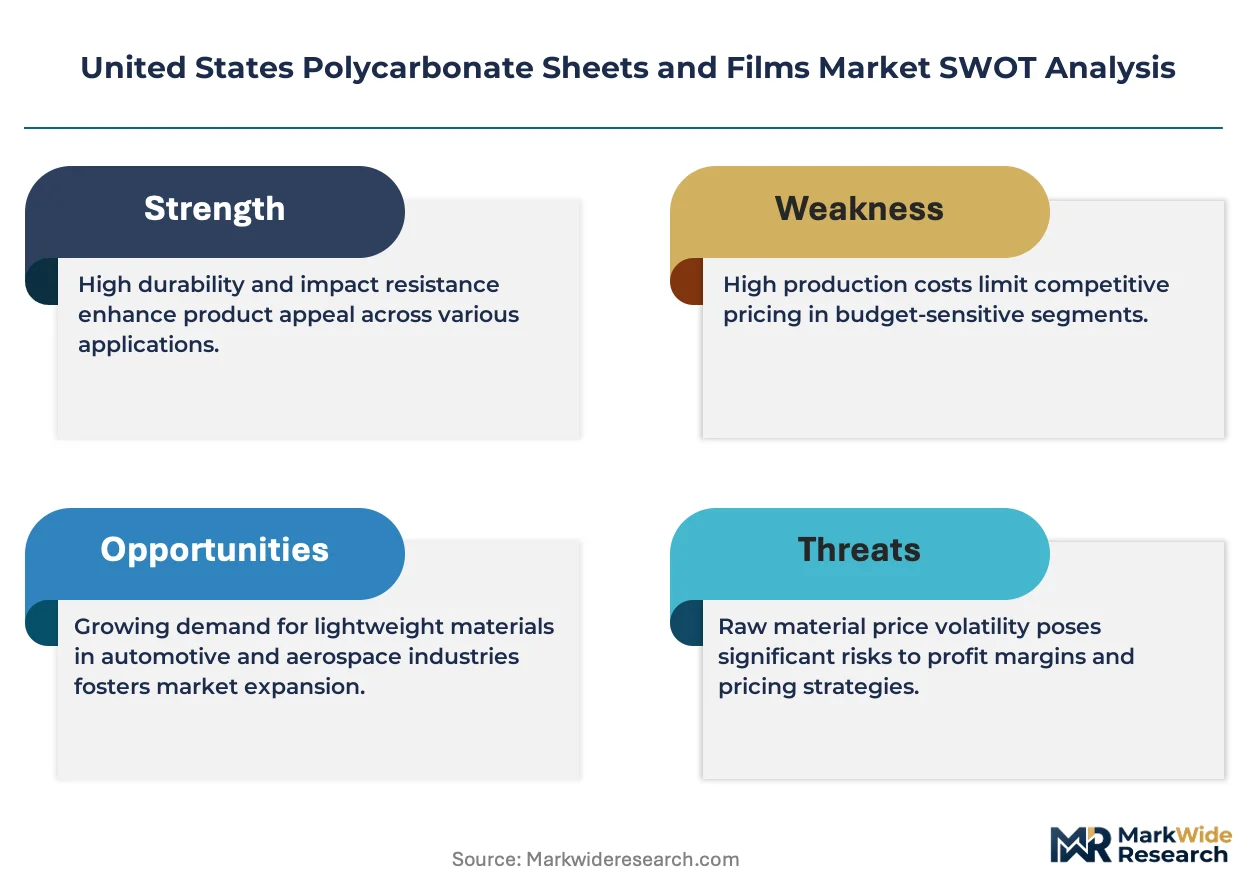
The EPA enforces VOC emission standards for coating and lamination processes affecting polycarbonate fabrication facilities. OSHA mandates workplace exposure limits for bisphenol-A handling in resin production environments. State energy codes in California and New York increasingly reference NFRC-certified thermal performance for glazing materials. Stakeholders must monitor evolving state-level building electrification mandates and potential EPA action on bisphenol-A classification that could reshape material substitution dynamics and capital allocation across the value chain.
Market Dynamics
EPA tightening of thermal performance standards for commercial building envelopes is forcing rapid specification upgrades across architectural glazing supply chains, compressing product development cycles and rewarding domestic extrusion capacity.
Growth Catalysts
- California Title 24 energy codes:Mandatory cool roof and high-performance glazing requirements in commercial retrofits are pulling multiwall sheet volumes into the state's construction pipeline.
- Automotive lightweighting:Electric vehicle manufacturers are specifying polycarbonate glazing for panoramic roof systems to offset battery weight, creating dedicated demand clusters in Texas and Michigan assembly corridors.
- Agricultural controlled environment agriculture:Greenhouse operators in the Southwest are adopting diffused multiwall sheets to manage solar heat gain while maintaining PAR transmission for crop yields.
Market Restraints
- Bisphenol-A feedstock volatility:Resin prices track benzene and propylene cost swings, squeezing extruder margins when upstream petrochemical cycles tighten.
- Gulf Coast supply concentration:Over sixty percent of domestic polycarbonate resin capacity sits within hurricane exposure zones, creating business continuity risk for sheet manufacturers lacking diversified sourcing.
- Acrylic substitution in display applications:Optical-grade PMMA is capturing share in consumer electronics where scratch resistance outweighs impact performance requirements.
Strategic Opportunities
- Texas-Mexico border manufacturing:Nearshoring of automotive assembly is creating demand for cross-border logistics of protective films and glazing components serving maquiladora operations.
- IRA clean energy tax credits:Solar canopy and agrivoltaic installations qualify for investment incentives, opening specification pathways for UV-stable sheet products in utility-scale deployments.
- Digital printing integration:Wide-format UV-curable inkjet systems are enabling mass customization of decorative polycarbonate panels for retail and hospitality interiors.
Industry Challenges
- NFRC certification timelines:Third-party thermal performance validation for new product formulations extends commercialization cycles by eight to fourteen months.
- Extrusion die engineering scarcity:Specialized tooling design for multiwall geometry complexity limits rapid product line expansion among mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Polycarbonate Sheets and Films Market |
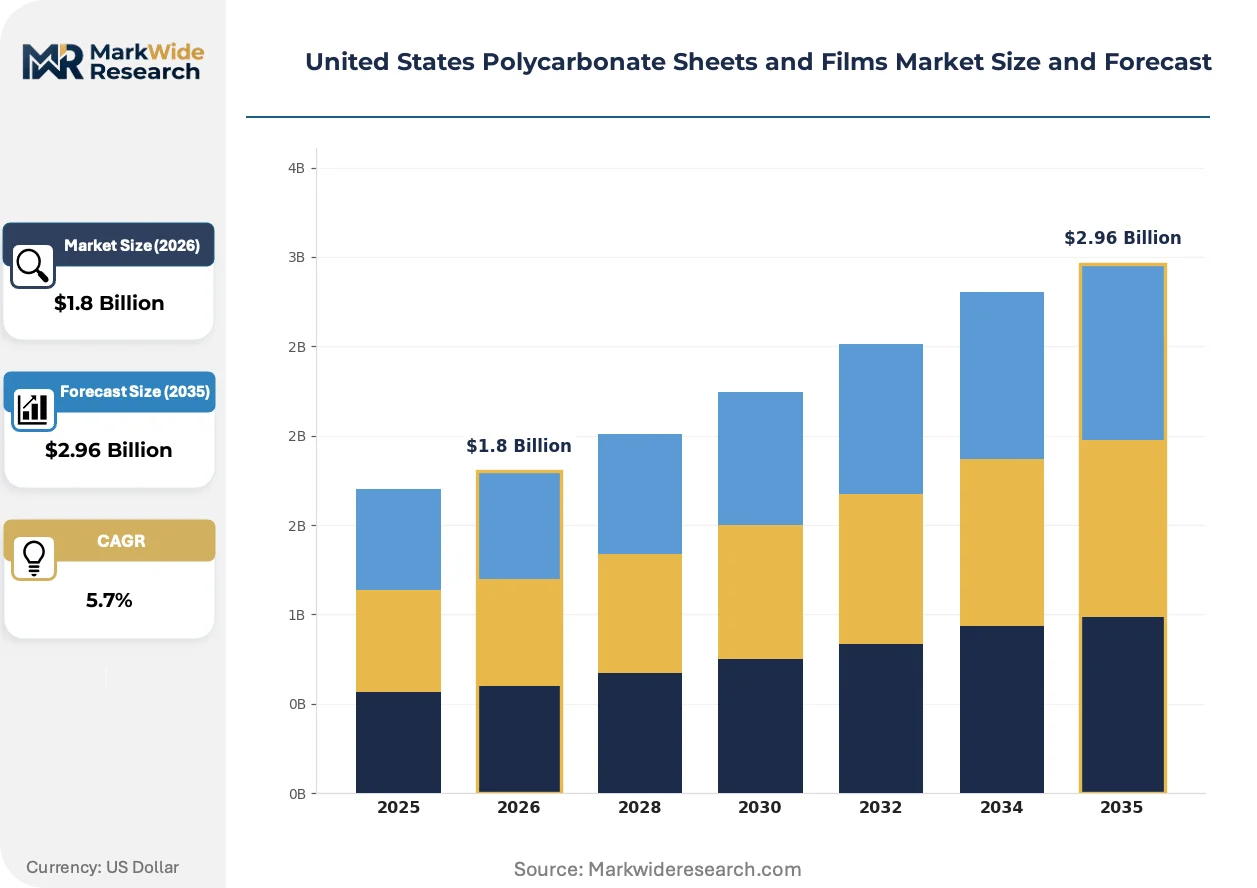
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Sheets, Multiwall Sheets, Solid Sheets, Films End User: Construction, Automotive, Electronics, Medical Thickness: Thin, Medium, Thick, Extra Thick Application: Glazing, Lighting, Signage, Safety Shields |
| Companies Covered | Covestro AG, Trinseo, SABIC, LG Chem, Plazit-Polygal Group, Palram Industries Ltd., AGC Inc., Teijin Limited, Plaskolite, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Polycarbonate Sheets and Films Market Evolving Landscape
Co-extrusion capabilities and surface functionalization are expanding polycarbonate utility beyond commodity glazing into specialized barrier and display applications, compressing the boundary between sheet and film product categories.
Co-extruded UV-capping layers are integrating into standard sheet architectures to extend outdoor service life without secondary coating operations. Agricultural greenhouse builders in California's Central Valley are specifying these products for twenty-year warranty compliance. This integration is compressing the installed cost gap between polycarbonate and glass in commercial retrofit specifications.
The EPA's proposed tighter bisphenol-A hazard classification is accelerating reformulation investments across resin producers and sheet extruders. Facilities in Texas and Ohio are piloting alternative feedstock pathways to preempt supply disruption. Safety and medical packaging segments face the most acute exposure, driving qualification of copolyester substitutes in device tray applications.
Consolidation among regional glazing distributors is compressing channel options for independent sheet processors. Large commercial contractors in Texas and Florida now prefer single-source envelope material procurement, squeezing out specialized polycarbonate-only distributors. This concentration is most visible in the Sun Belt where new construction volume has tilted bargaining power toward national building material distributors.
United States Polycarbonate Sheets and Films Market Segmentation
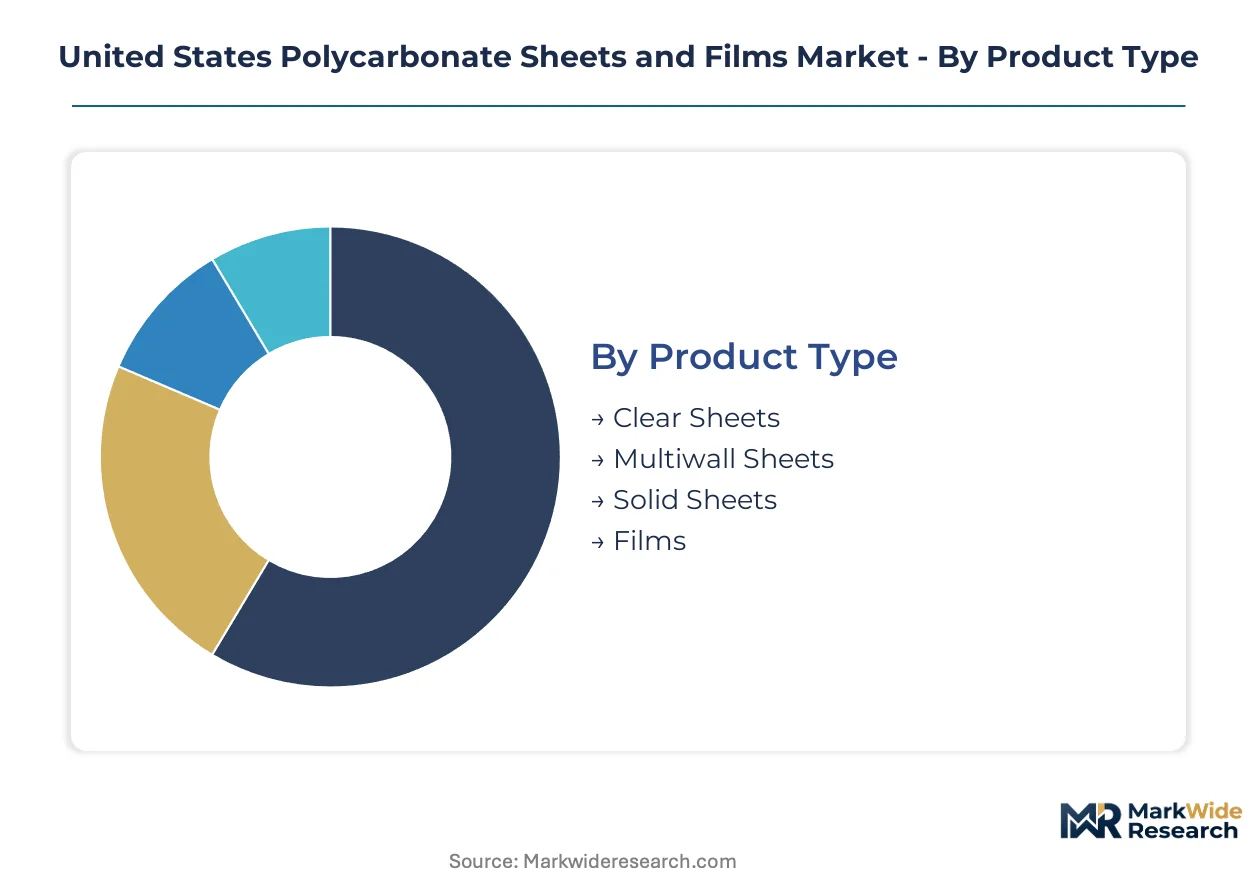
Segmentation in the US polycarbonate market reveals how capital allocation, regulatory compliance, and end-use performance requirements fragment demand across distinct technical specifications. Understanding these divides illuminates where extrusion capacity earns premium returns versus commodity pricing pressure.
Product Type:
Capital intensity varies sharply across extrusion formats, with multiwall geometry demanding specialized die engineering and co-extrusion lines that smaller processors cannot finance.
- Clear Sheets:Monolithic extrusions with optical-grade surface finish serve commercial glazing where NFRC-certified thermal performance commands specification. California Title 24 retrofits concentrate demand in the state's commercial building pipeline.
- Multiwall Sheets:Co-extruded cellular structures with internal rib geometry deliver thermal insulation values critical for agricultural greenhouse and industrial roofing applications. Southwest controlled environment agriculture operators specify diffused variants to manage solar heat gain while maintaining photosynthetically active radiation transmission.
- Solid Sheets:High-density monolithic panels for ballistic and security barriers where impact resistance exceeds optical clarity priorities.
- Films:Precision-calendered thin-gauge products for medical device packaging and automotive instrument cluster overlays requiring tight thickness tolerance control.
Clear sheets absorb the bulk of installed extrusion capacity; multiwall sheets are expanding most quickly.
End User:
Margin structure diverges by customer sophistication, with medical and electronics buyers paying qualification premiums that construction procurement rarely matches.
- Construction:Architectural glazing and roofing systems dominate volume, driven by EPA thermal performance mandates and state energy code tightening. Texas and California commercial retrofits pull disproportionate sheet volumes.
- Automotive:Electric vehicle manufacturers specify polycarbonate panoramic roof systems for lightweighting against battery mass penalties. Michigan and Texas assembly corridors anchor demand clusters.
- Electronics:Optical-grade formulations for display substrates and LED light guides where precision thickness and clarity specifications filter out commodity suppliers.
- Medical:Sterile barrier packaging and device trays face acute reformulation pressure from EPA bisphenol-A hazard classification proposals, accelerating copolyester substitution trials.
Construction commands the largest share of extruder output; automotive applications are climbing the fastest.
Thickness:
Processing economics favor medium and thick gauges where line speed and yield rates offset resin cost volatility.
- Thin:Films and light-gauge sheets for flexible electronics and packaging where calendering precision replaces extrusion.
- Medium:Standard architectural glazing thicknesses balancing structural performance with handling efficiency. Most Texas and California commercial projects specify this range.
- Thick:Industrial safety barriers and machine guarding where impact resistance requirements dominate specification.
- Extra Thick:Specialized ballistic and blast-resistant applications with limited but high-margin demand from federal and institutional security projects.
Medium thickness captures the majority of production volume; extra thick commands the steepest per-pound premiums.
Application:
Specification authority varies by application, with lighting and safety segments offering more direct processor-to-OEM relationships than glazing's distributor-mediated channels.
- Glazing:Architectural windows, skylights, and curtain walls subject to NFRC certification and state energy code compliance. California Title 24 and New York building electrification mandates reshape product qualification requirements.
- Lighting:LED diffusers and luminaire housings where optical efficiency and heat resistance specifications filter supplier pools.
- Signage:Wide-format printable substrates for retail and hospitality interiors where UV-curable inkjet compatibility enables mass customization.
- Safety Shields:Machine guards, face shields, and protective barriers where impact resistance testing to ANSI standards governs procurement.
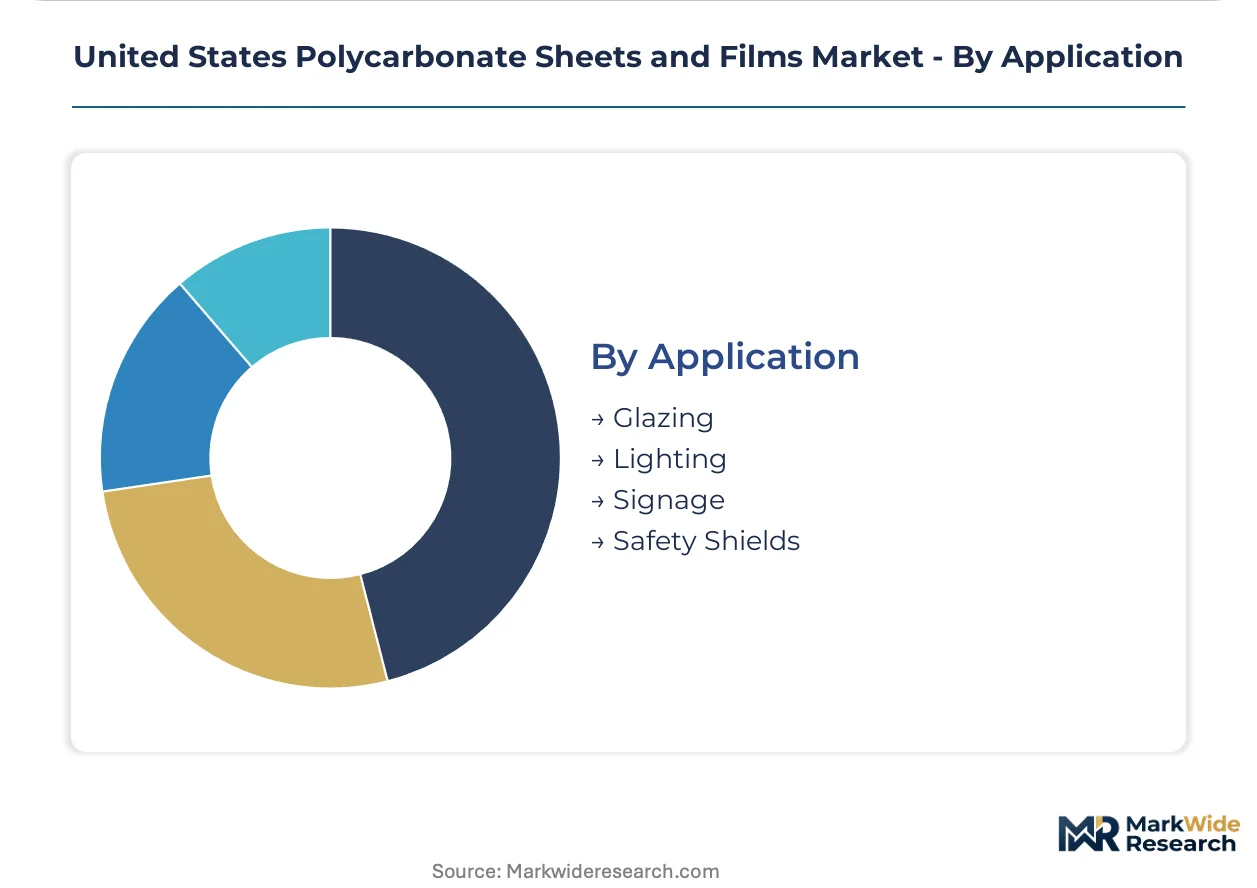
Glazing represents the dominant application by volume; lighting applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bisphenol-A resin production clusters along the Gulf Coast anchor polycarbonate sheet and film manufacturing across the United States. Texas and Louisiana petrochemical corridors feed extrusion capacity concentrated in hurricane-exposed zones. State-level energy codes and federal thermal performance mandates reshape regional demand patterns.
Texas
Commercial construction in Dallas-Fort Worth and Houston drives multiwall sheet specifications for cool roof compliance. The Texas Commission on Environmental Quality enforces air quality standards for coating and lamination facilities. The Baytown petrochemical complex sustains domestic resin supply for regional extruders serving automotive glazing clusters.
California
Title 24 energy codes mandate high-performance glazing in commercial retrofits across Los Angeles and San Francisco markets. The California Energy Commission certifies NFRC thermal performance ratings for building envelope materials. Central Valley greenhouse operators specify diffused multiwall sheets for controlled environment agriculture expansion.
Michigan
Electric vehicle assembly corridors in Detroit and Grand Rapids pull polycarbonate panoramic roof specifications for lightweighting. The Michigan Department of Environment, Great Lakes, and Energy oversees VOC emission controls for fabrication facilities. Tier 1 automotive suppliers cluster in Southeast Michigan for just-in-time glazing component delivery.
Florida
Hurricane-resistant glazing demand concentrates in Miami-Dade and Tampa commercial construction. The Florida Building Commission enforces strict impact resistance standards for architectural materials. Regional distributors consolidate procurement power, squeezing specialized polycarbonate-only suppliers from specification channels.
Ohio
Medical device packaging reformulation trials accelerate in Cleveland and Cincinnati corridors. The Ohio EPA monitors bisphenol-A handling protocols in resin processing environments. Precision film calendering operations serve Midwestern electronics and healthcare manufacturing clusters.
United States Polycarbonate Sheets and Films Market Competitive Landscape
Capacity expansion dominates the current landscape as resin producers and extruders respond to EPA thermal performance mandates and state energy code tightening. The vendor base separates into three tiers: integrated resin-to-sheet producers, specialized optical-grade formulators, and regional extrusion processors. Strategic archetypes include Gulf Coast resin anchors, automotive glazing specialists, and medical packaging reformulators. M&A activity concentrates among regional distributors, while backward integration into resin supply chains represents the second dominant competitive move.
Among integrated resin producers, Covestro AG exemplifies the Gulf Coast production anchor archetype through its Baytown complex operations. Trinseo occupies a position within the specialized formulation tier, serving electronics and medical end-use requirements. SABIC represents the high-performance resin technology archetype through its Lexan brand positioning in safety and glazing segments. These three companies illustrate how feedstock access, formulation specialization, and application-specific branding stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Covestro AG |
| Trinseo |
| SABIC |
| LG Chem |
| Plazit-Polygal Group |
| Palram Industries Ltd. |
| AGC Inc. |
| Teijin Limited |
| Plaskolite |
| Others |
Value Network & Pricing Analysis
California Title 24 retrofit mandates for high-performance glazing are compressing procurement timelines and forcing extruders to absorb certification costs or lose specification, reshaping how sheet processors negotiate resin contracts and warranty terms.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from commodity extruders, with twenty-year service-life guarantees now standard for multiwall agricultural products while unbundled pricing dominates spot construction procurement. Three-tier pricing structure across premium, standard, and economy levels reflects NFRC certification status, co-extrusion capability, and geographic delivery radius. Cost compression in the commodity clear-sheet tier is intensifying as Gulf Coast resin volatility squeezes processor margins. National building material distributors exhibit lowest price sensitivity due to consolidated procurement power, while independent regional glazing contractors face acute margin pressure.
Supply Chain Analysis
Domestic-content preferences in federally funded infrastructure and Buy America-compliant solar canopy projects are redirecting procurement toward Texas and Ohio extrusion capacity over Asian import alternatives. Resin supply concentrates in Texas and Louisiana petrochemical corridors, with bisphenol-A feedstock drawing from benzene and propylene streams anchored in Gulf Coast crackers. Single-source vulnerability pervades the value chain as hurricane exposure threatens sixty percent of domestic resin capacity. Distribution runs through consolidated national building material distributors and specialized glazing contractors serving commercial envelope projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EPA thermal performance mandates and OSHA bisphenol-A handling protocols erect capital barriers that favor incumbent extruders with certified testing infrastructure and environmental compliance systems.
For Market Incumbents: To counter acrylic substitution in consumer electronics display applications, Covestro and Trinseo should deepen captive supply of optical-grade resin formulations while expanding co-extrusion capacity in Texas to capture Title 24-driven retrofit volumes. Backward integration into alternative feedstock pilot programs in Ohio and Texas mitigates regulatory reclassification risk.
For New Entrants and Emerging Players: Digital printing-compatible UV-curable sheet substrates represent the most penetrable white-space opportunity, with retail and hospitality interior customization demand outpacing incumbent capacity. Agrivoltaic installation specifications in the Southwest offer a second entry vector. A direct-to-fabricator go-to-market model bypasses consolidated distributor channels.
For Investors and Strategic Acquirers: The window for entry favors specialized optical-grade formulators with medical device qualification pathways and automotive glazing certification. Long-term viability hinges on reformulation capabilities that preempt EPA bisphenol-A hazard reclassification. Watch NFRC certification backlog durations as the inflection signal for extrusion capacity tightness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Feedstock | Ohio and Texas pilot facilities preempt EPA bisphenol-A supply disruption for medical packaging segments. |
| Co-Extrusion Capacity Expansion | Multiwall geometry capability captures California Title 24 agricultural and commercial retrofit specifications. |
| NFRC Certification Investment | Third-party thermal performance validation unlocks specification in Texas and California energy code compliance projects. |
| Digital Printing Surface Functionalization | UV-curable inkjet compatibility opens mass customization revenue pools in retail and hospitality interiors. |
| Long-Term Supply Agreement with Resin Producers | Diversified sourcing contracts mitigate Gulf Coast hurricane concentration risk for sheet extruders. |
Research Methodology
Trade association filings, customs and resin import records, and SEC 10-K disclosures from petrochemical and extrusion companies formed the secondary backbone, cross-referenced with primary interviews involving plant managers at Gulf Coast resin facilities, procurement leads at Texas and California commercial glazing contractors, distribution channel partners, and technical R&D directors at optical-grade formulators. Bottom-up capacity utilization estimates and top-down construction spending allocation models were triangulated to validate volume assumptions.
Historical trendline analysis of extrusion capacity additions, resin price volatility indices, and NFRC certification issuance rates informed the projection framework across the analysis window. Segmentation modeling incorporated product type, end-use industry, thickness gauge, and regional energy code compliance tier. CAGRs were derived from elasticity-adjusted demand curves and substitution rate assumptions for acrylic and glass alternatives.
Several conditions sit outside the modeled scope, including potential EPA reclassification of bisphenol-A hazard status, hurricane-induced supply disruptions exceeding historical frequency, and federal infrastructure funding allocation shifts. Forecasts reflect documented assumptions about resin cost pass-through rates and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Poly Coated Kraft Paper Market
Poly film
PVC Cling Film Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Printed Plastic Films Market
Poly film
Polyester Film Market
Poly film
Cast Stretch Packaging Films Market
Poly film
PE Foam Films Market
Poly film
India BOPP Films Market
Poly film
Soft Touch Film Market
Poly film
Nylon Films Market
Poly film
Polysaccharide Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Blown Film Extruder Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
Recyclable Lidding Films Market