
 Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market | 2026-2036
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market Intelligence
Buyer consolidation within the automotive industry is expanding the need for TPU film suppliers with global production footprints and consistent quality control. Covestro AG leverages its extensive polymer science portfolio to secure large-scale contracts from major original equipment manufacturers. BASF SE competes on material innovation, particularly in developing advanced bio-based TPU formulations that meet sustainability targets. The Lubrizol Corporation specializes in high-performance films for niche applications, including surface protection and medical devices.
Synthetic and bio thermoplastic polyurethane (TPU) films are elastomeric polymers prized for their high elasticity, abrasion resistance, and transparency. Produced through methods like casting and extrusion, these films serve as durable, flexible protective layers in demanding environments. While extruded films command a significant share due to manufacturing efficiency, the bio-based variants are gaining momentum. The automotive sector remains the largest consumer, utilizing TPU films for paint protection, interior surfaces, and anti-chipping applications.
Regulatory frameworks significantly influence material selection and product development. The European Union's REACH and RoHS directives restrict certain hazardous substances, encouraging the adoption of safer, bio-based TPU alternatives. In the United States, EPA regulations on volatile organic compounds (VOCs) favor water-based over solvent-based formulations. The ability to navigate these complex standards and scale production of compliant materials will be critical for suppliers.
Market Dynamics
The central force shaping the market is the dual demand for enhanced material performance in the automotive sector and verifiable sustainability credentials driven by regulations like the EU Green Deal. This dynamic creates a competitive field where both synthetic and bio-based innovation are critical.
Growth Catalysts
- Automotive Sector Demand:The adoption of TPU films for paint protection (PPF) and interior surface safeguarding in vehicles provides a significant and continuous demand stream, particularly for high-clarity, durable grades.
- Sustainability Mandates:European Union regulations, including REACH and the Green Deal, incentivize the development and use of bio-based TPU films by restricting certain chemicals and promoting circular economy principles.
- Advancements in Bio-polymers:Continuous innovation in bio-based feedstocks is improving the performance characteristics of bio-TPU films, making them viable alternatives to synthetic versions in more demanding applications.
Market Restraints
- Input Cost Volatility:Synthetic TPU film pricing is tied to the volatile costs of petrochemical precursors like MDI and polyols, while bio-TPU relies on agricultural feedstock prices which can fluctuate with crop yields.
- Performance Gaps in Bio-variants:Certain first-generation bio-based TPU films exhibit lower thermal stability or UV resistance compared to their established synthetic counterparts, limiting their use in harsh exterior applications.
- Substitution from Other Polymers:In less demanding applications, lower-cost polymers such as polyvinyl chloride (PVC) and thermoplastic olefins (TPO) present a persistent substitution threat to TPU films.
Strategic Opportunities
- Medical Device Applications:There is a significant opportunity for specialized TPU films in the medical sector for applications like wound care dressings, catheter tubing, and sterile device packaging, which require biocompatibility.
- Expansion in Electronics:The growing market for flexible displays and wearable technology creates new use cases for thin, transparent, and abrasion-resistant TPU films as protective layers.
- Water-Based Formulations:Stricter EPA regulations on volatile organic compounds (VOCs) in the United States create an opportunity for suppliers of water-based TPU dispersions used in film coatings and adhesives.
Industry Challenges
- Production Scalability:Manufacturers face challenges in scaling up the production of new bio-based TPU formulations while maintaining the consistent quality and performance required by global automotive OEMs.
- Complex Certification Pathways:Securing material approvals for new TPU film formulations in highly regulated sectors like automotive and medical devices involves long, expensive validation and certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market |
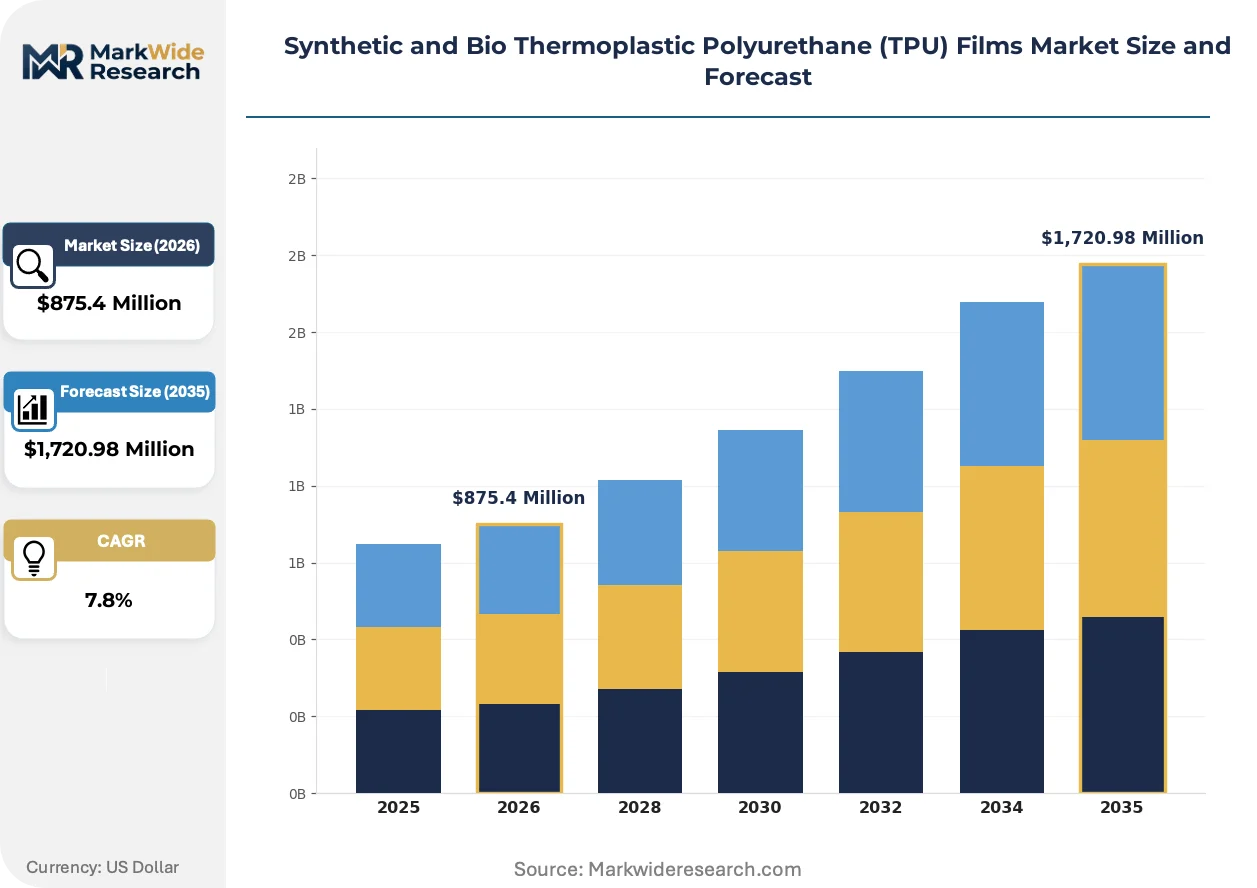
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,720.98 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Films, Blow Films, Extruded Films, Coated Films End Use Industry: Automotive, Packaging, Footwear, Medical Formulation Type: Water-Based, Solvent-Based, Oil-Based, Hot-Melt Thickness: Thin Films, Medium Films, Thick Films, Ultra-Thin Films |
| Companies Covered | Wanhua Chemical Group, Mitsui Chemicals, BASF SE, Avery Dennison Corporation, Evonik Industries AG, Covestro AG, Lubrizol Corporation, Dow Inc., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market Strategic Shifts & Innovations
Material science advancements are enabling TPU films with specialized functionalities, while regulatory pressures are accelerating the shift toward sustainable formulations. These forces are redefining performance benchmarks and procurement criteria across key end-use industries.
Self-healing TPU films, which utilize reversible polymer networks to repair minor scratches, represent a significant product evolution. The premium automotive segment is the primary adopter for paint protection films that maintain a flawless finish. This advanced material technology is expanding into high-end consumer electronics for screen protectors and device casings, offering enhanced durability and product longevity beyond its original automotive niche.
The European Union's REACH directive profoundly impacts material formulation across the supply chain. This regulation restricts the use of certain hazardous substances, compelling manufacturers to reformulate their TPU films to ensure compliance. Suppliers aiming for the European automotive and consumer goods markets are therefore prioritizing the development and commercialization of safer, often bio-based, alternative materials to secure market access.
A notable behavioral shift is the increasing demand from OEMs for comprehensive sustainability documentation during material selection. This trend moves procurement decisions beyond traditional cost-per-kilogram metrics, disrupting sales models that rely solely on price. The requirement for life-cycle assessment (LCA) data is most pronounced in Western Europe, where corporate sustainability reporting mandates like the CSRD are becoming standard.
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market Segmentation
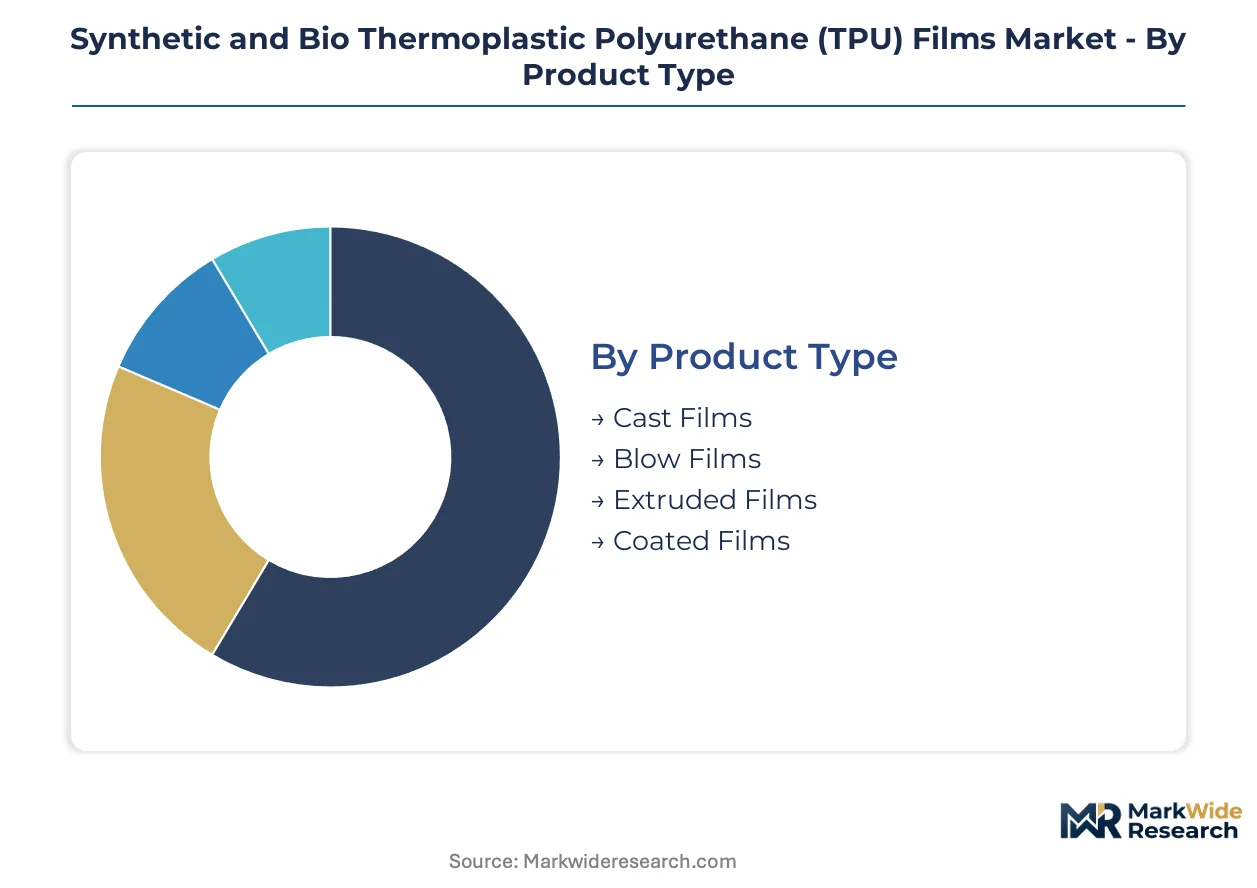
The Synthetic and Bio Thermoplastic Polyurethane (TPU) Films market is differentiated by product type, end-use applications, formulation, and film thickness. Understanding these segments helps suppliers align their material properties with specific industry requirements, ensuring compliance and performance in diverse applications.
Product Type:
Material certification requirements often dictate the selection of TPU film product types for regulated end-uses like medical devices or automotive interiors. Each production method imparts distinct physical properties and performance characteristics to the final film.
- Extruded Films:These films are produced through a continuous manufacturing process, offering high volume and cost efficiency for general industrial and automotive applications. Their consistent thickness and broad property range make them suitable for paint protection films in the European automotive sector.
- Cast Films:Cast films typically exhibit superior optical clarity, surface smoothness, and mechanical properties compared to extruded counterparts, making them ideal for high-performance applications. The production method allows for precise control over film thickness and surface finish, critical for medical device packaging and high-end consumer electronics.
- Blow Films:Blow films are often used for flexible packaging and bags, valuing elasticity and puncture resistance over optical clarity. The process allows for the creation of tubular films, which are then slit or converted.
- Coated Films:These films feature an additional functional layer applied to a base TPU film, enhancing properties like scratch resistance, UV stability, or anti-fog capabilities. Coated TPU films are gaining traction in specialized automotive interior applications.
Leading the category by volume: Extruded Films. Growing fastest: Cast Films.
End Use Industry:
The volume contribution of each end-use industry influences manufacturing scale and product development priorities for TPU film suppliers. Diverse industry demands drive innovation in specific material properties.
- Automotive:This sector utilizes TPU films extensively for paint protection, anti-chipping layers, and interior surface protection due to their durability, flexibility, and UV resistance. German automotive OEMs are particularly stringent regarding film performance and longevity.
- Medical:Specialized TPU films find applications in wound care, catheter tubing, and sterile packaging, requiring biocompatibility and compliance with regulatory bodies like the FDA in the United States and the EMA in Europe. The Lubrizol Corporation focuses on high-performance films for these niche medical device applications.
- Packaging:TPU films offer excellent puncture resistance and flexibility for protective packaging, particularly for sensitive electronics and food products. Their elastomeric properties help secure contents during transit.
- Footwear:TPU films are integrated into athletic footwear for structural support, abrasion resistance, and aesthetic elements. The material provides both durability and design flexibility for shoe components.
The largest revenue contributor is Automotive, while Medical exhibits the most dynamic expansion.
Formulation Type:
Cost tiers often differentiate formulation types, with performance and regulatory compliance influencing material selection. Each formulation offers distinct processing advantages and environmental profiles.
- Water-Based:These formulations are favored due to stricter environmental regulations, particularly EPA regulations on volatile organic compounds (VOCs) in the United States. Water-based TPU dispersions are used in film coatings and adhesives, offering a safer alternative to solvent-based systems.
- Solvent-Based:Traditional solvent-based formulations offer excellent adhesion and film-forming properties, often delivering superior performance in demanding industrial applications. However, their use faces increasing scrutiny under directives like the European Union's REACH.
- Hot-Melt:Hot-melt TPU formulations are solid at room temperature and applied by heating, providing strong bonds without the need for solvents. They are often used in textile lamination and automotive interior bonding for efficient assembly.
- Oil-Based:These formulations are less common for films but can offer specific properties like enhanced flexibility or chemical resistance for specialized industrial sealing applications. Oil-based systems are often evaluated for specific end-use environments.
Demand for Water-Based is driven by regulatory compliance, with Solvent-Based maintaining significant market presence.
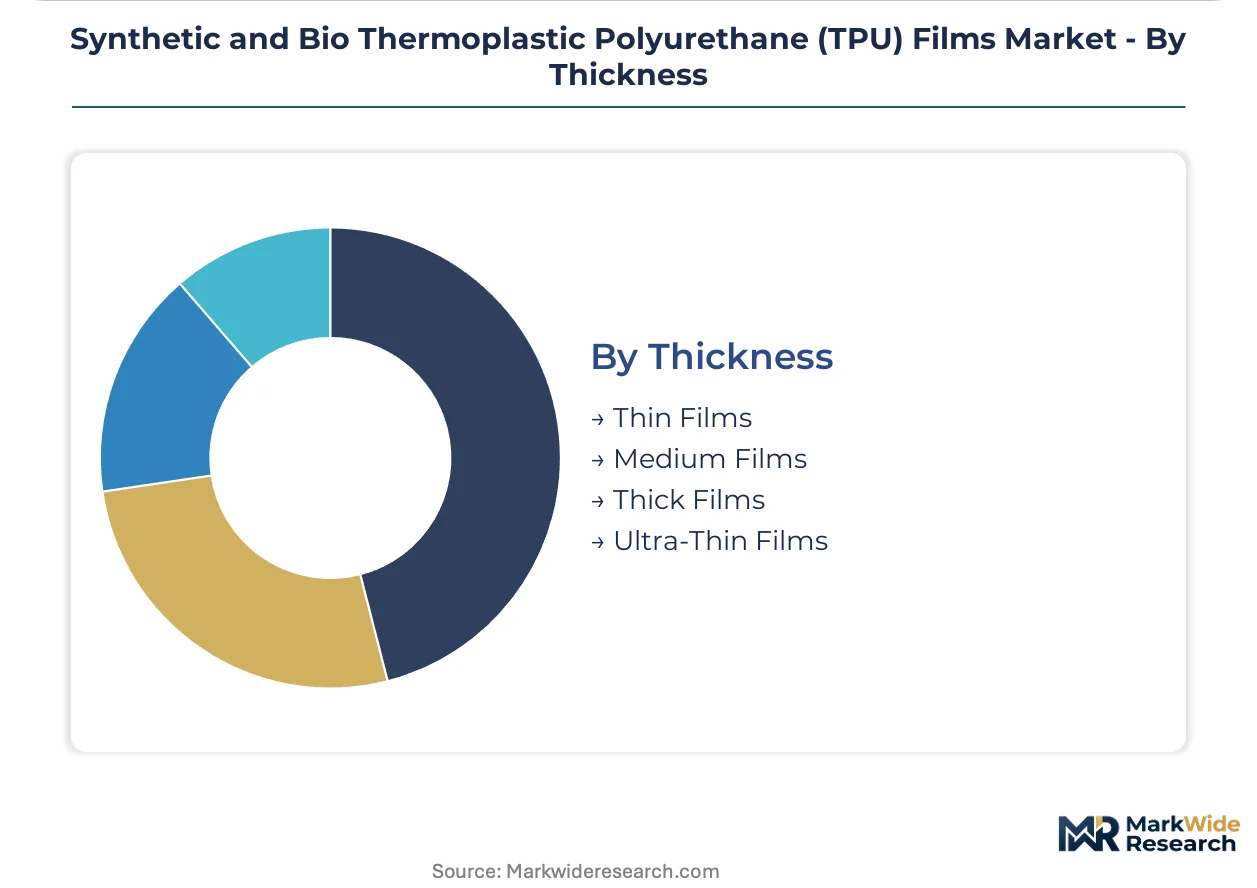
Thickness:
Performance characteristics directly correlate with film thickness, influencing material selection for various protective and functional roles. Each thickness range serves distinct application requirements.
- Ultra-Thin Films:These films, often measured in microns, are critical for flexible displays, wearable technology, and advanced electronics where transparency and minimal bulk are paramount. Their high clarity and abrasion resistance protect sensitive components.
- Thick Films:Thick films provide enhanced durability, impact resistance, and sound dampening properties, making them suitable for heavy-duty industrial protection and automotive anti-chipping applications. These films offer robust physical barriers.
- Thin Films:Thin films offer a balance of flexibility, protection, and optical clarity for general-purpose surface protection and lamination. They are widely used across various consumer goods and light industrial applications.
- Medium Films:These films bridge the gap between thin and thick, providing moderate protection and flexibility for applications like textile lamination and certain packaging solutions. Medium films balance cost and performance.
Thin Films find broad utility, while Ultra-Thin Films address specialized, high-precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for synthetic and bio thermoplastic polyurethane (TPU) films is particularly evident in regions with robust automotive manufacturing and stringent sustainability regulations. Key industrial clusters globally drive both material innovation and application expansion. This dynamic landscape necessitates a nuanced understanding of regional market drivers and regulatory frameworks.
Germany
Germany exhibits strong demand for high-performance TPU films in its advanced automotive sector and specialized industrial applications. The European Union's REACH directive heavily influences material selection, promoting safer bio-based alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia actively develop and integrate advanced TPU film solutions for vehicle interiors and paint protection.
United States
The United States market sees significant demand for TPU films in medical devices and specialized automotive applications. EPA regulations on volatile organic compounds (VOCs) encourage the adoption of water-based formulations. Research and development hubs in California and the Boston biotech corridor drive innovation for ultra-thin films and biocompatible materials.
China
China's market for TPU films is fueled by its expansive automotive production and rapidly growing electronics manufacturing base. National GB standards and dual carbon goals are increasingly influencing material choices towards sustainable options. Major manufacturing centers in the Yangtze River Delta and Pearl River Delta lead in large-scale TPU film production for domestic and export markets.
Japan
Japanese industries require high-clarity and durable TPU films for its precision automotive components and advanced flexible electronics. The Ministry of Economy, Trade and Industry (METI) supports research into high-performance polymer materials. Automotive and electronics manufacturing hubs in Aichi Prefecture and the Kansai region focus on developing specialized TPU film grades with enhanced functionalities.
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue niche applications and advanced bio-based formulations. The market structure exhibits a tiered consolidation, with major chemical companies leveraging extensive R&D capabilities. Strategic archetypes include large-scale polymer manufacturers, specialized film converters, and innovative bio-material developers. Competitive moves frequently involve portfolio diversification into sustainable solutions and strategic partnerships to secure raw material supply chains.
Within the established polymer science tier, Covestro AG and BASF SE exemplify leaders with broad portfolios. Covestro AG, a German-based company, leverages its extensive polymer science to secure large-scale contracts from major original equipment manufacturers. BASF SE, also a German chemical giant, competes on material innovation, particularly in advanced bio-based TPU formulations. The Lubrizol Corporation, an American specialty chemicals company, occupies a position as a specialist in high-performance films for niche applications, including surface protection and medical devices.
| Leading Market Players |
|---|
| Wanhua Chemical Group |
| Mitsui Chemicals |
| BASF SE |
| Avery Dennison Corporation |
| Evonik Industries AG |
| Covestro AG |
| Lubrizol Corporation |
| Dow Inc. |
| Huntsman Corporation |
| Others |
Cost & Logistics Intelligence
Skilled polymer science workforces in Germany influence pricing tiers, particularly for advanced TPU films, due to specialized expertise and higher labor costs. This differential impacts overall manufacturing expenses and product pricing across global markets.
Pricing Analysis
Volume-driven segments for general industrial use operate on narrower margins, while specialized cast films for medical devices command premium pricing. Contract-based long-term offtake agreements define much of the automotive sector's pricing for certified grades, driven by certification level and customization. Pricing pressure stems from volatile petrochemical and agricultural feedstock costs, particularly impacting standard grades. Automotive OEMs exhibit lower price sensitivity for high-performance films, contrasting with more price-sensitive general industrial buyers.
Supply Chain Analysis
TPU film supply relies heavily on petrochemical precursors like MDI and polyols, sourced primarily from chemical giants in Germany and China. Bio-TPU production draws from agricultural feedstocks, whose prices fluctuate with crop yields. Single-source vulnerability for specialized additives presents a structural supply chain risk. Distribution runs through direct sales channels for major automotive OEMs and specialized chemical distributors for smaller industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TPU films market presents a consolidation play, driven by the escalating regulatory burden from directives like EU REACH and the need for global production footprints. This pressure forces smaller, less diversified players out, favoring large-scale polymer manufacturers.
For Market Incumbents: Deploy targeted capacity expansion in bio-based TPU films to address evolving sustainability mandates and mitigate input cost volatility. Secure long-term offtake agreements with automotive OEMs by investing in advanced material certification and global quality control. Diversify into high-margin medical device applications, leveraging existing polymer science expertise. This defends against emerging bio-material developers and substitution from lower-cost polymers.
For New Entrants and Emerging Players: Online B2B platforms offer a viable route for new entrants to target specialized niche applications in medical devices and flexible electronics. Focus on developing ultra-thin films or water-based formulations that meet specific regulatory requirements, such as EPA VOC standards. Partner with specialized film converters to access smaller, high-value customer segments. This approach bypasses established OEM supply chains and addresses unmet needs.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists in bio-based TPU given accelerating sustainability mandates and demand for high-performance films. Focus on companies with proprietary formulations or unique processing technologies in water-based systems. Long-term viability rests on the transition to a circular economy and continued demand for advanced protective layers. The acceleration of bio-TPU adoption in automotive paint protection films signals a critical inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint, meeting EU Green Deal mandates for European market access. |
| Long-term Supply Agreement | Secures consistent material flow, stabilizing input costs for automotive OEMs. |
| Joint Venture | Accelerates development of novel bio-based formulations, sharing R&D costs and market access. |
| Capacity Expansion | Addresses growing demand for TPU films in Asia, particularly for electronics and automotive. |
| Technology Licensing | Broadens market reach for specialized film properties, particularly in medical device applications. |
Research Approach
Chemical industry association reports, government publications from EPA and ECHA, and company investor presentations formed the secondary backbone for this analysis. Insights were cross-referenced with primary interviews involving R&D directors, automotive OEM procurement leads, medical device engineers, and specialized film converters. This approach ensured robust bottom-up and top-down triangulation of market data.
Historical trendline analysis, coupled with future demand projections, informed the forecast across the analysis window. The model segmented the market by product type, end-use industry, formulation type, and film thickness. Compound annual growth rates were derived from both historical performance and anticipated shifts in material preference. Automotive production volumes and bio-material innovation rates served as key forecast inputs.
The model holds under current regulatory frameworks and stable petrochemical supply; deviation in sustainability policy or disruptive material science breakthroughs would shift projections. Forecasts reflect assumptions regarding raw material availability and technological adoption rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Bio-PET Film Market
Poly film
Poland Plastic Packaging Films Market
Poly film
MDO-PE Films Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Multi-Layer Blown Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Co Extruded Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
PP Film Blowing Machine Market
Poly film
Polybag Mailers Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Spain Plastic Packaging Films Market