
 Brazil Plastic Packaging Films Market | 2026-2036
Brazil Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Plastic Packaging Films Market Insights
Subscription-based film procurement and predictive maintenance contracts are restructuring how Brazilian converters monetize their customer relationships. Amcor PLC leverages its technical service agreements to lock in multi-year supply commitments from multinational food processors. Berry Global Inc. sustains margin advantages through captive resin compounding operations near São Paulo petrochemical hubs. Videplast Packaging Industry Ltda. anchors its competitive position with specialized shrink film formulations tailored for Brazilian tropical distribution conditions.
Brazil plastic packaging films are flexible polymer substrates, typically 12 to 150 microns thick, manufactured through blown or cast extrusion processes with optional biaxial orientation and metallization for oxygen and moisture barrier performance. These structures protect perishable goods through controlled permeability, mechanical resilience, and heat-seal integrity across temperature-variable supply chains. Stretch film commands the largest volume position due to palletization demand from Brazil's expanding agribusiness and beverage distribution networks, while barrier film generates the highest value per kilogram as meat exporters adopt ethylene vinyl alcohol copolymer and polyamide multilayer specifications. Coextruded film structures are displacing monolayer alternatives in premium applications where ANVISA compliance and extended shelf life justify material complexity.
ANVISA governs food contact compliance through Resolution RDC 326 and subsequent updates, while INMETRO administers conformity assessment for packaging labeled with recycled content claims under the National Solid Waste Policy. The Brazilian Association of Technical Standards (ABNT) publishes voluntary specifications for biodegradable films that influence procurement criteria among retail chains with ESG commitments. Stakeholders must monitor how upcoming federal packaging waste regulations and state-level extended producer responsibility frameworks in São Paulo and Minas Gerais reshape collection infrastructure and recycled resin availability for circular film production.
Market Dynamics
ANVISA's migration testing mandates for multilayer structures are compressing formulation timelines and forcing converters to revalidate entire product portfolios ahead of enforcement deadlines.
Growth Catalysts
- Protein export specifications:Meat and dairy processors in Minas Gerais and Rio Grande do Sul are specifying ethylene vinyl alcohol copolymer barriers to meet shelf-life requirements for Middle Eastern and Asian destination markets.
- Agribusiness palletization:Stretch film consumption is accelerating through expanded soybean and corn logistics networks serving the Port of Santos corridor.
- Extended producer responsibility frameworks:São Paulo and Minas Gerais state-level EPR regulations are creating certified recycled resin demand that rewards early-mover converters with preferential procurement status.
Market Restraints
- Polyethylene resin concentration:Brazilian converters remain dependent on Braskem's domestic ethylene supply, exposing margin structures to naphtha-linked volatility and planned maintenance shutdowns.
- Metallization equipment scarcity:High-barrier film production is constrained by limited domestic vacuum deposition capacity, forcing reliance on imported metallized substrates or capital-intensive foreign equipment procurement.
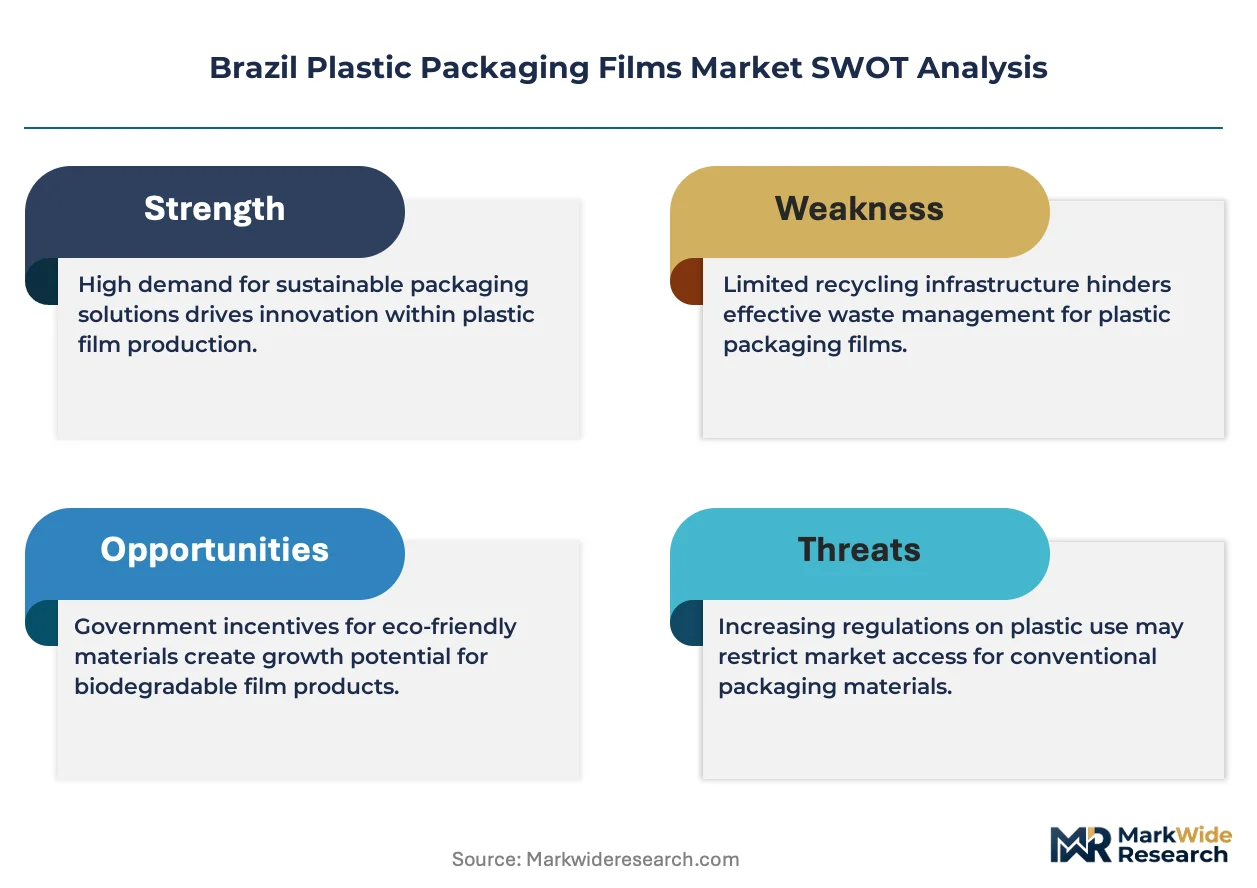
- Multilayer recycling incompatibility:Current mechanical recycling infrastructure cannot process polyamide-ethylene vinyl alcohol-polyethylene structures, creating landfill liability under pending federal packaging waste regulations.
Strategic Opportunities
- Northeast Brazil food retail expansion:Supermarket chains in Recife and Salvador are adopting modified atmosphere packaging for fresh produce, creating specification upgrade demand previously concentrated in São Paulo.
- Chemical recycling feedstock partnerships:Pyrolysis-based polyolefin recovery is enabling food-contact compliant recycled content claims that satisfy INMETRO conformity assessment for premium private-label positioning.
- Biodegradable film standardization:ABNT voluntary specifications for oxo-biodegradable and compostable films are influencing ESG-linked procurement criteria among Carrefour and GPA retail banners.
Industry Challenges
- Migration testing laboratory capacity:ANVISA's updated Resolution RDC 326 requirements have overwhelmed certified testing facilities, extending validation timelines from weeks to months and delaying product launches.
- Coextrusion die retrofit complexity:Converters upgrading from monolayer to seven-layer barrier structures face extended commissioning periods and scrap rate spikes during barrier layer distribution optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Plastic Packaging Films Market |
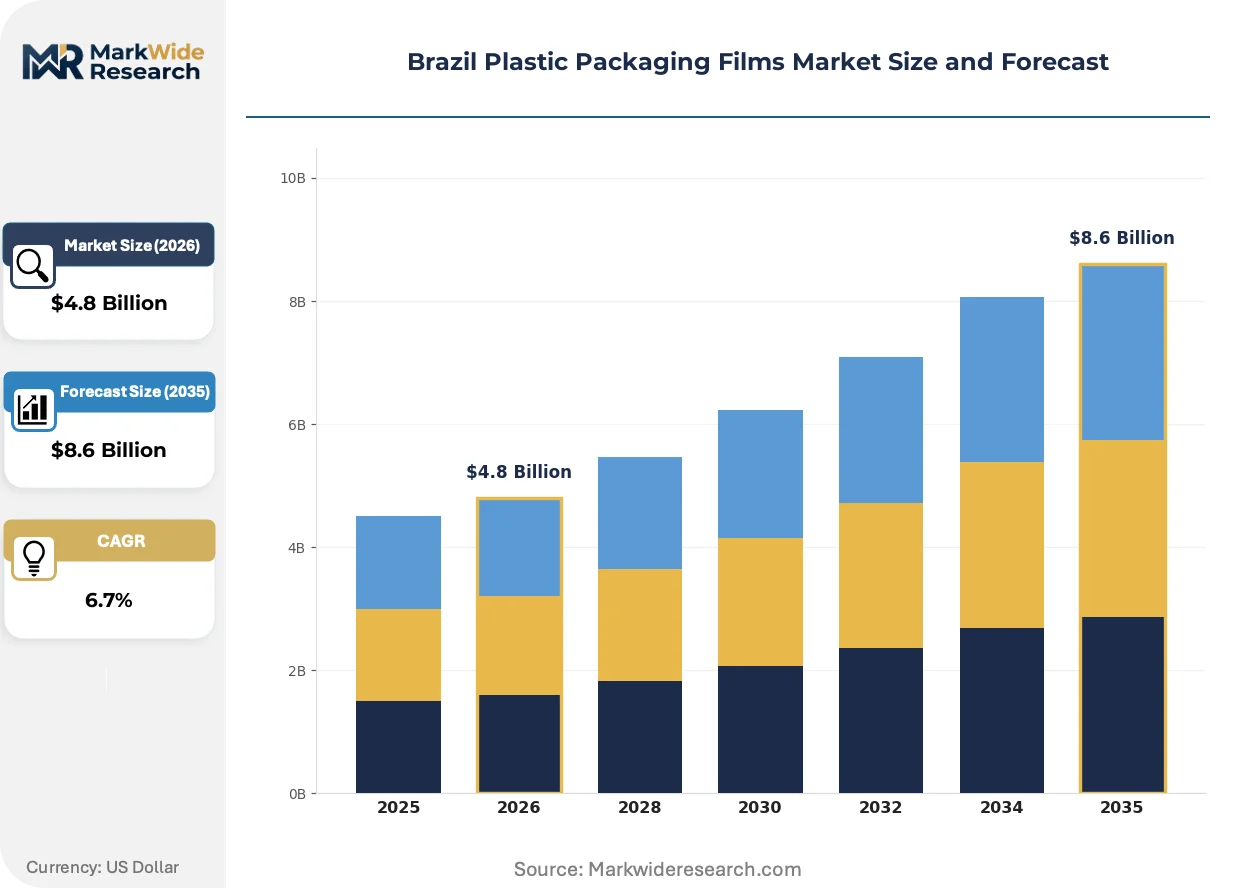
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Coextruded Film End Use Industry: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Form: Roll, Bag, Pouch, Sheet |
| Companies Covered | Lord Brasil, Videplast Packaging Industry Ltda., Amcor PLC, Sonoco Products Company, Berry Global Inc., Parnaplast, Sealed Air Corporation, Mondi Group, Constantia Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Plastic Packaging Films Market Trends and Innovations
Digital printing integration and predictive analytics are compressing converter-customer relationships from transactional supply toward embedded technical partnerships with shared shelf-life risk.
Digital flexographic printing is unifying short-run customization with high-speed production economics previously split between rotogravure and offset alternatives. Mid-sized meat processors in São Paulo's ABC region are adopting digitally printed barrier films for seasonal promotional SKUs with two-week turnaround requirements. This capability is unifying brand differentiation with supply chain responsiveness, collapsing minimum order quantities and enabling just-in-time inventory positioning against import competition.
ANVISA's Resolution RDC 326 implementation timeline is forcing simultaneous reformulation of adhesive layers and antioxidant packages across multilayer film portfolios. Converters are consolidating supplier relationships to secure batch-to-batch migration consistency documentation required for food contact compliance certificates. The regulatory pressure is most acute in dairy applications, where lipid-rich contents accelerate additive migration and processors are responding by pre-qualifying film suppliers through joint validation protocols.
Subscription-based technical service agreements are displacing spot procurement among multinational food processors with complex barrier requirements. Amcor PLC and regional converters are embedding predictive maintenance and inventory management into multi-year supply contracts with penalty clauses for shelf-life failures. This contractual evolution is most visible in Rio Grande do Sul poultry export corridors, where temperature excursion liability is being transferred upstream to film suppliers with embedded sensor integration.
Brazil Plastic Packaging Films Market Segmentation
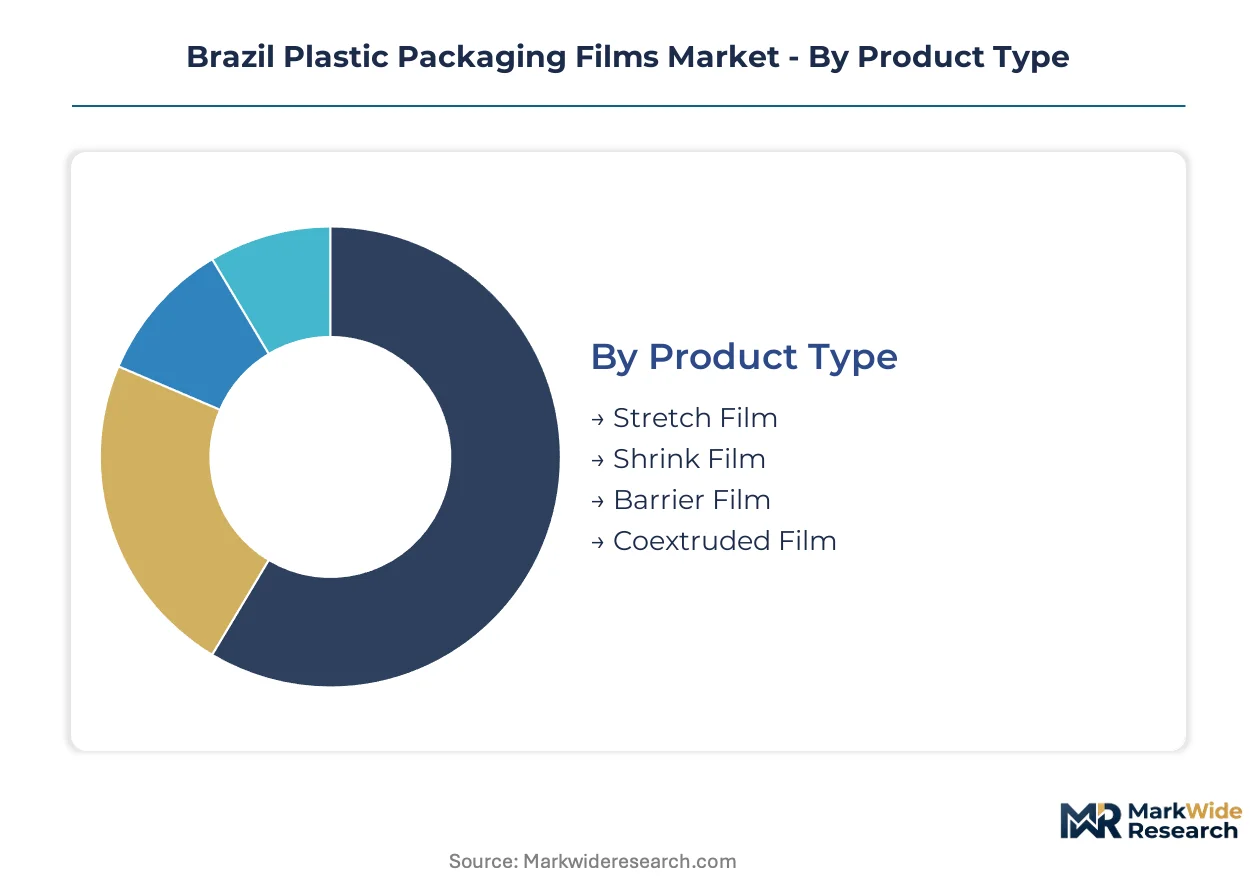
Segmentation in Brazil's plastic packaging films market reveals how volume commodity positions and premium barrier specifications serve fundamentally different customer economics. Understanding these splits helps converters align capital deployment with margin structure and regulatory exposure across the value chain.
Product Type:
Stretch film dominates tonnage while barrier film commands the steepest value per kilogram premium.
- Stretch Film:Linear low-density polyethylene formulations optimized for load containment and puncture resistance during palletization. Demand concentrates in São Paulo's agribusiness logistics corridors serving soybean and corn exports through the Port of Santos, driven by expanded grain handling capacity and automated wrapping lines.
- Barrier Film:Multilayer structures incorporating ethylene vinyl alcohol copolymer and polyamide for oxygen and moisture control. Meat and dairy processors in Minas Gerais and Rio Grande do Sul specify these for Middle Eastern and Asian export markets where shelf-life requirements exceed 90 days.
- Shrink Film:Polyolefin-based formulations providing printed surface protection and retail presentation for bottled beverages and consumer goods.
- Coextruded Film:Seven-layer and nine-layer structures displacing laminated alternatives in premium food contact applications requiring ANVISA-compliant migration performance.
Mature deployment sits with stretch film serving established agribusiness networks. Newer deployment is concentrated in coextruded barrier structures responding to protein export specification upgrades.
End Use Industry:
Food contact compliance requirements create the widest divergence in technical specification and validation burden.
- Food & Beverage:Modified atmosphere packaging for fresh produce, vacuum skin packs for proteins, and high-barrier lidding for dairy. Supermarket chains in Recife and Salvador are adopting specifications previously limited to São Paulo's ABC retail corridor.
- Pharmaceuticals:Blister packs and cold-form foil laminates requiring child-resistant and senior-friendly opening features alongside moisture barrier performance. ANVISA's pharmaceutical packaging regulations impose stricter extractables testing than food contact standards.
- Consumer Goods:Printed overwrap and multi-pack bundling for personal care and household products where shelf appeal drives specification.
- Electronics:Anti-static and moisture barrier bags for component protection during Brazil's humid distribution conditions.
Validation infrastructure concentrates in food and beverage. Emerging demand is expanding fastest in pharmaceutical applications with specialized barrier requirements.
Material:
Feedstock access and resin compounding capabilities determine regional production economics.
- Polyethylene:Linear low-density and metallocene grades for stretch film and sealant layers. Braskem's domestic ethylene supply anchors converter margins, though naphtha-linked volatility exposes cost structures.
- Polypropylene:Cast and biaxially oriented grades for high-clarity food packaging and metallization substrates. Demand from fresh produce retail chains in the Northeast is climbing the fastest among regional expansion corridors.
- Polyvinyl Chloride:Shrink film and blister pack applications with declining share due to ESG procurement criteria and mechanical recycling incompatibility.
- Others:Polyamide for barrier layers, ethylene vinyl alcohol copolymer for oxygen scavenging, and bio-based alternatives responding to ABNT biodegradable specifications.
Established capacity centers on polyethylene serving commodity film demand. Investment flows are redirecting toward polypropylene and barrier resin compounding near São Paulo petrochemical hubs.
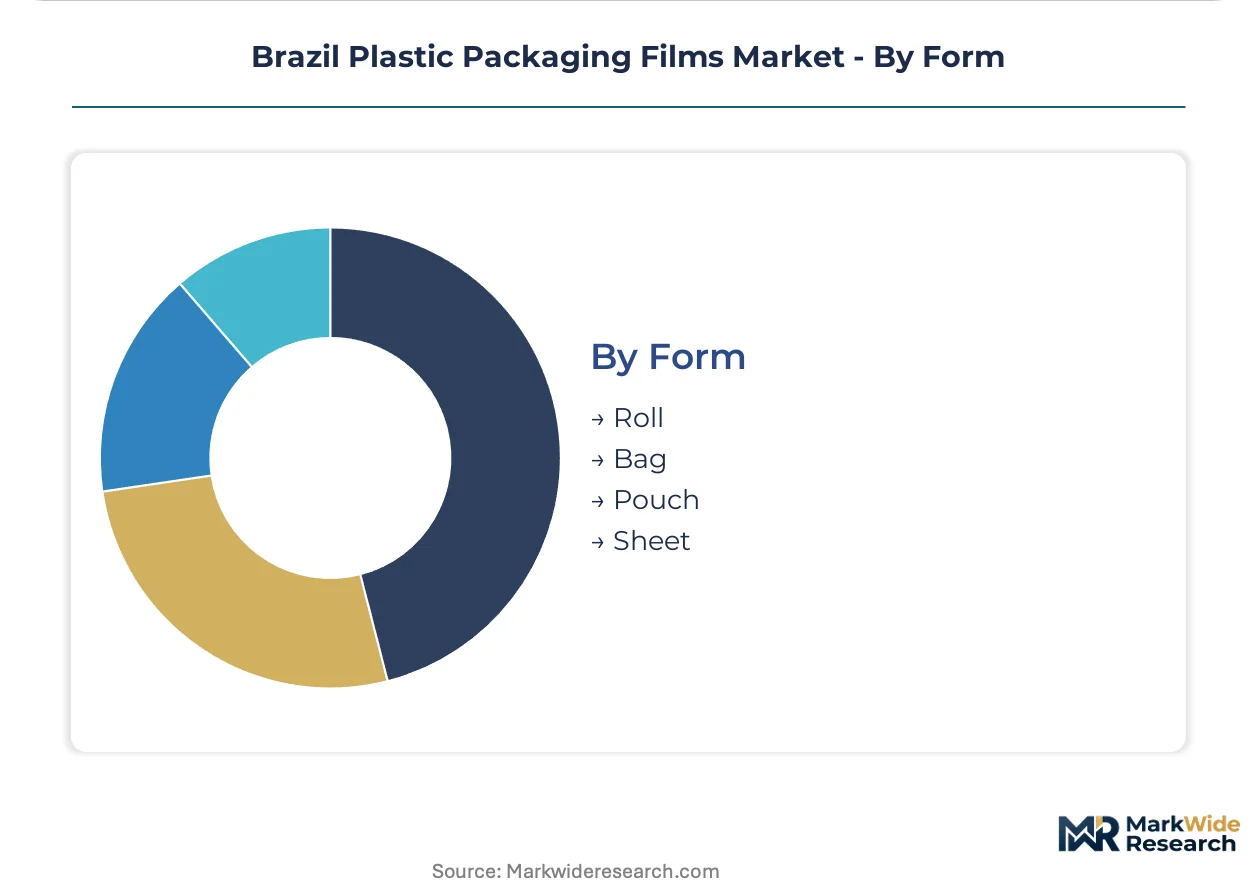
Form:
Converter equipment configuration and customer fulfillment models shape form factor preference.
- Roll:Master rolls for downstream converting and automated packaging lines. Stretch and shrink films ship predominantly in this format to large-scale food processors and logistics operators.
- Bag:Pre-formed open-mouth and gusseted configurations for manual and semi-automated filling operations.
- Pouch:Stand-up and flat pouches with reseal features for retail-ready presentation. Digital printing integration is enabling shorter runs for seasonal promotional SKUs.
- Sheet:Cut-to-size substrates for thermoforming and tray sealing applications in protein packaging.
Roll format retains the largest volume position serving industrial customers. Pouch and sheet configurations are gaining specification share in retail-ready and modified atmosphere applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's ABC industrial corridor anchors Brazilian plastic packaging film demand through its concentration of food processors, beverage bottlers, and petrochemical feedstock access. The Port of Santos logistics network channels agribusiness exports that consume stretch film at scale. State-level extended producer responsibility frameworks in São Paulo and Minas Gerais are reshaping procurement criteria toward certified recycled content.
São Paulo
Multinational food processors and retail chains drive specification upgrades for high-barrier lidding and modified atmosphere packaging. ANVISA's Resolution RDC 326 compliance requirements concentrate validation laboratory capacity in the ABC region. São Paulo's petrochemical hubs supply captive resin compounding operations that anchor converter margin structures against import competition.
Minas Gerais
Meat and dairy exporters in the Triângulo Mineiro and Belo Horizonte corridors specify ethylene vinyl alcohol copolymer barriers for Middle Eastern destination markets. State-level extended producer responsibility regulations create preferential procurement status for converters with certified recycled resin supply chains. Uberlândia's protein processing cluster demands multilayer structures with 90-plus day shelf-life performance.
Rio Grande do Sul
Poultry export processors in Santa Maria and Pelotas drive subscription-based technical service agreements with predictive maintenance clauses. ANVISA migration testing mandates compress formulation timelines for lipid-rich dairy applications. Porto Alegre's converting sector specializes in vacuum skin packs for premium protein retail positioning.
Rio de Janeiro
Beverage distribution networks serving the metropolitan region expand stretch film consumption for automated palletization lines. The state's pharmaceutical packaging sector demands child-resistant blister formats with stricter extractables testing than food contact standards. Duque de Caxias hosts converting operations supplying retail-ready pouch formats for coastal consumer goods markets.
Bahia
Supermarket chains in Salvador adopt modified atmosphere packaging specifications previously concentrated in Southeast retail corridors. Northeast Brazil's food retail expansion creates demand for tropical-condition shrink film formulations with enhanced heat-seal integrity. Camaçari's petrochemical complex offers alternative polyethylene feedstock sourcing reducing dependence on Southeast resin supply.
Brazil Plastic Packaging Films Market Competitive Landscape
Capital-heavy producers with captive resin compounding and metallization assets compete with asset-light converters focused on formulation specialization and technical service partnerships. The market structures around three tiers: multinational integrated players with multi-year supply contracts, regional converters with state-level EPR compliance advantages, and specialized niche formulators serving tropical distribution requirements. Strategic moves concentrate on backward integration into resin compounding, chemical recycling feedstock partnerships, and predictive maintenance contract embedding.
Among multinational integrated players, Amcor PLC and Berry Global Inc. occupy positions exemplifying the technical service agreement model. Videplast Packaging Industry Ltda. represents the regional specialist archetype with formulation capabilities tailored to Brazilian distribution conditions. These three anchors illustrate the competitive spectrum from global scale to local specialization without implying specific market share positions or strategic actions beyond their visible naming conventions.
| Leading Market Players |
|---|
| Lord Brasil |
| Videplast Packaging Industry Ltda. |
| Amcor PLC |
| Sonoco Products Company |
| Berry Global Inc. |
| Parnaplast |
| Sealed Air Corporation |
| Mondi Group |
| Constantia Flexibles |
| Others |
Pricing and Supply Chain Analysis
Braskem's naphtha-linked ethylene price index cascades through Brazilian converter cost structures, stratifying film pricing across premium barrier specifications, standard coextruded grades, and commodity stretch alternatives while compressing margins for non-integrated players.
Pricing Analysis
Margin tightening in standard-grade polyethylene film reflects Braskem's maintenance shutdown exposure and import parity pricing. Three-tier pricing structure across premium EVOH barrier, standard multilayer, and economy monolayer levels separates converters by migration testing certification and resin compounding integration. Cost-down pressure on commodity stretch film accelerates because agribusiness buyers consolidate palletization procurement through annual tenders. Food processors with export shelf-life requirements show least price sensitivity; logistics operators serving grain elevators exhibit highest.
Supply Chain Analysis
Dual-sourcing mandates from multinational meat processors in Minas Gerais and Rio Grande do Sul require ANVISA-compliant film qualification across at least two converter relationships. Raw material dependencies center on domestic ethylene from Braskem's São Paulo petrochemical complex, imported EVOH barrier resins from Japan and Belgium, and polyamide feedstocks from Germany and the United States. Single-source vulnerability concentrates in metallization equipment, where vacuum deposition capacity scarcity forces substrate imports or capital-intensive foreign machinery procurement. Distribution runs through São Paulo's ABC converting corridor to protein processing clusters, with Northeast retail expansion pulling supply northward.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's plastic packaging films market sits in a technology-transition phase as digital printing and predictive maintenance contracts displace spot procurement and rotogravure dominance.
For Market Incumbents: Anticipate margin compression from chemical recycling entrants by securing pyrolysis feedstock partnerships before INMETRO certification scarcity advantages erode. Defensive consolidation through captive resin compounding capacity in São Paulo petrochemical hubs anchors cost position against naphtha volatility. Subscription-based technical service agreements with embedded sensor integration lock in multinational protein processors before regional converters achieve ANVISA validation parity. For New Entrants and Emerging Players: E-commerce-enabled direct procurement channels bypass established distributor relationships in Northeast Brazil's supermarket expansion corridors. White-space concentration sits with modified atmosphere packaging specifications for fresh produce in Recife and Salvador, where tropical-condition formulation expertise creates defensible positioning. Target chemical recycling feedstock partnerships with São Paulo waste management operators to secure INMETRO-compliant recycled content claims ahead of federal packaging waste regulation enforcement. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier converters with ANVISA pre-qualified portfolios and state-level EPR compliance infrastructure in Minas Gerais. Long-term viability hinges on backward integration into resin compounding or forward integration into digital printing capability. Watch ANVISA migration testing laboratory capacity expansion as the inflection signal for product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene supply from Braskem's São Paulo hubs insulates margin structures from naphtha-linked volatility. |
| Chemical Recycling Feedstock Partnership | Pyrolysis-based polyolefin recovery enables INMETRO-compliant recycled content claims for premium private-label positioning. |
| Digital Printing Capability Deployment | Flexographic integration collapses minimum order quantities for seasonal promotional SKUs in São Paulo's ABC meat processing corridor. |
| Predictive Maintenance Contract Embedding | Technical service agreements with shelf-life failure penalty clauses transfer temperature excursion liability upstream to film suppliers. |
| State-Level EPR Compliance Infrastructure | Certified recycled resin supply chains in São Paulo and Minas Gerais secure preferential procurement status from retail chains with ESG commitments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving film converter plant managers, multinational food processor procurement leads, ANVISA regulatory affairs specialists, and petrochemical distribution channel partners. Bottom-up volume estimates from resin consumption patterns and top-down value validation from export trade statistics were reconciled through iterative triangulation. ABNT biodegradable specifications, INMETRO conformity assessment records, and Braskem ethylene supply disclosures provided foundational benchmarks.
Data-stream reconciliation across production capacity surveys, equipment installation tracking, and customer procurement pattern analysis informed the analytical framework. Segmentation dimensions modeled include product type, end-use industry, material composition, and regional production hub characteristics across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules, with protein export specification upgrades and agribusiness palletization intensity serving as primary demand drivers.
Inputs from ANVISA migration testing laboratories and state environmental agency EPR implementation records were available through the study window; gaps in chemical recycling commercial scale-up timelines introduce uncertainty bands around recycled content penetration assumptions. Deviation in federal packaging waste regulation enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global BOPET Packaging Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
Poly Coated Paper Market
Poly film
France Plastic Packaging Films Market
Poly film
Polystyrene Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Blown Film Extruder Market
Poly film
Polyurethane (PU) Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Multi-Layer Blown Films Market
Poly film
Global Thermoplastic Films Market
Poly film
Timber Wrap Films Market
Poly film
Global EVOH Films for Packaging Market
Poly film
Polypropylene Packaging Films Market