
 Germany Plastic Packaging Films Market | 2026-2036
Germany Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Plastic Packaging Films Market Insights
Specialty film distribution through regional converters is fragmenting as direct-to-brand relationships bypass traditional wholesale tiers. SÜDPACK Holding GmbH leverages its vertical integration across extrusion and printing to secure premium food contracts. TORAY FILMS EUROPE anchors its position through PET film leadership in pharmaceutical blister applications. Klöckner Pentaplast competes aggressively in rigid films for modified-atmosphere meat packaging across Central European processing lines.
Germany plastic packaging films comprise polymer-based flexible substrates engineered to thicknesses between 12 and 150 microns, manufactured via cast or blown extrusion with optional biaxial orientation, coextrusion, or metallization to achieve oxygen transmission rates below 1 cc/m²/day for sensitive goods. Their primary purpose spans containment, preservation, unitization, and shelf-ready display across industrial and consumer supply chains. Barrier films lead value generation due to ethylene vinyl alcohol and polyamide coextrusion requirements in protein packaging, while stretch films dominate tonnage through pallet wrap standardization in German logistics networks. Polyethylene sustains volume leadership across bags and roll stock formats, though polypropylene is displacing legacy substrates in transparent retail pouches where clarity and heat resistance command price premiums.
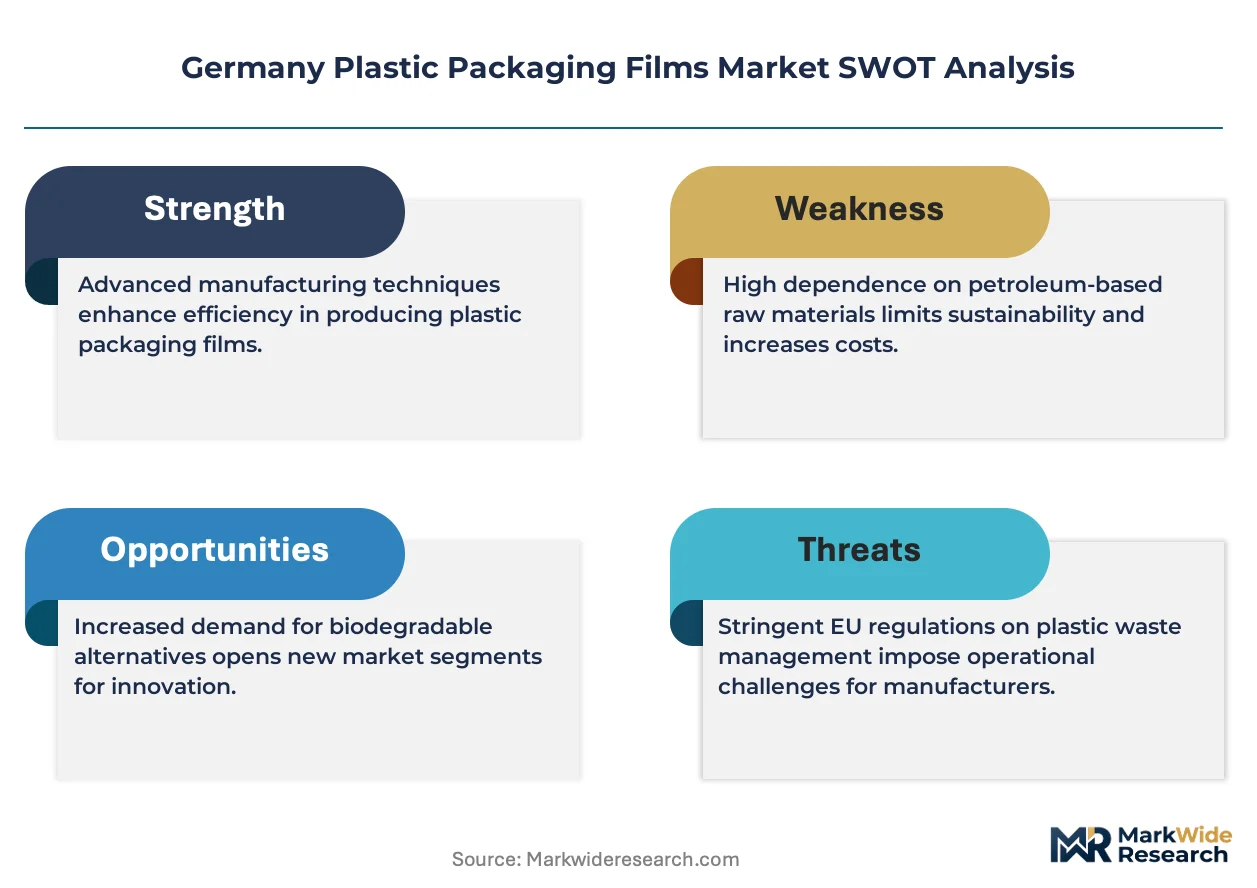
The EU Green Deal and Germany's national Packaging Act enforce extended producer responsibility and recycled content thresholds that reshape raw material procurement for film extruders. REACH compliance and the F-Gas Regulation constrain solvent-based adhesive systems and fluorinated barrier chemistries, redirecting R&D toward waterborne coatings and bio-based sealants. Stakeholders must monitor how the CSRD disclosure requirements will expose Scope 3 emissions from petrochemical feedstocks, forcing strategic decisions between imported recycled resin premiums and domestic chemical recycling partnerships.
Market Dynamics
Extended producer responsibility mandates under Germany's Packaging Act are forcing converters to reengineer supply chains around verified recycled content streams, compressing margins for non-compliant substrate suppliers.
Growth Catalysts
- High-barrier coextrusion:Meat and dairy processors in Bavaria's industrial corridor are specifying ethylene vinyl oxygen barriers below 1 cc/m²/day to extend protein shelf life and reduce retail waste.
- EU Green Deal packaging targets:Recycled content thresholds are redirecting procurement toward chemical recycling partnerships and domestic reprocessing infrastructure.
- Pharmaceutical serialization:Blister packaging for temperature-sensitive biologics is driving PET film specifications with metallization and child-resistant lidding requirements.
Market Restraints
- Feedstock cost volatility:Naphtha-linked polyethylene and polypropylene resin prices swing with crude differentials, compressing extruder margins on fixed-price annual contracts.
- Fluorinated chemistry constraints:REACH and the F-Gas Regulation are banning per- and polyfluoroalkyl substances in high-barrier applications, forcing costly reformulation of legacy sealant systems.
- Mechanical recycling quality gaps:Post-consumer film bales from German collection systems carry odor and contamination loads that fail food-contact migration testing.
Strategic Opportunities
- Baden-Württemberg automotive battery films:Lithium-ion cell wrapping and thermal runaway barriers represent an underpenetrated specification channel as domestic gigafactory capacity scales.
- Waterborne adhesive convergence:Solventless lamination paired with UV-cured coatings is opening premium pharmaceutical contracts previously held by solvent-based systems.
- Extended producer responsibility credits:The Packaging Act's dual system fees reward lightweighting and mono-material designs, creating margin recovery pathways for compliant converters.
Industry Challenges
- Migration testing bottlenecks:Food-contact certification for novel bio-based sealants faces 18-24 month evaluation timelines at BfR, delaying commercial launch windows.
- Extrusion technician scarcity:Blown film die adjustment and gauge control expertise is retiring faster than vocational programs in Saxony and North Rhine-Westphalia can replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Plastic Packaging Films Market |
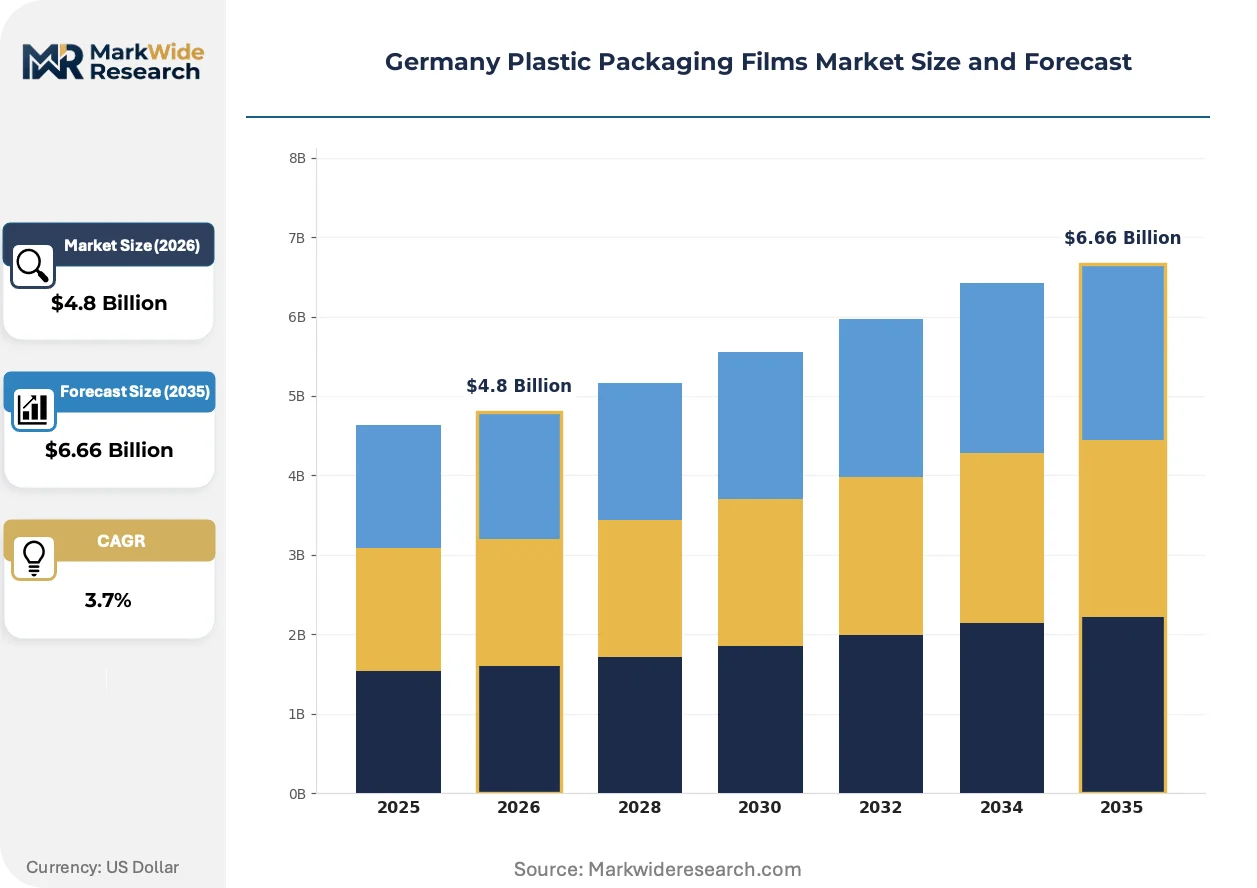
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Barrier Films, Rigid Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Packaging Type: Pouches, Bags, Roll Stock, Containers |
| Companies Covered | SÜDPACK Holding GmbH, Berry Global Inc., TORAY FILMS EUROPE, Innovia Films, Taghleef Industries, Klöckner Pentaplast, Mitsubishi Polyester Film GmbH, DUO PLAST AG, Jindal Films Europe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Plastic Packaging Films Market Trends and Innovations
Mono-material polyolefin structures are displacing multi-layer laminates as sorting infrastructure and near-infrared detection systems advance, compressing the technical advantage of complex coextrusion.
Digital watermarking embedded during extrusion is rendering obsolete traditional resin identification methods that relied on manual sorting and inconsistent near-infrared signatures. Bavarian dairy brands are piloting these markers to secure green-dot fee reductions. The technology is compressing value capture for converters lacking inline printing and encoding capabilities.
CSRD disclosure requirements are exposing Scope 3 emissions from petrochemical feedstocks, forcing film extruders to document cradle-to-gate carbon intensity or lose preferred supplier status. Large German food manufacturers are embedding these thresholds in procurement scorecards. Pharmaceutical packaging contracts show the steepest compliance premium differentiation.
Direct specification relationships between brand owners and resin compounders are bypassing traditional converter wholesale tiers in high-volume categories. Retail chains in North Rhine-Westphalia are sourcing standard polyethylene roll stock through centralized procurement platforms. Channel compression is fragmenting margin pools for regional distributors without extrusion assets.
Germany Plastic Packaging Films Market Segmentation
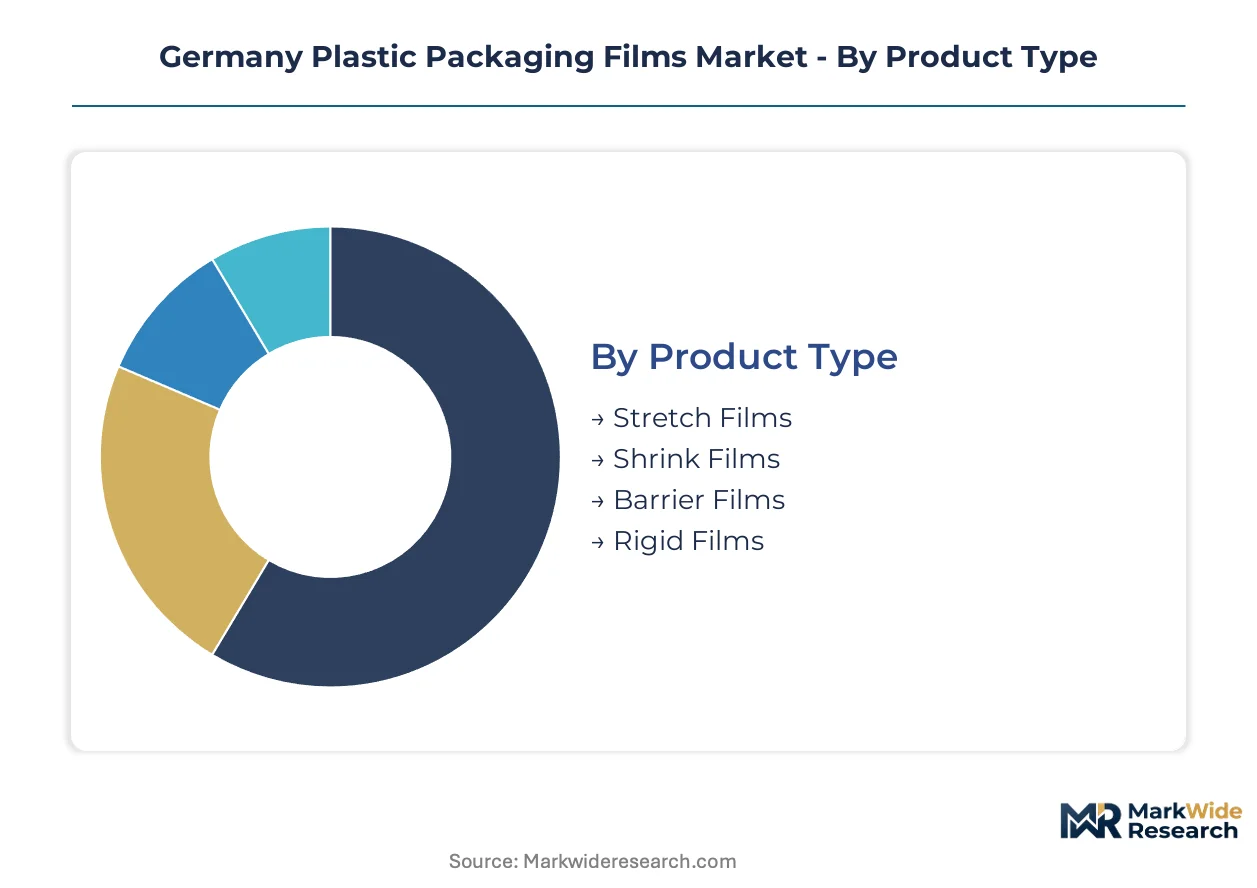
Segmentation in Germany's plastic packaging films market reveals how technical specifications, regulatory pressures, and end-use requirements fragment procurement patterns across converters and brand owners. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Converters across Bavaria and North Rhine-Westphalia engineer film architectures to match oxygen transmission thresholds, mechanical load requirements, and optical clarity demands across protein packaging, pharmaceutical blisters, and logistics unitization.
- Barrier Films:Multi-layer coextrusions incorporating ethylene vinyl alcohol and polyamide achieve oxygen transmission below 1 cc/m²/day for modified-atmosphere meat packaging in Bavarian dairy and protein processing corridors. German food processors specify these substrates to extend retail shelf life and meet EU food waste reduction targets.
- Stretch Films:Linear low-density polyethylene formulations dominate pallet wrap applications across German logistics networks, with thickness optimization driven by the Packaging Act's dual system fee structures that reward lightweighting. Standardization around 17-23 micron specifications has compressed differentiation among commodity suppliers.
- Shrink Films:Polyolefin and polyvinyl chloride formulations provide unitization and retail display clarity for beverage multipacks and consumer goods bundling.
- Rigid Films:Thermoformable polystyrene and polyester substrates serve pharmaceutical blister packs and modified-atmosphere trays for premium protein cuts.
The dominant share belongs to Stretch Films through logistics standardization, while Barrier Films is closing the gap fastest on protein shelf-life extension mandates.
Material:
Resin selection determines compliance pathways under REACH, mechanical recycling compatibility, and carbon intensity documentation for CSRD disclosures.
- Polyethylene:Low-density and linear low-density grades sustain volume leadership across bags, roll stock, and stretch wrap formats. German converters favor polyethylene for mono-material designs that qualify for green-dot fee reductions under extended producer responsibility frameworks.
- Polypropylene:Cast and biaxially oriented variants displace legacy substrates in transparent retail pouches where heat resistance and optical clarity support microwaveable and hot-fill applications. North Rhine-Westphalia retail chains specify polypropylene for private-label ready-meal packaging.
- Polyvinyl Chloride:Pharmaceutical blister and shrink sleeve applications persist despite regulatory pressure on chlorine chemistry and mechanical recycling incompatibility.
- Others:Bio-based polylactic acid and chemically recycled polyesters serve niche pharmaceutical and organic food segments requiring fossil-free feedstock documentation.
Polyethylene commands installed extrusion capacity, though Polypropylene is gaining share fastest on retail clarity and heat resistance specifications.
End User:
Downstream procurement patterns concentrate demand geographically and drive divergent certification requirements for migration testing, serialization, and carbon accounting.
- Food & Beverage:Meat and dairy processors in Bavaria's industrial corridor specify high-barrier coextrusions with ethylene vinyl alcohol cores to achieve 21-28 day shelf life for case-ready proteins. The EU Green Deal packaging targets are redirecting procurement toward chemically recycled content and mono-material structures compatible with existing German sorting infrastructure.
- Healthcare:Pharmaceutical manufacturers specify metallized polyester and cold-form aluminum laminates for temperature-sensitive biologics requiring child-resistant lidding and serialization compliance. BfR food-contact certification timelines of 18-24 months constrain novel substrate adoption.
- Consumer Goods:Personal care and household product brands prioritize shelf-ready display properties and e-commerce durability over barrier performance.
- Electronics:Anti-static and moisture-barrier films protect components through automated assembly lines and export packaging.
Food & Beverage absorbs the greatest extrusion tonnage, while Healthcare delivers the steepest margin expansion on certification barriers and serialization complexity.
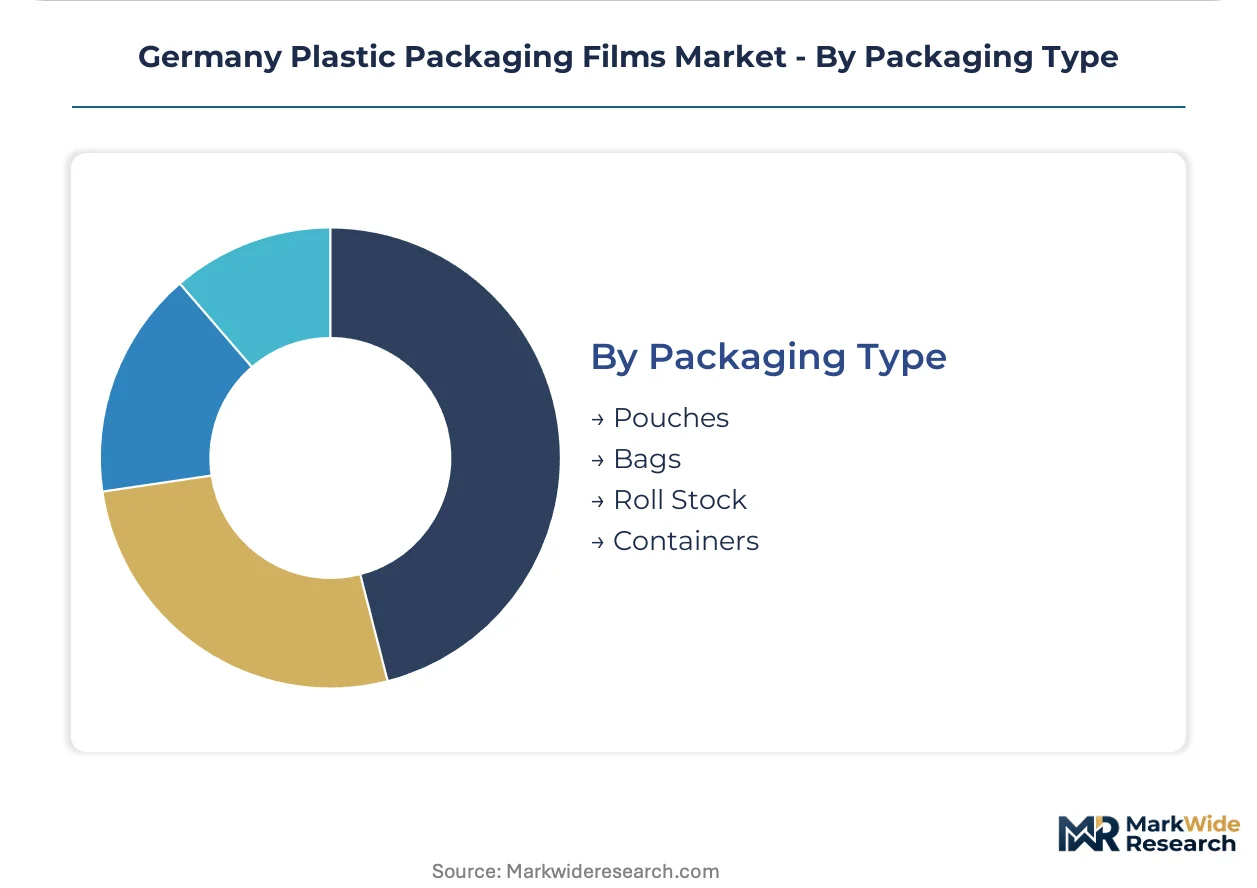
Packaging Type:
Format selection determines converter equipment requirements, printing registration tolerances, and downstream filling line integration complexity.
- Roll Stock:Unprinted or surface-printed webs supply form-fill-seal operations across German dairy and meat processing lines. Baden-Württemberg automotive battery film specifications are emerging as a specialty roll stock channel for lithium-ion cell wrapping.
- Pouches:Stand-up and flat pouch formats displace rigid containers in premium pet food and organic grain segments, requiring zippers and spout fitment integration.
- Bags:Side-seal and bottom-gusseted polyethylene formats serve commodity produce and frozen vegetable distribution.
- Containers:Thermoformed trays and lidded tubs integrate rigid films with flexible lidding for modified-atmosphere protein retail.
Roll Stock dominates converter output volumes, while Pouches is expanding most quickly on premiumization and convenience positioning in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and Germany's Packaging Act anchor regulatory frameworks across Central European film markets, with national implementations creating divergent compliance costs and procurement patterns for extruders and converters.
Bavaria
Meat and dairy processors in Bavaria's industrial corridor specify ethylene vinyl alcohol barrier films below 1 cc/m²/day oxygen transmission. Germany's Packaging Act mandates extended producer responsibility fees that reward lightweighting and mono-material designs. Munich and Nuremberg host converter clusters serving case-ready protein packaging lines with 21-28 day shelf-life requirements.
North Rhine-Westphalia
Retail chains in this region centralize procurement of standard polyethylene roll stock through digital platforms, bypassing traditional wholesale tiers. REACH compliance constrains solvent-based adhesive systems, redirecting lamination toward waterborne coatings. The Rhine-Ruhr metropolitan area concentrates stretch film extrusion capacity for German logistics networks.
Baden-Württemberg
Automotive battery film specifications are emerging for lithium-ion cell wrapping and thermal runaway barriers as domestic gigafactory capacity scales. The F-Gas Regulation bans fluorinated chemistries in high-barrier applications, forcing sealant reformulation. Stuttgart's industrial belt attracts specialty film investments for electric vehicle supply chains.
Lower Saxony
Agricultural film demand concentrates in this northern region for silage wrap and greenhouse applications. CSRD disclosure requirements expose Scope 3 emissions from petrochemical feedstocks, forcing carbon intensity documentation. Hanover and Wolfsburg anchor distribution networks serving northern European farming operations.
Hesse
Pharmaceutical packaging procurement clusters around Frankfurt's logistics hub for temperature-sensitive biologics requiring serialization compliance. BfR food-contact certification timelines of 18-24 months constrain novel substrate adoption. The Rhine-Main region hosts metallized polyester specifications for child-resistant lidding applications.
Germany Plastic Packaging Films Market Competitive Landscape
Vertically integrated specialists and regional converters split the market between premium specification channels and commodity tonnage. Three archetypes dominate: extrusion-integrated compounders controlling resin-to-film conversion, independent converters reliant on toll coating partnerships, and resin suppliers forward-integrating into film production. Competitive intensity centers on chemical recycling partnerships securing verified recycled content streams, and mono-material design capabilities qualifying for green-dot fee reductions.
Among Germany-based integrated producers, SÜDPACK Holding GmbH and DUO PLAST AG occupy positions spanning extrusion and printing operations. TORAY FILMS EUROPE represents the multinational specialty film archetype with European manufacturing footprint. Klöckner Pentaplast exemplifies rigid film specialists competing in modified-atmosphere packaging specifications. These anchors illustrate how backward integration into resin compounding and captive coating capacity separates premium-tier positioning from commodity reliance.
| Leading Market Players |
|---|
| SÜDPACK Holding GmbH |
| Berry Global Inc. |
| TORAY FILMS EUROPE |
| Innovia Films |
| Taghleef Industries |
| Klöckner Pentaplast |
| Mitsubishi Polyester Film GmbH |
| DUO PLAST AG |
| Jindal Films Europe |
| Others |
Pricing and Supply Chain Analysis
Belgian and Dutch resin compounders supplying polyethylene and polypropylene feedstocks to German extruders capture upstream margin pools that converters downstream struggle to reclaim without backward integration into compounding operations. The Packaging Act's dual system fee structures reward lightweighting and mono-material designs, redirecting procurement negotiations toward specification premiums rather than commodity tonnage discounts.
Pricing Analysis
Bavarian dairy processors pay 15-25% premiums over North Rhine-Westphalia retail chains for ethylene vinyl oxygen barrier specifications below 1 cc/m²/day. Three-tier pricing structure across premium, standard, and economy levels separates certified food-contact grades from industrial stretch wrap and agricultural silage film. Cost compression in standard polyethylene roll stock intensifies because retail procurement platforms centralize volume and squeeze converter margins. Logistics operators purchasing stretch film for pallet wrap exhibit highest price sensitivity, while pharmaceutical manufacturers specifying metallized polyester for blister packs show least sensitivity due to serialization compliance requirements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate converter-resin supplier relationships, with supply-chain finance facilities emerging as working capital bridges for mid-tier extruders. Feedstock concentration in Belgium, the Netherlands, and Germany's own chemical corridor near Ludwigshafen creates geographic clustering around Rhine-Ruhr logistics networks. Raw material dependencies on naphtha-linked polyethylene, polypropylene, and ethylene vinyl alcohol copolymers expose margins to crude differential volatility. Single-source vulnerability concentrates in ethylene vinyl alcohol supply from limited European polymerization capacity. Distribution runs through regional converter clusters in Bavaria and North Rhine-Westphalia serving protein processors and retail chains respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's plastic packaging films market represents a high-growth disruption as the EU Green Deal's recycled content mandates force a complete reengineering of raw material procurement and specification relationships across the value chain.
For Market Incumbents: Build certification moats around BfR food-contact approvals and CSRD-compliant carbon intensity documentation to lock out non-compliant competitors. Secure chemical recycling partnerships with domestic reprocessors to guarantee verified recycled content streams before mandates tighten. Channel control through direct-to-brand relationships bypasses wholesale tier fragmentation threatening regional distributors without extrusion assets.
For New Entrants and Emerging Players: Baden-Württemberg's automotive battery film channel for lithium-ion cell wrapping remains underpenetrated by incumbent flexible packaging specialists focused on food applications. Waterborne adhesive convergence in pharmaceutical lamination opens contracts previously held by solvent-based legacy suppliers. Target specialty roll stock specifications for electric vehicle thermal runaway barriers as domestic gigafactory capacity scales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical recycling and mono-material R&D infrastructure, favoring scaled players with balance sheet capacity. Acquisition target archetype: mid-tier converters with captive coating capacity and established brand-direct relationships but lacking resin compounding backward integration. Monitor BfR certification timeline compression as signal for novel bio-based sealant commercialization inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Secures verified recycled polyethylene streams qualifying for Packaging Act green-dot fee reductions. |
| Mono-Material Design Transition | Enables food-contact compliance under extended producer responsibility frameworks advancing across EU member states. |
| Waterborne Coating Adoption | Opens pharmaceutical lamination contracts as REACH constraints ban solvent-based adhesive systems. |
| Digital Watermarking Integration | Captures green-dot fee reductions for Bavarian dairy brands piloting inline encoding during extrusion. |
| Battery Film Specification Entry | Positions converters for lithium-ion cell wrapping demand scaling with Baden-Württemberg gigafactory investments. |
Research Methodology
A spread of perspectives from blown film extrusion technicians, procurement leads at Bavarian meat processors, pharmaceutical packaging engineers, and logistics operators converged on the working assumptions shaping this analysis. Primary interviews with converters, resin compounders, and brand owner specification teams combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, BfR food-contact certification databases, and German customs trade data. Bottom-up capacity and demand modeling triangulated against top-down spending pattern analysis across food, healthcare, and automotive end-use segments.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning barrier performance tier, material chemistry, end-use industry, and regional production cluster. CAGRs derived from installed extrusion capacity expansion plans, substitution elasticity estimates for mono-material structures, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs incorporated ethylene vinyl alcohol supply constraints and chemical recycling yield rate projections.
Practitioners should monitor recycled resin price spreads, BfR certification queue lengths, and automotive battery film specification releases for early signals of inflection. Forecasts reflect assumptions about regulatory enforcement timelines, mechanical recycling infrastructure deployment, and feedstock cost volatility. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Cast Stretch Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Soft Touch Film Market
Poly film
PVC Cling Film Market
Poly film
Polycarbonate Films Market
Poly film
Packaging Film Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
MOPP Packaging Films Market
Poly film
PCR Bubble Films Market
Poly film
Formable Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Poly Coated Paper Market
Poly film
Global PVDC Coated Films Market
Poly film
China Plastic Packaging Film Market