
 Thermal Insulation Packaging Market | 2026-2036
Thermal Insulation Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Insulation Packaging Market Analytics
Temperature-monitoring subscription services is broadening what thermal insulation packaging vendors sell beyond physical containers. Sonoco ThermoSafe leverages integrated digital tracking to differentiate its pharmaceutical offerings across North American and European lanes. Cold Chain Technologies anchors its competitive position through specialized qualification protocols for cell-and-gene-therapy shipments. Va-Q-tec dominates vacuum-insulated panel manufacturing with proprietary fumed-silica core technology that sustains extended hold times without active cooling.
Thermal insulation packaging comprises engineered enclosures, wraps, and containers designed to maintain specified temperature ranges for sensitive goods during transit and storage. These systems typically integrate expanded polystyrene, polyurethane foam, vacuum-insulated panels, or reflective metallized films with phase-change materials to achieve thermal resistance values exceeding R-8 per inch in premium configurations. Foam-based product types command the largest installed base due to low unit cost and established molding infrastructure, though vacuum-insulated panels represent the fastest-expanding category as pharmaceutical cold-chain requirements tighten below -70°C. Material selection increasingly polarizes between lightweight polyethylene solutions for last-mile food delivery and high-performance fiberglass-composite assemblies for intercontinental pharmaceutical lanes where excursion tolerance approaches zero.
The US FDA enforces stringent distribution documentation for temperature-sensitive biologics under current Good Distribution Practice guidelines, directly elevating qualification burdens for packaging suppliers seeking pharmaceutical market access. The EU REACH framework and ECHA substance restrictions constrain certain blowing agents and flame retardants used in polystyrene foams, redirecting R&D investment toward bio-based and recyclable alternatives. Stakeholders must monitor evolving pharmacopeial standards and refrigerant-phase-down schedules to align material roadmaps with compliance trajectories that will reshape cost structures and competitive viability.
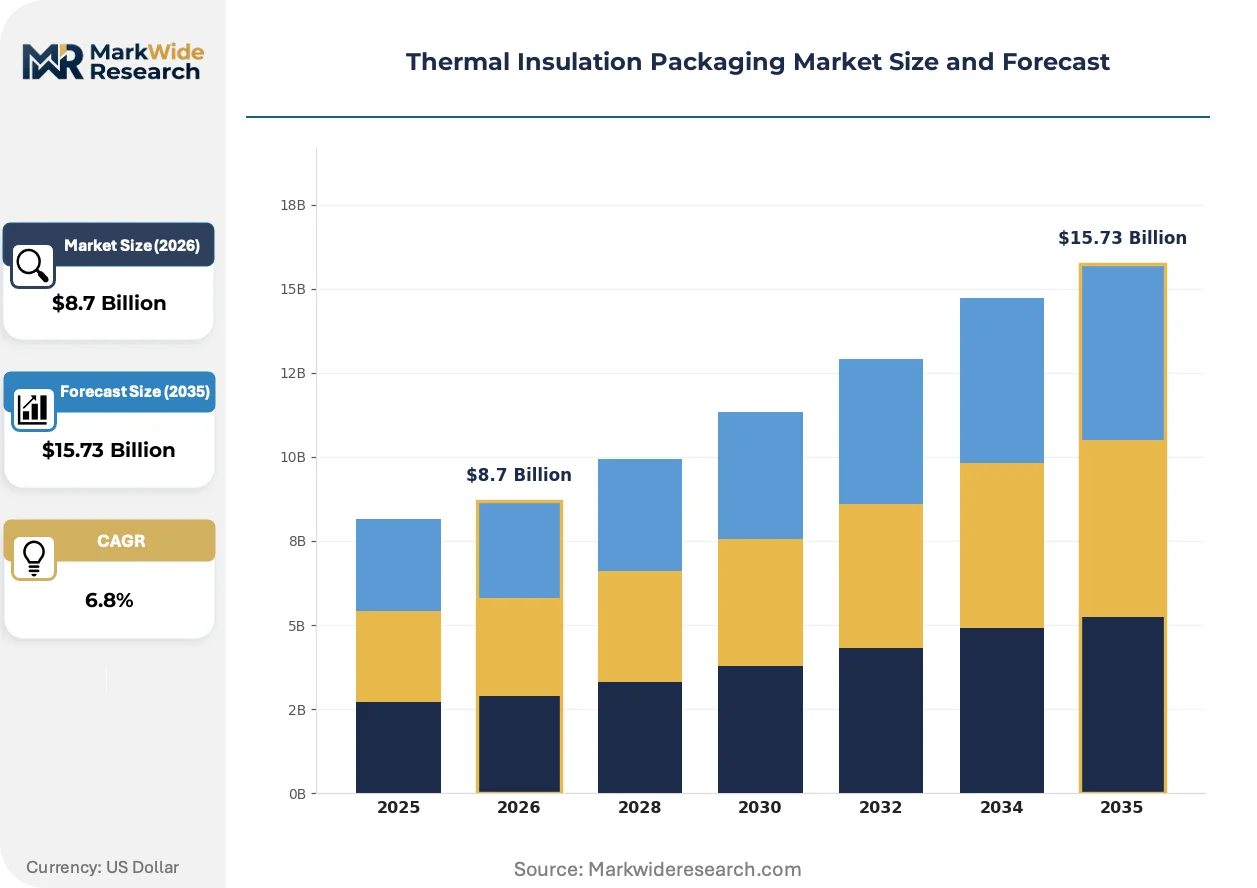
Market Dynamics
Passive thermal protection systems are displacing active refrigeration in pharmaceutical logistics as the EU F-Gas Regulation and parallel refrigerant-phase-down policies escalate operational costs for mechanical cooling units.
Growth Catalysts
- Cell-and-gene therapy expansion:Advanced biologics requiring ultra-low temperature stability below -70°C are multiplying clinical trial volumes and commercial shipments, forcing adoption of vacuum-insulated panel systems with extended hold times.
- REACH substance restrictions:The EU ECHA framework constrains hydrofluorocarbon blowing agents and halogenated flame retardants in conventional polystyrene foams, redirecting material innovation toward bio-based aerogels and silica-core composites.
- Last-mile food delivery densification:Urban consolidation centers and quick-commerce fulfillment networks in metropolitan Germany and the Netherlands are standardizing lightweight polyethylene thermal liners for same-day grocery temperature integrity.
Market Restraints
- Raw material supply concentration:Fumed silica feedstock for vacuum-insulated panel cores concentrates among German and Chinese chemical producers, exposing packaging manufacturers to input volatility and allocation constraints.
- Performance-cost asymmetry:Vacuum-insulated panels deliver thermal resistance values exceeding R-30 per inch but command unit costs 8-12× expanded polystyrene equivalents, limiting penetration in cost-sensitive food service applications.
- End-of-life regulatory friction:The EU Single-Use Plastics Directive and emerging Extended Producer Responsibility schemes impose collection and recycling obligations on multi-material thermal packaging assemblies, complicating reverse logistics.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO-licensed biologics manufacturing hubs in Hyderabad and Bangalore are scaling temperature-controlled air freight to European and North American markets, creating demand for qualification-ready passive containers.
- Digital-physical convergence:Integration of IoT temperature loggers with blockchain-verified chain-of-custody documentation is enabling outcome-based service contracts that bundle packaging with excursion liability transfer.
- Japan's regenerative medicine acceleration:METI's strategic prioritization of iPSC-derived therapies and allogeneic cell products is tightening domestic cold-chain standards and opening specialized qualification service markets.
Industry Challenges
- Thermal qualification engineering scarcity:Pharmaceutical packaging validation against ISTA 7E and WHO PQS protocols requires specialized expertise in computational fluid dynamics and phase-change material calibration that outpaces workforce development.
- Multi-modal integration complexity:Container systems must maintain temperature integrity across air, ocean, and road legs with divergent handling protocols, forcing redundant safety margins that inflate dimensional weight and freight cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Insulation Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Bubble Wrap, Panels, Sheets Material: Polyethylene, Polystyrene, Fiberglass, Reflective Foil Application: Food Delivery, Pharmaceutical Shipping, Electronics Packaging, Industrial Transport End User: Food Service, Healthcare, Retail, Manufacturing |
| Companies Covered | Sonoco ThermoSafe, Cold Chain Technologies, ThermoSafe Solutions, Pelican BioThermal, Sealed Air Corporation, Cryopak, Softbox Systems, Va-Q-tec, Intelsius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Insulation Packaging Market Evolving Landscape
Aerogel-composite insulation layers are penetrating pharmaceutical cold-chain applications as manufacturers seek sub-ambient performance without mechanical refrigeration dependency or fluorinated refrigerant exposure.
Silica-aerogel blankets laminated with metallized polymer films are rewriting performance benchmarks for ultra-low-temperature shipments. Cell-and-gene therapy distributors are adopting these systems for intercontinental lanes where active cooling unit failures carry catastrophic product loss. The technology is compressing acceptable excursion windows from hours to minutes by eliminating thermal mass penalties of traditional phase-change material configurations.
The EU F-Gas Regulation mandates an 80% reduction in hydrofluorocarbon consumption by 2030 against 2015 baselines. This policy is accelerating passive insulation substitution in temperature-controlled logistics previously dominated by mechanical compression refrigeration. Pharmaceutical lanes between Germany and the United States are experiencing the fastest displacement as qualification protocols for vacuum-insulated panel systems achieve parity with active unit documentation.
Buying organizations are consolidating vendor relationships around integrated packaging-plus-monitoring service providers. Food retailers and third-party logistics operators are displacing component procurement with multi-year performance contracts that bundle thermal container supply, real-time tracking, and reverse logistics. This pattern is most visible in German and Dutch grocery e-commerce networks where same-day delivery promises compress tolerance for temperature deviation to near-zero.
Thermal Insulation Packaging Market Segmentation
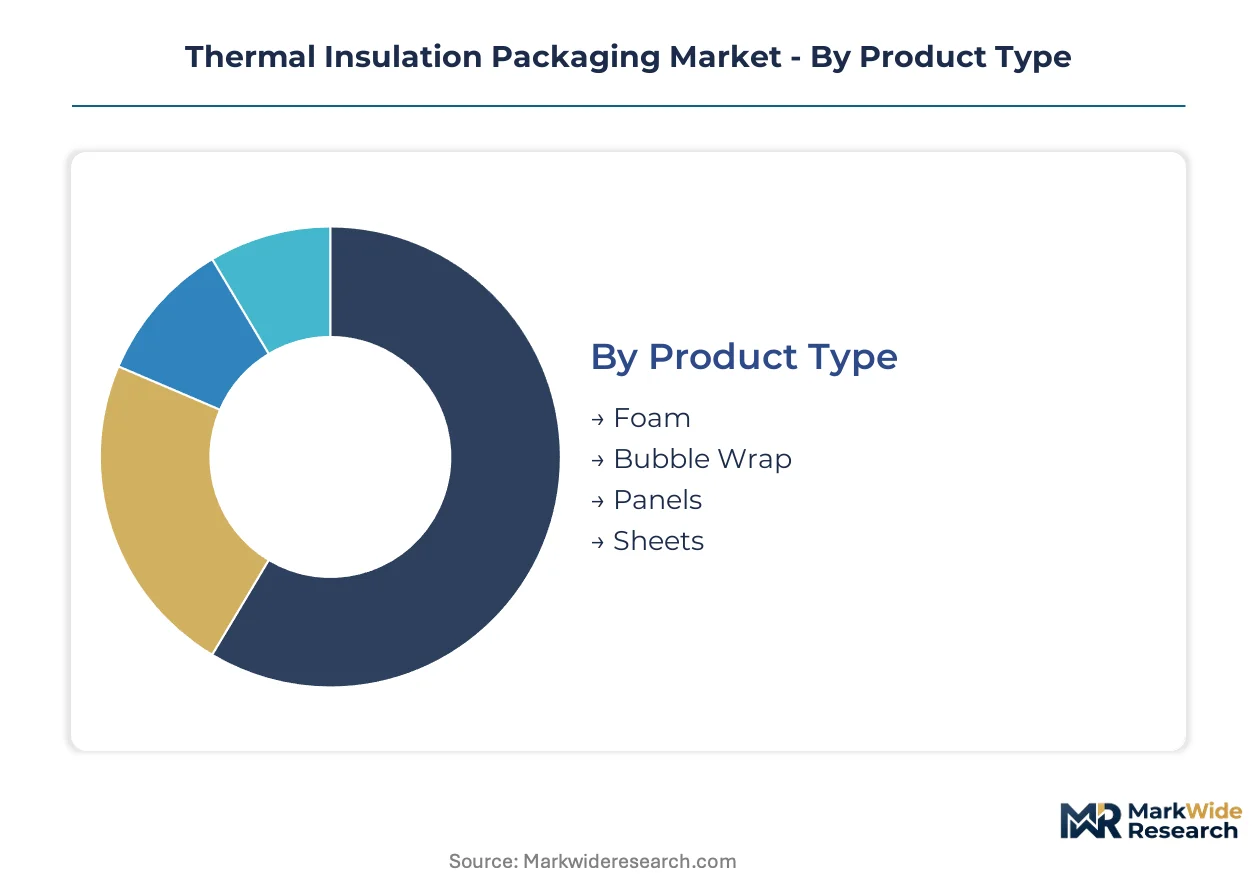
Thermal insulation packaging configurations span commodity-grade disposables to engineered systems requiring pharmaceutical qualification. Material selection and performance tier determine compliance eligibility, freight economics, and end-of-life obligations across regulated supply chains.
Product Type:
Customization intensity varies from molded commodity shapes to precision-engineered vacuum assemblies with validated hold-time documentation.
- Foam:Expanded polystyrene and polyurethane configurations dominate pharmaceutical and food service lanes through established molding infrastructure and low unit economics. Demand concentrates in North American pharmaceutical distribution networks where FDA qualification protocols favor proven material documentation over novel alternatives.
- Panels:Vacuum-insulated panel systems achieve thermal resistance values exceeding R-30 per inch through fumed-silica cores and metallized barrier films. Cell-and-gene therapy shippers in Germany and the United States specify these assemblies for ultra-low-temperature lanes below -70°C where excursion tolerance approaches zero.
- Bubble Wrap:Air-encapsulated polyethylene films serve lightweight cushioning applications with modest thermal retention requirements. E-commerce fulfillment centers deploy these liners for ambient-stable electronics and non-perishable retail shipments.
- Sheets:Flat-stock insulation materials enable on-site fabrication of custom enclosure dimensions. Industrial transport operators in manufacturing corridors favor sheet formats for irregular machinery and equipment protection.
Most installed capacity flows through Foam. Expansion is steepest in Panels.
Material:
Cost structure and regulatory compliance pressure separate commodity petrochemical feedstocks from advanced composites facing REACH substance restrictions.
- Polyethylene:Lightweight, recyclable films and foams standardize last-mile grocery delivery in Dutch and German urban consolidation networks. Quick-commerce operators specify polyethylene thermal liners for same-day temperature integrity with minimal dimensional weight penalty.
- Polystyrene:Expanded and extruded forms retain the largest installed base through mature supply chains and molding equipment depreciation. ECHA constraints on hydrofluorocarbon blowing agents and halogenated flame retardants are redirecting R&D investment toward bio-based alternatives.
- Fiberglass:High-density composite assemblies serve intercontinental pharmaceutical lanes requiring mechanical durability and extended hold times. These materials command premium positioning against commodity foam alternatives.
- Reflective Foil:Metallized polymer films laminate with aerogel or foam substrates to create radiant barrier systems. Electronics packaging applications favor these configurations for combined thermal and electrostatic protection.
Polystyrene retains the deepest installed base. Polyethylene is climbing the fastest as last-mile delivery densifies.
Application:
Performance requirements and qualification burden create distinct procurement patterns across temperature-sensitive verticals.
- Pharmaceutical Shipping:Biologics and cell-and-gene therapies mandate validated cold-chain documentation under FDA and EMA distribution guidelines. Passive insulation systems are displacing active refrigeration as EU F-Gas Regulation compliance costs escalate.
- Food Delivery:Quick-commerce and meal-kit operators standardize lightweight thermal liners for same-day temperature integrity. German and Dutch grocery e-commerce networks compress tolerance for deviation through consumer delivery promises.
- Electronics Packaging:Thermal management combines with electrostatic and shock protection for semiconductor and device shipments. Reflective foil laminates address radiant heat exposure during air freight.
- Industrial Transport:Heavy-equipment and machinery protection emphasizes mechanical durability over precision temperature control. Sheet and panel formats enable field-fabricated enclosure solutions.
Food Delivery generates the highest shipment velocity. Pharmaceutical Shipping commands the steepest qualification premium.
End User:
Procurement sophistication and compliance exposure differentiate regulated healthcare environments from cost-optimized retail operations.
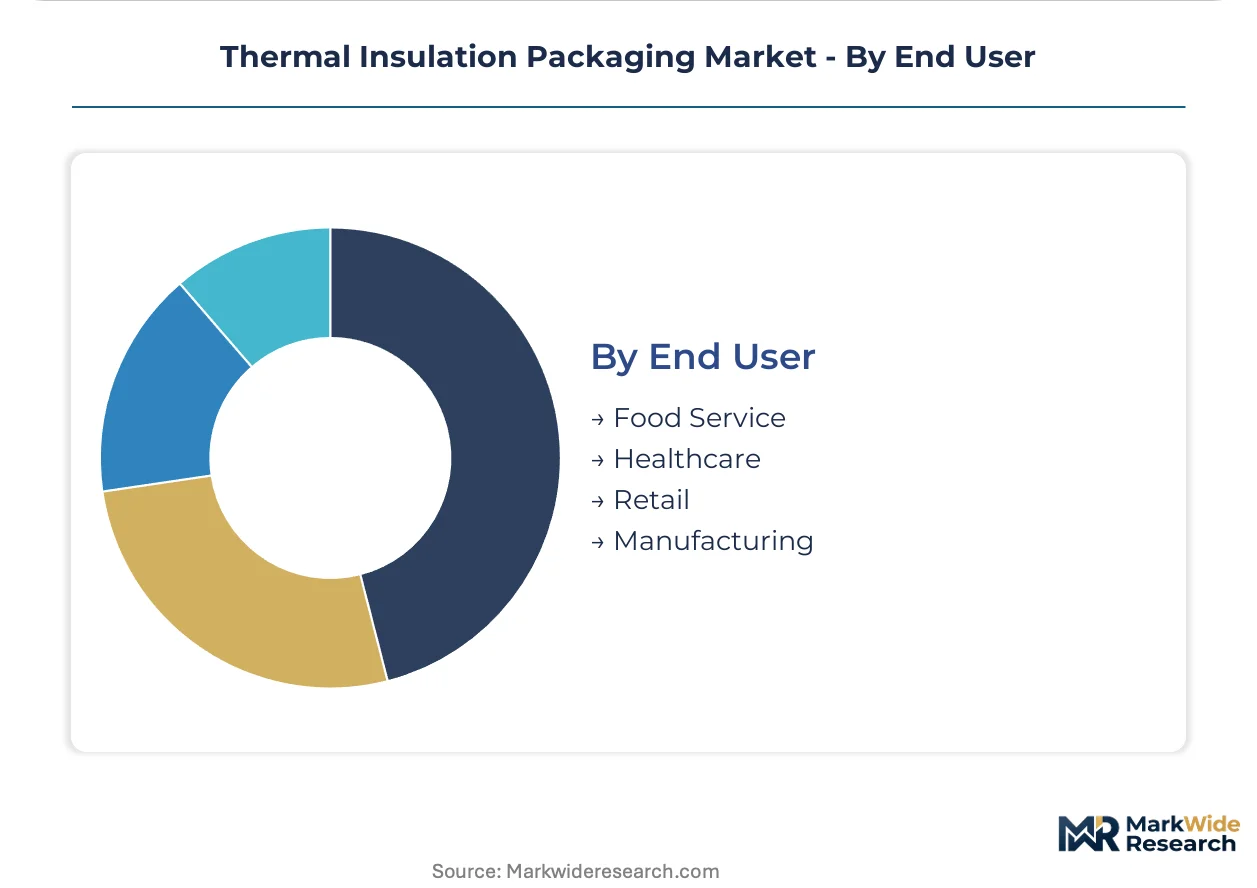
- Healthcare:Hospital systems, pharmacies, and clinical trial logistics operators require packaging validated against WHO PQS and ISTA 7E protocols. CDSCO-licensed manufacturers in Hyderabad and Bangalore are scaling demand for qualification-ready passive containers serving European and North American export corridors.
- Food Service:Restaurant chains, catering operators, and cloud kitchens prioritize unit economics and disposal convenience over extended hold times. Lightweight polyethylene solutions dominate procurement specifications.
- Retail:Omnichannel grocers and specialty food merchants balance temperature performance with brand-aligned unboxing experience. Subscription meal-kit providers influence material selection through recurring shipment volumes.
- Manufacturing:Industrial shippers of chemicals, coatings, and temperature-sensitive components specify custom-fabricated insulation for irregular dimensions. Procurement emphasizes durability and reuse cycles over single-use disposability.
Healthcare absorbs the highest qualification investment. Food Service drives the greatest shipment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing thermal insulation packaging production toward jurisdictions with lower compliance costs for fumed-silica feedstock and refrigerant-phase-down obligations. Manufacturers are relocating vacuum-insulated panel assembly to exploit gaps between EU F-Gas Regulation enforcement and emerging market substance controls.
Germany
Va-Q-tec anchors European vacuum-insulated panel production from its Würzburg headquarters, supplying pharmaceutical cold-chain systems for intercontinental biologics shipments. The EU F-Gas Regulation drives domestic demand for passive insulation alternatives as mechanical refrigeration operational costs escalate. Bavarian chemical clusters near Ludwigshafen concentrate fumed-silica precursor manufacturing, creating captive supply advantages for advanced panel fabricators.
United States
FDA qualification protocols for temperature-sensitive biologics under cGDP guidelines elevate procurement standards for packaging suppliers seeking pharmaceutical market access. The EPA refrigerant management program parallels EU phase-down timelines, accelerating passive system substitution in domestic cold-chain logistics. Greater Boston and Research Triangle Park biotech corridors generate concentrated demand for validated ultra-low-temperature shipping containers.
India
CDSCO-licensed biologics manufacturing hubs in Hyderabad and Bangalore are scaling temperature-controlled air freight to European and North American export markets. The PLI scheme for pharmaceutical manufacturing indirectly supports cold-chain infrastructure investment without direct packaging subsidies. Karnataka's aerospace logistics cluster near Bangalore International Airport is emerging as a qualification service hub for passive container validation.
Netherlands
Quick-commerce fulfillment networks in Amsterdam and Rotterdam urban consolidation centers standardize lightweight polyethylene thermal liners for same-day grocery temperature integrity. REACH substance restrictions on hydrofluorocarbon blowing agents redirect food service procurement toward recyclable alternatives. Dutch horticultural export corridors through Schiphol cargo terminals generate secondary demand for floral and perishable temperature protection systems.
Japan
METI's strategic prioritization of iPSC-derived therapies and allogeneic cell products tightens domestic cold-chain standards beyond conventional pharmaceutical benchmarks. The PMDA accelerated approval pathway for regenerative medicines compresses packaging qualification timelines, favoring suppliers with established WHO PQS documentation. Kanto region biotech manufacturing concentration around Tsukuba and Yokohama drives specialized passive container specification.
Thermal Insulation Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical qualification requirements favoring branded incumbents while food service procurement tilts toward OEM fabricators. The market exhibits moderate concentration at the premium tier where vacuum-insulated panel technology creates defendable positioning, with fragmentation characterizing commodity foam segments. Three archetypes dominate: integrated packaging-plus-monitoring service providers, specialized qualification engineering houses, and scale-driven foam molders. Consolidation is accelerating through strategic partnerships between materials suppliers and logistics operators, while geographic expansion into Indian pharmaceutical export corridors represents the dominant capacity deployment vector.
Among integrated service providers, Sonoco ThermoSafe and Cold Chain Technologies exemplify the packaging-plus-digital-monitoring convergence that pharmaceutical buyers increasingly specify. Va-Q-tec occupies a distinctive position as a technology anchor for vacuum-insulated panel manufacturing, with its proprietary fumed-silica core approach representing the high-performance tier. These three entities collectively illustrate how competitive positioning stratifies across service integration, materials science specialization, and qualification protocol mastery.
| Leading Market Players |
|---|
| Sonoco ThermoSafe |
| Cold Chain Technologies |
| ThermoSafe Solutions |
| Pelican BioThermal |
| Sealed Air Corporation |
| Cryopak |
| Softbox Systems |
| Va-Q-tec |
| Intelsius |
| Others |
Value Network & Pricing Analysis
Vacuum-insulated panel production migration toward fumed-silica feedstock clusters simultaneously compresses unit economics and concentrates supplier leverage among German and Chinese chemical producers. This geographic tethering of high-performance thermal packaging to Bavarian and Yangtze River Delta manufacturing corridors reshapes how buyers negotiate volume contracts and qualification timelines.
Pricing Analysis
Distributor margins on pharmaceutical-grade thermal containers absorb 15-25% of landed cost before hospital or biotech procurement teams take ownership. Three-tier pricing structure across premium VIP systems, qualified foam assemblies, and commodity polyethylene liners separates FDA-validated shipments from last-mile grocery delivery. Cost compression in commodity foam tiers is intensifying because REACH-compliant blowing agent substitutes raise material input expenses. Food service operators exhibit acute price sensitivity, while cell-and-gene therapy logistics teams prioritize excursion-proof performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fumed-silica precursor manufacturers who supply vacuum-insulated panel cores for ultra-low-temperature pharmaceutical shipments. Finished thermal packaging assembly concentrates in Germany, the United States, and India as CDSCO-licensed biologics exporters scale temperature-controlled air freight capacity. Raw material procurement draws from petrochemical feedstocks, metallized barrier films, and phase-change material formulations. Tariff exposure on Chinese silica imports threatens cost stability for European panel fabricators. Distribution runs through direct OEM relationships with pharmaceutical 3PLs and quick-commerce fulfillment operators rather than wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in thermal insulation packaging rests on fumed-silica core manufacturing scale economies and the premium-tier shift toward validated VIP systems for cell-and-gene therapy corridors.
For Market Incumbents: Hedge against bio-based aerogel substitution by securing captive fumed-silica supply through backward integration into Bavarian chemical clusters. Defend pharmaceutical qualification moats through accelerated WHO PQS protocol documentation ahead of Indian export corridor densification. Capacity addition in Karnataka's aerospace logistics cluster near Bangalore International Airport captures CDSCO-licensed manufacturer demand before regional competitors achieve parity validation. For New Entrants and Emerging Players: Enter via lightweight polyethylene thermal liner supply to Dutch and German quick-commerce urban consolidation centers where same-day delivery promises compress incumbent response times. Target food service procurement specifications for recyclable alternatives as EU Single-Use Plastics Directive compliance obligations mature. A subscription-based packaging-plus-monitoring service model displaces transactional component sales in grocery e-commerce networks. For Investors and Strategic Acquirers: Valuations sit cheapest among contract foam molders lacking pharmaceutical qualification infrastructure as regulatory barriers steepen. Long-term viability favors integrated packaging-plus-digital-monitoring service providers with established ISTA 7E validation capabilities. Watch for inflection when Indian pharmaceutical export volumes to European and North American markets trigger regional passive container qualification hub development.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fumed-Silica Feedstock | Captive supply from Bavarian chemical clusters secures VIP core cost stability against Chinese import volatility. |
| Qualification Service Hub Establishment | Karnataka aerospace logistics infrastructure near Bangalore International Airport captures CDSCO-licensed biologics exporter demand. |
| Packaging-Plus-Monitoring Subscription Launch | Bundled IoT temperature logger integration displaces transactional sales in German grocery e-commerce networks. |
| Bio-Based Aerogel R&D Partnership | REACH-compliant blowing agent alternatives redirect polystyrene foam innovation toward ECHA-aligned material roadmaps. |
| Indian Pharmaceutical Export Corridor Expansion | Hyderabad and Bangalore temperature-controlled air freight scaling creates demand for WHO PQS-validated passive containers. |
Research Methodology
Multiple input streams — primary interviews with cold-chain logistics directors, pharmaceutical packaging engineers, and quick-commerce procurement leads; secondary validation through customs trade data, ECHA substance restriction filings, and FDA cGDP guidance documents; plus SEC filings from listed packaging suppliers — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned qualification protocol specialists, fumed-silica chemical producers, and third-party logistics operators managing cell-and-gene therapy shipments.
Historical volume trajectories were cross-referenced against panel-based growth assumptions and foam substitution patterns across the projection horizon. Segmentation dimensions modeled include product type, material chemistry, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from shipment volume build-ups by lane and qualification tier, incorporating EU F-Gas Regulation phase-down schedules and Indian pharmaceutical export growth assumptions as industry-specific forecast inputs.
Inputs from EMA distribution guideline updates and CDSCO licensing databases were available through the study window; gaps in real-time quick-commerce procurement transaction data introduce uncertainty bands around last-mile segment sizing. Forecasts reflect documented assumptions about refrigerant-phase-down acceleration and biologics pipeline advancement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Book Wraps Market
Packaging Materials
Kraft Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Thermoformed Tubs Market
Packaging Materials
Foil Laminates Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Cargo Moisture Control Products Market
Packaging Materials
PET Strap Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Packaging Primers Market
Packaging Materials
VCI Films Market