
 Advanced Empty Capsule Market | 2026-2036
Advanced Empty Capsule Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Empty Capsule Market Outlook
Buyer concentration among pharmaceutical manufacturers is expanding as large-scale contract manufacturers consolidate procurement volumes across multiple dosage form facilities. Lonza Group leverages its integrated biologics-capsule supply chain to capture long-term supply agreements with top-tier drug developers. ACG anchors the Indian subcontinent with dedicated HPMC capsule lines serving both domestic export markets. Suheung competes through specialized gelatin formulations optimized for high-humidity tropical distribution.
Advanced empty capsules are dosage delivery shells engineered from gelatin, hydroxypropyl methylcellulose, or modified polymers, with wall thickness typically ranging from 0.10 to 0.15 mm and moisture content controlled below 15% to ensure mechanical integrity and dissolution predictability. Their primary commercial purpose is to encapsulate powders, granules, or semi-solids for oral administration while masking taste, protecting active ingredients, and enabling precise unit dosing. Gelatin capsules still occupy the largest revenue pool due to established supply chains and cost efficiency, though HPMC capsules are recording the fastest volume ascent as vegetarian and religious-dietary compliance requirements harden across European and Asian prescription markets. Functional coated capsules, including delayed release variants, concentrate margin pools where enteric polymers command premium positioning for acid-sensitive APIs and probiotic formulations.
The US FDA enforces dissolution profile consistency through its chemistry, manufacturing, and controls framework, while EMA's MDR and REACH compliance obligations shape capsule polymer selection and migration testing protocols for European market access. India's CDSCO has aligned with ICH stability guidelines, accelerating local manufacturers' qualification for US and EU export registrations. Stakeholders must monitor how EMA's evolving nitrosamine impurity thresholds and FDA's enhanced data integrity expectations reshape excipient qualification timelines and capsule supplier audit frequencies.
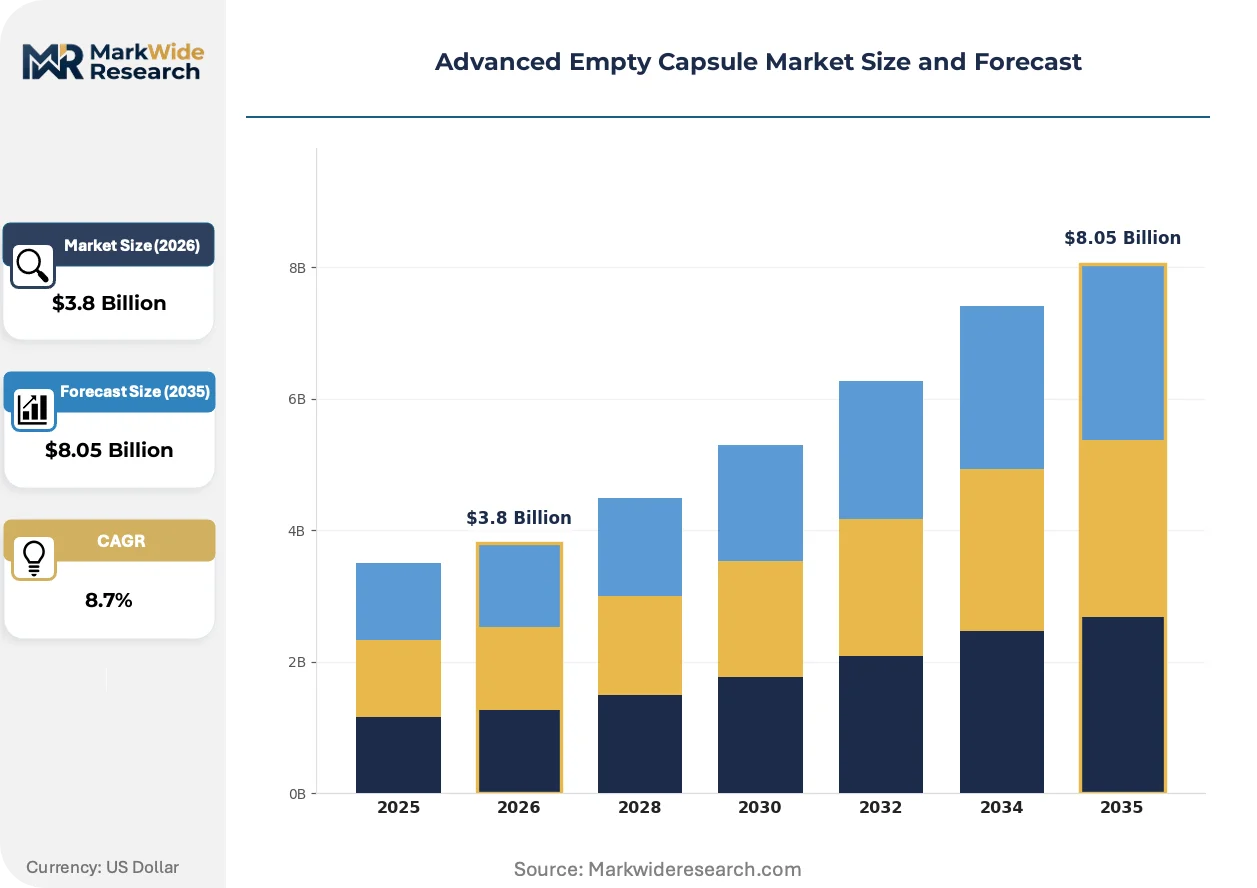
Market Dynamics
Clean-label pharmaceutical and nutraceutical procurement is compressing gelatin capsule demand while accelerating HPMC and pullulan material qualification across European and Asian manufacturing networks.
Growth Catalysts
- EMA MDR and REACH compliance:European pharmaceutical manufacturers are mandating vegetarian capsule alternatives to satisfy migration testing protocols and eliminate animal-derived excipient risks from supply chains.
- Nutraceutical clean-label pivot:Dietary supplement brands in Germany and the Netherlands are specifying HPMC shells to capture religious-dietary and vegan consumer segments previously excluded from gelatin-based products.
- India CDSCO-ICH alignment:Domestic Indian manufacturers are accelerating US and EU export registrations through stability guideline harmonization, unlocking contract manufacturing scale for international pharma clients.
Market Restraints
- Gelatin supply concentration:Bovine and porcine-derived raw material sourcing clusters in Brazil and Argentina expose capsule producers to livestock disease quarantine risks and price volatility.
- HPMC polymer cost premium:Hydroxypropyl methylcellulose raw materials command 40-60% higher input costs than pharmaceutical-grade gelatin, compressing margin structures for mid-tier capsule converters.
- Dissolution variability:HPMC capsules exhibit wider in-vitro dissolution profile variation across pH ranges compared to gelatin standards, complicating bioequivalence studies for generic drug developers.
Strategic Opportunities
- Indonesia and Vietnam pharma manufacturing:Southeast Asian contract manufacturing organizations are building dedicated capsule filling capacity to serve domestic ASEAN markets and Japanese export demand.
- Enteric-coated probiotic delivery:Acid-resistant functional coatings are enabling shelf-stable live culture formulations previously limited to refrigerated supply chains, opening pediatric and travel health applications.
- US FDA quality agreement standardization:The agency's enhanced data integrity expectations are creating qualification service opportunities for capsule suppliers with pre-validated manufacturing documentation packages.
Industry Challenges
- Polymer characterization expertise gap:Capsule manufacturers lack sufficient analytical chemistry capacity to execute nitrosamine impurity screening and polymer molecular weight distribution testing required by evolving EMA thresholds.
- Multi-site audit fatigue:Pharmaceutical buyers are consolidating supplier bases to reduce qualification burden, forcing smaller capsule producers to absorb repeated facility inspections without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Empty Capsule Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin Capsules, HPMC Capsules, Functional Coated Capsules, Delayed Release Capsules Application: Pharmaceuticals, Nutraceuticals, Clinical Trials, Dietary Supplements End User: Pharmaceutical Manufacturers, Contract Manufacturers, Research Institutions, Hospitals Delivery Mode: Oral Delivery, Sustained Release, Targeted Delivery, Immediate Release |
| Companies Covered | Suheung, Catalent, Lonza Group, Nitta Gelatin, Sirio Pharma, ACG, CapsCanada, Associated Capsules, Roquette Frères, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Empty Capsule Market Strategic Shifts
Capsule shell engineering is shifting from passive containment toward active ingredient protection and targeted release functionality, with material science and coating technologies advancing in parallel.
Modified-release polymer systems are converging with precision coating deposition technologies to enable gastric-resistant, colon-targeted, and chronotherapeutic delivery profiles previously achievable only through tablet compression. Specialty pharmaceutical developers in Switzerland and Massachusetts are piloting these combinations for peptide and biologic oral formulations. The convergence is compressing development timelines for complex generic products seeking 505(b)(2) regulatory pathways.
REACH Article 33 substance of very high concern disclosure requirements are forcing European capsule manufacturers to map full polymer supply chains and substitute legacy plasticizers with bio-based alternatives. Industrial consequence includes reformulation of shell flexibility agents and renewed migration testing for existing product registrations. German and French pharma packagers are responding by consolidating procurement with suppliers holding third-party EPD and ISO 14001 environmental certifications.
Certification-driven supplier selection is displacing price-first procurement among mid-sized generic drug manufacturers previously optimizing on unit cost alone. Audited capsule suppliers with pre-qualified Drug Master Files are capturing multi-year supply agreements that lock out unqualified competitors. This pattern is most visible in Indian pharmaceutical export clusters supplying regulated US and EU markets where customer audit costs exceed $50,000 per qualification cycle.
Advanced Empty Capsule Market Segmentation
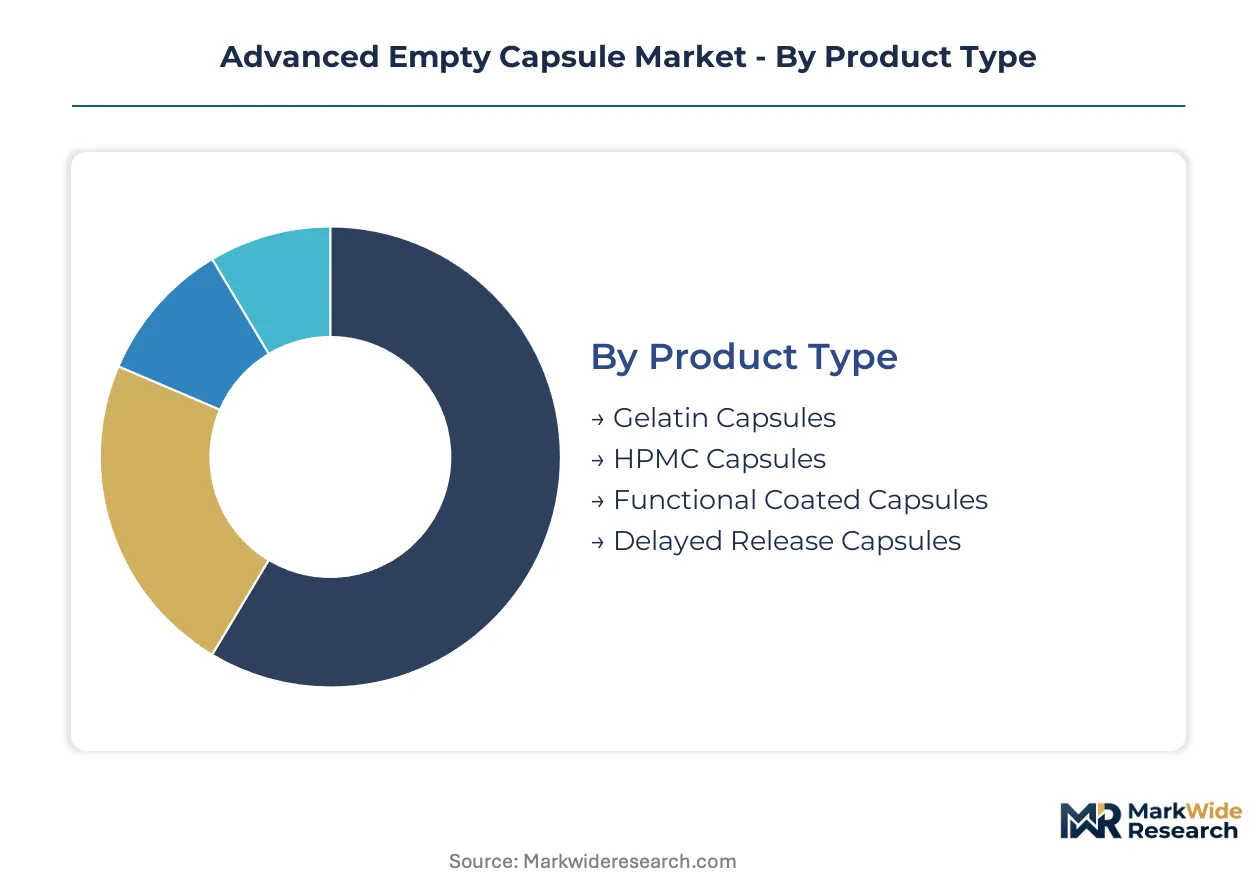
Capsule procurement patterns diverge sharply across material chemistry, therapeutic application, and manufacturing scale. Each segmentation axis reveals distinct buyer priorities that reshape supplier qualification requirements and margin structures.
Product Type:
Material selection separates buyers by regulatory exposure, dietary compliance obligations, and dissolution performance requirements.
- HPMC Capsules:Derived from hydroxypropyl methylcellulose, these vegetarian shells eliminate animal-derived excipient risks and satisfy EMA REACH migration testing protocols. European pharmaceutical manufacturers and German nutraceutical brands are mandating HPMC specifications to capture religious-dietary and vegan consumer segments previously excluded from gelatin-based products.
- Functional Coated Capsules:Enteric and acid-resistant polymer coatings enable gastric protection for acid-sensitive APIs and shelf-stable probiotic formulations. Swiss specialty pharmaceutical developers and Massachusetts biologic firms are piloting these shells for peptide oral delivery, compressing development timelines for 505(b)(2) regulatory pathways.
- Gelatin Capsules:Pharmaceutical-grade bovine and porcine-derived shells retain cost efficiency and established dissolution predictability across pH ranges.
- Delayed Release Capsules:Chronotherapeutic polymer systems target colon-specific or time-programmed API release profiles.
Gelatin capsules lead volumes today; HPMC capsules are gaining share fastest.
Application:
Dosage form complexity and regulatory scrutiny intensity define procurement behavior across therapeutic categories.
- Pharmaceuticals:Prescription drug developers demand validated dissolution profiles and pre-qualified Drug Master Files for FDA chemistry, manufacturing, and controls compliance. Indian contract manufacturers serving US and EU export markets are consolidating procurement with audited suppliers holding multi-year supply agreements.
- Nutraceuticals:Dietary supplement brands prioritize clean-label positioning and vegetarian shell alternatives to differentiate in saturated European and Asian consumer markets. Dutch and German brands specify HPMC to capture religious-dietary segments.
- Clinical Trials:Investigational drug sponsors require rapid material qualification and flexible batch sizing for adaptive study designs.
- Dietary Supplements:Mass-market vitamin and mineral brands optimize on unit cost while maintaining basic dissolution performance standards.
Pharmaceuticals dominates revenue contribution; nutraceuticals shows the steepest expansion trajectory.
End User:
Scale and vertical integration depth determine sourcing strategy and supplier relationship intensity.
- Pharmaceutical Manufacturers:Large-scale drug developers with in-house formulation capabilities negotiate long-term supply agreements locking in volume commitments and audit rights. Lonza Group leverages integrated biologics-capsule supply chains to capture these relationships.
- Contract Manufacturers:Multi-site CDMOs consolidate procurement across dosage form facilities to reduce qualification burden and leverage scale pricing. Indian CMOs are accelerating US and EU export registrations through CDSCO-ICH stability guideline alignment.
- Research Institutions:Academic and government labs prioritize small-batch flexibility and rapid material availability for exploratory formulations.
- Hospitals:Compounding pharmacies and institutional formulators require specialized shell sizes and custom color coding for patient adherence programs.
Pharmaceutical manufacturers anchor demand concentration; contract manufacturers are scaling procurement volumes most rapidly.
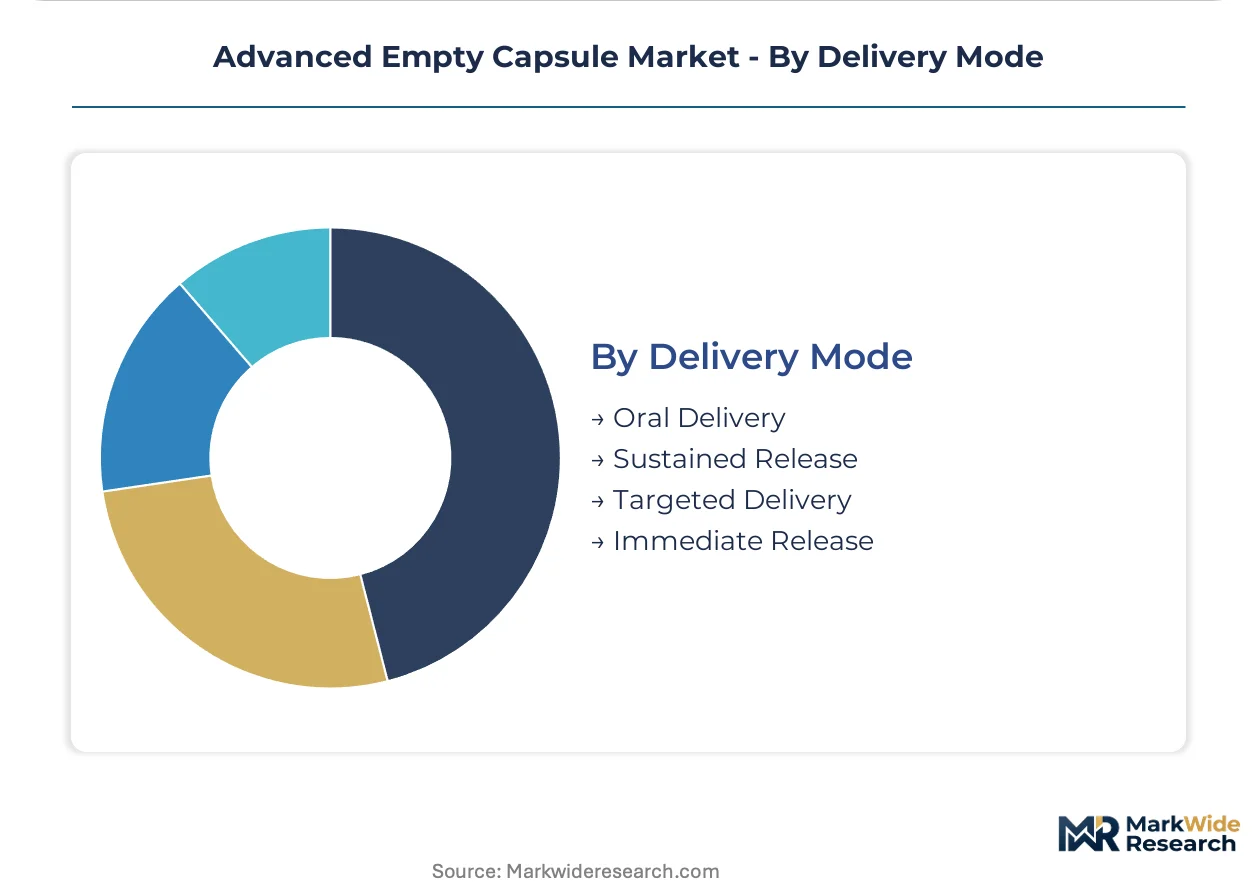
Delivery Mode:
Release kinetics and anatomical targeting requirements dictate polymer selection and coating technology investments.
- Targeted Delivery:Colon-specific and chronotherapeutic release profiles demand advanced enteric polymer systems and precision coating deposition. Southeast Asian CMOs in Indonesia and Vietnam are building dedicated capacity for Japanese export demand.
- Sustained Release:Extended API dissolution over 12-24 hours requires modified-release polymer matrices and controlled shell porosity engineering.
- Oral Delivery:Standard immediate-release capsules remain the default for bioavailable small molecules and routine supplement formulations.
- Immediate Release:Rapid dissolution shells prioritize disintegration speed for fast-acting analgesics and acute care medications.
Oral delivery maintains volume leadership; targeted delivery commands the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China dominate contract manufacturing volumes, while Switzerland and Germany concentrate specialty formulation innovation. Regulatory harmonization across these markets is compressing qualification timelines for export-oriented capsule suppliers.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts drive demand for pre-qualified Drug Master Files and validated dissolution profiles. FDA chemistry, manufacturing, and controls enforcement shapes supplier audit frequencies and documentation standards. The Boston-Cambridge biotech corridor anchors specialty capsule procurement for peptide and biologic oral formulations.
Germany
Nutraceutical brands in Bavaria and North Rhine-Westphalia mandate HPMC specifications to capture vegan and religious-dietary consumer segments. EMA REACH migration testing protocols and MDR compliance obligations eliminate animal-derived excipient risks from supply chains. The Frankfurt-Rhine-Main pharma cluster concentrates clean-label capsule sourcing for European export markets.
India
Contract manufacturers in Maharashtra and Gujarat scale HPMC capsule lines to serve domestic and export pharmaceutical demand. CDSCO alignment with ICH stability guidelines accelerates US and EU registration timelines for local producers. The Hyderabad-Visakhapatnam corridor anchors integrated capsule-filling capacity for international generic drug clients.
Switzerland
Specialty pharmaceutical developers in Basel and Zurich pilot functional coated capsules for peptide oral delivery and 505(b)(2) regulatory pathways. Swissmedic standards for nitrosamine impurity thresholds shape polymer characterization requirements. The Basel biotech cluster concentrates enteric-coated probiotic formulation development for pediatric applications.
China
Domestic pharma output in Jiangsu and Zhejiang provinces scales gelatin and HPMC capsule production for ASEAN and Japanese export markets. NMPA stability guidelines and dual carbon goals pressure manufacturers toward bio-based plasticizer alternatives. The Suzhou-Wuxi pharmaceutical manufacturing belt anchors contract filling capacity for regional contract manufacturing organizations.
Advanced Empty Capsule Market Competitive Environment
Indian producers anchor one tier; Swiss and American specialists hold premium positioning through integrated supply chains and biologics-capsule convergence. The vendor base separates into three strategic tiers: large-scale integrated manufacturers with captive raw material sourcing, mid-tier regional converters serving domestic pharma networks, and niche specialists in functional coatings and modified-release polymer systems. Competitive moves concentrate on backward integration into HPMC polymer production and multi-year supply agreement lock-ins with audited suppliers.
Within the integrated manufacturing tier, Lonza Group and ACG exemplify divergent geographic anchoring strategies. Lonza occupies a position bridging biologics production and capsule supply chain integration. ACG represents Indian subcontinent concentration with dedicated vegetarian capsule line investments. Suheung sits within the specialized gelatin formulation archetype optimized for tropical distribution requirements. These three anchors illustrate how regional regulatory exposure and raw material access shape competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Suheung |
| Catalent |
| Lonza Group |
| Nitta Gelatin |
| Sirio Pharma |
| ACG |
| CapsCanada |
| Associated Capsules |
| Roquette Frères |
| Others |
Value Chain & Pricing Dynamics
HPMC polymer feedstock costs flow from cellulose ether producers in China and Germany through three-tier pricing structures separating pre-qualified DMF holders from regional converters and spot-market suppliers. Pharmaceutical-grade gelatin pricing anchors the economy tier while vegetarian shell premiums reflect EMA REACH compliance investments and nitrosamine screening capabilities.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard gelatin capsules while compressing margins for mid-tier converters lacking backward integration into HPMC polymer production. Three-tier pricing structure across premium, standard, and economy levels separates FDA-audited suppliers with validated dissolution profiles from CDSCO-registered regional players and unqualified spot-market sources. Pricing pressure stems from HPMC raw material premiums running 40-60% above gelatin benchmarks. Contract manufacturers exhibit highest price sensitivity due to multi-site qualification burdens, while specialty pharmaceutical developers in Switzerland and Massachusetts absorb premiums for functional coated variants.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle large-scale volume commitments with locked multi-year agreements, while distributor networks serve mid-tier generic drug makers and nutraceutical brands. Raw material sourcing concentrates in Brazil and Argentina for bovine and porcine gelatin, with HPMC polymer production anchored in China and Germany. Capsule shell manufacturing clusters in India, China, and the United States feed global pharmaceutical and nutraceutical demand. Supply chain risk centers on livestock disease quarantine exposure in South American sourcing regions. Distribution runs through validated cold-chain logistics for moisture-sensitive HPMC inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Advanced Empty Capsule Market represents a late-cycle quality story as pharmaceutical procurement shifts decisively toward pre-qualified Drug Master Files and nitrosamine-screened polymer grades. Nutraceutical clean-label specifications are hardening across European and Asian buyer networks.
For Market Incumbents: Cement long-term supply agreements with audited contract manufacturers before CDSCO-ICH alignment completes across Indian export clusters. Lock in backward integration into HPMC polymer production to defend margin structures against 40-60% raw material premiums. Prioritize nitrosamine impurity screening capacity investments as EMA thresholds tighten.
For New Entrants and Emerging Players: Capture white-space in Southeast Asian contract manufacturing as Indonesian and Vietnamese CMOs build dedicated capsule filling capacity for Japanese export demand. Target functional coated probiotic delivery where acid-resistant polymer systems command premium positioning. Lead with rapid DMF qualification services for adaptive clinical trial sponsors.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap capsule converters with pre-qualified DMFs because pharmaceutical buyer consolidation is reducing supplier bases and locking out unqualified competitors. Focus on targets with validated dissolution profiles and EMA REACH compliance documentation. Watch EMA nitrosamine threshold announcements as inflection signals for polymer characterization capability scarcity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HPMC Polymer Production | Captures margin compression from 40-60% raw material premiums and secures supply certainty. |
| Pre-Qualified Drug Master File Investment | Unlocks multi-year pharmaceutical supply agreements with audit rights and volume commitments. |
| Nitrosamine Impurity Screening Capacity Buildout | Aligns with evolving EMA thresholds and accelerates excipient qualification timelines. |
| Functional Coating Technology Acquisition | Enables enteric and acid-resistant delivery for peptide and probiotic formulations. |
| Southeast Asian Manufacturing Footprint Expansion | Positions for Indonesian and Vietnamese CMO demand serving ASEAN and Japanese markets. |
Study Parameters
Direct dialogue with capsule manufacturing executives, pharmaceutical procurement directors, regulatory affairs leads at CDSCO and EMA, and nutraceutical brand managers grounded the qualitative foundation. Secondary validation drew from FDA Drug Master File databases, EMA submission records, CDSCO stability guideline publications, and REACH Article 33 substance disclosure filings. Bottom-up demand modeling across material chemistry, therapeutic application, and manufacturing scale segments triangulated with top-down market sizing.
Bottom-up volume projections tracked HPMC, gelatin, and functional coated capsule demand by pharmaceutical, nutraceutical, and clinical trial applications across the analysis window. Top-down constraints incorporated regulatory framework evolution, raw material supply concentration, and buyer consolidation patterns. CAGR derivation reflected segment-specific growth differentials between established gelatin volumes and accelerating vegetarian shell adoption.
Regulatory timeline acceleration, raw material supply disruption in South American sourcing regions, and pharmaceutical buyer consolidation beyond current trajectories are the dominant revision risks. Forecasts reflect assumptions about EMA nitrosamine threshold implementation and CDSCO-ICH alignment completion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market