
 India Plastic Packaging Film Market | 2026-2036
India Plastic Packaging Film Market Size, Share, and Industry Trends Forecast 2026-2036
India Plastic Packaging Film Market Insights
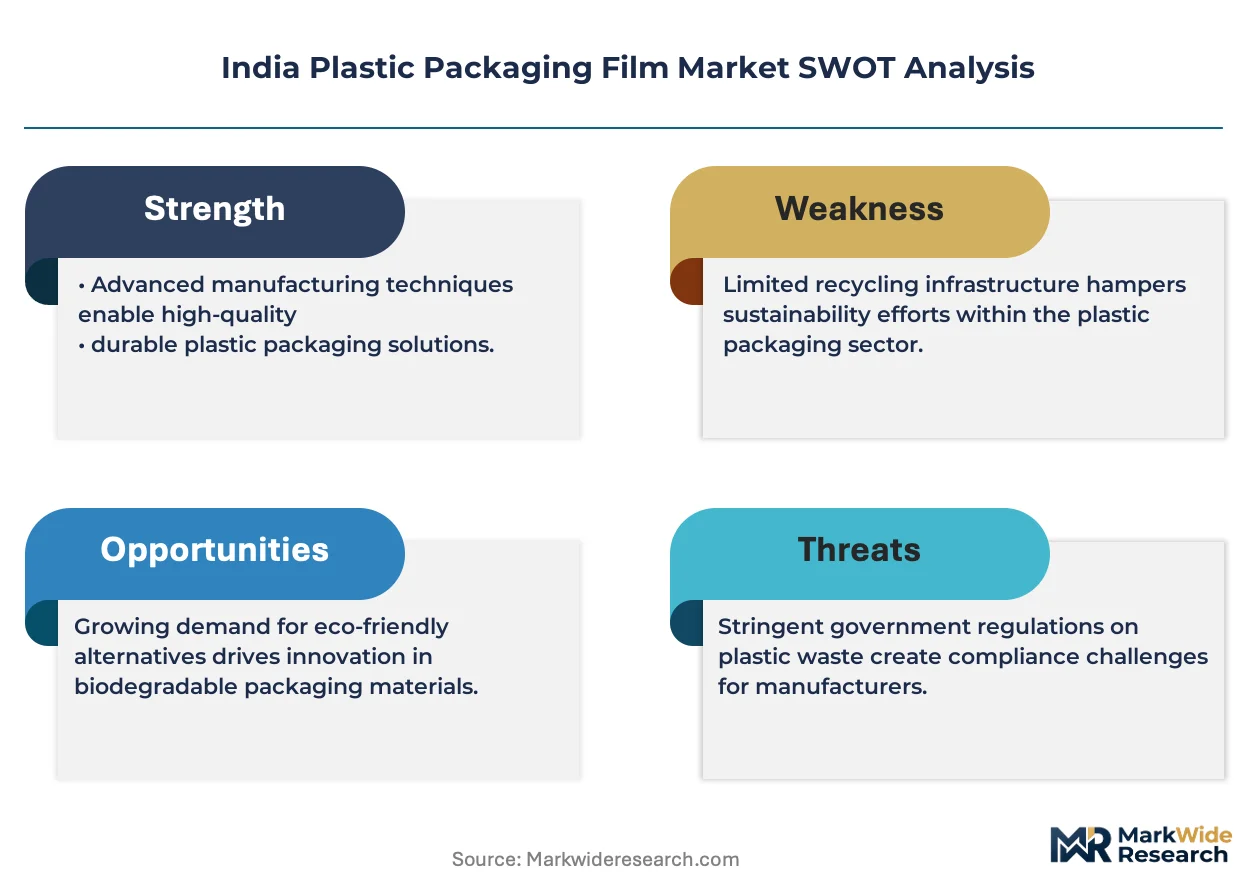
The Plastic Waste Management Rules is rebalancing capital allocation across the India Plastic Packaging Film Market. UFlex Limited leverages backward integration into resin compounding and metallization to sustain margin control amid EPR compliance costs. Jindal Poly Films anchors volume production of BOPET and BOPP substrates from its manufacturing base in Karnataka. SRF Limited specializes in specialty polyester films for pharmaceutical and industrial applications, competing on technical specifications rather than commodity throughput.
India plastic packaging film encompasses flexible substrates manufactured through extrusion, biaxial orientation, or cast processes, typically ranging from 8 to 150 microns in thickness, engineered for moisture barrier, oxygen resistance, or mechanical protection across consumer and industrial goods. The material dimension shows polyethylene and polypropylene commanding current volumes due to established supply chains and conversion economics, while biodegradable alternatives attract pilot investments as BIS certification pathways mature and brand EPR obligations tighten. Barrier films within the product type classification capture expanding pharmaceutical and processed food demand, whereas stretch films dominate logistics and palletization applications where load stability requirements govern specification.
BIS standards for food-contact plastics, CPCB's EPR enforcement mechanisms, and state-level plastic ban implementations across Maharashtra, Tamil Nadu, and Karnataka collectively reshape formulation choices and recycling infrastructure requirements for domestic producers. FSSAI compliance for direct food-contact applications adds a parallel certification burden that filters smaller converters from premium supply contracts. Stakeholders must monitor regulatory divergence between state plastic ban schedules and central EPR timelines, as misalignment creates operational complexity for national distribution networks.
Market Dynamics
Central Pollution Control Board enforcement of Extended Producer Responsibility obligations is compressing formulation choices and forcing converters toward certified recyclable structures, reshaping capital deployment across Maharashtra and Gujarat processing clusters.
Growth Catalysts
- EPR Mandate Compliance:CPCB enforcement timelines accelerate investment in mono-material barrier films that simplify mechanical recycling, pulling converters away from multi-layer laminates.
- Food-Contact Certification Expansion:FSSAI compliance requirements for direct-contact applications filter smaller competitors from premium supply contracts, concentrating volume among certified processors.
- Pharmaceutical Packaging Demand:Specialty polyester films for blister packs and sachets capture expanding domestic drug manufacturing, with barrier specifications tightening across CDSCO-regulated facilities.
Market Restraints
- Resin Price Volatility:Polyethylene and polypropylene input costs fluctuate with naphtha-linked import parity, squeezing margin stability for non-integrated converters lacking captive compounding.
- Recycling Infrastructure Gaps:Post-consumer film collection and reprocessing capacity concentrates in western India, leaving southern and eastern converters dependent on fragmented waste supply chains.
- Biodegradable Performance Limitations:PLA and starch-blend alternatives fail oxygen barrier specifications for retort applications, blocking substitution in high-value processed food segments.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments in Gujarat create pathways for mixed-film waste streams currently rejected by mechanical recyclers.
- E-Commerce Logistics Films:Stretch and shrink formats for palletization capture demand from quick-commerce fulfillment centers expanding across Tier-2 cities.
- PLI Scheme Incentives:Government production-linked incentives for specialty chemicals and advanced materials subsidize capital equipment for barrier coating lines.
Industry Challenges
- Multi-Layer Delamination Expertise:Separating incompatible polymers in post-consumer laminates requires solvent-based or thermal processes that few domestic recyclers have operationalized at scale.
- BIS Certification Timelines:Food-contact testing protocols and migration studies extend product launch cycles by 8-12 months, delaying revenue recognition for new formulations.
- Legacy Extruder Retrofitting:Converting cast lines to handle bio-based resins with different melt rheology demands capital outlays that mid-tier processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plastic Packaging Film Market |
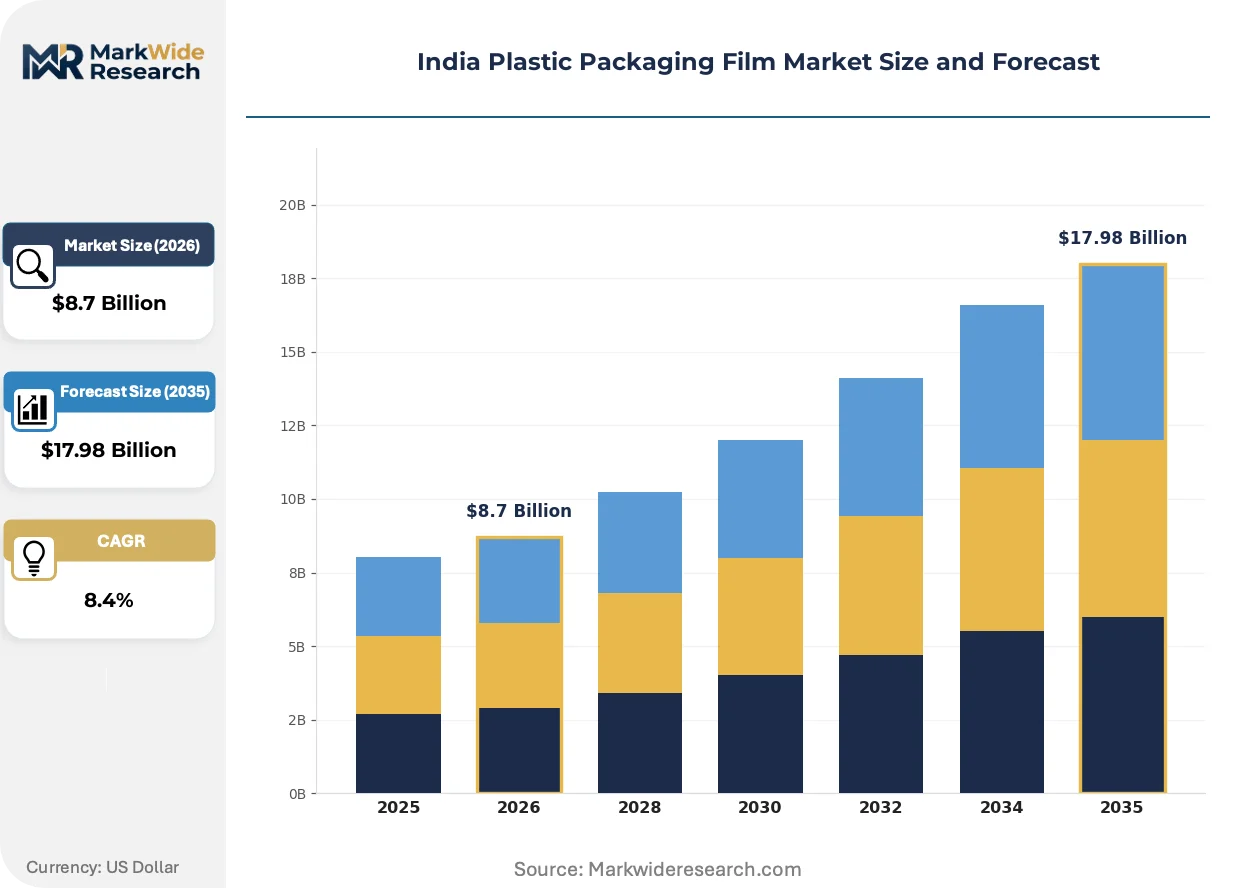
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Rigid Film End User: Food and Beverage, Pharmaceuticals, Personal Care, Electronics Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Biodegradable Application: Packaging, Labeling, Wrapping, Textile |
| Companies Covered | UFlex Limited, Cosmo Films Limited, Jindal Poly Films, Manjushree Technopack Limited, SRF Limited, Polyplex Corporation Limited, Supreme Industries Limited, Ecoplast Ltd, Chiripal Poly Films Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plastic Packaging Film Market Trends and Innovations
Active developments across material science, regulatory compliance architecture, and procurement systems are compressing product lifecycles and rewiring supplier-buyer relationships throughout the value chain.
Mono-material barrier structures are modularizing flexible packaging design by replacing aluminum foil and PET laminates with metallized BOPP or EVOH-coated PE substrates that maintain oxygen transmission rates below 0.5 cc/m²/day. Pharmaceutical and snack food processors in Maharashtra are piloting these structures at commercial volumes. The technology is modularizing converter equipment requirements, enabling single-extruder lines to produce film grades previously demanding coextrusion or lamination investments.
CPCB's 2024 amendments to Plastic Waste Management Rules tighten EPR target trajectories and mandate traceability documentation through centralized digital portals. Domestic brand owners must now demonstrate verifiable recycling of 50% of introduced rigid and flexible packaging by 2025, up from 30% under prior schedules. Food and beverage multinationals with pan-India distribution are responding by consolidating supplier bases to converters with certified recycling partnerships in Gujarat and Karnataka.
Brand technical audits of converter facilities are replacing certificate-based supplier qualification, with Nestlé, ITC, and Hindustan Unilever deploying dedicated packaging engineers to assess extrusion hygiene, migration control, and waste segregation protocols. This behavior compresses procurement cycles for qualified suppliers while extending vendor development timelines for uncertified competitors. The shift is most visible in western India, where polymer processing clusters enable same-day technical site visits from major FMCG headquarters.
India Plastic Packaging Film Market Segmentation
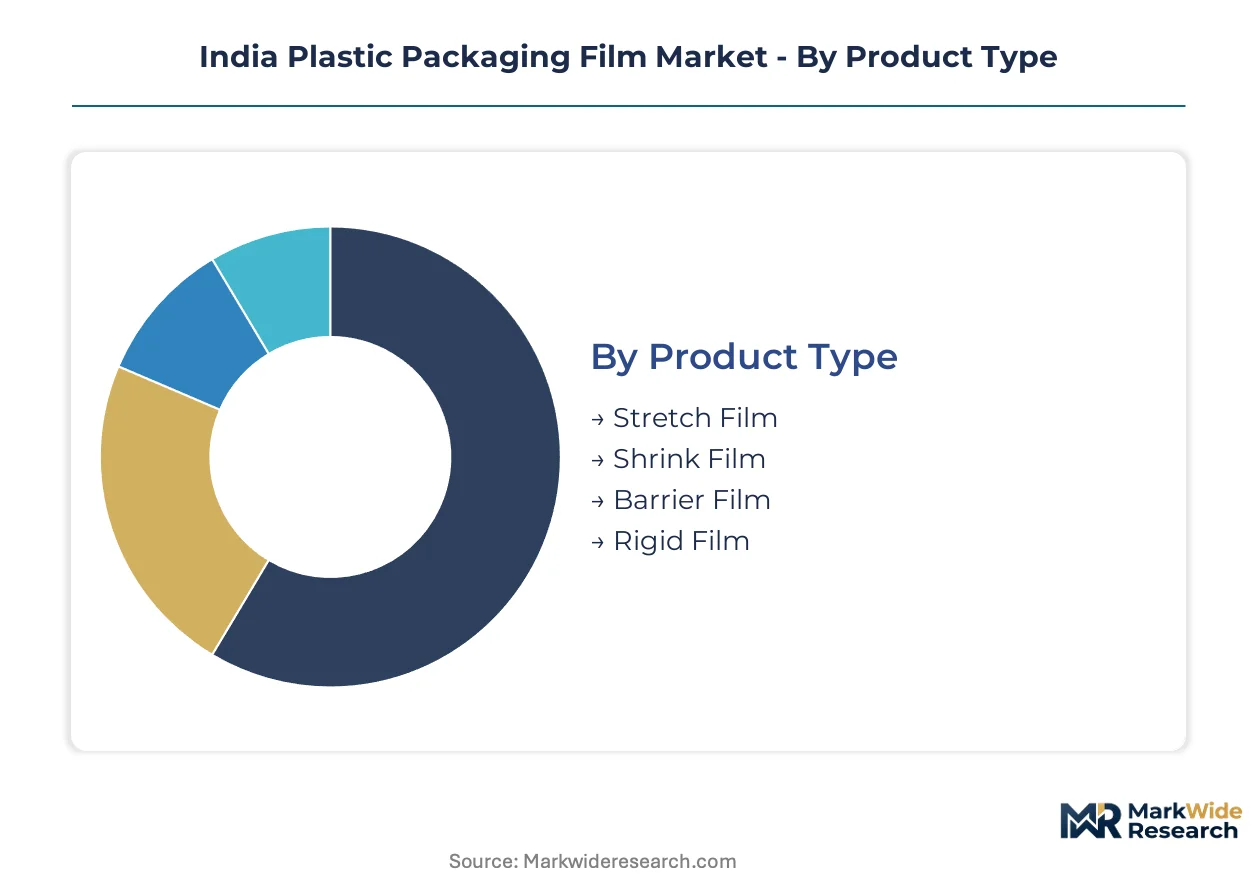
Segmentation in the India Plastic Packaging Film Market reveals how converters balance commodity scale against specialty margins. Each dimension—product format, end-use requirements, material chemistry, and application function—imposes distinct certification burdens and capital intensity thresholds that filter competitor participation.
Product Type:
Standardization dominates stretch and shrink formats where gauge tolerance governs pricing, while barrier films demand customized coextrusion or metallization investments that concentrate among integrated processors.
- Barrier Film:Multi-layer or metallized structures engineered for oxygen transmission below 0.5 cc/m²/day serve pharmaceutical blister packs and retort food pouches. Maharashtra processors capture premium contracts from FSSAI-certified drug manufacturers facing CDSCO packaging mandates.
- Stretch Film:Linear low-density polyethylene cast or blown films ranging 12-35 microns wrap palletized loads for logistics networks. Quick-commerce fulfillment centers in Bengaluru and Hyderabad drive specification tightening for load stability at reduced gauge.
- Shrink Film:Biaxially oriented polyolefin or PVC formulations contract uniformly around bundled consumer goods; beverage multipacks and personal care kits in Gujarat processing clusters represent core demand.
- Rigid Film:Thermoformable PET or PP sheets convert into trays and containers for ready-meal segments; airline catering and institutional food service in Delhi-NCR anchor volume.
Leading the category by volume: Stretch Film. Growing fastest: Barrier Film.
End User:
Customer concentration varies sharply—FMCG majors consolidate supplier bases for audit efficiency while pharmaceutical and electronics segments fragment across specialized converters.
- Food and Beverage:Processed snacks, dairy, and ready-to-eat meals demand oxygen and moisture barriers with FSSAI migration compliance. Nestlé, ITC, and Hindustan Unilever technical audits filter uncertified converters from western India supply chains.
- Pharmaceuticals:Blister lidding, sachet laminates, and strip packaging for domestic drug manufacturing require CDSCO facility approvals and traceable raw material documentation.
- Personal Care:Sachets and flexible pouches for shampoo, conditioner, and skincare sachetization in rural distribution favor cost-optimized mono-PE structures.
- Electronics:Anti-static films and moisture barrier bags protect components through humidity-exposed supply chains; Tamil Nadu semiconductor assembly plants specify ESD-controlled formats.
Dominating procurement scale: Food and Beverage. Expanding most quickly: Pharmaceuticals.
Material:
Supply security and EPR recyclability now outweigh pure conversion economics in material selection, favoring mono-polymer structures over legacy multi-material laminates.
- Polyethylene:LDPE, LLDPE, and HDPE grades command flexible packaging volumes through established polymer import parity and mechanical recycling infrastructure concentration in Gujarat.
- Polypropylene:BOPP and cast PP films deliver stiffness and clarity for snack food lamination; biaxial orientation lines in Karnataka and Maharashtra supply national converters.
- Polyvinyl Chloride:Shrink sleeve and blister applications persist despite EPR compliance friction; pharmaceutical lidding maintains PVC demand where barrier specifications resist substitution.
- Biodegradable:PLA and starch-blend pilot volumes target single-use bans in Maharashtra and Tamil Nadu, though oxygen barrier failures block retort food adoption.
Volume leader: Polyethylene. Steepest expansion trajectory: Biodegradable.
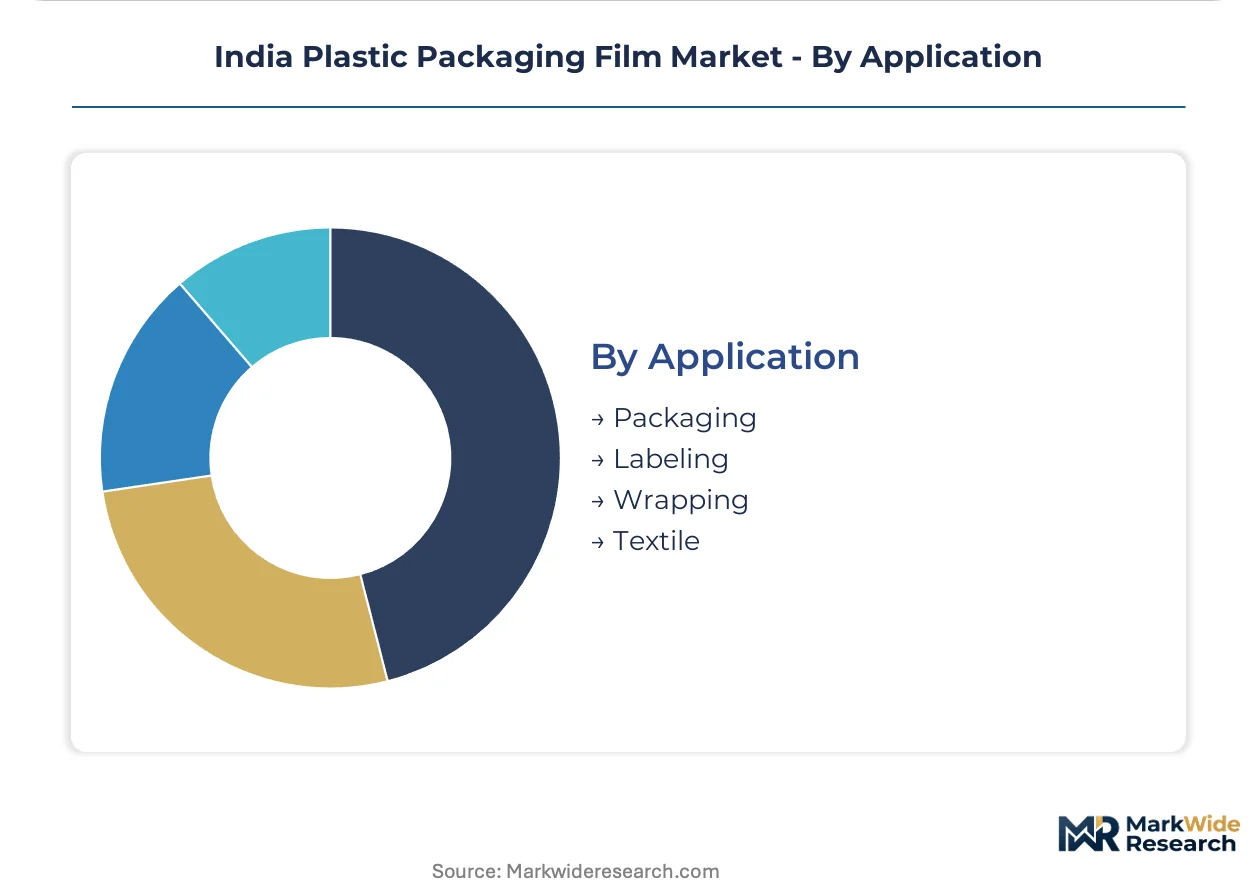
Application:
Functional differentiation separates commodity wrapping from value-added labeling and technical textile coatings, with margin structure inverting the apparent simplicity of each use case.
- Packaging:Primary and secondary flexible containment for consumer goods spans lidding, pouches, and form-fill-seal webs; EPR traceability requirements now penetrate this largest application segment.
- Labeling:Pressure-sensitive and in-mold label films demand optical clarity and print adhesion; beverage and personal care brand owners in Mumbai and Ahmedabad drive specification.
- Wrapping:Industrial and agricultural stretch formats for palletization and silage represent volume throughput with thin margin profiles dependent on resin cost timing.
- Textile:Release films for composite manufacturing and protective interleaving for fabric shipment command technical specifications that filter commodity converters.
Application commanding greatest tonnage: Packaging. Gaining share fastest: Labeling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer processing clusters concentrate in western India, where Maharashtra and Gujarat host the densest converting infrastructure and benefit from proximity to petrochemical feedstock and port access for resin imports.
Maharashtra
Food and beverage processors in Mumbai and Pune drive specification tightening for barrier films with FSSAI migration compliance. The state's 2018 plastic ban implementation predated central EPR mandates, creating early compliance experience among local converters. Thane-Bhiwandi industrial corridors anchor stretch film production for quick-commerce fulfillment networks expanding across western India.
Gujarat
Petrochemical integration from Dahej and Hazira supply chains supports cost-competitive PE and PP film extrusion for national distribution. CPCB-registered EPR facilitators cluster in Ahmedabad and Vadodara, enabling traceability documentation that brand owners require for 2025 compliance targets. Chemical recycling pilot investments in Sanand target mixed-film waste streams rejected by mechanical recyclers.
Karnataka
Biaxial orientation lines in Bengaluru and Mysuru supply BOPET and BOPP substrates for pharmaceutical blister packaging facing CDSCO facility approvals. The state's semiconductor assembly plants in Electronics City specify anti-static films with ESD control for component protection. Bengaluru quick-commerce hubs drive demand for reduced-gauge stretch films with load stability certification.
Tamil Nadu
Pharmaceutical manufacturing in Chennai and Coimbatore sustains specialty polyester film demand for strip packaging and sachet laminates. State-level plastic ban enforcement in Chennai municipal limits accelerates biodegradable pilot programs, though oxygen barrier limitations block retort food adoption. Sriperumbudur electronics corridors anchor anti-static film consumption for export-oriented component assembly.
Delhi-NCR
Airline catering and institutional food service in Gurgaon and Noida anchor rigid film demand for thermoformed trays. The region's position as northern distribution hub concentrates secondary packaging film consumption for FMCG brands serving Punjab and Haryana markets. NCR-based converters face operational complexity from Delhi's intermittent plastic ban enforcement overlapping with central EPR timelines.
India Plastic Packaging Film Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Integrated resin-to-film processors command margin stability against converters dependent on spot resin purchases. Three archetypes dominate: backward-integrated petrochemical players, specialty barrier film technologists, and commodity scale operators serving logistics applications. Competitive moves concentrate on recycling partnership certifications and mono-material barrier line investments.
Among India-based integrated processors, UFlex Limited exemplifies the resin-compounding archetype with metallization capabilities, while Jindal Poly Films anchors volume production of oriented substrates from its Karnataka manufacturing base. SRF Limited occupies a position within specialty polyester films for pharmaceutical applications, competing on technical specifications rather than commodity throughput.
| Leading Market Players |
|---|
| UFlex Limited |
| Cosmo Films Limited |
| Jindal Poly Films |
| Manjushree Technopack Limited |
| SRF Limited |
| Polyplex Corporation Limited |
| Supreme Industries Limited |
| Ecoplast Ltd |
| Chiripal Poly Films Limited |
| Others |
Pricing and Supply Chain Analysis
CPCB Extended Producer Responsibility enforcement gates qualified supply and premium-tier pricing access for converters serving Nestlé, ITC, and Hindustan Unilever. Brand technical audits filter uncertified processors from western India supply chains, compressing procurement cycles for compliant suppliers while extending vendor development timelines for competitors lacking recycling partnerships in Gujarat.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers with premium rates for short lead times and discounts for spot inventory. Price differentiation hinges on FSSAI certification grade and volume scale, with certified barrier film converters commanding sustained premiums while commodity stretch film processors face margin compression from naphtha-linked resin volatility. Quick-commerce fulfillment centers in Bengaluru and Hyderabad exhibit highest price sensitivity for reduced-gauge logistics films, whereas pharmaceutical blister pack specifications show lowest sensitivity due to CDSCO-mandated barrier performance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Saudi Arabia and South Korea for naphtha-derived polyethylene and polypropylene feedstock. Raw material dependencies center on LLDPE resin, metallized BOPP substrates, and EVOH barrier coatings. Tariff exposure on polymer imports creates margin instability for non-integrated converters lacking captive compounding. Distribution runs through Maharashtra and Gujarat processing clusters with secondary routing to Bengaluru and Chennai for pharmaceutical and electronics end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material barrier structures are displacing multi-layer laminates across pharmaceutical and processed food packaging, compressing product lifecycles for legacy coextrusion equipment.
For Market Incumbents: To counter chemical recycling scale-up by Gujarat-based competitors, anchor position through backward integration into resin compounding and metallization capabilities. Prioritize EPR facilitator certifications in Ahmedabad and Vadodara to maintain access to Nestlé and Hindustan Unilever procurement pools. Accelerate mono-material barrier line investments ahead of CPCB's tightened traceability documentation mandates. For New Entrants and Emerging Players: Enter via biodegradable pilot programs targeting Maharashtra and Tamil Nadu state-level plastic ban enforcement, where oxygen barrier limitations in PLA and starch-blend alternatives create white-space for compostable non-retort applications. Focus on quick-commerce stretch film specifications for Tier-2 city fulfillment centers where reduced-gauge load stability certification remains underpenetrated. Pursue co-development partnerships with Karnataka semiconductor assembly plants for ESD-controlled anti-static formats. For Investors and Strategic Acquirers: CPCB's 2024 amendments tightening EPR target trajectories is the leading indicator that recycling infrastructure consolidation will accelerate across western India. Position for 5-10 year viability through acquisition of mid-tier converters with established BIS certification pathways and Gujarat-based EPR partnerships. Monitor chemical recycling pilot investment announcements in Sanand as the inflection signal for mixed-film waste stream valorization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive LLDPE supply insulates margin from naphtha import parity volatility for Maharashtra processors. |
| Mono-Material Barrier Line Investment | Single-extruder metallized BOPP output replaces aluminum-PET laminates for FSSAI-certified drug manufacturers. |
| EPR Facilitator Partnership Certification | CPCB-registered traceability documentation unlocks Nestlé and ITC supplier consolidation in Gujarat. |
| Chemical Recycling Scale-Up | Pyrolysis investments in Sanand create pathways for mixed-film waste rejected by mechanical recyclers. |
| Biodegradable Pilot Program Launch | PLA and starch-blend trials target Maharashtra single-use bans despite retort oxygen barrier limitations. |
Research Methodology
Independent corroboration across plant managers at polymer processing facilities, procurement leads at FMCG brand owners, distribution channel partners in western India, and technical R&D directors at barrier film converters underwrites the qualitative findings. Secondary validation drew from BIS certification databases, CPCB EPR registration portals, FSSAI migration study publications, and customs records of polyethylene and polypropylene resin imports. Bottom-up capacity assessments at Maharashtra and Gujarat extrusion facilities triangulated against top-down demand estimates from food and beverage, pharmaceutical, and electronics end-use segments.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift effects and pricing trajectory. Segmentation modeling incorporated product type, end user, material chemistry, and application function dimensions with regional production hub differentiation. CAGRs derived from historical polymer consumption patterns, converter capacity utilization rates, and brand owner packaging specification surveys. Industry-specific inputs included CDSCO facility approval timelines for pharmaceutical packaging and quick-commerce fulfillment center expansion rates across Tier-2 cities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt state-level plastic ban enforcement diverging from central EPR timelines. Forecasts reflect assumptions regarding BIS certification pathway maturation, chemical recycling pilot scale-up economics, and biodegradable resin performance improvement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polypropylene Packaging Films Market
Poly film
PCR Lidding Films Market
Poly film
Shrink Bundling Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
PP Laminating Films Market
Poly film
LDPE Films Market
Poly film
Bopet Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Global Fluoropolymer Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
North America Polyimide Films Market
Poly film
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market
Poly film
Blown Film Extruder Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Tube Laminating Films Market
Poly film
Co Extruded Films Market