
 North America Shrink and Stretch Film Market | 2026-2036
North America Shrink and Stretch Film Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shrink and Stretch Film Market Analytics
California's SB 54 extended producer responsibility mandate is shifting procurement criteria toward post-consumer recycled content across the North American flexible packaging value chain. Sigma Plastics Group leverages backward integration into resin compounding to secure supply continuity for high-performance stretch formulations. Berry Global Inc. anchors its position through manufacturing scale across multiple US states. Sealed Air Corporation differentiates via technology leadership in automated wrapping systems integrated with film supply.
Shrink and stretch films are polyolefin-based flexible packaging materials manufactured through cast or blown extrusion processes, with thicknesses typically ranging from twelve to one hundred fifty microns depending on load containment requirements. These films function primarily to unitize palletized goods, protect surfaces from moisture and abrasion, and stabilize products during transportation and storage. Stretch film dominates volume flows in pallet wrapping applications across food and beverage end users where throughput speed and load retention specifications drive procurement decisions. Shrink film commands premium positioning in consumer goods protective covers where optical clarity and seal integrity determine performance acceptance. Bioriented film represents the fastest-expanding category as electronics manufacturers demand enhanced puncture resistance for fragile component shipment.
The US EPA regulates recycled content claims under Green Guides enforcement while OSHA sets workplace exposure limits for resin handling in film extrusion facilities. State regulators in California and New York impose additional reporting burdens through extended producer responsibility frameworks that affect material sourcing decisions. Canadian authorities under Health Canada and Environment and Climate Change Canada administer parallel chemical substance assessments that influence cross-border product formulations. Stakeholders must monitor evolving state-level packaging fees and recycled-content thresholds that will determine competitive compliance costs across the North American manufacturing footprint.
Market Dynamics
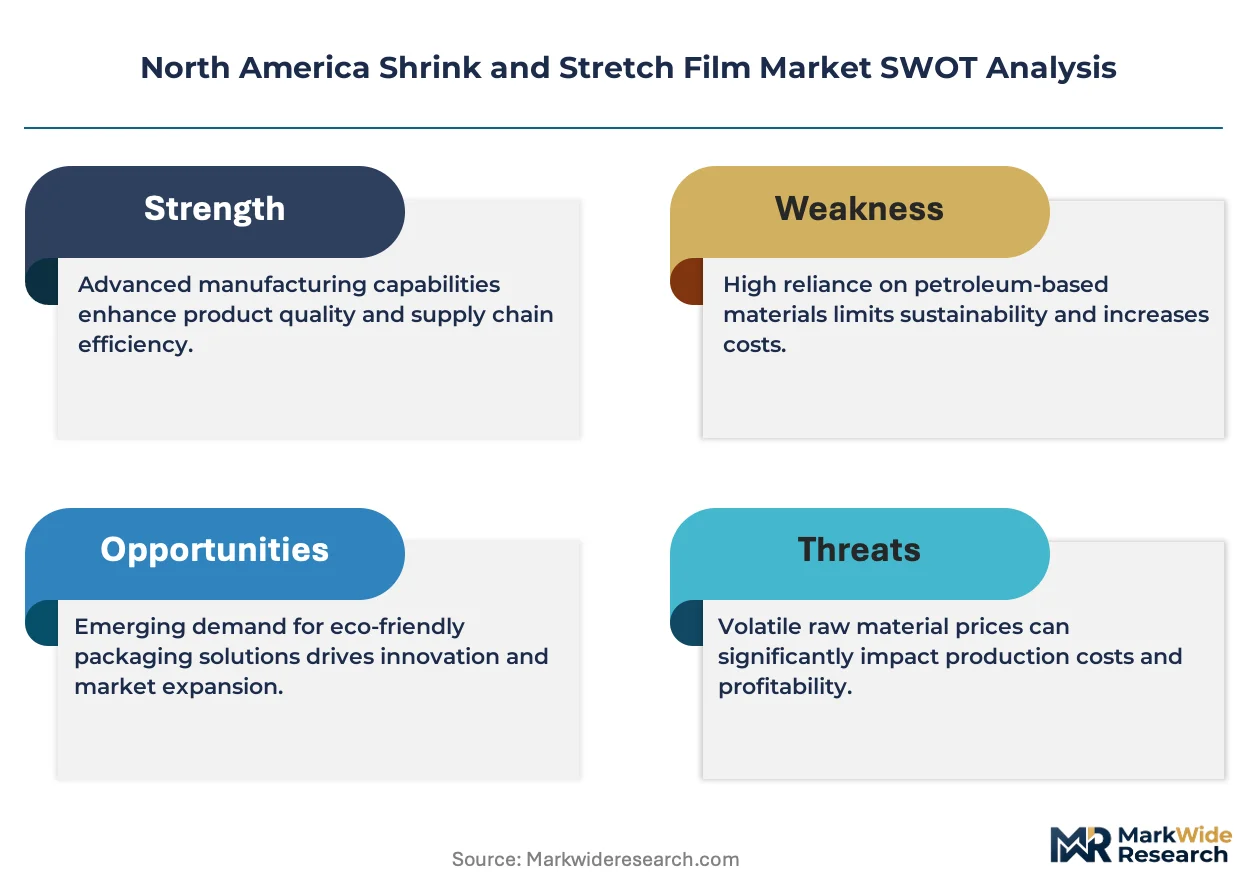
E-commerce fulfillment networks are reconfiguring film demand patterns as automated pallet-wrapping systems impose stricter performance specifications on stretch film elasticity and tear propagation resistance.
Growth Catalysts
- California SB 54 mandates:Extended producer responsibility frameworks are compelling brand owners to specify post-consumer recycled content in flexible packaging procurement contracts.
- Polymer processing clusters:Concentrated resin compounding capacity in Texas and the US Southeast is shortening lead times for regional distribution networks serving food and beverage manufacturers.
- Bioriented film technology:Electronics manufacturers are adopting puncture-resistant formulations for fragile component shipment, expanding addressable applications beyond traditional pallet unitization.
Market Restraints
- Ethylene feedstock volatility:Crude oil price fluctuations transmit directly to polyethylene resin costs, compressing margin stability for extrusion operators without backward integration into resin production.
- Single-supplier concentration:Regional markets dependent on Gulf Coast polymer production face hurricane-season supply interruption risks that propagate through distribution networks.
- Mechanical recycling limitations:Contamination from multi-layer film structures degrades reprocessed resin quality, constraining closed-loop material flows under EPA Green Guides enforcement.
Strategic Opportunities
- Mexico nearshoring expansion:Automotive and appliance manufacturers relocating assembly capacity to northern Mexico are creating demand for cross-border film supply chains with bilingual technical service support.
- Chemical recycling scale-up:Pyrolysis and depolymerization investments are enabling food-contact compliance for recycled content films previously excluded from sensitive applications.
- Automated wrapping convergence:Integration of machine vision with stretch wrapping equipment is generating demand for films with calibrated cling and consistent gauge profiles.
Industry Challenges
- Extrusion technician scarcity:Blown film production requires specialized knowledge of bubble stability and gauge control that retiring workforces are not replenishing through vocational pipelines.
- OSHA resin handling compliance:Workplace exposure limit enforcement demands capital expenditure on ventilation and personal protective equipment that smaller extruders struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shrink and Stretch Film Market |
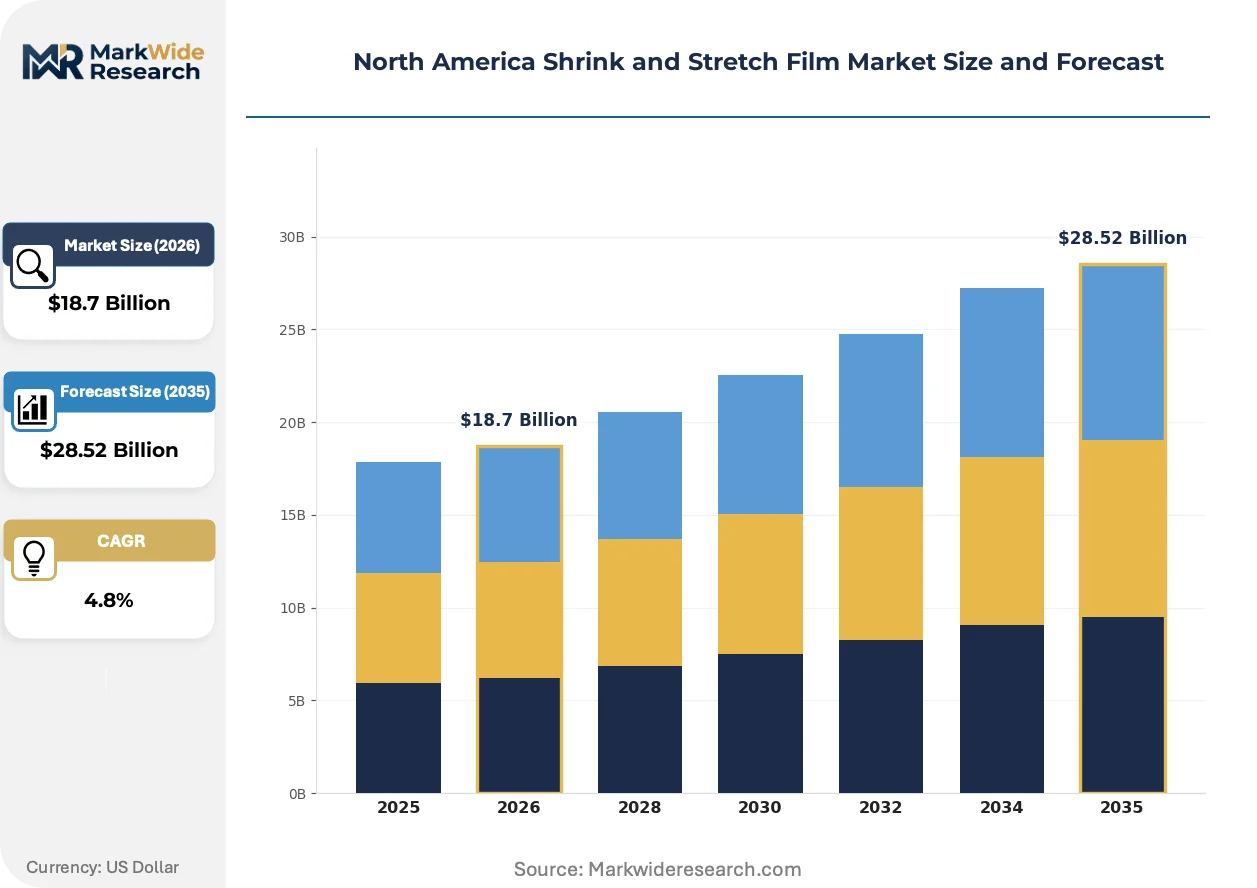
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Shrink Film, Stretch Film, Bioriented Film, Polyethylene Film Application: Packaging, Pallet Wrapping, Protective Covers, Bundling End User: Food & Beverage, Consumer Goods, Electronics, Pharmaceuticals Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | Sigma Plastics Group, Amcor Group GmbH, Sealed Air Corporation, Klöckner Pentaplast Group, Coveris Holdings S.A., Berry Global Inc., Intertape Polymer Group Inc., Paragon Films, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shrink and Stretch Film Market Evolving Landscape
Material science advances and regulatory compliance automation are converging to redefine performance benchmarks and sourcing criteria across the flexible packaging value chain.
Downgauging through multi-layer coextrusion is decentralizing film consumption patterns by enabling equivalent load containment at reduced material weights. Food and beverage distributors are adopting 12-micron high-performance formulations for standard pallet loads previously requiring 20-micron films. This technology is decentralizing volume concentration away from commodity-grade producers toward specialists with metallized barrier and nano-layer capabilities.
EPA Green Guides enforcement is tightening substantiation requirements for recycled content claims in flexible packaging marketing. Brand owners must now maintain chain-of-custody documentation that traces post-consumer material through reprocessing and extrusion stages. Consumer goods segments with premium positioning are most affected, with several major retailers now requiring third-party certification of environmental claims before contract renewal.
Consolidated buying through national distribution agreements is compressing supplier margins while demanding enhanced technical service support. Regional film distributors are losing share to direct manufacturer relationships as large e-commerce fulfillment operators centralize procurement across multi-state warehouse networks. This pattern is most visible in the US Southeast, where Amazon, Walmart, and Target have established dense fulfillment footprints with standardized wrapping protocols.
North America Shrink and Stretch Film Market Segmentation
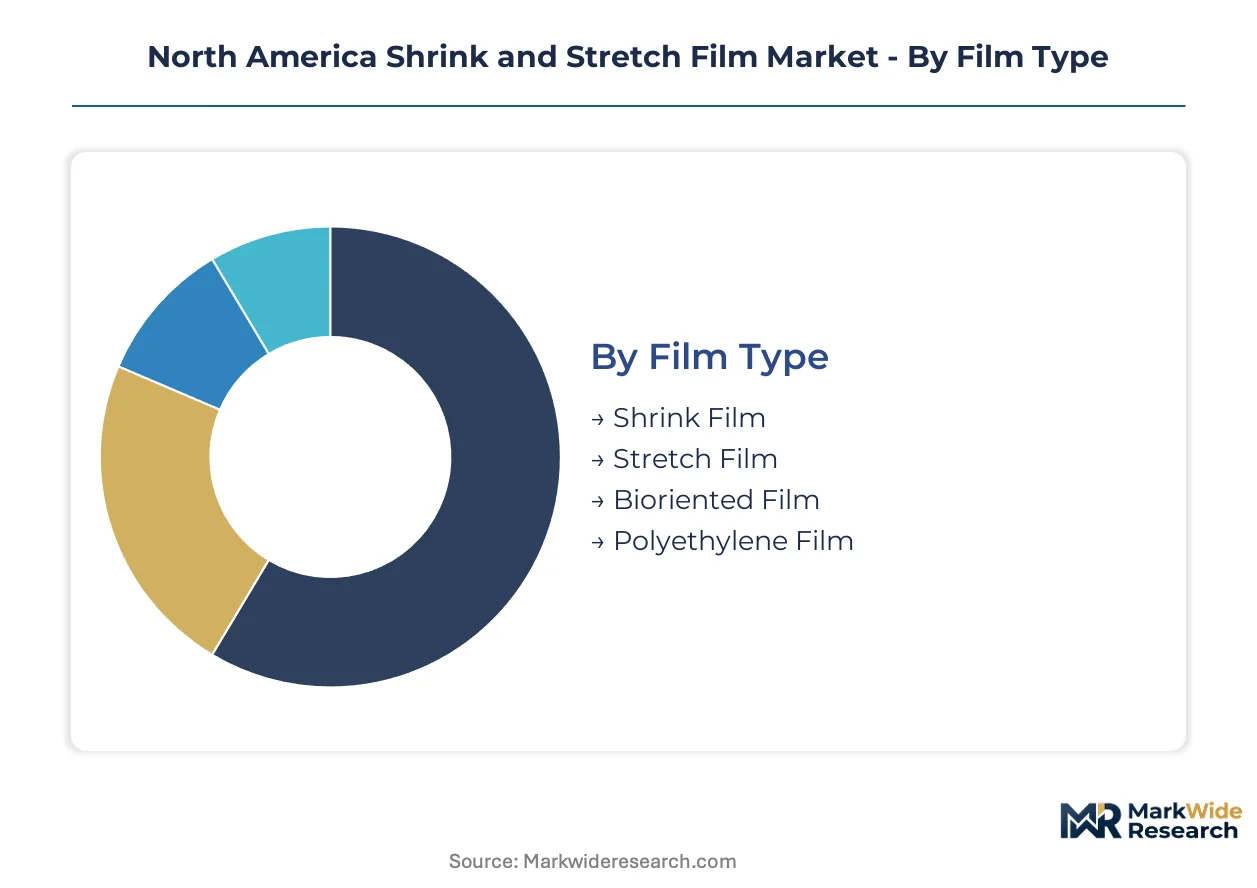
Segmentation in shrink and stretch film markets reveals how resin compounding geography and end-use performance requirements partition value capture. Procurement patterns diverge sharply between commodity pallet wrap and specialized protective applications.
Film Type:
Resin compounding capacity concentrates in Texas and Louisiana Gulf Coast clusters, with blown and cast extrusion lines positioned to minimize freight costs to regional distribution networks.
- Stretch Film:Linear low-density polyethylene formulations dominate pallet unitization with emphasis on cling properties and load retention force. Food and beverage distributors in the US Southeast specify machine-grade rolls for automated wrapping lines at high-throughput fulfillment centers. EPA Green Guides enforcement on recycled content claims is reshaping procurement contracts toward certified post-consumer formulations.
- Shrink Film:Cross-linked and non-cross-linked polyolefin grades provide optical clarity and seal integrity for consumer goods display packaging. Electronics manufacturers in California and Mexico border states drive demand for low-temperature shrink initiation to protect heat-sensitive components. State-level extended producer responsibility mandates in California and New York are accelerating specification of recyclable mono-material structures.
- Bioriented Film:Stretched in machine and transverse directions to enhance puncture resistance and tensile strength for fragile component shipment.
- Polyethylene Film:Commodity-grade low-density and linear low-density variants serve cost-sensitive bundling and temporary protective applications.
Stretch film absorbs the bulk of installed capacity; bioriented film is expanding most quickly.
Application:
Cost tier differentiation separates high-volume standardized wrapping from premium protective specifications requiring technical service support.
- Pallet Wrapping:Machine-applied stretch film secures unitized loads for transportation stability with calibrated pre-stretch ratios and cling balance. E-commerce fulfillment networks in Texas, Georgia, and Pennsylvania operate automated wrapping systems demanding consistent gauge profiles and low neck-down behavior. OSHA workplace exposure regulations for resin handling affect extrusion facility location decisions near these demand clusters.
- Packaging:Shrink film configurations include centerfold, single-wound, and pre-perforated formats for product bundling and retail display. Consumer goods brand owners facing California SB 54 compliance deadlines are rewriting supplier contracts to mandate post-consumer recycled content thresholds. Third-party certification of environmental claims has become a contract renewal requirement for premium positioning segments.
- Protective Covers:UV-stabilized and anti-static formulations shield industrial equipment and electronics during storage and transit.
- Bundling:Hand-wrap and machine-grade stretch configurations group smaller items for handling efficiency in retail distribution.
Pallet wrapping commands the greatest resin throughput; packaging applications are climbing the fastest as regulatory compliance reshapes material specifications.
End User:
Volume concentration in food and beverage processing creates procurement scale that compresses supplier margins while demanding technical service proximity.
- Food & Beverage:Stretch film palletization dominates inbound ingredient and outbound finished goods logistics with strict FDA food-contact compliance requirements. Midwest and Southeast processing clusters source film through direct manufacturer relationships to secure supply continuity. Multi-layer coextrusion downgauging is displacing heavier legacy formulations without sacrificing load containment performance.
- Electronics:Bioriented and anti-static films protect fragile components from electrostatic discharge and mechanical damage during cross-border shipment. Northern Mexico maquiladora operations create demand for bilingual technical service and just-in-time delivery coordination. Puncture resistance specifications exceed standard pallet wrap requirements by substantial margins.
- Consumer Goods:Optical clarity and printability drive shrink film selection for retail-ready packaging presentation.
- Pharmaceuticals:Cleanroom-compatible films with extractables and leachables documentation support secondary packaging of drug products.
Food and beverage absorbs the bulk of installed capacity; electronics is gaining share fastest as nearshoring expands manufacturing footprint.
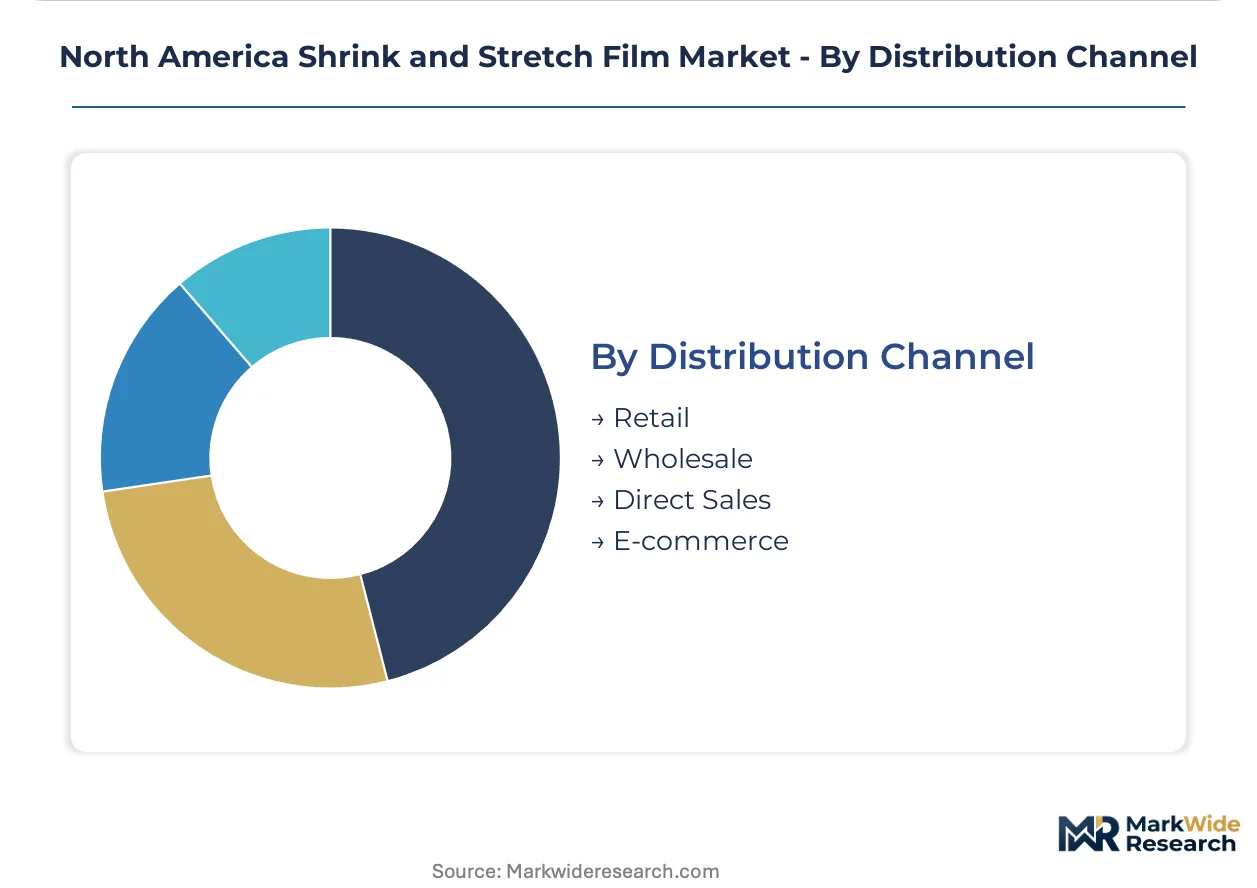
Distribution Channel:
Customer type stratification separates consolidated national buyers from fragmented regional accounts with diverging service requirements.
- Direct Sales:Large e-commerce and retail fulfillment operators negotiate national agreements with extrusion manufacturers for standardized specifications across multi-state warehouse networks. Amazon, Walmart, and Target procurement teams centralize stretch film buying to leverage volume scale. Technical service integration includes on-site wrapping equipment optimization and inventory management programs.
- Wholesale:Regional distributors serve mid-size food processors and manufacturing operations with mixed product portfolios and shorter lead time requirements. Texas and Southeast polymer processing clusters enable competitive positioning through freight cost advantages. Distributor margins face compression as direct manufacturer relationships capture share in top accounts.
- Retail:Small-format hand-wrap and specialty shrink film sales through industrial supply stores.
- E-commerce:Digital procurement platforms for standardized commodity grades with limited technical support.
Direct sales absorbs the bulk of volume concentration; wholesale is expanding most quickly among mid-tier processors seeking supply diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast polymer corridor anchors North American film production capacity, with resin compounding clusters in Houston and Beaumont feeding extrusion lines across the southern United States.
United States
E-commerce fulfillment centers in Georgia, Pennsylvania, and Texas drive machine-grade stretch film consumption for automated pallet wrapping. EPA Green Guides enforcement tightens substantiation requirements for recycled content claims in flexible packaging marketing. The Southeast industrial corridor from Atlanta to Charlotte hosts dense warehousing networks where Sigma Plastics Group and Berry Global Inc. maintain manufacturing proximity.
Canada
Cross-border automotive parts shipments from Ontario to Michigan and Ohio generate demand for puncture-resistant bioriented films. Health Canada and Environment and Climate Change Canada administer chemical substance assessments that influence product formulations for food-contact applications. The Windsor-Quebec City corridor concentrates stretch film consumption at tier-one automotive supplier facilities.
Mexico
Maquiladora operations in Nuevo León and Baja California nearshoring from US electronics brands create demand for anti-static protective films. Mexican environmental regulations under SEMARNAT increasingly align with California SB 54 extended producer responsibility frameworks. The Tijuana-Mexicali border zone anchors electronics assembly clusters requiring just-in-time film delivery coordination.
North America Shrink and Stretch Film Market Competitive Landscape
The competitive structure tilts toward scale-driven integrated producers with captive resin supply. Large extrusion operators with backward integration into polyethylene compounding command freight cost advantages to regional distribution networks. Two strategic archetypes dominate: Gulf Coast resin-integrated producers and multi-state manufacturing scale players. Competitive moves concentrate on capacity expansion in polymer processing clusters and direct sales relationships with national e-commerce fulfillment operators.
Among North American integrated producers, Sigma Plastics Group exemplifies the resin-backward archetype through compounding control, while Sealed Air Corporation occupies a position emphasizing automated wrapping system integration. Berry Global Inc. represents multi-state manufacturing scale across diverse US locations. These three anchors illustrate how supply continuity and technical service proximity determine competitive positioning in fulfillment network procurement.
| Leading Market Players |
|---|
| Sigma Plastics Group |
| Amcor Group GmbH |
| Sealed Air Corporation |
| Klöckner Pentaplast Group |
| Coveris Holdings S.A. |
| Berry Global Inc. |
| Intertape Polymer Group Inc. |
| Paragon Films |
| Dow Inc. |
| Others |
Value Network & Pricing Analysis
National e-commerce fulfillment operators with consolidated multi-state procurement contracts dictate value-based pricing anchored to automated wrapping system throughput and load retention performance. Their volume concentration forces suppliers to price against measurable outcomes rather than resin input costs alone.
Pricing Analysis
Throughput-based pricing anchors stretch film valuation to pallet-wrapping speed and load stability metrics rather than per-pound resin equivalence. Three-tier pricing structure across premium certified-recycled, standard machine-grade, and economy hand-wrap levels separates compliance-grade formulations from commodity alternatives. Cost compression in standard grades intensifies as Gulf Coast resin-integrated producers leverage captive polyethylene supply. Food and beverage distributors exhibit highest price sensitivity due to thin logistics margins, while electronics manufacturers prioritize puncture resistance over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Georgia, and Pennsylvania operate hub-and-spoke patterns feeding automated fulfillment networks with just-in-time film replenishment. Manufacturing concentrates in the United States Gulf Coast, with compounding clusters in Texas and Louisiana anchoring extrusion capacity. Raw material flows draw from ethylene crackers, linear low-density polyethylene resin, and post-consumer recycled flake feedstocks. Hurricane-season disruption risk threatens single-source Gulf Coast polymer production. Distribution runs through direct manufacturer relationships with national accounts and wholesale distributors serving regional processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California SB 54 mandates erect a cost-of-compliance barrier that rewards early investment in post-consumer recycled content certification while marginalizing smaller extruders lacking chain-of-custody documentation capabilities.
For Market Incumbents: Hedge against resin price volatility through backward integration into polyethylene compounding or long-term offtake agreements with Gulf Coast crackers. Defend market position by accelerating chemical recycling partnerships to secure food-contact compliant recycled content ahead of state-level threshold escalations. Capacity expansion in Mexico border states captures nearshoring electronics demand while reducing freight exposure to hurricane disruptions. For New Entrants and Emerging Players: Capture share in mid-tier food processors bypassed by direct sales teams of integrated producers, offering bilingual technical service and flexible minimum order quantities. White-space concentrates in northern Mexico maquiladora corridors where anti-static film demand outpaces established supplier presence. Lead with certified post-consumer recycled formulations to differentiate against legacy commodity producers in California and New York compliance-driven procurement. For Investors and Strategic Acquirers: The window for entry favors resin-integrated regional specialists with captive compounding capacity and established direct relationships with e-commerce fulfillment networks. Long-term viability hinges on chemical recycling infrastructure positioning ahead of EPA Green Guides enforcement tightening. Watch for state-level packaging fee escalations as the inflection signal separating compliant from non-compliant asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates margin stability against ethylene feedstock volatility from crude oil fluctuations. |
| Chemical Recycling Scale-Up | Pyrolysis investments enable food-contact compliance for recycled content films previously excluded from sensitive applications. |
| Mexico Manufacturing Footprint Expansion | Proximity to Nuevo León electronics clusters reduces freight costs and enables just-in-time delivery coordination. |
| Automated Wrapping System Integration | Machine vision compatibility requirements generate demand for films with calibrated cling and consistent gauge profiles. |
| Post-Consumer Recycled Content Certification | Third-party chain-of-custody documentation satisfies California SB 54 mandates for extended producer responsibility compliance. |
Research Methodology
Independent corroboration across extrusion plant managers, procurement leads at food and beverage distributors, polymer chemists at resin compounding facilities, and technical directors at automated wrapping equipment manufacturers underwrites the qualitative findings. Primary interviews with regional wholesale distributors and e-commerce fulfillment network operators combined with secondary validation from EPA enforcement records, OSHA workplace exposure filings, state-level extended producer responsibility regulatory texts, and customs trade data for polyethylene resin imports. Bottom-up capacity estimates from identified extrusion lines triangulate against top-down consumption models derived from end-use sector demand analysis.
Comparable-period anchoring to historical resin price cycles and fulfillment center construction permitting data establishes the forecast window baseline. Segmentation modeling spans film type, application, end-user industry, and distribution channel dimensions across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating downgauging technology diffusion and regulatory compliance cost pass-through assumptions. Forecast inputs include ethylene cracker operating rates, e-commerce warehouse square footage expansion, and state-level recycled content threshold schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hurricane disruption frequency, chemical recycling yield rates, and California SB 54 enforcement escalation. The analysis reflects assumptions about polymer processing cluster resilience and nearshoring momentum continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PVC Cling Film Market
Poly film
Starch-Based Plastic Films Market
Poly film
Wrap Around Label Films Market
Poly film
France Plastic Packaging Films Market
Poly film
APET Film Market
Poly film
Waste Wrap Film Market
Poly film
Shrink Bundling Films Market
Poly film
Polyethylene Cast Film Market
Poly film
Easy Peel Film Packaging Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Cellulose Film Packaging Market
Poly film
Peelable and Resealable Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Forming Films Market
Poly film
Polycarbonate Films Market
Poly film
MDO-PE Films Market