
 Global Cast Polypropylene Packaging Films Market | 2026-2036
Global Cast Polypropylene Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cast Polypropylene Packaging Films Market Foresight
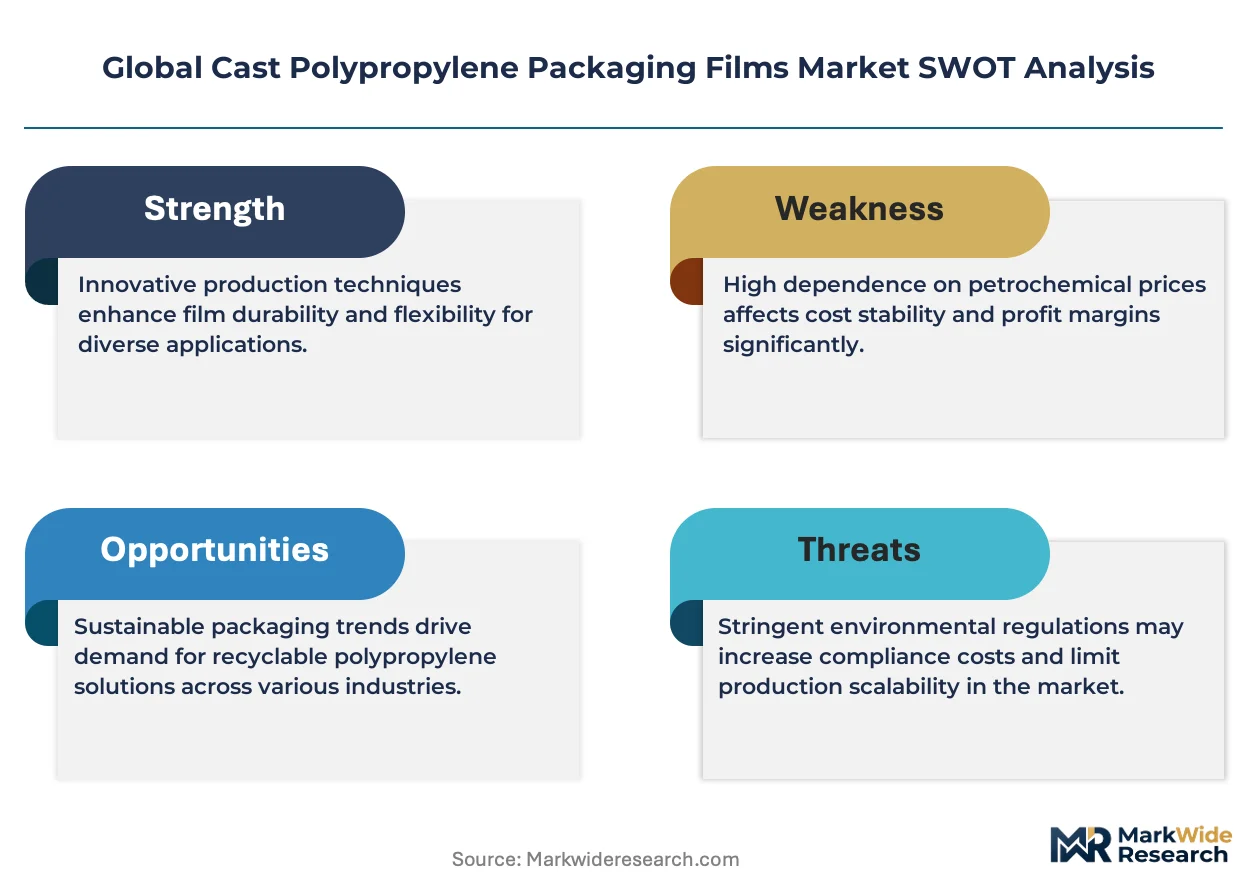
The EU Packaging and Packaging Waste Regulation is rebalancing procurement criteria across European food processors, forcing converters to certify mono-material recyclability in flexible formats. Uflex Ltd. anchors South Asian supply through backward integration into resin compounding and metallization. Taghleef Industries competes on certified circular film grades for premium snack and bakery clients. Jindal Poly Films Limited dominates domestic Indian demand with scale advantages in biaxial and coextruded lines.
Cast polypropylene packaging films are thermoplastic sheets extruded through a chill-roll casting process, typically ranging from 18 to 80 microns in thickness, engineered for clarity, heat sealability, and moisture barrier performance in flexible packaging. Biaxial films lead value capture due to balanced orientation delivering superior mechanical strength and printability for high-speed form-fill-seal operations. Metallized films occupy the fastest-expanding margin pool as brand owners substitute aluminum foil with vacuum-deposited CPP for lightweight barrier in snack and confectionery wraps. Coated films sustain steady pharmaceutical and electronics demand where specialized heat-seal or anti-fog chemistries command specification premiums.
FDA food contact regulations in the United States, REACH compliance obligations under ECHA in Europe, and BIS certification requirements in India collectively shape resin approval pathways, migration limits, and market access conditions for CPP film exporters. The EU Green Deal's packaging recyclability targets are accelerating converter qualification of mono-axial and embossed films designed for single-polymer recovery streams. Stakeholders must monitor evolving extended producer responsibility frameworks and resin certification costs to preserve margin structure across regional supply positions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to redesign multi-layer laminates into mono-material CPP formats, compressing qualification timelines and resin approval pathways across European supply chains.
Growth Catalysts
- EU Green Deal recyclability mandates:Mono-material CPP films now qualify for single-polymer recovery streams, unlocking preferential procurement from multinational food processors.
- India:Domestic flexible packaging consumption is outpacing installed film capacity, drawing imports and greenfield extrusion investments.
- Metallization technology:Vacuum-deposited aluminum layers on CPP substrates are displacing foil in snack and confectionery barrier applications.
Market Restraints
- Propylene feedstock volatility:Naphtha and propane price swings transmit directly to resin costs, squeezing converter margins.
- Supply concentration in Northeast Asia:Biaxial orientation line capacity clusters in China and South Korea, creating import dependency for regional converters.
- Technical limitation in high-temperature retort:CPP films lack the dimensional stability of PET for sterilizable pouch applications above 121°C.
Strategic Opportunities
- Indonesia and Vietnam:Underpenetrated flexible packaging markets in Southeast Asia offer first-mover positioning for metallized and coated CPP grades.
- Pharmaceutical blister lidding:Push-through foil replacement with high-barrier CPP is gaining traction in tropical markets.
- Extended producer responsibility frameworks:France and Germany are advancing eco-modulated fees that reward mono-material packaging adoption.
Industry Challenges
- Migration testing timelines:EFSA and FDA food contact approvals for novel resin additives now extend 18-24 months, delaying product launches.
- Coextrusion technician scarcity:Skilled operators for seven-layer cast lines are concentrated among legacy European and Japanese engineering firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cast Polypropylene Packaging Films Market |
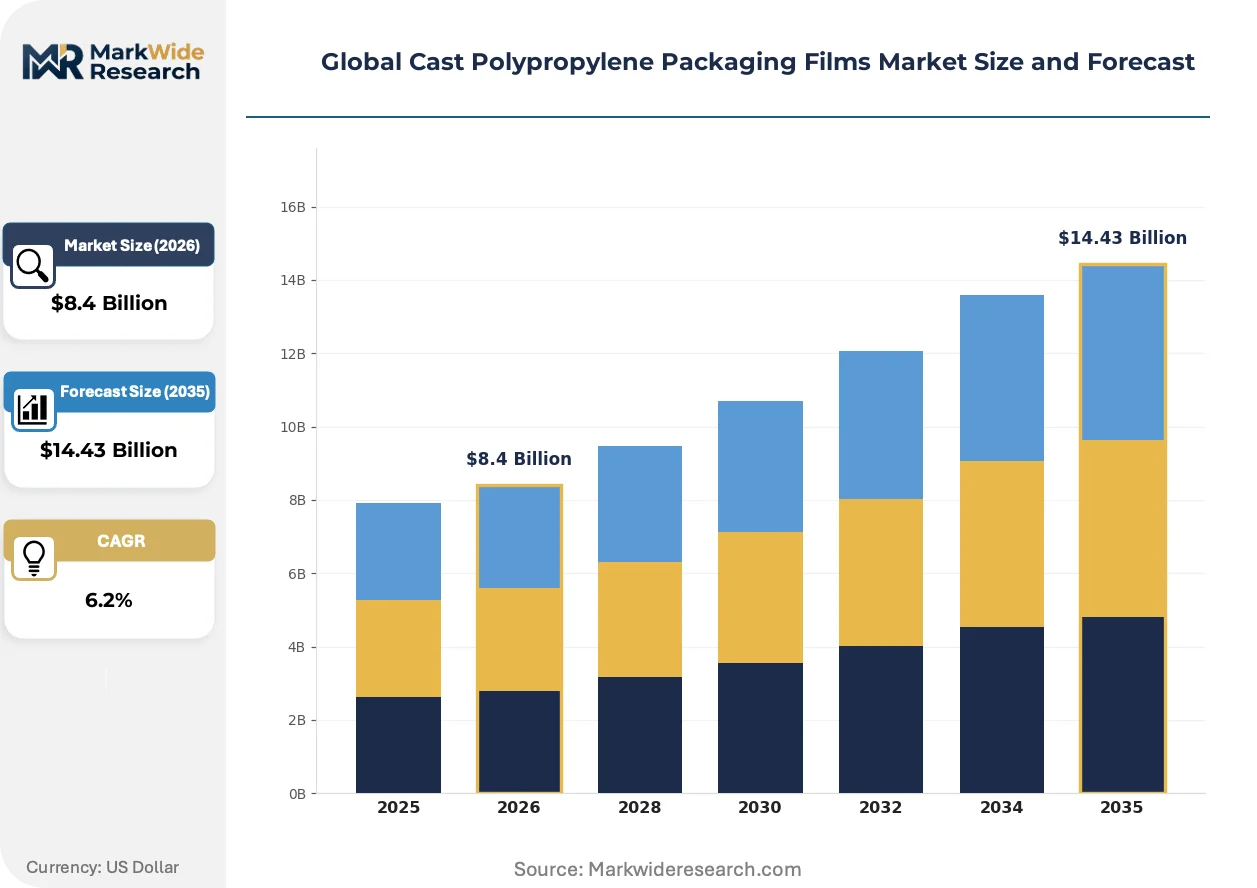
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoaxial Films, Biaxial Films, Coated Films, Metallized Films, Embossed Films, Antistatic Films Application: Food Packaging, Pharmaceutical Wrapping, Textile Protection, Industrial Packaging, Consumer Goods Covers, Agricultural Wraps Packaging Format: Rolls, Sheets, Pouches, Bags, Blister Packs, Vacuum Packs End User Industry: Personal Care, Electronics, Construction Materials, Paper Goods, Stationery, Home Furnishings |
| Companies Covered | Uflex Ltd., Oben Holding Group, Polyplex Corporation Limited, Copol International Ltd., Polinas, Taghleef Industries, American Profol, Inc., LC Packaging International BV, Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cast Polypropylene Packaging Films Market Shifts & Advancements
Active developments across material science, regulatory compliance, and buyer behavior are compressing product lifecycles and redefining competitive differentiation in flexible packaging films.
Water-based barrier coatings are expanding into high-moisture snack applications where ethylene vinyl alcohol coextrusions previously dominated. Tier-one confectionery brands in Germany and Switzerland are qualifying these formulations for 12-month shelf-life targets. The technology is expanding into premium chocolate and baked-goods segments previously reserved for aluminum-oxide metallized films.
REACH compliance obligations under ECHA are tightening migration limits for oligomers and additives in food-contact CPP. Converters must now document substance volumes above 0.1% w/w across the full polymer formulation. The regulatory burden falls heaviest on small and mid-size extruders serving private-label retail channels.
Brand-owner sustainability scorecards are compressing supplier qualification cycles from 24 months to 12 months. Major European dairy and meat processors now require third-party recyclability certification before contract award. The pattern is most pronounced in the Netherlands and Denmark, where retailer-led packaging pacts have created pooled procurement power.
Global Cast Polypropylene Packaging Films Market Segmentation
Cast polypropylene films differentiate through orientation chemistry, surface engineering, and barrier architecture. Procurement teams align specification tiers with line speed, shelf-life targets, and recovery stream requirements.
Product Type:
Orientation and surface treatment define mechanical performance, optical clarity, and seal integrity across converting lines.
- Biaxial Films:Balanced machine-direction and transverse orientation yield tensile strength above 150 MPa and dimensional stability for high-speed form-fill-seal equipment. European snack processors specify these grades for pillow-pack lines running above 200 cycles per minute.
- Metallized Films:Vacuum-deposited aluminum layers at 30-50 nm thickness deliver oxygen transmission rates below 0.5 cc/m²/day, displacing foil in confectionery and dried fruit laminates. Swiss and German chocolate brands drive qualification volumes.
- Monoaxial Films:Single-direction orientation prioritizes tear propagation resistance for twist-wrap confectionery.
- Coated Films:Acrylic or PVDC surface treatments enable heat-seal initiation at reduced jaw temperatures.
- Embossed Films:Textured surfaces improve machinability on vacuum thermoforming lines for cheese and processed meat.
- Antistatic Films:Migratory or permanent additive packages dissipate surface charge for electronics and pharmaceutical dust-sensitive filling.
Biaxial films lead on scale; metallized films lead on momentum.
Application:
End-use shelf-life demands and regulatory contact status reshape film specification priorities.
- Food Packaging:Moisture barrier, heat-seal latitude, and metal-detectable options dominate specification sheets for bakery, snack, and fresh produce. Indian retail chains are converting from rigid trays to flexible CPP pouches for dry pulses and spice blends.
- Pharmaceutical Wrapping:US FDA and EU EMA migration limits for oligomers and additives compress resin approval pathways. Tropical-market blister lidding applications are qualifying high-barrier metallized CPP as push-through foil alternatives.
- Textile Protection:Low-slip surfaces and UV stabilization protect garment shipments during extended container transit.
- Industrial Packaging:Heavy-gauge embossed grades cushion metal components and automotive parts.
- Consumer Goods Covers:Clarity and printability support retail display requirements for household durables.
- Agricultural Wraps:UV-stabilized grades with 12-24 month field life protect silage and greenhouse films.
Food packaging commands volume concentration; pharmaceutical wrapping climbs the fastest.
Packaging Format:
Converting equipment and distribution logistics determine dimensional and handling specifications.
- Rolls:Master rolls at 1000-3000 meter lengths feed downstream slitting and printing operations. Indian flexible packaging converters import jumbo rolls from South Korean and Chinese producers due to domestic biaxial line shortages.
- Pouches:Pre-formed stand-up and flat pouches demand precise thickness tolerance for zipper attachment and bottom gusset sealing.
- Sheets:Cut-to-size formats serve manual packaging operations in small-batch confectionery and artisanal food.
- Bags:Side-seal and bottom-seal configurations target bulk commodity and retail carry-out applications.
- Blister Packs:Thermoformable grades with deep-draw capability replace PVC in pharmaceutical and battery packaging.
- Vacuum Packs:Multilayer coextrusions with EVOH or PA tie layers achieve sub-1 cc/m²/day oxygen barrier for cured meat and cheese.
Rolls dominate upstream supply; pouches expand most quickly in downstream value-add.
End User Industry:
Surface sensitivity, chemical compatibility, and aesthetic requirements fragment demand across non-food sectors.
- Personal Care:Matte and soft-touch coated films differentiate premium shampoo and cosmetic sachets in Southeast Asian markets.
- Electronics:Antistatic and moisture barrier grades protect semiconductors and display components during cleanroom shipment.
- Construction Materials:UV-stabilized embossed films wrap insulation batts and membrane roofing for outdoor storage.
- Paper Goods:High-clarity overwrap preserves retail presentation for stationery and greeting card products.
- Stationery:Stiff monoaxial grades provide tear-resistant document and notebook covers.
- Home Furnishings:Low-slip surfaces prevent textile and upholstery abrasion during warehouse handling.
Personal care anchors non-food volume; electronics offers the steepest specification premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cast polypropylene film extrusion originated in post-war Germany and Japan, where chill-roll casting technology scaled through the 1960s before migrating to South Korea and China. Today production clusters span three continents with distinct regulatory and demand profiles.
Germany
Snack and bakery processors in Bavaria and Baden-Württemberg specify high-barrier metallized grades for 200+ cycle-per-minute form-fill-seal lines. The EU Green Deal's packaging recyclability targets force converters to certify mono-material CPP formats through ECHA-compliant migration testing. The Düsseldorf-Cologne corridor hosts compounding operations supplying embossed films for cheese thermoforming.
India
Domestic flexible packaging consumption for pulses and spice blends outpaces installed biaxial line capacity, drawing jumbo roll imports from South Korea. BIS certification requirements shape resin approval pathways for food-contact applications. The Mumbai-Pune industrial belt concentrates slitting and metallization operations serving retail chain private labels.
China
Guangdong and Zhejiang provinces cluster biaxial orientation line capacity serving export demand for electronics antistatic films. NMPA food contact regulations and GB standards govern oligomer migration limits for pharmaceutical wrapping grades. The Yangtze River Delta houses vacuum metallization facilities supplying Swiss chocolate brands.
United States
Midwest meat processors convert from rigid trays to flexible vacuum packs using coextruded CPP with EVOH tie layers. FDA food contact regulations and state-level extended producer responsibility frameworks in California and New York reshape procurement criteria. The Chicago-Detroit corridor anchors form-fill-seal equipment integration with film supply.
South Korea
Seoul-based converters export metallized barrier films to Southeast Asian snack markets where aluminum foil displacement accelerates. MFDS pharmaceutical packaging standards and corporate carbon neutrality pledges drive qualification of recyclable mono-material structures. The Busan-Ulsan industrial complex supplies masterbatch compounds for UV-stabilized agricultural wraps.
Global Cast Polypropylene Packaging Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and metallization capability, with the market consolidating around resin-compounding specialists and multi-territory film converters. Three strategic archetypes dominate: backward-integrated resin compounders with captive polymer supply, metallization specialists vacuum-depositing aluminum at nanometer precision, and regional scale players serving domestic flexible packaging demand. Competitive moves concentrate on capacity expansion in underpenetrated Southeast Asian markets and portfolio diversification into pharmaceutical-grade barrier films.
Among India-based integrated packaging groups, Uflex Ltd. and Jindal Poly Films Limited exemplify the backward-integration archetype through in-house resin compounding and metallization operations. Taghleef Industries occupies a position within the premium-tier specialist segment, while American Profol, Inc. represents North American regional scale production. Polyplex Corporation Limited and Oben Holding Group sit within the multi-territory converter tier serving cross-border snack and confectionery brands.
| Leading Market Players |
|---|
| Uflex Ltd. |
| Oben Holding Group |
| Polyplex Corporation Limited |
| Copol International Ltd. |
| Polinas |
| Taghleef Industries |
| American Profol, Inc. |
| LC Packaging International BV |
| Jindal Poly Films Limited |
| Others |
Supply & Pricing Matrix
EU Green Deal recyclability mandates are forcing snack and bakery processors to specify mono-material CPP formats, compelling converters to absorb resin certification costs and pass selective premiums through supply contracts while spot propylene volatility squeezes margin buffers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates metallized barrier grades from biaxial commodity films from monoaxial twist-wrap volumes. Price differentiation rests on ECHA-compliant migration certification and vacuum-deposition precision. Cost compression in standard-grade biaxial rolls is intensifying because South Korean and Chinese capacity expansions outpace Indian demand growth. Private-label retail chains exhibit highest price sensitivity; Swiss chocolate brands tolerate specification premiums for certified circular film grades.
Supply Chain Analysis
Direct-to-converter channels handle high-volume European snack processor demand, while distributor networks serve mid-size Indian flexible packaging converters lacking metallization capability. Manufacturing concentrates in China, South Korea, and Germany, with compounding operations clustered along the Yangtze River Delta and Busan-Ulsan corridor. Raw material sourcing draws from naphtha crackers in Northeast Asia and propane dehydrogenation units in the Middle East. Single-source vulnerability in biaxial orientation line engineering creates bottlenecks, as skilled technicians for seven-layer cast systems concentrate among legacy Japanese and European equipment suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: resin compounding and metallization investments in India capture cost advantages against European regulatory compliance burdens, while Southeast Asian demand growth outruns local extrusion capacity.
For Market Incumbents: Deepen backward integration into propylene resin compounding to buffer feedstock volatility and secure BIS certification pathways for Indian food-contact applications. Add biaxial orientation capacity in Maharashtra or Gujarat before South Korean import dependency hardens. Prioritize ECHA migration testing investments to defend premium positioning against emerging metallization specialists. For New Entrants and Emerging Players: Indonesian and Vietnamese snack processors lacking qualified local CPP supply represent the most penetrable buyer archetype. Enter through toll-metallization partnerships with Chinese substrate suppliers, then migrate to captive coating capability. Target pharmaceutical blister-lidding qualification in tropical markets where push-through foil substitution accelerates. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale metallization specialists holding EFSA pre-approvals and vacuum-deposition equipment transferable to mono-material barrier formats. Five-to-ten-year viability hinges on extended producer responsibility framework maturation in France and Germany. Watch for eco-modulated fee schedules as the inflection signal rewarding single-polymer packaging adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Uflex Ltd. and Jindal Poly Films Limited anchor Indian supply through captive polymer production, insulating margin from propylene volatility. |
| Metallization Capacity Expansion | Vacuum-deposition investments in the Yangtze River Delta serve Swiss and German chocolate brands displacing aluminum foil barriers. |
| Mono-Material Certification Investment | Taghleef Industries captures EU Green Deal procurement shifts through ECHA-compliant circular film grades for premium snack clients. |
| Southeast Asian Greenfield Extrusion | First-mover positioning in Indonesia and Vietnam accesses underpenetrated flexible packaging demand for metallized and coated CPP grades. |
| Pharmaceutical Barrier Qualification | High-barrier metallized CPP trials in tropical blister-lidding applications target MFDS and NMPA migration standards for foil substitution. |
Research Methodology
Direct dialogue with extrusion plant managers, flexible packaging procurement leads at European snack processors, metallization equipment engineers, and ECHA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from customs trade data, BIS certification registries, SEC filings of listed packaging groups, and EU Packaging and Packaging Waste Regulation impact assessments. Bottom-up capacity modeling across biaxial orientation lines combined with top-down demand triangulation from food processor converting rates.
Segment-level value outputs emerged from product-type splits across biaxial, metallized, and coated grades; application tiers spanning food packaging, pharmaceutical wrapping, and electronics protection; and regional production clusters in Germany, India, China, and South Korea. CAGRs were derived from installed capacity expansion schedules, resin price elasticity assumptions, and substitution elasticities between CPP and competing barrier substrates. Forecast inputs incorporated EU extended producer responsibility implementation timelines and Indian retail chain flexible packaging conversion rates.
Inputs from extruder operating rates and resin contract pricing were available through the study window; gaps in proprietary migration testing timelines and seven-layer line utilization rates introduce uncertainty bands around metallized film penetration assumptions. Forecasts reflect documented base-case assumptions regarding regulatory enforcement intensity and feedstock price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Japan Polypropylene Packaging Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Automotive Wrap Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Polystyrene Films Market
Poly film
Surface Printed Film Market
Poly film
PET Lidding Films Market
Poly film
India Plastic Packaging Film Market
Poly film
Global Specialty Films Polymer Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Lidding Films Market
Poly film
Global BOPP Films Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
Poly Coated Paper Market