
 Japan Polypropylene Packaging Films Market | 2026-2036
Japan Polypropylene Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Polypropylene Packaging Films Market Foresight
The widening performance gap between premium barrier films and commodity stretch wraps is repositioning procurement strategies across Japan's packaging value chain. Toray Industries, Inc. leverages its biaxial orientation expertise to dominate high-end pharmaceutical applications. Mitsui Chemicals Tohcello, Inc. anchors the industrial segment through integrated resin-to-film operations. Toyobo Co., Ltd. differentiates via specialized co-extrusion lines serving cosmetic brands with ultra-thin gauge solutions.
Japan polypropylene packaging films are thermoplastic polymer sheets, typically 8–50 microns thick, manufactured through cast, blown, or co-extrusion processes to deliver moisture resistance, optical clarity, and seal integrity for product protection. Barrier Films command premium positioning in pharmaceutical and fresh-food applications where oxygen transmission rates below 5 cc/m²/day justify higher unit economics. Co-extrusion Technology leads capacity investments as converters seek to consolidate multi-layer functionality into mono-material structures compatible with Japan's recycling infrastructure. Cast Technology sustains volume leadership in standard food wrapping where throughput speed outweighs specialized performance requirements.
METI's resource circulation policies and JIS standards for plastic packaging recyclability are tightening specifications on film composition, directly limiting multi-polymer laminate adoption in favor of pure PP streams. PMDA's pharmaceutical packaging guidelines enforce strict extractables and leachables testing, elevating compliance costs for barrier film suppliers serving drug manufacturers. Stakeholders must monitor how Osaka and Nagoya industrial clusters adapt conversion equipment to meet emerging mono-material mandates without sacrificing barrier performance.
Market Dynamics
METI's mono-material packaging mandates are compressing multi-layer laminate demand while forcing converters to redesign film architectures around pure polypropylene streams compatible with Japan's mechanical recycling infrastructure.
Growth Catalysts
- Barrier Performance Requirements:Pharmaceutical manufacturers in Osaka's manufacturing corridor are specifying oxygen transmission rates below 5 cc/m²/day for drug stability, pulling premium co-extruded films into chronic disease medication packaging.
- METI Resource Circulation Policies:The ministry's push for design-for-recyclability is redirecting R&D spending toward mono-material structures that eliminate adhesive lamination layers.
- Kanto Ready-to-Eat Meal Expansion:Food manufacturers in Tokyo's metropolitan zone are adopting high-clarity barrier films to extend chilled prepared food shelf life without modified atmosphere packaging equipment.
Market Restraints
- Propylene Feedstock Volatility:Naphtha-derived propylene monomer costs fluctuate with crude oil benchmarks, squeezing cast film margins in commodity food wrapping applications.
- Equipment Retrofit Burden:Co-extrusion line upgrades to handle mono-material barrier specifications require capital outlays that smaller converters in Nagoya's industrial belt cannot finance.
- Multi-Polymer Laminate Lock-In:Existing pharmaceutical packaging lines optimized for PET/PE/Al laminates face technical friction migrating to all-PP structures without validated barrier equivalence.
Strategic Opportunities
- Hokkaido Agricultural Export Corridor:Fresh produce shippers serving premium Asian markets are specifying vapor-deposited PP films for vacuum-packed seafood and dairy exports.
- PMDA Extractables Guidelines:Stricter pharmaceutical packaging validation requirements are creating compliance-based differentiation for film suppliers with dedicated cleanroom co-extrusion capacity.
- Cosmetic Sample Sachet Conversion:Beauty brands in Tokyo's Shibuya and Ginza districts are replacing multi-material sample pouches with ultra-thin gauge mono-PP alternatives for boutique retail distribution.
Industry Challenges
- Barrier-Recyclability Trade-Off Engineering:R&D teams must reconcile oxygen and moisture barrier performance with mono-material purity requirements without the crutch of ethylene vinyl alcohol copolymer layers.
- Cleanroom Validation Timelines:Pharmaceutical film qualification under PMDA guidelines extends new product introduction cycles by 18-24 months versus industrial applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Polypropylene Packaging Films Market |
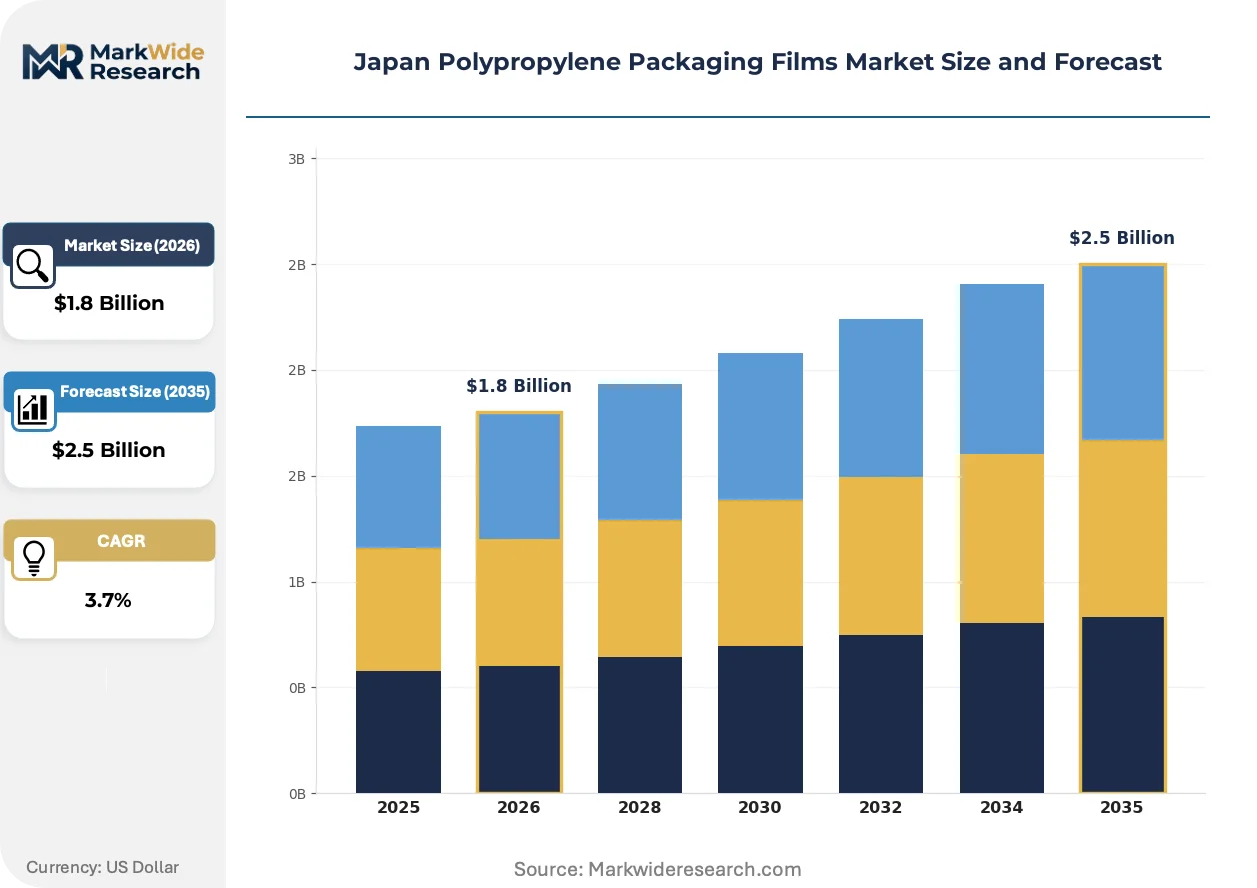
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Shrink Films, Protective Films, Barrier Films Application: Food Packaging, Pharmaceutical Packaging, Personal Care Packaging, Industrial Packaging End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, E-Commerce Retailers Technology: Cast Technology, Blown Technology, Co-extrusion Technology, Laminating Technology |
| Companies Covered | Toray Industries, Inc., Mitsui Chemicals Tohcello, Inc., Toyobo Co., Ltd., Futamura Chemical Co., Ltd., Toppan, Inc., Cosmo Films Ltd., Idemitsu Unitech Co., Ltd., Takigawa Corporation, Gunze Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Polypropylene Packaging Films Market Shifts & Advancements
Film architecture innovation centers on eliminating incompatible polymer layers while preserving functional performance. Three developments dominate converter investment priorities.
Co-extrusion with nano-layer distribution technology is overtaking conventional cast and blown methods for barrier-critical applications. Pharmaceutical packagers in Osaka and Tokyo are specifying 9-layer and 11-layer structures with cyclic olefin copolymer tie layers to achieve glass-like clarity with metal-level oxygen protection. This capability compression is marginalizing commodity cast film suppliers in standard food wrapping segments where barrier performance carries no price premium.
METI's 2030 plastic resource circulation targets are tightening JIS standards for packaging recyclability. The regulation forces elimination of polyethylene tie layers and adhesive laminations that contaminate PP recycling streams. Fresh food converters in Kanto and Kansai regions are responding by qualifying vapor-deposited silicon oxide coatings as barrier alternatives to aluminum metallization.
Buyers in Tokyo's pharmaceutical and cosmetic clusters are consolidating film procurement under single-source technical partnerships. Long-term supply agreements with embedded R&D collaboration are displacing spot purchasing through trading houses. This relationship compression is most visible among Osaka-based generic drug manufacturers seeking validated film supply chains with documented extractables profiles.
Japan Polypropylene Packaging Films Market Segmentation
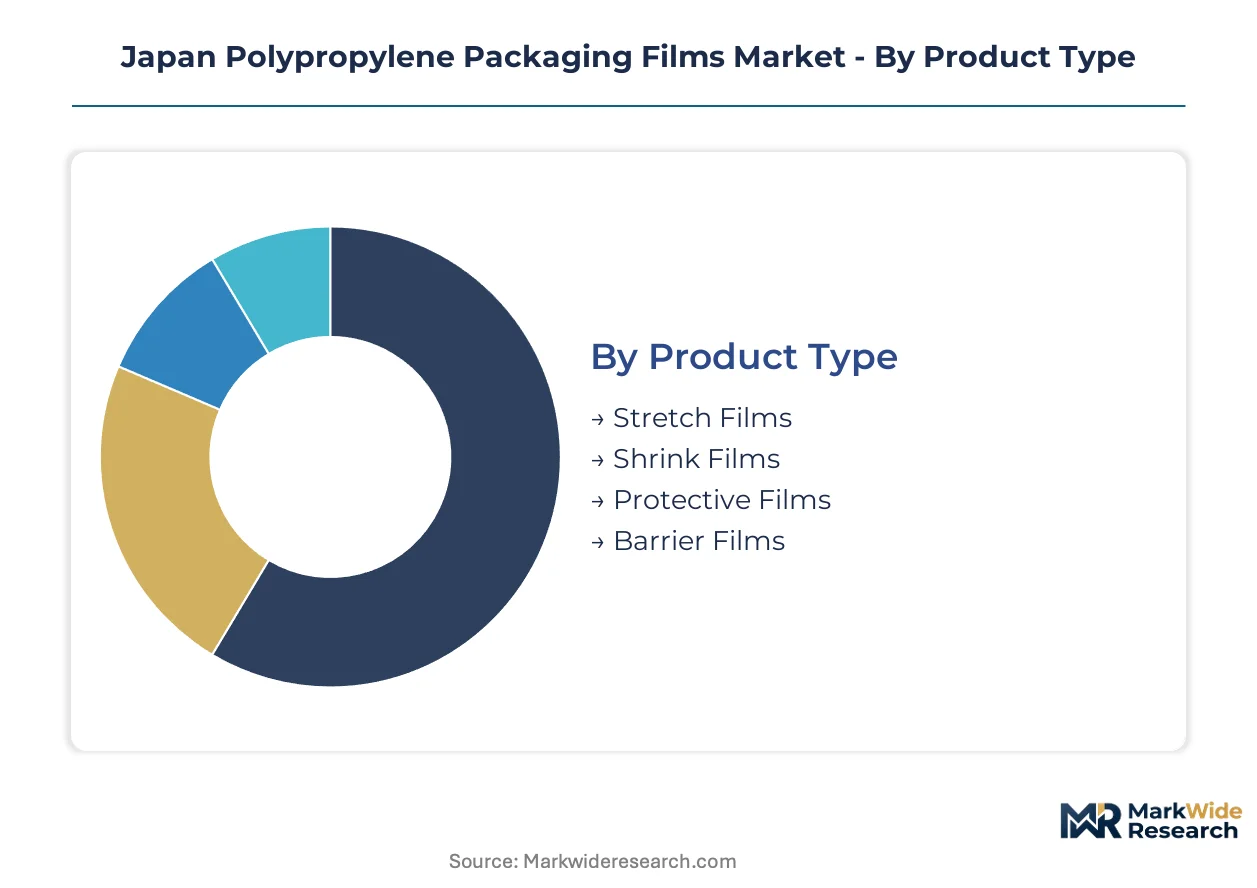
Film specification varies sharply across Japan's packaging value chain. Procurement teams segment requirements by barrier performance, regulatory compliance, and conversion equipment compatibility rather than commodity grade alone.
Product Type:
Capital intensity escalates dramatically from commodity wraps to precision barrier films, with vapor deposition and nano-layer co-extrusion lines demanding tenfold higher investment per ton of annual capacity.
- Barrier Films:Multi-layer co-extruded structures with oxygen transmission rates below 5 cc/m²/day dominate chronic disease medication packaging in Osaka's pharmaceutical corridor. METI's mono-material mandates are forcing redesign of these high-value films to eliminate polyethylene tie layers without sacrificing metal-level protection.
- Stretch Films:Linear low-density polyethylene blends and cast PP formulations wrap palletized loads across Nagoya's automotive parts distribution network. Margins compress when naphtha-derived propylene feedstock costs spike, yet volume throughput sustains converter economics.
- Shrink Films:Biaxially oriented PP with controlled crystallinity delivers printed label conformity for beverage multipacks in Tokyo's retail supply chain.
- Protective Films:Low-tack adhesive layers guard electronics surfaces and automotive panels during Kansai region assembly and export.
Stretch films absorb the bulk of installed capacity; barrier films are expanding most quickly.
Application:
Regulatory burden stratifies the application landscape, with pharmaceutical and food segments facing divergent compliance architectures.
- Pharmaceutical Packaging:PMDA extractables and leachables testing extends qualification timelines to 18-24 months. Osaka-based generic drug manufacturers now demand documented cleanroom production protocols and validated supply chains from film suppliers.
- Food Packaging:Kanto region ready-to-eat meal producers specify high-clarity barrier films to extend chilled shelf life without modified atmosphere equipment. METI's design-for-recyclability rules are disqualifying multi-polymer laminates from this segment.
- Personal Care Packaging:Tokyo's Shibuya and Ginza cosmetic brands are converting sample sachets from multi-material pouches to ultra-thin mono-PP alternatives.
- Industrial Packaging:Standard cast films protect machinery components and construction materials with minimal specification overhead.
Food packaging commands the largest volume position; pharmaceutical packaging carries the steepest expansion trajectory.
End User:
Customer scale and technical sophistication create distinct procurement patterns across buyer categories.
- Pharmaceutical Companies:Osaka's manufacturing corridor is consolidating film procurement under single-source partnerships with embedded R&D collaboration. Long-term agreements displace spot purchasing through trading houses.
- Food Manufacturers:Kanto region processors balance barrier performance against METI recyclability mandates, driving qualification of vapor-deposited silicon oxide coatings as aluminum alternatives.
- Cosmetic Brands:Boutique retail distribution in Tokyo demands ultra-thin gauge solutions with premium tactile and optical properties.
- E-Commerce Retailers:Protective and stretch film consumption scales with parcel volume through Osaka and Tokyo fulfillment centers.
Food manufacturers represent the largest addressable base; pharmaceutical companies are gaining share fastest.
Technology:
Process selection locks converters into specific performance tiers and retrofit costs.
- Co-extrusion Technology:9-layer and 11-layer lines with cyclic olefin copolymer tie layers achieve glass-like clarity with pharmaceutical-grade barrier protection. Equipment upgrades to handle mono-material specifications require capital outlays that marginalize smaller Nagoya belt converters.
- Cast Technology:High-speed throughput dominates standard food wrapping where barrier performance carries no price premium. This process sustains volume leadership despite thinner margins.
- Blown Technology:Tubular quenching delivers balanced orientation for shrink film applications in beverage and retail packaging.
- Laminating Technology:Adhesive-based multi-polymer bonding faces technical friction under METI's resource circulation targets; converters are decommissioning lines or retooling for thermal lamination of compatible PP layers.
Cast technology holds the greatest installed base; co-extrusion technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka's pharmaceutical manufacturing corridor anchors Japan's polypropylene packaging films demand through chronic disease medication packaging and PMDA-mandated barrier specifications.
Kanto/Tokyo
Ready-to-eat meal producers in Tokyo's metropolitan zone specify high-clarity barrier films for chilled prepared foods. METI's design-for-recyclability rules disqualify multi-polymer laminates from this segment. Food manufacturers in Saitama and Chiba prefectures are qualifying vapor-deposited silicon oxide coatings as aluminum metallization alternatives.
Kansai/Osaka
Generic drug manufacturers in Osaka's manufacturing corridor demand oxygen transmission rates below 5 cc/m²/day for medication stability. PMDA extractables and leachables testing extends qualification timelines to 18-24 months. Pharmaceutical companies are consolidating film procurement under single-source technical partnerships with embedded R&D collaboration.
Chubu/Nagoya
Automotive parts distributors across Aichi prefecture consume cast stretch films for palletized load containment. Naphtha-derived propylene monomer cost volatility squeezes margins in commodity applications. Smaller converters in the industrial belt face capital constraints upgrading co-extrusion lines for mono-material barrier specifications.
Hokkaido
Fresh produce exporters serving premium Asian markets specify vapor-deposited PP films for vacuum-packed seafood and dairy. Agricultural shippers in Sapporo and Hakodate prioritize moisture barrier performance for extended shelf life during international transit. Regional processors are adapting to METI's resource circulation targets through pure PP stream qualification.
Kyushu
Electronics manufacturers in Fukuoka prefecture utilize low-tack protective films for semiconductor and display panel surface guarding during assembly and export. Industrial packaging demand scales with precision component shipments to Asian markets. Local converters supply standard cast formulations with minimal specification overhead.
Japan Polypropylene Packaging Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier performance tiers, with pharmaceutical-grade specifications commanding threefold unit economics over standard food wrapping. The vendor base organizes around integrated resin-to-film operations, specialized co-extrusion capabilities, and trading house distribution networks. Three archetypes dominate: diversified chemical conglomerates with captive polymer supply, precision film specialists with cleanroom validation capacity, and regional converters serving industrial stretch and protective film segments. Competitive dynamics center on co-extrusion line upgrades for mono-material compliance and long-term supply agreements displacing spot purchasing.
Among Japan-based diversified manufacturers, Toray Industries, Inc. and Mitsui Chemicals Tohcello, Inc. represent the integrated chemical conglomerate archetype with backward polymer control. Toyobo Co., Ltd. occupies a position exemplifying specialized film precision capabilities. These three entities anchor the competitive structure through differentiated technology access and customer relationship depth.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Mitsui Chemicals Tohcello, Inc. |
| Toyobo Co., Ltd. |
| Futamura Chemical Co., Ltd. |
| Toppan, Inc. |
| Cosmo Films Ltd. |
| Idemitsu Unitech Co., Ltd. |
| Takigawa Corporation |
| Gunze Limited |
| Others |
Supply & Pricing Matrix
Pharmaceutical procurement consolidation in Osaka's manufacturing corridor anchors value-based pricing for barrier-grade polypropylene films. Long-term technical partnerships with embedded R&D collaboration displace spot purchasing through trading houses.
Pricing Analysis
Value-based pricing tied to oxygen transmission performance and PMDA compliance documentation anchors premium tiers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels separates barrier films with sub-5 cc/m²/day ratings from commodity cast wraps. Cost compression in standard food wrapping intensifies because naphtha-derived propylene feedstock volatility squeezes cast film margins. Industrial stretch film buyers in Nagoya's automotive belt exhibit highest price sensitivity, while Osaka pharmaceutical companies prioritize barrier validation over unit cost.
Supply Chain Analysis
Propylene monomer supply rests on Japanese petrochemical complexes and integrated refinery operations across Chiba and Yamaguchi prefectures. Specialty cyclic olefin copolymers for tie layers draw from limited domestic producers, while vapor deposition equipment sources from German and Japanese precision engineering specialists. Single-source vulnerability concentrates in cleanroom-qualified co-extrusion capacity serving PMDA-regulated pharmaceutical applications. Distribution runs through converter-direct relationships for premium barrier films and trading house networks for commodity industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom-validated co-extrusion capacity scarcity props pricing for pharmaceutical-grade barrier films. Mono-material compliance mandates constrain supply elasticity across the forecast window.
For Market Incumbents: Lock in pharmaceutical procurement consolidation through dedicated R&D collaboration agreements and documented extractables profiles. Invest in 9-layer and 11-layer co-extrusion line upgrades for mono-material barrier specifications to defend against commodity cast film margin erosion. Secure backward integration into cyclic olefin copolymer tie layer supply. For New Entrants and Emerging Players: Begin with cosmetic sample sachet conversion in Tokyo's Shibuya and Ginza districts, where ultra-thin gauge mono-PP alternatives displace multi-material pouches with minimal cleanroom validation burden. Target Hokkaido agricultural export corridors for vapor-deposited film qualification. Pursue co-development partnerships with regional food manufacturers seeking METI-compliant barrier solutions. For Investors and Strategic Acquirers: The window for entry favors precision film specialists with existing cleanroom infrastructure and PMDA validation track records. Mid-cap converters with captive resin supply and co-extrusion technical depth offer strongest long-term viability. Watch METI enforcement timelines for mono-material mandates as inflection indicator for capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Co-extrusion Line Upgrade for Mono-Material Compliance | Enables METI-aligned film architectures without sacrificing barrier performance for pharmaceutical clients. |
| Backward Integration into Cyclic Olefin Copolymer Supply | Secures captive tie layer material for 9-layer and 11-layer barrier structures. |
| Long-term Supply Agreement with Embedded R&D Collaboration | Mirrors Osaka pharmaceutical procurement consolidation and displaces spot purchasing. |
| Cleanroom Validation Capacity Expansion | Addresses PMDA extractables testing requirements extending qualification timelines. |
| Vapor Deposition Equipment Partnership | Qualifies silicon oxide barrier alternatives to aluminum metallization for Kanto food manufacturers. |
Research Methodology
Trade association filings, METI resource circulation policy documents, and PMDA pharmaceutical packaging guidelines formed the secondary backbone. Primary interviews with co-extrusion line operators, pharmaceutical procurement managers in Osaka, food packaging technical directors in Kanto, and resin procurement leads at integrated chemical producers combined with secondary validation. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing across technology and application segments.
Historical trendline analysis of installed co-extrusion capacity and pharmaceutical packaging qualification timelines informed projection frameworks. Segmentation dimensions modeled include barrier performance tier, end-use regulatory cluster, conversion technology type, and regional industrial corridor concentration. CAGRs derived from capacity utilization trajectories and substitution elasticity between multi-polymer laminates and mono-material structures. Forecast inputs incorporated METI mandate implementation schedules and PMDA validation pipeline data.
Feedstock cost volatility, regulatory enforcement timing, and barrier-recyclability trade-off breakthroughs are the dominant revision risks. Forecasts reflect assumptions about mono-material adoption curves and pharmaceutical procurement consolidation rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PP Film Blowing Machine Market
Poly film
PE Foam Films Market
Poly film
Global Biaxially Oriented Polypropylene (BOPP) in Films and Sheets Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Twist Wrap Film Market
Poly film
Bio-PET Film Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Resealable Films Market
Poly film
Starch-Based Plastic Films Market
Poly film
Surface Printed Film Market
Poly film
Isotropic Film Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Nigeria Plastic Packaging Films Market