
 Insulated Delivery Bag Market | 2026-2036
Insulated Delivery Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Delivery Bag Market Insights
Asset-light leasing and third-party logistics financing is fragmenting competitive access across the insulated delivery bag supply chain. Packir leverages its manufacturing scale to anchor bulk contracts with national food delivery aggregators. Cambro Manufacturing sustains institutional kitchen dominance through deep vertical integration into polymer fabrication. Yeti Holdings differentiates via premium thermal engineering that commands higher price points in catering and medical transport segments.
Insulated delivery bags are passive temperature-control containers engineered with multi-layer insulation—typically closed-cell foam or reflective metallized film laminated between polyester or nylon shells—to maintain hot or cold conditions for perishable goods during transit. The primary commercial purpose centers on preserving food safety, pharmaceutical efficacy, and product quality across variable-duration last-mile distribution. Food delivery bags lead volume within the product type dimension, while medical transport under the use case category posts the fastest structural expansion as hospital and laboratory procurement tightens cold-chain integrity standards. Polyester dominates material selection for cost-driven restaurant procurement, though nylon gains share in premium grocery and catering applications where abrasion resistance justifies higher unit costs.
The US FDA enforces food safety transport standards that mandate cleanable surfaces and temperature documentation for commercial food carriers, while the EU F-Gas Regulation indirectly shapes insulation material choices by restricting certain synthetic blowing agents. California's SB 54 implements extended producer responsibility for plastic packaging that filters into bag liner compliance costs for suppliers serving the US West Coast. Stakeholders must monitor how fragmented municipal composting mandates across Germany, France, and the Netherlands will redefine acceptable end-of-life pathways for multi-material bag constructions.
Market Dynamics
Food delivery aggregators are consolidating procurement power into national framework agreements, compressing supplier margins while demanding real-time temperature traceability that forces bag manufacturers to embed sensor-ready architecture into standard product lines.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive's phase-out mandates for disposable foodware are redirecting restaurant procurement toward durable, multi-use insulated bags across Germany, France, and the Netherlands.
- Cloud kitchen proliferation:Delivery-native food preparation facilities in dense urban corridors are scaling thermal bag fleets to match hyperlocal delivery radius requirements.
- Phase-change material advances:Salt hydrate and paraffin wax formulations are extending passive cold-chain duration, opening pharmaceutical specimen transport to bag-based solutions.
Market Restraints
- Petrochemical input volatility:Polyester shell fabrics and closed-cell polyethylene foam cores expose manufacturers to crude-linked cost swings with limited pass-through elasticity.
- Chinese manufacturing concentration:Zhejiang and Guangdong provinces dominate woven textile and insulation substrate output, creating single-source vulnerability for Western brand owners.
- Thermal performance ceiling:Passive insulation cannot match active refrigeration for shipments exceeding four hours, restricting addressable market in rural last-mile routes.
Strategic Opportunities
- India food delivery expansion:Swiggy and Zomato are building dedicated logistics arms requiring localized bag specifications for tropical climate performance.
- Reusable packaging mandates:California's SB 54 extended producer responsibility framework incentivizes bag-as-a-service leasing models for West Coast restaurant chains.
- RFID-thermal convergence:Embedding temperature-logging tags with inventory tracking is creating premium product tiers for hospital laboratory specimen workflows.
Industry Challenges
- Multi-material recycling complexity:Laminated foam-film-textile constructions lack established end-of-life processing infrastructure, complicating compliance with fragmented municipal composting standards.
- Sensor integration capex:IoT-enabled bag development requires upfront hardware engineering investment that mid-tier manufacturers struggle to amortize across limited production volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Delivery Bag Market |
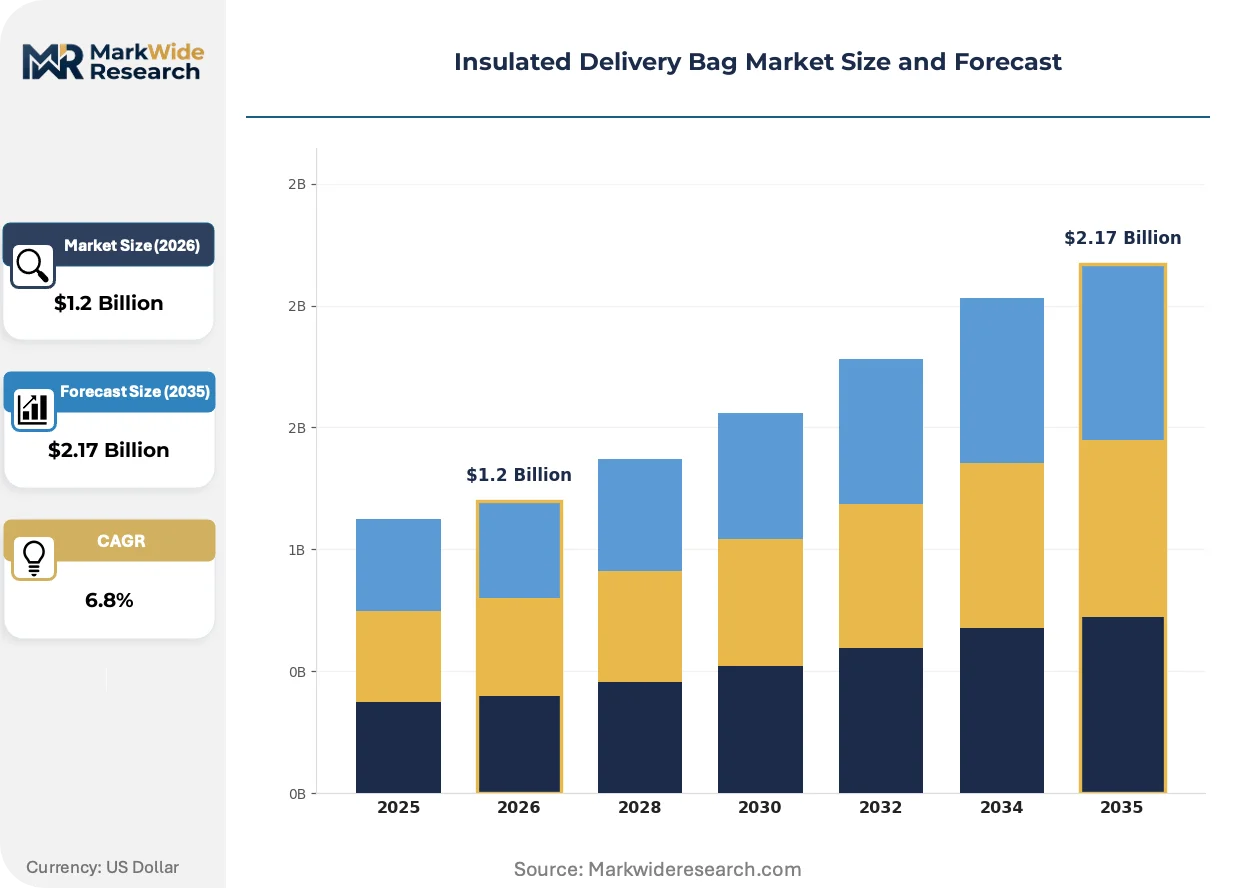
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
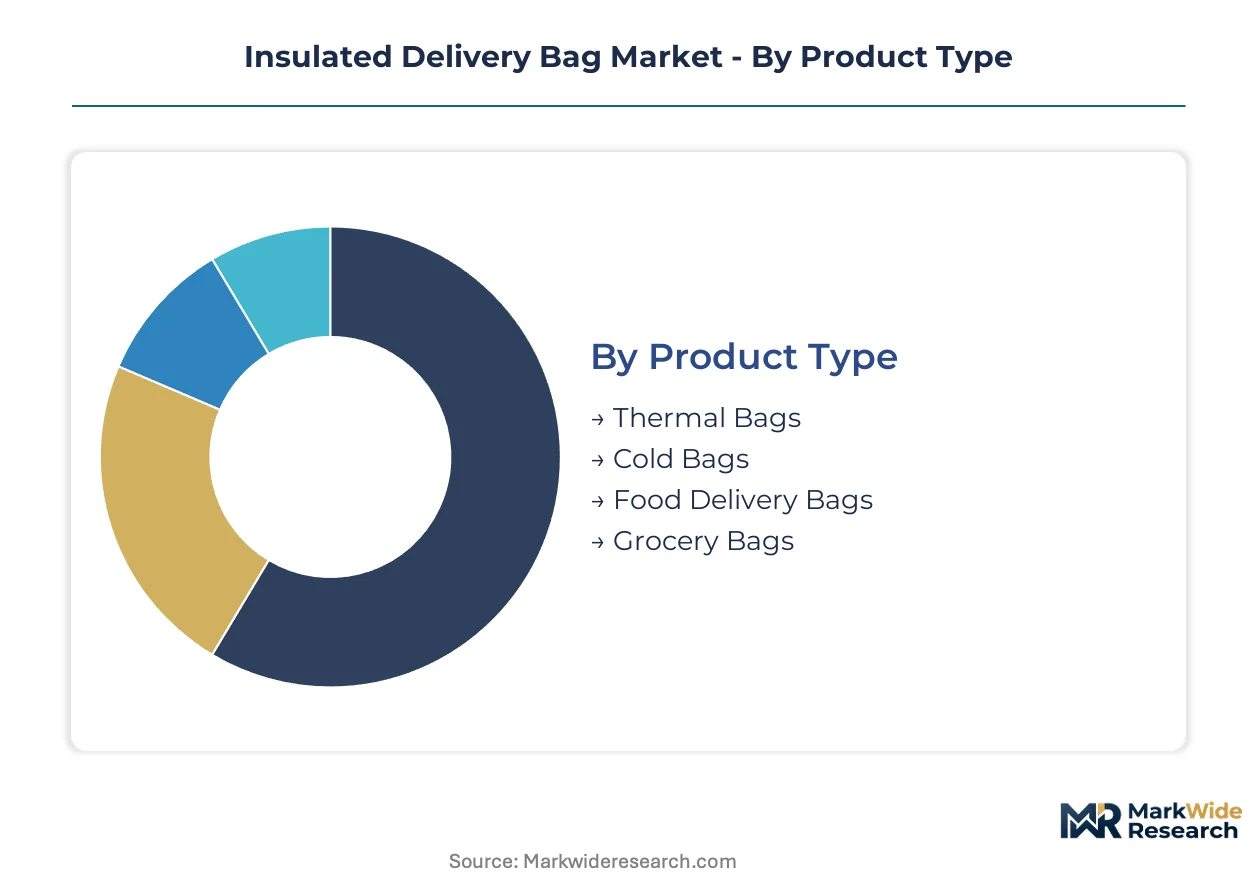
| Segmentation | Product Type: Thermal Bags, Cold Bags, Food Delivery Bags, Grocery Bags Material: Polyester, Nylon, Polypropylene, Canvas Use Case: Food Delivery, Medical Transport, Grocery Shopping, Catering Services End User: Restaurants, Retailers, Hospitals, Catering Companies |
| Companies Covered | Grubhub Gear, Packir, Cambro Manufacturing, Delivery Bags USA, Igloo Products Corp, Yeti Holdings, Vollrath Company, Hot Logic, Fresco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Delivery Bag Market Trends and Innovations
Material science and embedded electronics are converging to transform insulated bags from passive containers into traceable supply chain nodes, with regulatory pressure on food safety documentation accelerating hardware adoption timelines.
Phase-change material formulations are digitizing temperature assurance protocols by embedding programmable thermal mass that maintains precise setpoints without external power. Hospital laboratories and specialty pharmacy distributors are piloting these smart-thermal bags for vaccine and biologic shipments. The technology is digitizing compliance documentation, replacing manual temperature logs with automated blockchain-verified records that satisfy FDA and EMA audit requirements.
The EU F-Gas Regulation is restricting hydrofluorocarbon blowing agents in foam insulation production, forcing manufacturers to reformulate with water-blown or hydrocarbon alternatives. This regulatory compression is raising material costs while narrowing the performance gap between European-produced and imported Asian insulation substrates. German and French bag assemblers are responding by qualifying domestic foam suppliers to secure regulatory continuity.
Aggregators are consolidating supplier relationships into multi-year framework agreements with volume guarantees and technical performance clauses. Food delivery platforms in Japan and the United States are displacing spot purchasing with contracted manufacturing partnerships that specify minimum thermal duration standards and RFID traceability. This concentration is most visible in Tokyo and New York metropolitan zones where platform-owned logistics arms now directly procure bag fleets rather than delegating to restaurant operators.
Insulated Delivery Bag Market Segmentation
Segmentation in insulated delivery bags reveals how thermal performance requirements, regulatory compliance burdens, and procurement economics split demand across divergent technical specifications. Material choices and use-case architectures determine margin structures and supplier competitive positioning.
Product Type:
Food delivery aggregators deploy distinct thermal architectures depending on payload temperature range and transit duration requirements.
- Food Delivery Bags:Multi-layer polyester shells with closed-cell polyethylene foam cores dominate quick-service restaurant procurement. Dense metropolitan zones in the United States and Germany concentrate volume as platform-owned logistics arms displace operator-procured fleets.
- Cold Bags:Reflective metallized film laminates with phase-change material pockets extend frozen and chilled transport windows. Hospital laboratory networks and specialty pharmacy distributors in Japan are adopting these for vaccine shipments where passive cold-chain duration determines regulatory compliance.
- Thermal Bags:Lightweight constructions prioritize hot-food temperature retention for pizza and Asian cuisine delivery. Tropical climate performance requirements in India are driving localized specification adjustments for Swiggy and Zomato fleet procurement.
- Grocery Bags:Reinforced base panels and expanded volume accommodate multi-item supermarket orders. California's SB 54 extended producer responsibility framework incentivizes durable designs for West Coast retail chains.
Established volume favors Food Delivery Bags; emerging adoption favors Cold Bags.
Material:
Cost-performance tradeoffs and abrasion resistance requirements split procurement across synthetic and natural fiber constructions.
- Polyester:Woven polyethylene terephthalate dominates restaurant procurement due to cost efficiency and moisture resistance. Zhejiang and Guangdong province manufacturing concentration exposes Western brand owners to single-source supply vulnerability.
- Nylon:Higher denier weaves deliver superior tear strength for premium grocery and catering applications where unit cost tolerance expands. German bag assemblers are qualifying domestic foam suppliers to narrow the performance gap with Asian substrates under EU F-Gas Regulation constraints.
- Polypropylene:Non-woven spunbond constructions serve single-use and limited-reuse scenarios. Fragmented municipal composting mandates across France and the Netherlands complicate end-of-life processing for this material class.
- Canvas:Cotton-duck weaves appeal to sustainability-positioned catering brands seeking natural fiber credentials. Higher moisture absorption limits deployment in humid climate zones without supplemental waterproofing treatments.
Polyester commands procurement scale; Nylon climbs the fastest on premium application demand.
Use Case:
Temperature documentation requirements and transit risk profiles create divergent technical specifications across commercial applications.
- Medical Transport:RFID-embedded bags with automated temperature logging satisfy FDA and EMA audit requirements for pharmaceutical specimens. Blockchain-verified compliance documentation is replacing manual logs in hospital laboratory workflows.
- Food Delivery:Real-time temperature traceability demands are forcing sensor-ready architecture into standard product lines. National framework agreements with volume guarantees now dominate procurement for platform-owned logistics arms.
- Catering Services:Premium thermal engineering commands higher price points for event and institutional foodservice. Yeti Holdings and comparable specialists target this segment with extended-duration insulation packages.
- Grocery Shopping:Reusable packaging mandates redirect supermarket procurement toward durable multi-use designs. California's SB 54 implementation is accelerating bag-as-a-service leasing model adoption.
Food Delivery anchors installed base; Medical Transport shows steepest expansion trajectory.
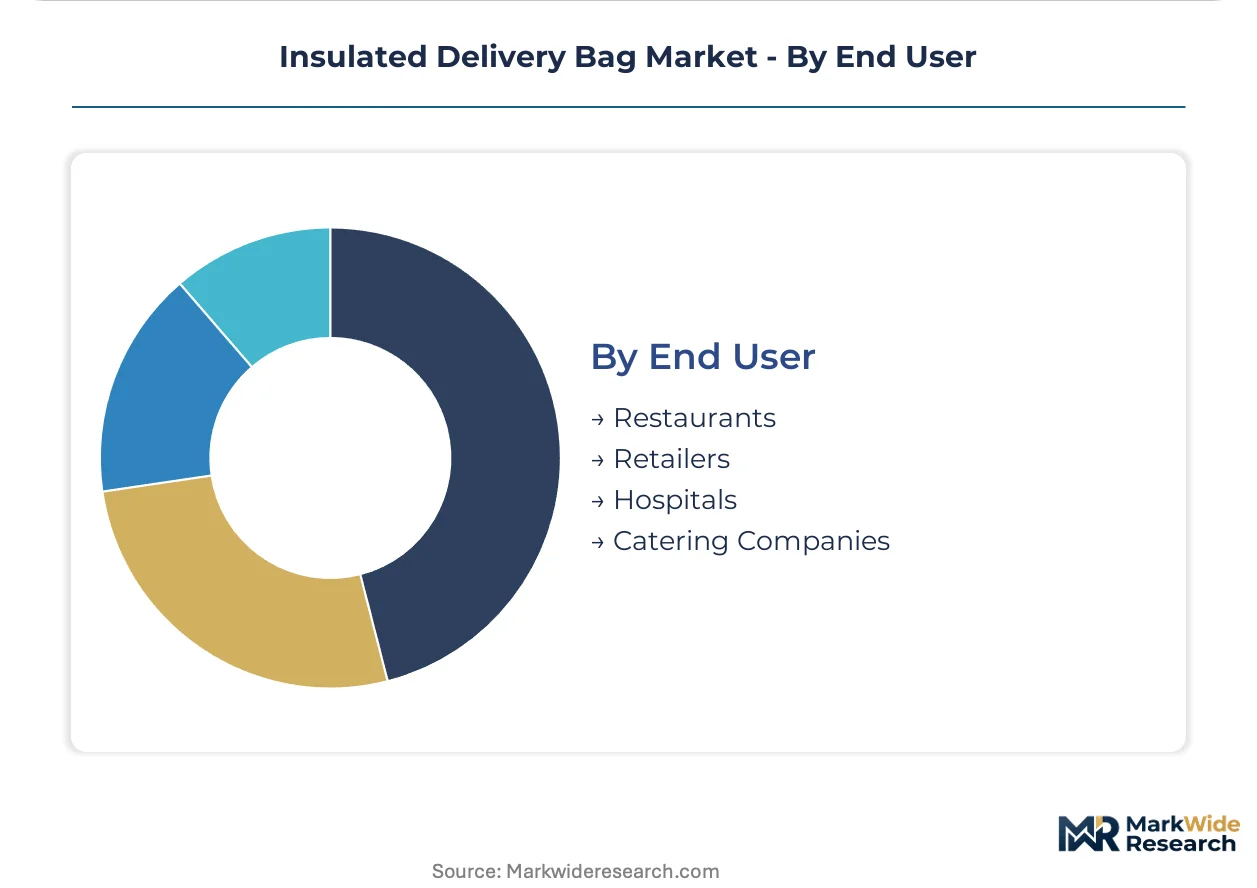
End User:
Procurement centralization patterns and compliance sophistication levels segment demand across institutional buyers.
- Restaurants:Quick-service and full-service operators face compressed margins under national aggregator framework agreements. Cleanable surface mandates under US FDA food safety transport rules constrain material selection.
- Hospitals:Laboratory and pharmacy departments tighten cold-chain integrity standards for specimen and biologic shipments. Phase-change material advances are opening bag-based solutions previously requiring active refrigeration.
- Retailers:Grocery chains and meal-kit providers scale thermal bag fleets for click-and-collect and delivery-native operations. Cloud kitchen proliferation in dense urban corridors expands addressable equipment demand.
- Catering Companies:Event and institutional foodservice operators prioritize thermal duration and brand presentation. Deep vertical integration into polymer fabrication sustains competitive positioning for established manufacturing specialists.
Restaurants concentrate procurement volume; Hospitals drive specification upgrading fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform-owned logistics arms concentrate procurement power in dense metropolitan zones where restaurant-to-consumer delivery volume runs highest. Food delivery aggregators now directly contract bag fleets rather than delegating to individual operators. Regulatory pressure on food safety documentation and single-use plastics phase-outs is reshaping supplier qualification criteria across major demand centers.
United States
Food delivery platforms in New York and Los Angeles metropolitan areas consolidate procurement into national framework agreements with thermal performance clauses. The FDA enforces cleanable surface mandates and temperature documentation requirements for commercial food carriers. Cloud kitchen proliferation in Chicago and Miami urban corridors expands fleet scaling requirements for passive thermal containers.
Germany
Restaurant aggregators across Berlin and Hamburg redirect procurement toward durable multi-use bags under EU Single-Use Plastics Directive implementation. The EU F-Gas Regulation restricts hydrofluorocarbon blowing agents in foam insulation production, forcing substrate reformulation. Bavarian and North Rhine-Westphalian bag assemblers qualify domestic foam suppliers to secure regulatory continuity.
Japan
Platform-owned logistics arms in Tokyo and Osaka metropolitan zones displace spot purchasing with contracted manufacturing partnerships specifying RFID traceability. METI standards shape cold-chain equipment specifications for pharmaceutical specimen workflows. Hospital laboratory networks in Nagoya and Fukuoka pilot phase-change material bags for vaccine shipments.
India
Swiggy and Zomato build dedicated logistics arms requiring localized bag specifications for tropical climate performance in Mumbai and Bangalore. FSSAI regulations on food transport hygiene constrain material selection for commercial carriers. Cloud kitchen clusters in Delhi-NCR and Hyderabad drive hyperlocal delivery radius equipment demand.
United Kingdom
Food delivery aggregators in London and Manchester metropolitan areas consolidate supplier relationships under extended producer responsibility anticipation. The UK Environment Agency enforces packaging waste regulations filtering into bag liner compliance costs. Meal-kit providers and grocery chains in Birmingham and Glasgow scale thermal bag fleets for click-and-collect operations.
Insulated Delivery Bag Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where scale-driven fabricators anchor national aggregator contracts while premium thermal engineers serve catering and medical segments. The vendor base splits between manufacturing-anchored suppliers with captive polymer production and assembly-focused specialists dependent on imported substrates. Two strategic archetypes dominate: vertically integrated polymer fabricators and sensor-ready architecture developers. Competitive moves concentrate on multi-year framework agreement pursuit and phase-change material formulation licensing.
Among North American equipment specialists, Cambro Manufacturing and Yeti Holdings exemplify divergent positioning archetypes. Cambro Manufacturing represents the vertically integrated polymer fabricator model with in-house production capabilities spanning institutional kitchen equipment. Yeti Holdings occupies the premium thermal engineering tier where extended-duration insulation packages command higher price points in catering and medical transport segments. Packir anchors the scale-driven contract manufacturing vector for platform-owned logistics procurement.
| Leading Market Players |
|---|
| Grubhub Gear |
| Packir |
| Cambro Manufacturing |
| Delivery Bags USA |
| Igloo Products Corp |
| Yeti Holdings |
| Vollrath Company |
| Hot Logic |
| Fresco |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Los Angeles transpacific corridor anchors cost dynamics for polyester shell fabrics and closed-cell foam cores, concentrating pricing power with Zhejiang-based substrate suppliers while forcing Western brand owners into cost-plus contracts indexed to crude-linked petrochemical benchmarks. Downstream, food delivery aggregators exploit procurement scale to compress supplier margins across standard thermal bag tiers, even as premium cold-chain specifications with phase-change material pockets sustain price differentiation for hospital laboratory networks.
Pricing Analysis
Cost-plus contracts with crude-linked indexation dominate procurement relationships between Asian substrate suppliers and Western bag assemblers. Three-tier pricing structure across premium, standard, and economy levels separates RFID-embedded medical transport units from sensor-ready food delivery architectures and basic quick-service restaurant procurement. Price differentiation rests on certification grade—FDA-compliant cleanable surfaces versus standard moisture-resistant linings—and volume scale under national framework agreements. Cost compression in the standard tier is intensifying because platform-owned logistics arms consolidate procurement into multi-year contracts with technical performance clauses. Quick-service restaurant operators exhibit highest price sensitivity; hospital laboratory networks tolerate premium positioning for automated compliance documentation.
Supply Chain Analysis
Upstream feedstock flows draw from purified terephthalic acid and ethylene glycol production concentrated in China, South Korea, and Saudi Arabia, with Zhejiang and Guangdong provinces dominating woven textile and insulation substrate output. Raw material dependencies center on polyester chips, polyethylene foam resins, and metallized film laminates sourced through petrochemical value chains. Single-source vulnerability from Chinese manufacturing concentration creates structural risk for Western brand owners dependent on imported substrates. Distribution runs through contracted manufacturing partnerships with platform-owned logistics arms in dense metropolitan zones, displacing spot purchasing and restaurant-operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insulated delivery bag demand is accelerating through a regulatory inflection as FDA and EMA audit requirements digitize temperature documentation, transforming passive containers into traceable supply chain nodes with embedded sensor architecture.
For Market Incumbents: Pre-empt margin erosion from national aggregator framework agreements by securing captive supply of water-blown foam substrates under EU F-Gas Regulation compliance, and anchor multi-year contracts with volume guarantees that specify minimum thermal duration standards ahead of competitor qualification. For New Entrants and Emerging Players: Mid-market cold-chain logistics providers in India represent the most penetrable entry point, where Swiggy and Zomato fleet procurement lacks localized tropical climate specifications; target hospital laboratory specimen workflows with RFID-thermal convergence products as the go-to-market angle. For Investors and Strategic Acquirers: Sensor-ready architecture developers with phase-change material formulation licensing offer superior long-term viability through the next decade, as blockchain-verified compliance documentation replaces manual temperature logs; monitor EU F-Gas Regulation enforcement intensity as the inflection indicator for substrate cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Phase-Change Material Licensing | Extends passive cold-chain duration for vaccine shipments under FDA audit protocols. |
| RFID-Thermal Convergence | Automates temperature logging for hospital laboratory compliance with EMA requirements. |
| Domestic Foam Supplier Qualification | Secures regulatory continuity under EU F-Gas Regulation substrate restrictions. |
| Bag-as-a-Service Leasing | Aligns with California SB 54 extended producer responsibility for West Coast chains. |
| Framework Agreement Pursuit | Locks volume guarantees with platform-owned logistics arms in Tokyo and New York. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with food delivery platform procurement directors, thermal bag manufacturing engineers, hospital laboratory supply managers, and cold-chain logistics operators; combined with secondary validation through FDA food safety transport guidance documents, EU F-Gas Regulation implementation notices, customs records for polyester textile imports, and aggregator fleet procurement disclosures. Bottom-up unit economics triangulated against top-down market sizing across material, product type, and use-case segmentation.
Forecast inputs considered food delivery aggregator expansion rates, cloud kitchen proliferation in dense urban corridors, and phase-change material adoption curves across pharmaceutical distribution networks. Segmentation dimensions modeled include product architecture, insulation substrate type, end-use application, and regional regulatory cluster. CAGRs were derived from growth rate convergence analysis applied to procurement volume trajectories and fleet replacement cycles.
Practitioners should monitor crude-linked petrochemical volatility, EU F-Gas Regulation enforcement timing, and municipal composting mandate fragmentation for early signals that could revise trajectory assumptions. Cross-checking against food delivery platform capex disclosures and hospital laboratory equipment procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Cassava Bags Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Foam Tube Mailer Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Bin Liners Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Block Sack Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Vacuum Sealer Bags Market