
 Global Adhesive Films Market | 2026-2036
Global Adhesive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesive Films Market Foresight
Project finance tied to automotive battery gigafactories is rewriting capital requirements for adhesive film suppliers seeking scale. 3M Company leverages its captive polymer research infrastructure to sustain pricing power in medical-grade silicone films. Henkel AG & Co. KGaA anchors its position through backward integration into epoxy resin production for electronics assembly. Avery Dennison Corporation competes by controlling narrow-web coating capacity that dominates North American label and tape channels.
Adhesive films are thin-layer polymer systems, typically 12–250 micrometers thick, engineered with pressure-sensitive or heat-activated chemistries to bond dissimilar substrates without mechanical fasteners. Their primary purpose spans surface protection, structural lamination, thermal management, and electromagnetic shielding across manufacturing industries. Acrylic formulations lead volume due to optical clarity and weatherability, while silicone films command premium positioning in medical devices and extreme-temperature automotive applications. Hot melt coating technology is displacing solvent-based lines as manufacturers navigate stricter emission protocols without sacrificing throughput speed.
The EPA enforces VOC limits under the National Emission Standards for Hazardous Air Pollutants that directly constrain solvent-based coating operations in U.S. production facilities. EMA and REACH jointly elevate biocompatibility and substance restriction requirements for medical-grade adhesive films sold into European healthcare markets. China's MEE implements dual carbon goals that pressure domestic coaters to convert energy-intensive thermal drying to UV curing systems. Stakeholders must monitor regulatory divergence between jurisdictions when siting new coating capacity or qualifying products for cross-border medical device supply chains.
Market Dynamics
Automotive electrification programs in Germany and Japan are accelerating demand for thermally conductive bonding layers, while REACH compliance in Europe and EPA guidelines in the United States tighten VOC emission thresholds for solvent-based formulations.
Growth Catalysts
- Automotive Battery Lamination:EV gigafactory construction in Germany and Japan is pulling demand for thermally conductive acrylic and silicone films that manage heat in battery pack assemblies.
- REACH Substance Restrictions:ECHA's evolving candidate list is forcing coaters to reformulate away from legacy chemistries, creating replacement demand for compliant acrylic and silicone alternatives.
- UV Curing Conversion:China's MEE dual carbon goals are pressuring domestic manufacturers to replace thermal drying with energy-efficient UV curing systems, expanding equipment upgrade cycles.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and silicone precursor costs fluctuate with crude oil and natural gas pricing, compressing margin predictability for film coaters.
- Substrate Concentration Risk:China and South Korea control the majority of global capacity expansion for acrylic and silicone film substrates, creating geographic supply vulnerability.
- Technical Performance Ceiling:Solvent-based formulations still achieve superior adhesion on low-surface-energy substrates compared to waterborne or hot-melt alternatives, slowing full conversion.
Strategic Opportunities
- India Electronics Assembly:PLI scheme incentives for domestic semiconductor and electronics manufacturing are creating virgin demand for epoxy-based adhesive films in PCB lamination.
- Medical-Grade Certification:EMA and FDA biocompatibility pathways for long-wear skin-contact applications represent premium pricing tiers for silicone film suppliers with validated cleanroom capacity.
- Thermal Interface Materials Convergence:Integration of phase-change materials with pressure-sensitive adhesive films is opening new specification slots in data center cooling and 5G infrastructure.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in UV-curable polymer synthesis and silicone crosslinking chemistry is concentrated among retiring specialists, constraining R&D throughput.
- Cleanroom Certification Timelines:ISO 13485 and FDA 21 CFR Part 820 qualification for medical-grade film production requires 18-24 month validation cycles, delaying market entry.
- Legacy Coating Asset Stranding:Solvent-based line conversions to hot-melt or UV systems demand capital redeployment that mid-tier coaters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesive Films Market |
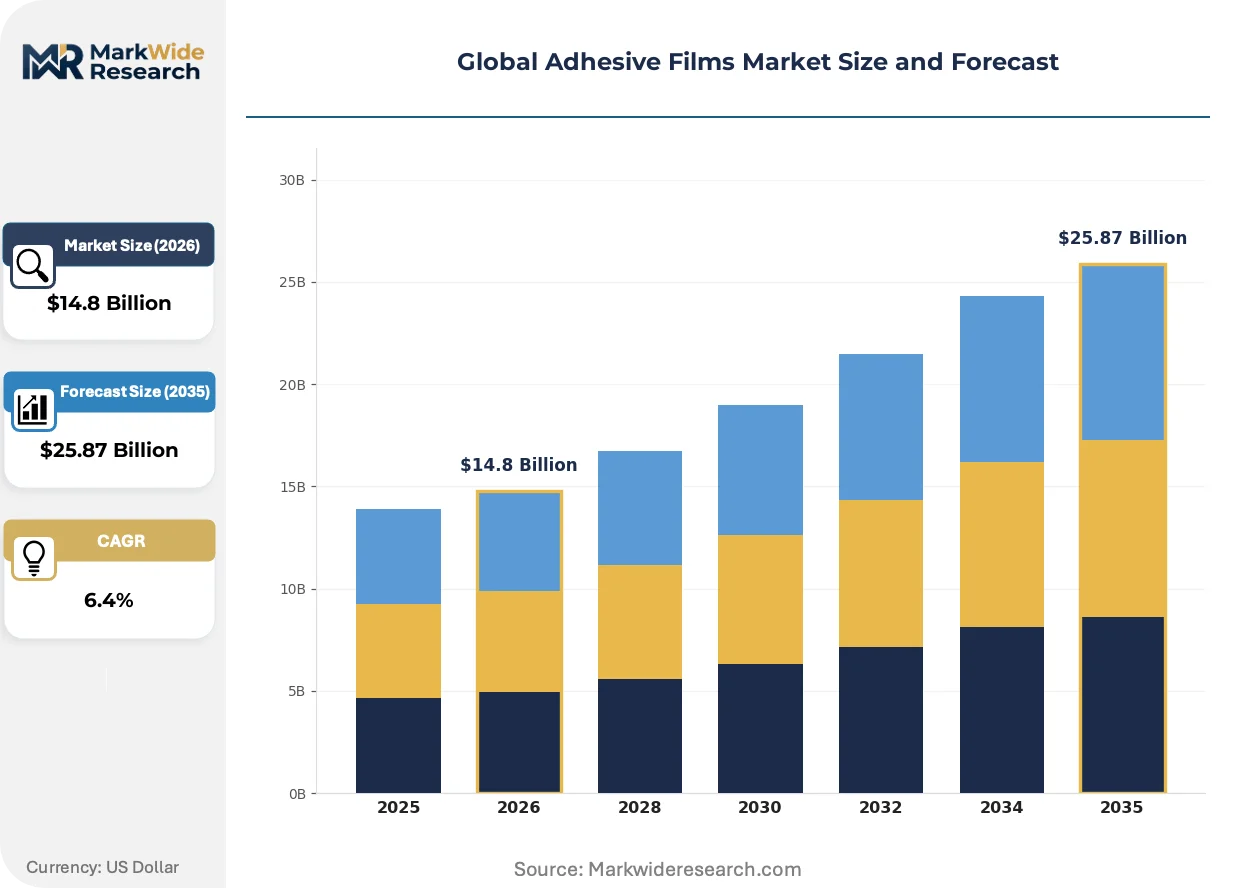
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Rubber, Silicone, Polyurethane, Epoxy, Hot Melt Application: Electronics Assembly, Medical Devices, Packaging Solutions, Automotive Components, Construction Materials, Consumer Goods End User: OEMs, Contract Manufacturers, Medical Facilities, Construction Contractors, Packaging Companies, Consumer Brands Technology: Solvent-Based Coating, Water-Based Coating, Hot Melt Coating, UV Curing, Reactive Coating, Radiation Curing |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Avery Dennison Corporation, H.B. Fuller Company, Nitto Denko Corporation, Lintec Corporation, Sika AG, Toray Industries, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesive Films Market Shifts & Advancements
Active chemistry evolution and coating process reinvention are compressing the competitive window for suppliers unable to bridge from legacy solvent systems to next-generation formulations.
Acrylic-silicone hybrid pressure-sensitive adhesives are hybridizing the weatherability of acrylic backbones with the extreme-temperature performance of silicone crosslinkers. Automotive underhood and battery pack engineers are specifying these films at accelerating rates for applications exceeding 150°C continuous exposure. This chemistry convergence is hybridizing what were historically separate specification categories, forcing suppliers to maintain dual formulation competencies or cede position.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is constraining solvent-based coating operations in U.S. production facilities. Manufacturers face capital decisions between emission control retrofits and full process conversion to hot-melt or UV curing. Medical-grade and electronics assembly segments are responding fastest, driven by buyer mandates for supply chain decarbonization disclosures.
Buyer specification behavior is compressing qualification cycles as automotive and electronics OEMs consolidate adhesive film vendors to reduce supply chain complexity. Tier-1 laminators are displacing spot-buy arrangements with multi-year framework agreements that lock in volume commitments and technical collaboration. This concentration is most visible in Germany and Japan, where battery gigafactory procurement teams are pre-qualifying film suppliers 24-36 months ahead of production ramp.
Global Adhesive Films Market Segmentation
Adhesive films serve divergent specification regimes across chemistries, coating technologies, and end-use environments. Segmentation clarity enables suppliers to align R&D pipelines with qualified demand pools and regulatory qualification pathways.
Product Type:
Cost tier differentiation separates commodity formulations from medical-grade and thermally conductive premium positions.
- Acrylic:Optical-grade acrylic films dominate label, tape, and electronics display lamination due to weatherability and clarity. Demand concentrates in German and Japanese automotive battery programs specifying thermally conductive acrylic bonding layers for pack assembly.
- Silicone:Platinum-catalyzed silicone films withstand continuous exposure above 150°C with stable adhesion. Medical device OEMs in the United States and Europe specify these for long-wear skin-contact applications requiring FDA and EMA biocompatibility validation.
- Rubber:Natural and synthetic rubber-based formulations serve cost-sensitive packaging and masking applications with aggressive tack properties.
- Polyurethane:Flexible polyurethane films bond dissimilar substrates in footwear and textile lamination where elasticity retention matters.
- Epoxy:Rigid epoxy films provide structural adhesion in PCB lamination and composite assembly for aerospace and electronics.
- Hot Melt:EVA and polyolefin hot melt films enable solvent-free bonding in high-speed packaging lines and disposable medical product assembly.
Acrylic holds installed capacity. Silicone is rotating up the share rankings.
Application:
Application segmentation tracks how qualification intensity and performance thresholds vary across end-use environments.
- Electronics Assembly:Die-attach films and thermal interface materials bond semiconductors, displays, and PCBs with precision thickness control. India's PLI scheme for domestic semiconductor manufacturing is pulling demand for epoxy and acrylic films in cleanroom assembly operations.
- Medical Devices:ISO 10993-compliant silicone and hydrocolloid films adhere to skin, wound sites, and surgical drapes for extended wear. EMA and FDA dual-qualification requirements extend validation cycles to 18-24 months, concentrating procurement among validated cleanroom coaters.
- Automotive Components:Battery pack lamination, interior trim bonding, and exterior sealing specify films with temperature, chemical, and vibration resistance. German and Japanese EV gigafactories are pre-qualifying suppliers 24-36 months ahead of production ramp.
- Packaging Solutions:Pressure-sensitive label stocks and flexible food packaging films prioritize clarity, printability, and migration compliance.
- Construction Materials:Vapor barrier membranes, flooring underlayment, and window flashing tapes employ butyl and rubber-modified films for weather sealing.
- Consumer Goods:Appliance assembly, furniture lamination, and personal care product bonding utilize commodity acrylic and hot melt formulations.
Electronics Assembly commands qualification investment. Medical Devices is climbing the fastest.
Technology:
Coating technology segmentation reveals the capital intensity and emission profiles governing manufacturing economics.
- Solvent-Based Coating:Toluene and ethyl acetate solvent systems achieve superior adhesion on low-surface-energy substrates. EPA National Emission Standards for Hazardous Air Pollutants constrain U.S. operations, forcing capital decisions between emission controls and process conversion.
- Hot Melt Coating:Molten polymer extrusion eliminates solvent handling and thermal drying, reducing energy intensity. Packaging and disposable medical segments are displacing solvent lines fastest due to buyer decarbonization mandates.
- UV Curing:Photoinitiator-acrylate formulations cure instantly under UV exposure, enabling high-speed narrow-web coating. China's MEE dual carbon goals are pressuring domestic coaters to convert thermal drying to UV systems.
- Water-Based Coating:Acrylic emulsion and polyurethane dispersion systems reduce VOC emissions but require longer drying tunnels and energy-intensive water removal.
- Reactive Coating:Two-component epoxy and polyurethane systems cure through chemical reaction, providing structural adhesion in aerospace and industrial assembly.
- Radiation Curing:Electron beam curing penetrates thick films without photoinitiators, serving food-contact and medical applications with zero migration risk.
Solvent-Based retains technical performance leadership. Hot Melt is gaining share fastest.
End User:
Customer type segmentation distinguishes specification authority, volume scale, and procurement behavior across the value chain.
- OEMs:Automotive, electronics, and medical device OEMs control adhesive film specification through approved vendor lists and multi-year framework agreements. German and Japanese battery manufacturers are consolidating suppliers to reduce qualification burden.
- Contract Manufacturers:Electronics manufacturing services and medical device contract assemblers procure films under OEM-directed specifications with volume flexibility requirements.
- Medical Facilities:Hospitals and surgical centers specify sterile barrier films and wound care adhesives through group purchasing organizations with biocompatibility documentation requirements.
- Construction Contractors:Regional builders and specialty contractors select weather-sealing and flooring films based on local code compliance and installer familiarity.
- Packaging Companies:Converters and label printers prioritize film coaters with narrow-web coating capacity and rapid changeover capabilities.
- Consumer Brands:Appliance and personal care manufacturers source commodity films through distributor channels with price and availability focus.
OEMs concentrate specification authority. Contract Manufacturers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adhesive films trade flows reveal a structural deficit in North America and Europe against concentrated Asian supply. Import dependency for specialty substrates shapes regional pricing and qualification timelines across automotive, electronics, and medical end-uses.
United States
EV battery gigafactories in Michigan and Tennessee pull thermally conductive acrylic films for pack assembly. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based coating capacity expansion, favoring hot-melt and UV curing investments. The Southeast manufacturing corridor attracts medical-grade film converters seeking FDA 21 CFR Part 820 qualification proximity to device OEM clusters.
Germany
Automotive electrification programs at BMW, Mercedes-Benz, and Volkswagen drive specification of silicone-acrylic hybrid films for battery thermal management. ECHA REACH substance restrictions force coaters to eliminate legacy chemistries, creating replacement demand for compliant formulations. The Baden-Württemberg industrial belt hosts concentrated narrow-web coating capacity serving label and electronics display markets.
China
Domestic EV production exceeds global demand, pulling acrylic and silicone film capacity expansion in Jiangsu and Guangdong provinces. MEE dual carbon goals pressure coaters to convert thermal drying to UV curing systems, accelerating equipment upgrade cycles. The Yangtze River Delta concentrates substrate manufacturing for export to European and North American laminators.
Japan
Precision electronics assembly in Nagoya and Osaka sustains demand for die-attach films and thermal interface materials. METI carbon neutrality targets drive solvent-to-hot-melt conversion in coating operations. The Kanto region anchors medical-grade silicone film production qualified to PMDA and FDA standards for long-wear skin-contact applications.
India
PLI scheme incentives for semiconductor and electronics manufacturing create virgin demand for epoxy-based adhesive films in PCB lamination. BIS certification requirements extend qualification timelines for imported film substrates. The Gujarat-Delhi-Mumbai industrial corridor attracts contract manufacturers establishing cleanroom assembly operations for export markets.
Global Adhesive Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and formulation supply. The market structures around three tiers: diversified materials conglomerates with captive polymer research, mid-cap coaters with narrow-web specialization, and regional converters serving price-sensitive packaging segments. Strategic moves concentrate on backward integration into resin production and multi-year framework agreements with automotive and electronics OEMs consolidating vendor bases.
Within the diversified conglomerate tier, 3M Company, Henkel AG & Co. KGaA, and Avery Dennison Corporation exemplify divergent defensive positions. 3M occupies a research-intensive anchor through captive polymer infrastructure sustaining premium positioning in medical-grade silicone films. Henkel exemplifies backward integration strategy through in-house epoxy resin production for electronics assembly qualification. Avery Dennison represents narrow-web coating scale concentration dominating North American label and tape distribution channels.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Nitto Denko Corporation |
| Lintec Corporation |
| Sika AG |
| Toray Industries |
| Arkema SA |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock volatility in acrylic monomer and silicone precursor markets compresses margin predictability for film coaters while simultaneously widening spreads between commodity and certified-grade pricing tiers. This input cost instability forces buyers into longer-term offtake commitments to secure volume, reshaping procurement relationships across automotive battery and medical device supply chains.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for thermally conductive films in German and Japanese EV battery programs. Three-tier pricing structure across medical-grade silicone, industrial acrylic, and commodity hot-melt levels reflects certification intensity and cleanroom validation status. Cost compression in standard-grade acrylic films is intensifying because Chinese substrate expansion outpaces demand absorption in packaging segments. Contract manufacturers in electronics assembly exhibit highest price sensitivity due to OEM-directed specifications, while medical device OEMs accept premium positioning for FDA and EMA dual-qualified silicone films.
Supply Chain Analysis
Export control restrictions on advanced coating equipment and UV curing photoinitiator technologies constrain technology transfer to emerging production hubs. Substrate manufacturing concentrates in China, South Korea, and Japan, with Jiangsu and Guangdong provinces hosting acrylic and silicone film expansion. Raw material flows draw from Saudi petrochemical complexes for acrylic monomers, German chemical clusters for epoxy resins, and Japanese silicone precursors. Single-source vulnerability runs through Chinese substrate concentration for European and North American laminators. Distribution runs through Tier-1 laminators holding multi-year framework agreements with automotive and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Adhesive Films Market sits in early-cycle recovery as automotive electrification capital deployment accelerates demand for thermally conductive bonding layers. Battery gigafactory construction timelines in Germany and Japan provide visible demand anchors through the projection horizon.
For Market Incumbents: Build formulation chemistry moats through captive R&D in UV-curable acrylate and platinum-catalyzed silicone crosslinking. Accelerate backward integration into epoxy resin production to defend margin position against petrochemical volatility. Secure ISO 13485 cleanroom certification in Southeast US manufacturing corridors to anchor medical-grade supply relationships. Lock multi-year framework agreements with battery OEM procurement teams 24-36 months ahead of production ramp.
For New Entrants and Emerging Players: India's PLI scheme electronics assembly corridor represents the most penetrable entry point for epoxy-based adhesive films in PCB lamination. Mid-tier coaters stranded with solvent-based assets in Europe create acquisition targets for UV curing technology retrofit. Target contract manufacturers in Gujarat-Delhi-Mumbai industrial belt with BIS-compliant film substrates priced below validated cleanroom competitors.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors narrow-web coating specialists with automotive qualification. Long-term viability rests on regulatory compliance infrastructure rather than commodity scale. Acquisition targets should exhibit dual FDA-EMA validation pathways and existing relationships with German Tier-1 laminators. Monitor ECHA REACH substance restriction announcements as inflection indicators for replacement demand cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Henkel's captive resin supply anchors electronics assembly qualification and margin defense. |
| UV Curing Equipment Conversion | China's MEE dual carbon goals accelerate domestic coater upgrade cycles and technology transfer. |
| Medical-Grade Cleanroom Certification | FDA 21 CFR Part 820 and ISO 13485 validation opens premium pricing tiers in long-wear skin-contact applications. |
| Multi-Year Framework Agreements with Battery OEMs | German and Japanese gigafactory procurement teams consolidate vendors to reduce qualification burden. |
| Acrylic-Silicone Hybrid Formulation Development | Automotive underhood specifications above 150°C continuous exposure drive chemistry convergence demand. |
Research Methodology
A standing panel of coating operations directors, automotive Tier-1 procurement managers, medical device regulatory affairs leads, and chemical distribution channel partners provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with downstream laminators and OEM specification engineers against secondary validation from EPA enforcement databases, ECHA REACH candidate list updates, SEC 10-K filings of listed materials conglomerates, and customs trade flow records for acrylic and silicone film substrates. Bottom-up capacity assessments across Jiangsu, Guangdong, Baden-Württemberg, and Southeast US manufacturing corridors were triangulated against top-down demand modeling from EV battery and electronics assembly end-use projections.
Scenario bracketing around regulatory enforcement intensity and petrochemical price volatility shaped the analytical framework across the analysis window. Segmentation dimensions modeled include chemistry type, coating technology, application environment, and end-user procurement behavior. CAGRs were derived from installed capacity expansion timelines, OEM pre-qualification cycles, and substitution elasticity between solvent-based and UV-curable formulations. Industry-specific forecast inputs incorporated EMA biocompatibility pathway timelines and METI carbon neutrality target compliance curves for Japanese coating operations.
Practitioners should monitor ECHA substance restriction announcements, EPA NESHAP enforcement actions, and MEE dual carbon policy implementation for early signals of demand displacement. Forecasts reflect assumptions regarding continued automotive electrification capital deployment and stable regulatory qualification timelines. Material shifts in REACH substance restrictions or battery chemistry transitions away from current thermal management architectures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Tray Liners Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Microwavable Barrier Films Market