
 Pallet Displays Market | 2026-2036
Pallet Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Displays Market Outlook
China is rewriting capacity dynamics in corrugated and converted board packaging, with new automated converting lines serving both domestic retail chains and export-oriented display producers. DS Smith plc leverages its European recycled paper network to supply lightweight cardboard pallet displays with certified post-consumer content. Smurfit WestRock plc anchors North American demand through integrated containerboard-to-display manufacturing. Georgia-Pacific LLC competes on scale, operating multiple corrugating plants that feed retail-ready display production.
Pallet displays are floor-standing merchandising units built on standard or custom pallet footprints, typically constructed from corrugated board, wood, or plastic with load-bearing bases designed for forklift handling and direct placement in retail aisles. Their primary purpose is to eliminate secondary handling by presenting products in shipper-ready configurations that transition directly from warehouse to selling floor. Cardboard pallet displays lead volume due to low unit cost and printability, while plastic variants capture margin pools in reusable closed-loop retail programs. Custom pallet displays represent the fastest-growing product type as brands seek aisle differentiation through die-cut shapes and integrated digital elements.
The EPA governs recycled content claims and forestry certification benchmarks that affect material sourcing for US-manufactured displays, while the EU Green Deal and national extended producer responsibility schemes in France and Germany mandate recyclability documentation and restrict single-use plastic components. The FDA maintains indirect food contact standards for displays positioned near unpackaged consumables in club and grocery channels. Stakeholders must monitor evolving state-level packaging laws in California and New York alongside EU harmonization timelines to align material portfolios with compliance requirements.
Market Dynamics
Supermarket chains are compressing restocking cycles by mandating floor-ready pallet displays that bypass backroom handling entirely, forcing converters to redesign load-bearing structures for direct forklift-to-aisle placement.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recyclability documentation across member states are accelerating material transitions toward certified post-consumer corrugated content.
- Retail automation in Germany:Automated guided vehicles in distribution centers require standardized pallet footprints that align with robotic handling protocols.
- Lightweight cardboard engineering:Advances in fluting profiles and adhesive bonding are expanding load capacity without increasing material weight.
Market Restraints
- Recycled fiber cost volatility:OCC (old corrugated containers) pricing swings in North American spot markets compress converter margins unpredictably.
- Single-use plastic restrictions:France's extended producer responsibility schemes and Germany's VerpackG amendments block reusable plastic pallet programs in certain retail channels.
- Dimensional constraints:Club store aisle widths and racking specifications limit display height and base footprint standardization.
Strategic Opportunities
- India's organized retail expansion:Reliance Retail and D-Mart are adopting Western-style floor-ready merchandising, creating first-mover advantage for corrugated display suppliers.
- Near-field communication integration:NFC-enabled pallet displays allow real-time inventory tracking and consumer engagement through smartphone interaction.
- California SB 54 implementation:Extended producer responsibility for packaging waste creates compliance service revenue streams for display manufacturers offering material documentation.
Industry Challenges
- Structural engineering talent scarcity:Shortage of corrugated board stress analysts capable of optimizing flute combinations for dynamic load conditions.
- Multi-jurisdiction certification timelines:FDA indirect food contact approvals for displays near unpackaged consumables require 8-14 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Displays Market |
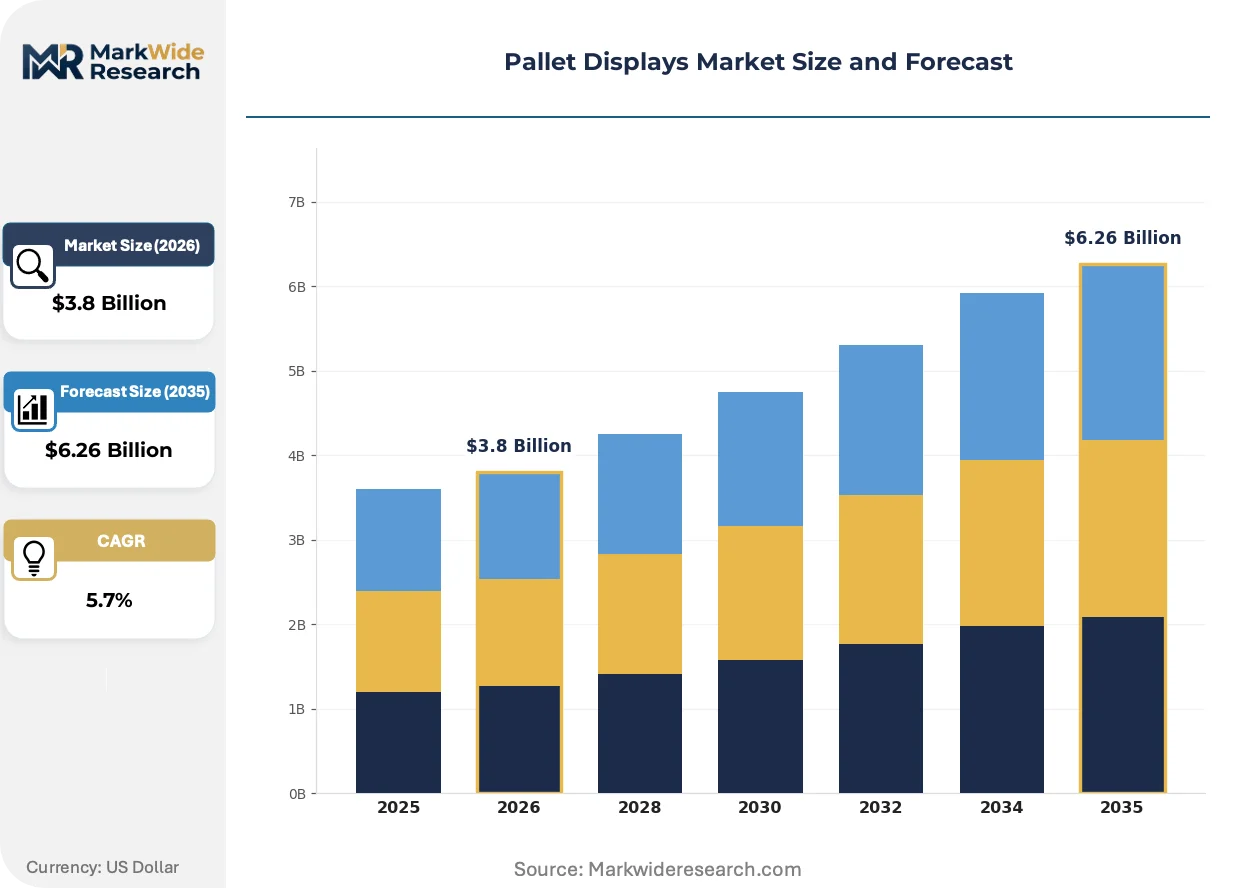
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pallet Displays, Custom Pallet Displays, Rotating Pallet Displays, Countertop Pallet Displays Material: Wood, Plastic, Metal, Cardboard End User: Retail Stores, Supermarkets, Warehouses, E-commerce Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Sonoco Products Company, DS Smith plc, Smurfit WestRock plc, International Paper Company, WestRock Company, Pratt Industries, Georgia-Pacific LLC, Menasha Packaging Company, LLC, Siffron, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Displays Market Strategic Shifts
Digital printing and embedded sensor technologies are collapsing the traditional separation between structural packaging and interactive media, converting static pallet displays into data-capture and consumer-engagement infrastructure.
Variable-data inkjet printing is digitizing short-run customization for regional promotional campaigns. Mass merchandisers in the US are adopting lot-size-one graphics capabilities to support store-specific pricing and localization strategies. This capability is digitizing the economics of display production, compressing minimum order quantities from truckload to pallet quantities without plate-change penalties.
REACH restrictions on certain flame-retardant coatings are redirecting material R&D toward bio-based barrier treatments. European converters are reformulating water-resistant coatings to maintain structural integrity in refrigerated dairy and produce aisles. Club and grocery channels in Germany and France are piloting these alternatives ahead of anticipated ECHA substance evaluations.
Retailers are unbundling display procurement from primary packaging contracts, creating direct relationships with specialized converters. This disintermediation shifts specification authority from CPG brand managers to retail category buyers. The phenomenon is most pronounced in US club channels, where Costco and Sam's Club maintain dedicated display engineering teams that bypass traditional supplier hierarchies.
Pallet Displays Market Segmentation
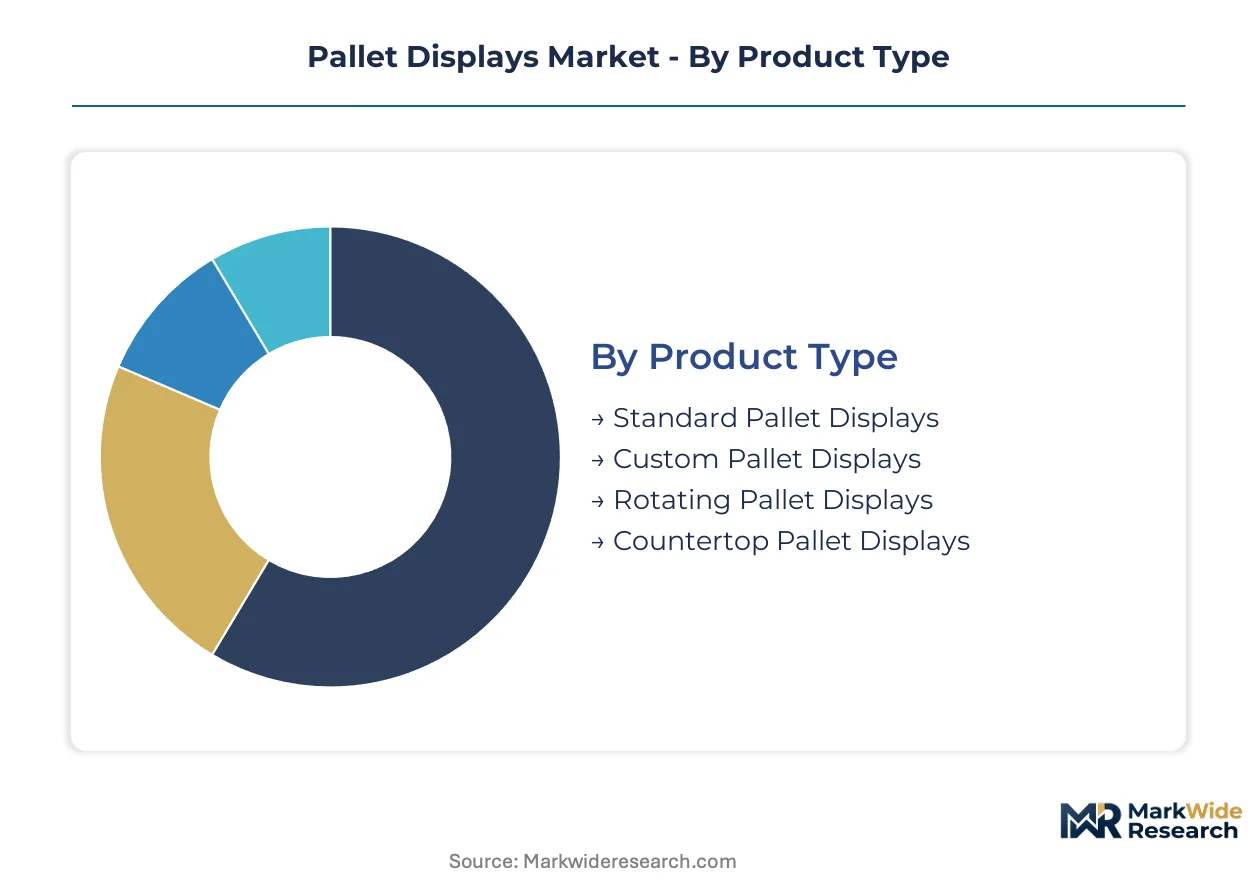
Pallet displays fragment across four structural dimensions that determine procurement economics and engineering specifications. Product type governs unit economics and customization depth, while material selection locks in recyclability credentials and load-bearing performance under retail automation protocols.
Product Type:
Mature formats dominate volume, though emerging configurations are capturing margin pools through automation compatibility and aisle differentiation.
- Standard Pallet Displays:Pre-engineered footprints with fixed dimensions optimize for high-velocity SKUs and robotic handling systems in German distribution centers. Retail chains in France and Germany specify these for automated guided vehicle compatibility, compressing restocking labor.
- Custom Pallet Displays:Die-cut structures with brand-specific geometries and integrated digital elements command premium positioning. US club stores and European supermarkets deploy these for seasonal campaigns requiring aisle differentiation.
- Rotating Pallet Displays:Turntable bases enable 360-degree product access in constrained retail footprints.
- Countertop Pallet Displays:Reduced-height variants serve checkout-adjacent impulse merchandising in convenience and grocery channels.
Standard pallet displays retain volume leadership; custom pallet displays hold the steepest expansion curve.
Material:
Cost tier separation runs from commodity fiberboard to engineered polymers, with compliance regimes fragmenting procurement portfolios across jurisdictions.
- Cardboard:Corrugated board with post-consumer certified content dominates unit economics and printability for promotional campaigns. EU Packaging and Packaging Waste Regulation mandates are accelerating transitions toward certified recycled fiber in Germany and France.
- Plastic:Polypropylene and HDPE variants capture reusable closed-loop programs in retail chains with reverse logistics infrastructure. France's extended producer responsibility schemes and Germany's VerpackG amendments now block single-use plastic deployments in certain channels.
- Wood:Hardwood and softwood pallet bases serve heavy-load industrial and beverage applications.
- Metal:Steel and aluminum frames anchor permanent fixture installations with multi-year depreciation cycles.
Cardboard commands absolute volume; plastic faces regulatory compression in core European markets.
End User:
Application intensity varies by channel automation level and floor-ready merchandising maturity.
- Supermarkets:Floor-ready pallet displays eliminate backroom handling entirely, with chains mandating direct forklift-to-aisle placement. German retailers lead automation integration, specifying standardized footprints for robotic handling protocols.
- Retail Stores:Mass merchandisers and specialty chains deploy mixed formats for promotional density and brand block formation.
- Warehouses:Bulk storage and cross-dock operations prioritize structural durability over print aesthetics.
- E-commerce:Fulfillment centers utilize display-ready packaging for last-mile efficiency in direct-to-consumer shipments.
Supermarkets drive specification authority; e-commerce represents the most volatile demand trajectory.
Distribution Channel:
Customer type fragmentation reflects disintermediation trends as retailers bypass traditional supplier hierarchies.
- Direct Sales:Specialized converters maintain engineering relationships with retail category buyers at Costco and Sam's Club, bypassing CPG brand managers. US club channels concentrate procurement authority in dedicated display engineering teams.
- Offline Retail:Traditional distributor networks serve mid-market retailers without captive specification capabilities.
- Online Retail:Digital procurement platforms aggregate small-format orders for regional promotional campaigns.
- Wholesalers:Inventory-based distribution serves price-sensitive segments with standardized specifications.
Direct sales channels are gaining share fastest; wholesale relationships face margin compression from specification disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corrugated board production clusters in Germany, the United States, and China supply the structural substrates for pallet display manufacturing. Automated converting lines in these markets serve both domestic retail chains and export-oriented display producers. Regulatory divergence across jurisdictions fragments material certification requirements.
United States
Club store chains mandate floor-ready pallet displays with direct forklift-to-aisle placement, compressing restocking labor. The EPA governs recycled content claims and forestry certification benchmarks affecting material sourcing. Georgia-Pacific LLC operates multiple corrugating plants across the Southeast and Midwest that feed retail-ready display production.
Germany
Automated guided vehicles in distribution centers require standardized pallet footprints aligned with robotic handling protocols. The EU Packaging and Packaging Waste Regulation and national VerpackG amendments mandate recyclability documentation and restrict single-use plastic components. Retail automation and sustainability mandates converge in Baden-Württemberg and North Rhine-Westphalia.
China
Domestic retail chains and export-oriented display producers absorb new automated converting line capacity. The country's national packaging standards regulator enforces material safety benchmarks for displays near consumables. Yangtze River Delta and Pearl River Delta clusters house integrated containerboard-to-display manufacturing operations.
France
Extended producer responsibility schemes block reusable plastic pallet programs in certain retail channels, accelerating cardboard transitions. ANSM and national environmental agencies enforce packaging waste documentation requirements. Île-de-France and Auvergne-Rhône-Alpes concentrate converter operations serving supermarket and hypermarket chains.
India
Reliance Retail and D-Mart adopt Western-style floor-ready merchandising, creating first-mover advantage for corrugated display suppliers. BIS standards govern structural packaging material specifications. Maharashtra and Gujarat host emerging converting capacity targeting organized retail expansion.
Pallet Displays Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate supply and structural engineering. The vendor base separates into three strategic tiers: integrated containerboard-to-display manufacturers, specialized converting operations, and captive retail engineering teams. Two dominant competitive moves define positioning: backward integration into recycled fiber networks and direct procurement relationships bypassing traditional CPG brand hierarchies.
Within the integrated tier, DS Smith plc and Smurfit WestRock plc exemplify platform dominance through captive paper networks and continental manufacturing footprints. Georgia-Pacific LLC anchors the North American scale vector with multi-plant corrugating operations feeding display production. Among specialized converters, Menasha Packaging Company, LLC occupies a position bridging structural engineering and retail-specific specification authority.
| Leading Market Players |
|---|
| Sonoco Products Company |
| DS Smith plc |
| Smurfit WestRock plc |
| International Paper Company |
| WestRock Company |
| Pratt Industries |
| Georgia-Pacific LLC |
| Menasha Packaging Company, LLC |
| Siffron, Inc. |
| Others |
Value Chain & Pricing Dynamics
OCC spot market volatility in North American fiber networks compresses converter margins unpredictably, forcing pricing tier spreads to widen between certified post-consumer corrugated and virgin board while reshaping procurement toward long-term offtake contracts with integrated paper suppliers.
Pricing Analysis
The EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across member states, separating certified post-consumer corrugated displays from standard fiberboard through recyclability documentation requirements. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with German supermarket chains absorbing premium positioning for automation-compatible footprints. Cost compression in standard cardboard tiers is intensifying because recycled fiber cost volatility compresses converter margins. Mass merchandisers in the US club channel exhibit highest price sensitivity, while European retailers with EPR mandates demonstrate lowest sensitivity due to compliance-driven specification authority.
Supply Chain Analysis
Integrated containerboard-to-display manufacturers in Germany, the United States, and China hold captive converting capacity serving both domestic retail chains and export-oriented producers. Supply chains draw from OCC recovery networks, virgin kraft pulp streams, and adhesive bonding chemistries, with structural engineering talent scarcity emerging as a binding constraint. Single-source vulnerability concentrates in German distribution automation protocols, where standardized pallet footprints for robotic handling lack alternative specification pathways. Distribution runs through direct sales relationships with retail category buyers, bypassing traditional CPG brand hierarchies in US club channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pallet displays market is entering a cyclical recovery phase as supermarket chains compress restocking cycles through floor-ready merchandising mandates, with automation integration in German distribution centers serving as the primary cyclical driver.
For Market Incumbents: Entrench specification authority by deepening captive recycled fiber networks and acquiring structural engineering capabilities in Baden-Württemberg and North Rhine-Westphalia, where retail automation and sustainability mandates converge. Defend against disintermediation threats from retail category buyers by embedding directly into Costco and Sam's Club display engineering teams. For New Entrants and Emerging Players: Pursue India's organized retail expansion, where Reliance Retail and D-Mart adoption of Western-style floor-ready merchandising creates first-mover positioning without incumbent saturation. Target NFC-enabled pallet displays for real-time inventory tracking as the most penetrable application segment, leveraging digital printing partnerships to bypass capital-intensive corrugating infrastructure. For Investors and Strategic Acquirers: California SB 54 implementation reshapes the acquisition landscape by creating compliance service revenue streams for display manufacturers offering material documentation. Long-term viability centers on platform integrators with backward integration into recycled paper networks and continental manufacturing footprints. Monitor EU harmonization timelines for packaging waste regulation as the signal to watch for material portfolio reallocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Networks | DS Smith plc leverages European OCC recovery infrastructure to secure certified post-consumer content supply. |
| NFC-Enabled Display Integration | Real-time inventory tracking capabilities align with German retail automation protocols and robotic handling systems. |
| Direct Retail Category Buyer Relationships | US club channels concentrate procurement authority in dedicated display engineering teams bypassing CPG hierarchies. |
| Lightweight Cardboard Engineering Investment | Advances in fluting profiles expand load capacity without increasing material weight for forklift-to-aisle placement. |
| India Organized Retail Expansion | Maharashtra and Gujarat converting capacity targets Reliance Retail and D-Mart floor-ready merchandising adoption. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with corrugated board stress analysts, retail category buyers at supermarket chains, converter procurement leads, and distribution center automation engineers; alongside secondary validation through EU Packaging and Packaging Waste Regulation documentation, EPA recycled content claim filings, SEC 10-K disclosures from integrated paper companies, and customs records for corrugated display trade flows. Bottom-up and top-down triangulation cross-validated unit economics and demand aggregation.
Forecast inputs considered product type segmentation across standard, custom, rotating, and countertop pallet displays; material tiers spanning cardboard, plastic, wood, and metal; end-user channel intensity in supermarkets, retail stores, warehouses, and e-commerce; and distribution pathway fragmentation between direct sales, offline retail, online retail, and wholesalers. CAGRs were derived through demand elasticity modeling against retail automation deployment curves and EPR scheme implementation schedules.
Sensitivities concentrate around OCC spot price volatility, EU regulatory harmonization timelines, and German robotic handling protocol standardization. Forecasts reflect assumptions regarding supermarket chain restocking cycle compression and club store aisle width constraints. Quarterly review of recycled fiber cost indices, retail automation deployment announcements, and state-level packaging legislation progression is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Global Pallet Racking System Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
Pallet Corner Boards Market