
 Hang Tag Applicators Market | 2026-2036
Hang Tag Applicators Market Size, Share, and Industry Trends Forecast 2026-2036
Hang Tag Applicators Market Foresight
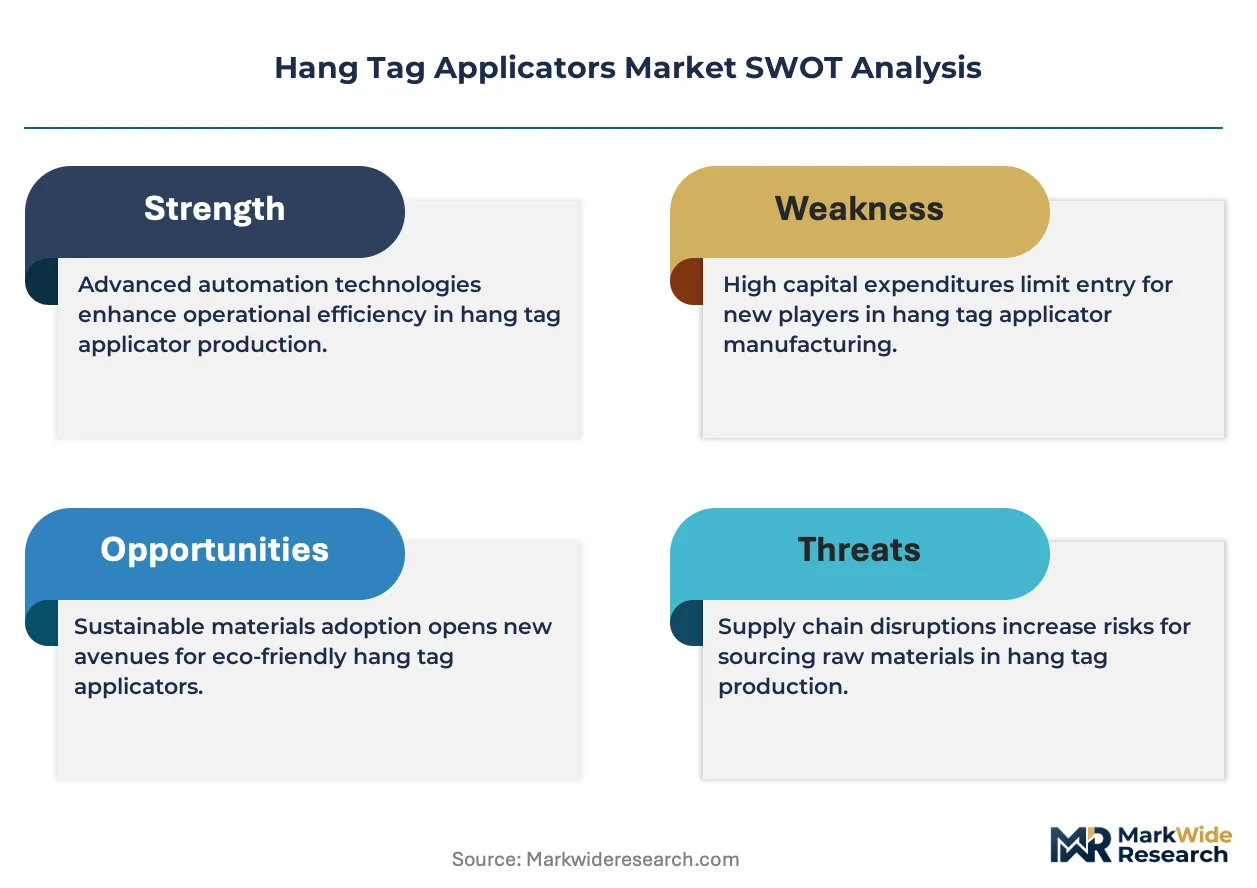
Recycled PET and biodegradable substrates are recalibrating hang tag economics as brands face pressure to eliminate virgin plastics. Avery Dennison Corporation leverages its materials science portfolio to develop sustainable fastening substrates that reduce environmental compliance costs. Markem-Imaje anchors European demand through precision pneumatic systems engineered for high-speed garment lines. Sato Holdings Corporation dominates Asian supply chains with electromechanical applicators calibrated for mixed-material tags.
A hang tag applicator is a mechanical or electromechanical device that affixes pricing, branding, or tracking tags to consumer goods through needle penetration, adhesive bonding, or clip attachment, typically operating at speeds of 20–120 tags per minute depending on automation level. Its primary purpose is to ensure accurate, consistent product identification across retail and logistics environments while minimizing manual labor and tag misplacement. Automated applicators command the largest installed base among product types due to their throughput advantages in high-volume apparel operations, though RFID-integrated systems represent the fastest-expanding technology segment as retailers deploy item-level tracking. E-commerce platforms constitute an accelerating end-user category, driven by return-processing requirements that demand precise tag-to-SKU matching.
The US Federal Trade Commission's Green Guides and the EU's REACH framework govern chemical content in tag substrates and adhesives, directly influencing applicator compatibility requirements and supplier qualification protocols. China's SAMR enforces GB standards for mechanical safety that shape electromechanical system designs exported from manufacturing hubs. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer to another, complicating platform standardization strategies.
Market Dynamics
Apparel retailers are consolidating tagging operations into centralized fulfillment centers, compressing demand for standalone applicators while amplifying requirements for high-throughput, multi-format systems capable of handling variable SKU batches.
Growth Catalysts
- RFID Mandates in North America:Major retailers are deploying item-level tracking infrastructure, requiring applicators with integrated encoding capabilities to meet supply chain visibility requirements.
- China Manufacturing Clusters:Contract producers in Guangdong and Zhejiang provinces serve global fashion brands with turnkey applicator-label integration, capturing economies of scale in equipment deployment.
- REACH Compliance in Europe:Chemical restrictions on tag substrates are accelerating replacement cycles for older pneumatic systems incompatible with biodegradable fastening materials.
Market Restraints
- Electronics Component Concentration:Servo motors and precision sensors for electromechanical applicators concentrate among Taiwanese and German suppliers, creating input vulnerability.
- Technical Speed Ceilings:Needle-based mechanical systems face hard limits near 120 tags per minute, constraining throughput for ultra-high-volume fast fashion lines.
- Substitution by Direct Printing:Inkjet and laser marking technologies for synthetic fabrics eliminate tag requirements entirely in specific garment categories.
Strategic Opportunities
- India Apparel Manufacturing:The country's Production Linked Incentive scheme for textiles is attracting greenfield garment facilities lacking automated tagging infrastructure.
- Reverse Logistics Integration:E-commerce return processing centers require applicators capable of re-tagging returned inventory with updated pricing and condition codes.
- Biodegradable Substrate Convergence:Combining electromechanical precision with compostable fastening materials addresses sustainability mandates in EU and North American markets simultaneously.
Industry Challenges
- Mechatronics Talent Scarcity:Maintenance of precision electromechanical systems requires technicians skilled in both mechanical calibration and PLC programming, a combination scarce in emerging manufacturing hubs.
- Legacy Pneumatic Integration:Retrofitting RFID encoding modules into existing compressed-air applicator lines demands custom engineering without standardized mounting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hang Tag Applicators Market |
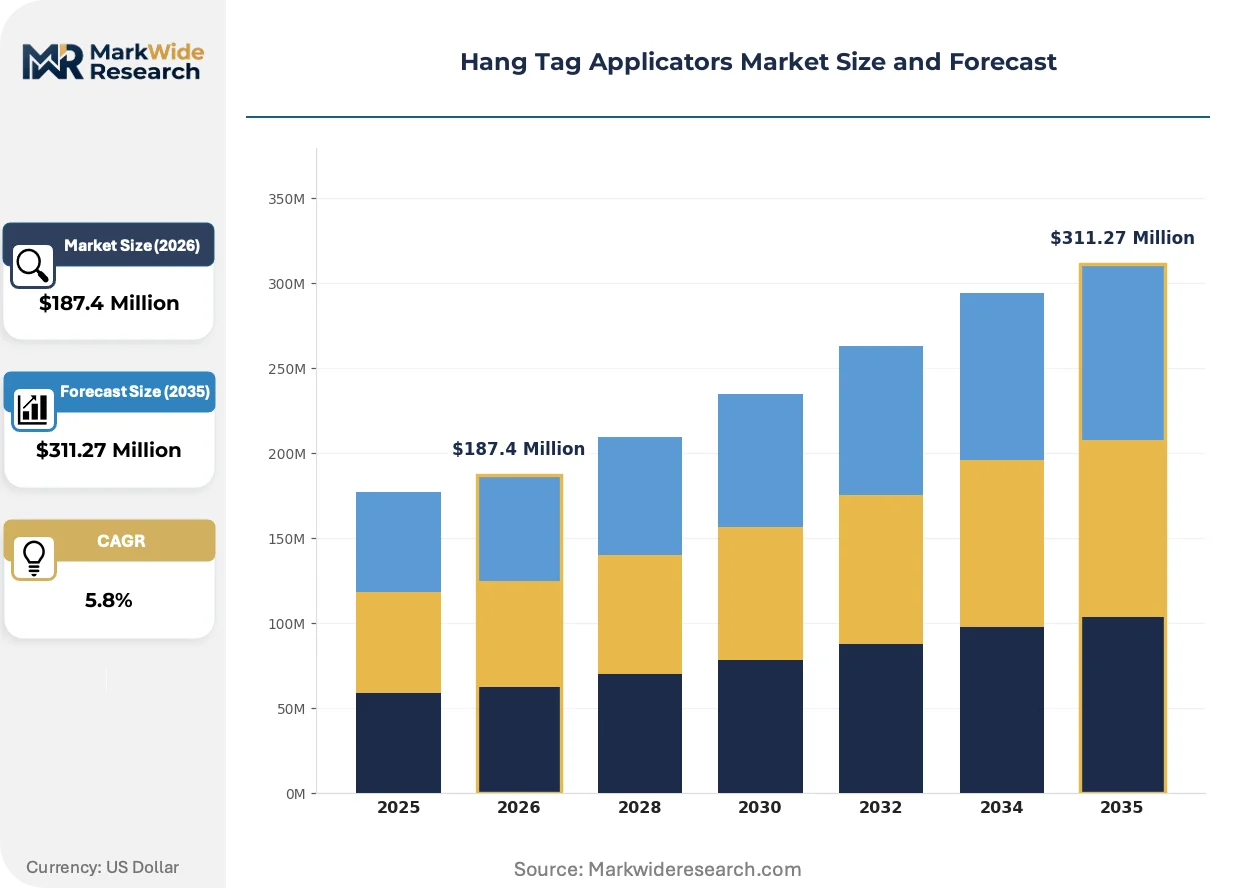
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Applicators, Automated Applicators, Semi-Automated Applicators, Tagging Guns End User: Retailers, Manufacturers, Logistics Providers, E-commerce Platforms Technology: Electromechanical, Pneumatic, Manual Mechanisms, RFID Systems Application: Fashion Industry, Food Packaging, Electronics, Home Goods |
| Companies Covered | Avery Dennison Corporation, Markem-Imaje, Sato Holdings Corporation, TSC Auto ID Technology Co., Ltd., Checkpoint Systems, Northfield Corporation, Kenco Label & Tag Co., LLC, Graphic Packaging International, Inc., Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hang Tag Applicators Market Shifts & Advancements
Automation architectures are bifurcating between high-speed fixed-line systems for mass production and flexible collaborative applicators for small-batch customization, with control software emerging as the primary differentiation layer.
Electromechanical servo-driven applicators are overtaking traditional pneumatic mechanisms in new installations across premium apparel segments. These systems deliver sub-millimeter placement accuracy required for RFID antenna alignment. European luxury houses and North American specialty retailers are specifying servo platforms for 60% of new capital expenditure. The shift is compressing maintenance intervals while expanding compatible substrate range from paper to woven and synthetic materials.
REACH substance restrictions and the EU Green Deal's packaging waste directives are forcing substrate reformulation across European supply chains. Manufacturers must validate applicator compatibility with starch-based adhesives and cellulose-derived fasteners that exhibit different tensile properties than petroleum-based alternatives. German and Italian equipment suppliers are releasing modular needle assemblies with adjustable penetration depth to accommodate these material transitions without full system replacement.
Brand procurement departments are consolidating vendor relationships from point-solution suppliers to integrated platform providers capable of delivering applicator, substrate, and data management as unified contracts. This behavior concentrates purchasing power among three to four equipment-label-software bundles per major retailer. The pattern is most pronounced in US and UK markets where chief procurement officers hold direct authority over store operations capital allocation.
Hang Tag Applicators Market Segmentation
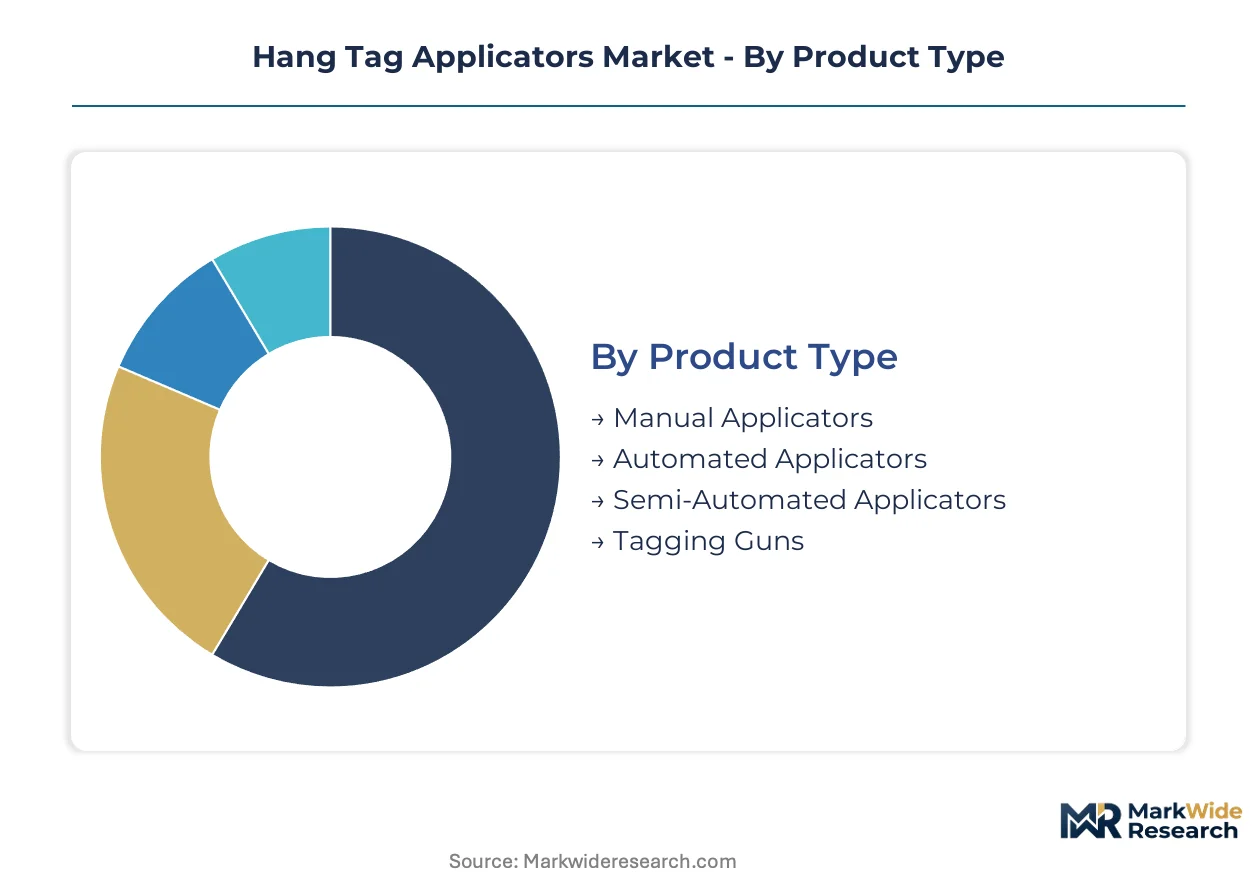
Hang tag applicator procurement decisions diverge sharply across automation levels and end-use requirements, with capital deployment patterns revealing which customer segments prioritize throughput over flexibility. Understanding these segment boundaries clarifies where technology investments concentrate and where legacy systems retain residual value.
Product Type:
Capital intensity escalates dramatically from handheld tools to servo-driven production lines, creating distinct financing and depreciation profiles across the equipment spectrum.
- Automated Applicators:These systems integrate programmable logic controllers with servo motor arrays to achieve placement precision within 0.5 millimeters at sustained operating speeds. Apparel fulfillment centers in Bangladesh and Vietnam deploy these units to meet contract terms with European fast fashion brands that mandate 99.5% tag accuracy for RFID-enabled inventory. The upfront equipment cost typically amortizes across 18-24 months in high-volume environments.
- Semi-Automated Applicators:Hybrid configurations pair human loading stations with automated fastening mechanisms, occupying the middle ground between throughput and labor retention. Turkish garment exporters favor this category to maintain workforce flexibility while satisfying retailer velocity requirements. Operators can reconfigure these units for mixed-material tags without engineering support.
- Manual Applicators:Handheld tagging guns and needle devices serve micro-retailers and boutique operations where volume variability defeats automation economics. Chinese factory-direct suppliers dominate this price-sensitive tier through Shenzhen-based component sourcing.
- Tagging Guns:Spring-loaded mechanical devices deliver single-tag application for repair services, sample rooms, and pop-up retail environments. Japanese precision manufacturers lead this niche with hardened steel needle assemblies rated for 50,000 cycles.
Most installed capacity flows through Automated Applicators. Expansion is steepest in Semi-Automated Applicators as mid-tier manufacturers hedge against demand volatility.
End User:
Procurement authority and technical specification complexity vary substantially across the value chain, with each end user imposing distinct validation protocols on equipment suppliers.
- Manufacturers:Contract garment producers in China's Guangdong province specify applicator-label bundles as turnkey packages, integrating equipment with substrate supply agreements. These buyers prioritize mean-time-between-failures metrics and 24-hour technical support availability. Capital budgets here concentrate in electromechanical systems with RFID encoding modules.
- E-commerce Platforms:Return processing centers require applicators capable of re-tagging inventory with dynamic pricing and condition codes, driving demand for software-integrated systems with database connectivity. Amazon's fulfillment network and Alibaba's Cainiao facilities have established proprietary specifications that shape supplier R&D priorities.
- Retailers:Department store chains and specialty apparel brands deploy applicators in centralized distribution centers rather than individual stores, consolidating tagging operations for cost control. These buyers emphasize multi-format compatibility across seasonal SKU rotations.
- Logistics Providers:Third-party warehouse operators serving multiple retail clients demand rapid format changeover capabilities to handle disparate tagging standards. DHL Supply Chain and similar operators specify modular applicator architectures with tool-less needle assembly swaps.
Equipment value capture concentrates with Manufacturers. E-commerce Platforms are climbing the fastest as reverse logistics infrastructure expands.
Technology:
Mechanism selection determines maintenance cadence, energy consumption, and substrate compatibility range, with trade-offs between precision and operational simplicity.
- Electromechanical:Servo-driven systems with closed-loop position feedback enable sub-millimeter tag placement accuracy required for RFID antenna alignment. European luxury houses and North American specialty retailers specify these platforms for premium garment handling where mechanical stress must be minimized.
- RFID Systems:Integrated encoding applicators write EPC data during the attachment cycle, eliminating separate encoding stations. Walmart's item-level tracking mandates and similar retailer requirements in Germany and France are accelerating deployment of these combined-function systems.
- Pneumatic:Compressed-air mechanisms retain installed base in legacy production lines but face replacement pressure from REACH compliance costs and energy efficiency regulations. Italian equipment suppliers continue supporting these systems through modular retrofit kits.
- Manual Mechanisms:Purely mechanical devices without power assistance persist in artisanal production and regulatory environments with limited electrical infrastructure. Indian handloom cooperatives and African textile initiatives represent residual demand pockets.
Technology investment flows predominantly toward Electromechanical platforms. RFID Systems are expanding most quickly as supply chain visibility mandates proliferate.
Application:
Product category characteristics dictate tag substrate variety, attachment point accessibility, and throughput requirements, segmenting applicator specifications across consumer goods verticals.
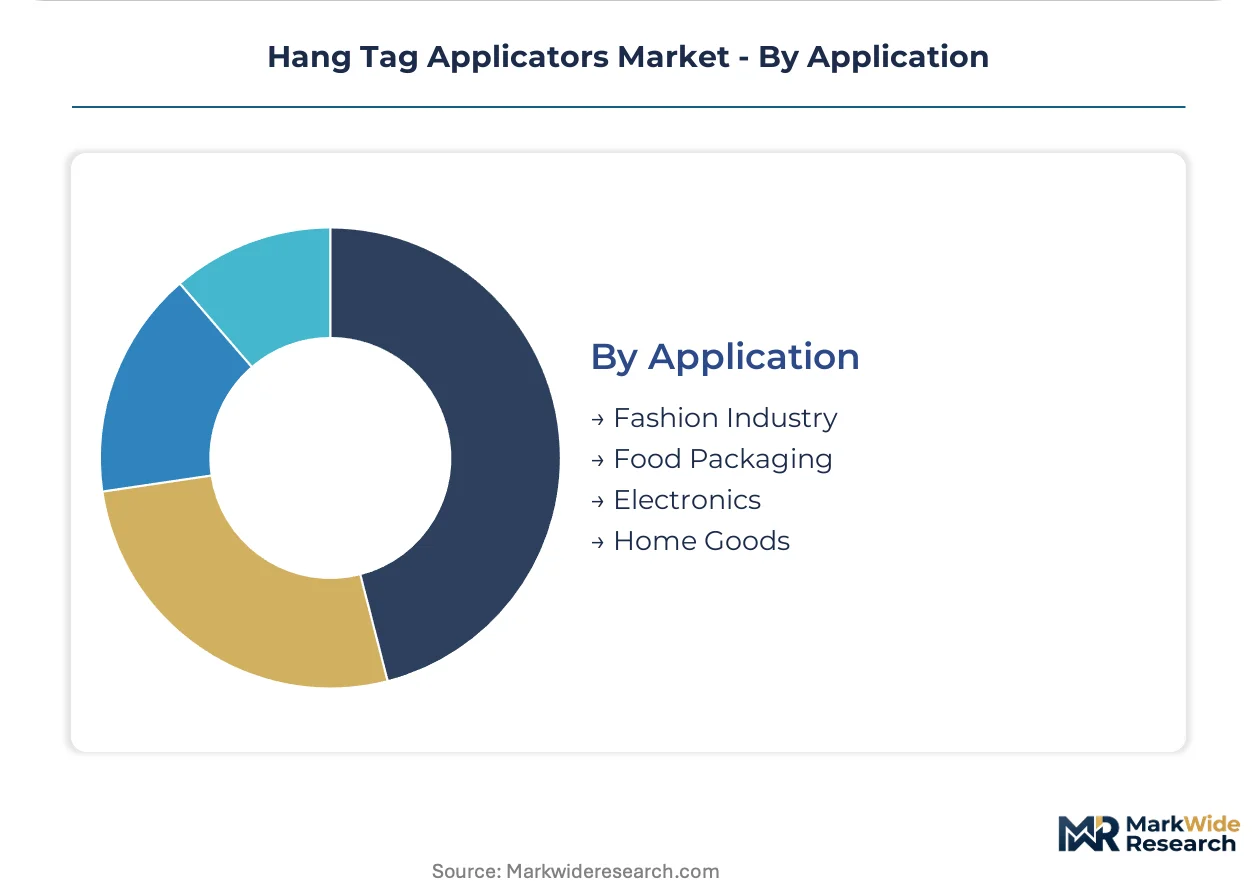
- Fashion Industry:Garment tagging demands handling of woven labels, synthetic heat-transfer substrates, and compostable paper alternatives with varying tensile properties. Applicators here require adjustable penetration depth and programmable pressure curves to prevent fabric damage.
- Food Packaging:Hygiene regulations and moisture-resistant substrate requirements shape equipment specifications, with stainless steel construction and washdown-rated enclosures common in this segment. Label attachment must not compromise package integrity.
- Electronics:Small-form-factor devices and anti-static requirements limit applicator size and mandate grounding protocols. Tag placement on compact consumer electronics emphasizes precision over speed.
- Home Goods:Variable product geometries from textiles to hard goods create demand for flexible applicator configurations with extended reach arms and custom fixturing options.
Application volume concentrates in Fashion Industry. Food Packaging is gaining share fastest as sustainable packaging regulations drive tagged outer packaging requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors equipment deployment through contract manufacturers supplying integrated applicator-label bundles to global fashion brands.
United States
Amazon's fulfillment network and Walmart's item-level RFID mandates drive demand for software-integrated re-tagging systems. The FTC's Green Guides govern chemical content in tag substrates, forcing applicator recalibration for biodegradable materials. Chicago and Dallas logistics corridors concentrate third-party warehouse operators requiring rapid format changeover capabilities.
Germany
European luxury houses specify servo-driven platforms for premium garment handling with sub-millimeter placement accuracy. REACH substance restrictions and the EU Green Deal's packaging waste directives accelerate replacement cycles for legacy pneumatic systems. Bavarian equipment suppliers release modular needle assemblies with adjustable penetration depth for starch-based adhesives.
China
Guangdong and Zhejiang manufacturing clusters serve global fashion brands with turnkey applicator-label integration capturing economies of scale. SAMR enforces GB standards for mechanical safety shaping electromechanical system designs exported from production hubs. Shenzhen-based component sourcing dominates price-sensitive manual applicator tiers.
India
The Production Linked Incentive scheme for textiles attracts greenfield garment facilities lacking automated tagging infrastructure. BIS certification requirements influence equipment specifications for imported electromechanical systems. Maharashtra and Gujarat textile belts concentrate mid-tier manufacturers hedging demand volatility with semi-automated configurations.
Vietnam
Apparel fulfillment centers deploy automated units to meet contract terms with European fast fashion brands mandating RFID accuracy. The country's national standards body regulates mechanical safety for imported equipment. Ho Chi Minh City industrial zones concentrate contract producers upgrading from manual to servo-driven tagging lines.
Hang Tag Applicators Market Competitive Landscape
Global majors compete with regional champions across technology integration and substrate compatibility dimensions. The vendor base organizes around three tiers: diversified materials science conglomerates with applicator divisions, precision equipment specialists focused on servo-driven platforms, and regional fabricators serving price-sensitive manual tool segments. Consolidation pressure intensifies as brand procurement departments consolidate vendor relationships toward integrated platform providers. Strategic moves concentrate on portfolio diversification into biodegradable substrate compatibility and geographic expansion through distribution partnerships in emerging manufacturing hubs.
Within the diversified conglomerate tier, Avery Dennison Corporation represents integrated materials-to-equipment positioning, while Sato Holdings Corporation exemplifies Asian supply chain dominance through electromechanical specialization. Markem-Imaje anchors European demand through precision pneumatic heritage transitioning toward servo platforms. Checkpoint Systems and Zebra Technologies occupy positions spanning RFID encoding integration and data management convergence. These five entities collectively illustrate the competitive spectrum from substrate science through automated application to supply chain visibility software.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Markem-Imaje |
| Sato Holdings Corporation |
| TSC Auto ID Technology Co., Ltd. |
| Checkpoint Systems |
| Northfield Corporation |
| Kenco Label & Tag Co., LLC |
| Graphic Packaging International, Inc. |
| Zebra Technologies |
| Others |
Supply & Pricing Matrix
Performance-grade divergence between servo-driven electromechanical systems and legacy pneumatic platforms manifests in both pricing stratification and supply chain configuration. Premium servo applicators command three-to-four-fold unit economics over compressed-air alternatives, with that premium reflecting Taiwanese servo motor sourcing and German precision sensor integration rather than assembly labor.
Pricing Analysis
Input-cost pass-through from concentrated electronics suppliers shapes three-tier pricing structure across premium, standard, and economy levels. Certification grade—specifically CE marking for European deployment and UL listing for North American facilities—drives price differentiation alongside after-sales service bundling. Pricing pressure stems from contract manufacturers in Guangdong province demanding volume discounts for turnkey applicator-label packages. Mid-tier Turkish garment exporters exhibit highest price sensitivity, while European luxury houses prioritize placement accuracy over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese servo motor fabricators and German precision sensor specialists, creating input concentration risk for electromechanical platform assemblers. Manufacturing draws from China, Germany, and Italy for final system integration, with raw material dependencies spanning rare-earth magnets, hardened steel needle assemblies, and programmable logic controllers. Tariff exposure on Chinese-assembled units entering North American markets represents the dominant supply chain risk. Distribution runs through direct OEM relationships with major apparel brands and regional equipment distributors serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India, where Production Linked Incentive subsidies for textiles offset capital equipment costs unavailable in mature manufacturing clusters like Vietnam or Bangladesh.
For Market Incumbents: Deepen backward integration into biodegradable substrate production to capture margin compression from REACH compliance mandates. Expand technical service capacity in Ho Chi Minh City industrial zones to defend installed base against emerging Chinese competitors. Electromechanical platform differentiation and RFID encoding module integration represent critical defensive levers against substitution by direct-to-garment printing technologies. For New Entrants and Emerging Players: E-commerce platform direct sales channels offer lowest customer acquisition friction for semi-automated applicator categories. Target India's Maharashtra and Gujarat textile belts, where greenfield facilities lack automated tagging infrastructure and procurement protocols remain unconsolidated. Position around rapid format changeover capabilities for third-party logistics operators serving multiple retail clients. For Investors and Strategic Acquirers: Consolidation pressure builds where brand procurement departments demand unified applicator-substrate-data management contracts exceeding regional fabricator capabilities. Five-to-ten year viability favors diversified materials science conglomerates with captive substrate development. Acquisition targets should display modular electromechanical architectures compatible with starch-based adhesive transitions. Monitor Walmart and Amazon proprietary specification releases as inflection signals for RFID-integrated system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Integration | REACH compliance in Germany and EU Green Deal mandates accelerate replacement cycles for legacy pneumatic systems. |
| Servo Platform R&D Expansion | European luxury houses specify sub-millimeter placement accuracy for RFID antenna alignment in premium garment handling. |
| India Distribution Partnership | PLI scheme for textiles attracts greenfield garment facilities lacking automated tagging infrastructure in Maharashtra. |
| Reverse Logistics Capability Buildout | Amazon's fulfillment network and Alibaba's Cainiao facilities establish proprietary re-tagging specifications. |
| RFID Encoding Module Acquisition | Walmart's item-level tracking mandates in the United States drive combined-function system deployment. |
Research Methodology
Direct dialogue with equipment procurement managers at contract manufacturers, maintenance directors at apparel fulfillment centers, plant engineers in Guangdong province, and aftermarket service heads at European equipment suppliers grounded qualitative assessment. Secondary validation drew from SAMR GB standard filings, ECHA REACH substance restriction updates, US FTC Green Guide revisions, and customs records for electromechanical applicator trade flows. Bottom-up installation base estimates triangulated against top-down capital expenditure patterns across the apparel value chain.
Segment-level outputs across the projection horizon reflect modeled interactions between automation level, technology mechanism, and end-user procurement authority. The analytical framework incorporated product type, end user category, technology platform, and application vertical as core segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves responding to RFID mandate proliferation and biodegradable substrate transition timelines. Industry-specific inputs included retailer tagging accuracy specifications and mean-time-between-failures benchmarks for centralized fulfillment center operations.
The model assumes a particular technology adoption path; alternative pathways for direct-to-garment printing would alter the outlook for mechanical applicator demand. Forecasts reflect assumptions regarding regulatory enforcement consistency for REACH substance restrictions and retailer RFID mandate adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Container Washing System Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Plastic Hopper Loader Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Thermal Impulse Sealers Market
Packaging Equipment
Retail Press Dispenser Pump Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Hand Sealers Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Packaging Tensioner Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Hydrapulper Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Flow Wrap Packaging Market