
 Latin America Plastic Packaging Films Market | 2026-2036
Latin America Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Plastic Packaging Films Market Insights
Modular pouch configurations with resealable closures and portion-controlled compartments is expanding choice among Latin American food manufacturers and personal care brands. Berry Global Inc leverages its continental manufacturing footprint to sustain supply agreements with multinational beverage packers. FLEX AMERICAS SA de CV anchors its position through specialized polyethylene production for high-clarity food wraps across Mexico and Central America. Cosmo Films differentiates via R&D intensity in co-extruded barrier structures for pharmaceutical blister packs.
Latin America plastic packaging films are polymer-based sheet materials typically ranging from 12 to 150 microns in thickness, manufactured through blown film extrusion, cast extrusion, or biaxial orientation processes to provide moisture barriers, mechanical protection, and shelf-life extension for consumer and industrial goods. Flexible films dominate volume throughput across the region due to their compatibility with form-fill-seal equipment and lower freight cost per unit shipped. Barrier films command premium positioning in food packaging and healthcare applications where oxygen and water vapor transmission rates determine product integrity. Polyethylene leads material consumption by tonnage, though polypropylene is displacing alternatives in high-temperature retort pouches for ready-meal adoption.
Brazil's ANVISA enforces migration limits for food-contact plastics that reshape formulation choices among compounders serving the São Paulo packaging cluster. Mexico's PROFEPA and SEMARNAT coordinate extended producer responsibility enforcement that elevates compliance costs for imported multilayer structures while creating preference for locally recyclable mono-material designs. Stakeholders must monitor pending harmonization between Mercosur technical regulations and Andean Community standards to anticipate cross-border product registration requirements and testing protocol shifts.
Market Dynamics
Extended producer responsibility mandates from SEMARNAT are forcing multilayer film converters toward mono-material redesigns, reshaping formulation priorities across Mexico's central highlands manufacturing belt and Brazil's São Paulo corridor.
Growth Catalysts
- Retort pouch adoption:Ready-meal manufacturers across Brazil are scaling polypropylene-based high-temperature films to replace metal cans in shelf-stable protein packaging.
- ANVISA migration compliance:Brazil's food-contact plastic regulations are accelerating investment in barrier co-extrusion capabilities among compounders serving the domestic market.
- Pharmaceutical blister demand:Healthcare packaging specifications for oxygen and moisture barriers are pulling specialized co-extruded structures into production across the region.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs fluctuate with naphtha-cracker economics tied to Pemex supply disruptions and import dependency.
- Multilayer recyclability limits:Current mechanical recycling infrastructure cannot process barrier films with EVOH or metallized layers, creating landfill diversion penalties.
- Import concentration risk:Specialty barrier resins and masterbatch additives concentrate in US Gulf Coast and Asian supply origins, exposing converters to freight and currency exposure.
Strategic Opportunities
- Central American underpenetration:Guatemala and Costa Rica present white space for high-clarity food wrap capacity as regional trade integration deepens.
- Chemical recycling partnerships:Pyrolysis and depolymerization investments are creating offtake agreements for post-industrial film scrap previously landfilled.
- Digital printing convergence:HP Indigo and EFI-equipped converters are capturing shorter-run flexible packaging demand from craft food brands seeking SKU proliferation.
Industry Challenges
- Co-extrusion technician scarcity:Blown film lines with seven-layer capability require operators trained in rheology and die geometry optimization, a skillset concentrated in legacy São Paulo facilities.
- Migration testing backlog:ANVISA's updated food-contact notification queue extends certification timelines for new barrier formulations, delaying commercial launches by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Plastic Packaging Films Market |
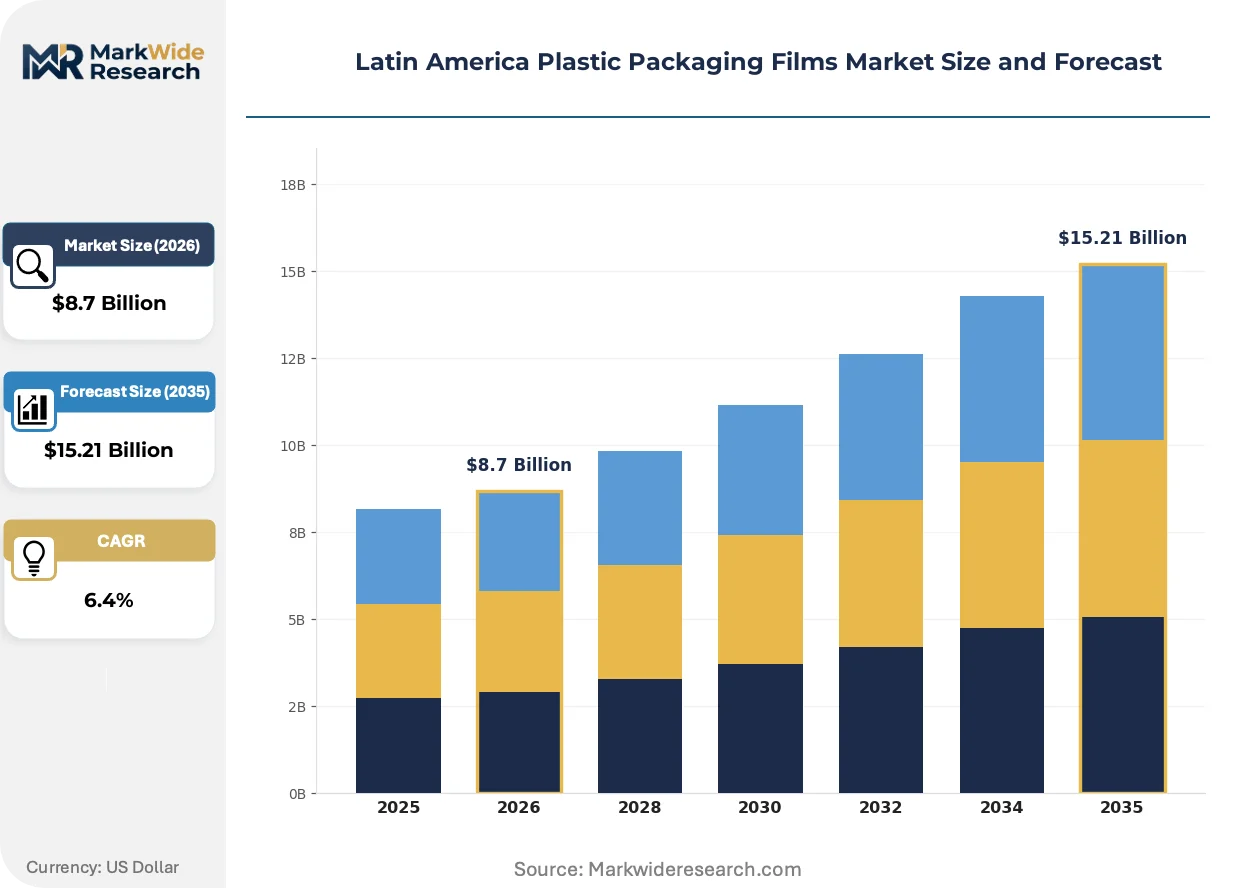
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Barrier Films, Shrink Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Application: Food Packaging, Personal Care, Healthcare, Industrial Packaging End User: Food Manufacturers, Beverage Packers, Pharmaceuticals, Retailers |
| Companies Covered | Taghleef Industries Group, Cosmo Films, Berry Global Inc, PLAMI SA DE CV, Evertis de Mexico S, FLEX AMERICAS SA de CV, Poly Rafia SA De CV, PYLA SA de CV, Innovia Films, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Plastic Packaging Films Market Trends and Innovations
Film functionality is fragmenting into application-specific stacks where barrier performance, seal integrity, and end-of-life pathways are engineered simultaneously rather than sequentially.
Mono-material polyethylene structures with plasma-enhanced barrier deposition are converging with conventional multilayer performance at lower gram weights. Brazilian meat exporters are piloting these films for vacuum-packed beef cuts destined for Middle Eastern markets. The technology is converging with existing form-fill-seal infrastructure, avoiding capital replacement cycles for processors.
PROFEPA's coordinated enforcement with SEMARNAT on extended producer responsibility is elevating compliance documentation requirements for imported film structures. Converters serving multinational beverage brands must now certify recyclability pathways or face import restrictions. The regulatory pressure is compressing demand toward locally produced mono-material alternatives with established collection infrastructure.
Brand procurement teams are consolidating supplier panels around film partners offering integrated design-to-recyclability services. Personal care multinationals operating in Mexico's Querétaro and Guanajuato manufacturing zones now require lifecycle assessment documentation as a bid qualification threshold. This specification compression favors converters with in-house analytical laboratories and polymer science capabilities over commodity distributors.
Latin America Plastic Packaging Films Market Segmentation
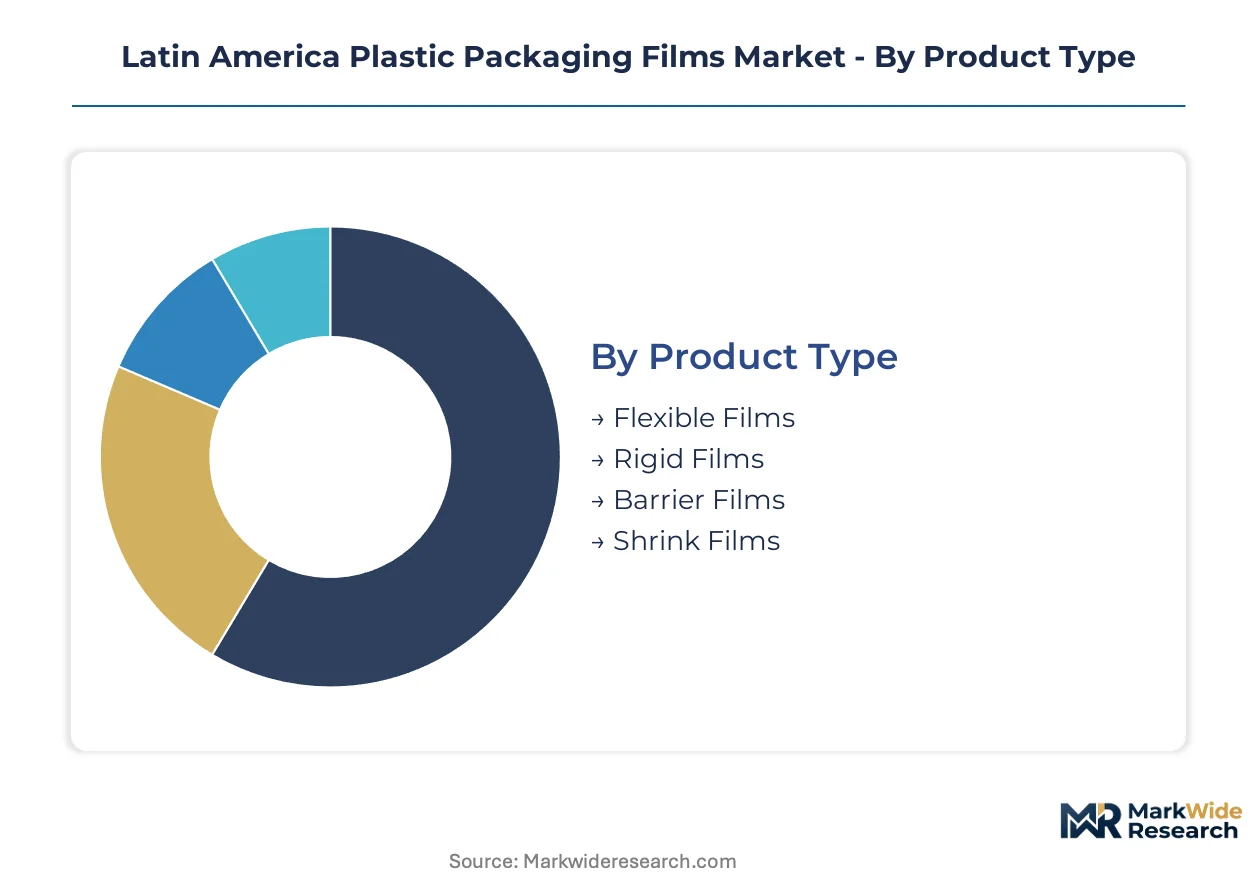
Segmentation in Latin America plastic packaging films reflects divergent performance requirements across temperature tolerance, barrier specifications, and regulatory compliance. Buyers prioritize material selection and film construction based on shelf-life targets, processing equipment compatibility, and end-of-life obligations under national extended producer responsibility frameworks.
Product Type:
Equipment compatibility and unit economics drive converter procurement decisions, with freight cost per square meter and form-fill-seal throughput rates determining film format selection.
- Flexible Films:Polymer structures ranging 12-150 microns manufactured through blown or cast extrusion, dominating volume throughput across Brazil's São Paulo corridor due to compatibility with high-speed packaging lines and reduced shipping cube versus rigid alternatives. São Paulo-based meat processors specify these films for vacuum-packed beef exports to Middle Eastern markets where barrier performance must withstand extended supply chains.
- Barrier Films:Co-extruded or metallized constructions incorporating EVOH or aluminum oxide layers to achieve oxygen transmission rates below 1 cc/m²/day, commanding premium positioning in pharmaceutical blister packs and retort-ready meal applications. Mexico's central highlands manufacturing belt pulls these structures for shelf-stable protein packaging as ready-meal adoption accelerates.
- Rigid Films:Thermoformable sheets typically 200-500 microns for tray and clamshell applications, serving fresh produce merchandising in Colombian and Peruvian retail chains.
- Shrink Films:Biaxially oriented polyethylene terephthalate or polyvinyl chloride constructions for unitization and retail display, concentrated in beverage multipack bundling across Mexican bottling operations.
Flexible films lead on scale; barrier films lead on momentum.
Material:
Resin selection hinges on thermal processing requirements, with melting point differentials determining suitability for retort, hot-fill, or ambient applications.
- Polyethylene:Linear low-density and metallocene grades comprising the majority of tonnage consumption, favored for seal layer functionality and cost efficiency in high-volume food wraps. Brazilian compounders serving ANVISA-regulated markets invest in migration-compliant formulations with reduced oligomer content.
- Polypropylene:Oriented and cast variants displacing alternatives in high-temperature retort pouches, with homopolymer grades gaining share in ready-meal packaging as Brazil's processed food sector expands. The material's 160°C melting point enables steam sterilization protocols that polyethylene cannot withstand.
- Polyvinyl Chloride:Remaining concentration in shrink sleeve labels and medical blister applications, facing substitution pressure from PET-G in environmentally sensitive procurement specifications.
- Others:Polyamide and ethylene vinyl alcohol copolymers serving niche barrier layer applications in multilayer constructions, with EVOH supply concentrated in US Gulf Coast and Asian import origins.
Polyethylene dominates absolute volume; polypropylene climbs the fastest on retort pouch conversion.
Application:
End-use performance specifications fragment demand, with oxygen and moisture transmission thresholds varying by product sensitivity and shelf-life extension targets.
- Food Packaging:The dominant application absorbing flexible and barrier film capacity, spanning vacuum-packed proteins, modified atmosphere produce bags, and lidding for thermoformed trays. Brazil's beef export sector and Mexico's tortilla and snack manufacturing anchor regional demand concentration.
- Healthcare:Pharmaceutical blister packs and medical device pouches requiring compliance with migration limits and sterility assurance, with ANVISA and COFEPRIS notification queues extending certification timelines for new barrier formulations.
- Personal Care:Sachets, pouches, and flow-wrap for cosmetics and hygiene products, with multinational brand owners in Querétaro and Guanajuato requiring lifecycle assessment documentation as bid qualification thresholds.
- Industrial Packaging:Stretch wrap, pallet unitization films, and construction membrane applications, competing with recycled content specifications in sustainability-focused procurement.
Food packaging leads on scale; healthcare leads on specification intensity.
End User:
Procurement sophistication varies by buyer scale, with multinational beverage and pharmaceutical operators imposing integrated design-to-recyclability requirements on converter panels.
- Food Manufacturers:Brazilian meat processors and Mexican snack and bakery operations driving flexible film specification, with migration testing backlogs at ANVISA delaying new product launches. These buyers prioritize seal integrity and optical clarity for retail presentation.
- Beverage Packers:Multinational bottlers in Mexico's central highlands and Brazil's southeast consolidating supplier relationships around partners offering mono-material recyclability certification to satisfy PROFEPA and SEMARNAT extended producer responsibility enforcement.
- Pharmaceuticals:Demanding oxygen and moisture barrier performance with full regulatory documentation, sourcing specialized co-extruded structures from converters with in-house analytical laboratories.
- Retailers:Private label specifications increasingly incorporating recyclability pathway documentation, with Central American chains in Guatemala and Costa Rica presenting white space for high-clarity food wrap capacity expansion.
Food manufacturers lead on volume absorption; beverage packers lead on supplier consolidation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Latin America plastic packaging films industry traces its industrial lineage to the 1970s petrochemical buildout along Brazil's São Paulo corridor and Mexico's Gulf Coast, when state-led import substitution policies established extrusion capacity to serve domestic consumer goods manufacturing.
Brazil
ANVISA migration limits for food-contact plastics are accelerating reformulation investments among compounders serving the São Paulo packaging cluster. Beef exporters in the São Paulo industrial corridor specify vacuum-packed barrier films for Middle Eastern markets. The city's legacy blown film facilities concentrate seven-layer co-extrusion technician expertise.
Mexico
PROFEPA and SEMARNAT coordination on extended producer responsibility is elevating compliance documentation for imported multilayer structures. Beverage packers in the central highlands manufacturing belt consolidate supplier panels around mono-material recyclability certification. Querétaro and Guanajuato zones impose lifecycle assessment thresholds on converter bids.
Argentina
Meat processing consolidation around Buenos Aires is pulling flexible film demand for vacuum-packed protein exports. The national industrial promotion agency channels credit toward packaging sector modernization. Rosario's agro-industrial hub anchors soybean oil and flour packaging film consumption.
Chile
Salmon export cold-chain requirements are driving barrier film specification for extended maritime shelf life. The environmental ministry's plastic reduction roadmap pressures converters toward recyclable mono-material designs. Santiago's packaging converters serve retail chains across the Andean region.
Colombia
Processed food manufacturing expansion in Bogotá's savanna zone is absorbing flexible film capacity for snack and bakery applications. The national food and drug surveillance institute enforces food-contact notification protocols. Medellín's industrial valley hosts thermoforming operations for fresh produce tray applications.
Latin America Plastic Packaging Films Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology and regulatory compliance capabilities. The market structure fragments between multinational resin-integrated operations, regional converter specialists, and local distribution-focused fabricators. Three archetypes dominate: resin-backward-integrated multinationals, co-extrusion technology specialists, and commodity film distributors with logistics scale. Competitive moves center on backward integration into resin compounding and strategic partnerships with brand owners for design-to-recyclability service bundling.
Among the named players, Berry Global Inc exemplifies the multinational resin-integrated archetype through its continental manufacturing footprint. FLEX AMERICAS SA de CV anchors the regional specialist tier with polyethylene production concentration for high-clarity applications. Cosmo Films occupies a position representing R&D-intensive differentiation in barrier structures. Taghleef Industries Group and Innovia Films represent European-origin multinationals with regional production presence. The remaining listed entities—PLAMI SA DE CV, Evertis de Mexico S, Poly Rafia SA De CV, and PYLA SA de CV—exemplify Mexico-based converter operations serving national and Central American markets.
| Leading Market Players |
|---|
| Taghleef Industries Group |
| Cosmo Films |
| Berry Global Inc |
| PLAMI SA DE CV |
| Evertis de Mexico S |
| FLEX AMERICAS SA de CV |
| Poly Rafia SA De CV |
| PYLA SA de CV |
| Innovia Films |
| Others |
Pricing and Supply Chain Analysis
Ethylene feedstock costs originating from Pemex naphtha crackers and US Gulf Coast import channels cascade through polyethylene resin quotations to converter pricing tiers across Mexico's central highlands and Brazil's São Paulo corridor. Brazilian compounders serving ANVISA-regulated markets absorb migration-testing overhead into premium-grade formulations, while commodity distributors compete on freight-optimized spot volumes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified barrier film converters with in-house analytical laboratories from regional specialists and commodity distributors. Price differentiation rests on ANVISA compliance documentation and mono-material recyclability certification versus generic multilayer offerings. Pricing pressure stems from ethylene feedstock volatility tied to Pemex supply disruptions. Beverage packers in Mexico's Querétaro zone exhibit highest price sensitivity due to PROFEPA documentation requirements, while pharmaceutical blister pack buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
SEMARNAT's domestic-content documentation requirements for extended producer responsibility compliance are reshaping sourcing patterns toward locally produced mono-material alternatives with established collection infrastructure. Raw material supply draws from US Gulf Coast specialty barrier resin origins, Asian EVOH copolymer import channels, and regional polyethylene production at Brazilian petrochemical complexes. Single-source vulnerability concentrates in metallized layer and masterbatch additive supply chains. Distribution runs through converter-direct relationships with multinational beverage brands and pharmaceutical OEMs, bypassing traditional distributor networks for specification-intensive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ANVISA migration testing backlogs in Brazil and PROFEPA enforcement intensity in Mexico create cost and timeline differentials for converters with dual-territory laboratory capabilities.
For Market Incumbents: To counter co-extrusion technician scarcity concentrated in legacy São Paulo facilities, backward integration into resin compounding secures formulation control while capacity expansion in Central American white-space markets captures regional trade integration benefits. Certification investment in lifecycle assessment documentation satisfies Querétaro and Guanajuato procurement thresholds. For New Entrants and Emerging Players: Enter via Guatemala and Costa Rica high-clarity food wrap segments where regional retailer procurement sophistication lags Mexican and Brazilian benchmarks. Chemical recycling offtake partnerships for post-industrial scrap offer differentiated service bundling. Target craft food brand digital printing demand through HP Indigo-equipped toll conversion arrangements. For Investors and Strategic Acquirers: Consolidation pressure builds where converter panels fragment between resin-integrated multinationals and commodity distributors lacking analytical laboratory capabilities. Five-to-ten-year viability favors R&D-intensive barrier specialists with pharmaceutical certification queues over pure-play polyethylene distributors. Monitor ANVISA notification queue clearance rates as inflection indicator for Brazilian formulation launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Redesign Investment | PROFEPA enforcement elevates recyclability certification to bid qualification threshold. |
| Chemical Recycling Partnership | Pyrolysis offtake agreements monetize post-industrial scrap previously diverted to landfill. |
| Seven-Layer Co-Extrusion Capacity Addition | Retort pouch adoption in Brazilian ready-meals pulls specialized high-temperature film demand. |
| Digital Printing Convergence | HP Indigo-equipped converters capture SKU proliferation from craft food brands. |
| Central American Geographic Expansion | Guatemala and Costa Rica present underpenetrated white space as trade integration deepens. |
Research Methodology
Direct dialogue with blown film plant managers, ANVISA regulatory affairs specialists, beverage packer procurement leads, and pharmaceutical packaging engineers grounded qualitative assessment in operational realities. Secondary validation drew from Brazilian customs trade records, ANVISA food-contact notification databases, SEMARNAT extended producer responsibility filings, and polyethylene resin price assessments. Bottom-up capacity estimates triangulated against top-down demand absorption across the analysis window.
Value projections across the modeling period reflect segmentation by product type, material grade, application performance tier, and end-user procurement sophistication. CAGRs derived from elasticity-adjusted volume trajectories incorporating ethylene feedstock price band sensitivity and regulatory compliance cost pass-through assumptions. Retort pouch conversion rates and pharmaceutical blister pack specification intensity served as industry-specific demand drivers.
Inputs from converter production disclosures and regulatory notification queues were available through the study window; gaps in real-time resin inventory positioning and undisclosed masterbatch formulation costs introduce uncertainty bands around margin compression scenarios. Forecasts reflect documented assumptions on ANVISA queue clearance velocity and PROFEPA enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Starch-Based Plastic Films Market
Poly film
Bundling Film Market
Poly film
Polystyrene Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Embossed Film Market
Poly film
Cellulose Film Packaging Market
Poly film
APET Film Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Peelable and Resealable Films Market
Poly film
North America BOPP Films Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Stretch Films Packs Market
Poly film
UAE Plastic Packaging Films Market
Poly film
North America Plastic Film Packaging Market
Poly film
North America Polyimide Films Market
Poly film
Twist Wrap Film Market