
 Vietnam Plastic Packaging Films Market | 2026-2036
Vietnam Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Plastic Packaging Films Market Insights
Vietnam's National Action Plan on Marine Plastic Waste Management is rebalancing procurement priorities across the packaging value chain. Rang Dong Long An Plastic JSC leverages integrated blown film extrusion to sustain cost leadership in polyethylene supply for domestic food processors. Polifilm Vietnam Co. Ltd. anchors its position through specialized multilayer barrier films serving export-oriented seafood packers. A.J. Plast (Vietnam) Co. Ltd. differentiates via controlled-atmosphere film technologies for tropical fruit logistics.
Plastic packaging films are thermoplastic polymer sheets, typically 10 to 150 microns thick, manufactured through cast or blown extrusion processes and engineered for moisture barrier, tensile strength, and heat-seal functionality. Polyethylene films dominate volume throughput due to their versatility in food contact applications and compatibility with existing converting equipment. Polypropylene films command premium positioning in medical supplies and electronics where clarity and sterilization tolerance matter. Thin films are gaining share in lightweighting initiatives while heavy films retain margin pools in industrial pallet wrapping and agricultural coverage.
The Ministry of Natural Resources and Environment enforces circular economy roadmaps that mandate recycled content thresholds, while the Vietnam Chemicals Agency monitors phthalate and heavy metal compliance under national technical regulations aligned with ASEAN harmonized standards. BIS-equivalent conformity assessment procedures for food-contact materials are tightening market access for unverified imports. Stakeholders must monitor enforcement cadence around extended producer responsibility frameworks to anticipate retrofitting timelines for existing extrusion assets.
Market Dynamics
Vietnam's National Action Plan on Marine Plastic Waste Management is compressing formulation timelines across the packaging value chain. Extrusion asset owners face immediate retrofitting decisions as recycled content mandates phase in ahead of technical readiness.
Growth Catalysts
- Regulatory mandate:The Ministry of Natural Resources and Environment's circular economy roadmap is forcing food-contact film suppliers to certify recycled content thresholds.
- Seafood export demand:Barrier-grade multilayer films are capturing procurement volumes from Ho Chi Minh City-based processors shipping to EU markets under EFSA compliance requirements.
- Biodegradable feedstock:Cassava-derived PLA formulations are displacing conventional polyethylene in fresh produce wrapping across southern retail chains.
Market Restraints
- Petrochemical input volatility:Ethylene and propylene spot pricing swings are compressing margin pools for non-integrated blown film extruders in Binh Duong province.
- Technical limitation:Current mechanical recycling infrastructure cannot deliver food-grade rPET flake at the purity levels required by Vietnam Chemicals Agency technical regulations.
- Substitution threat:Molded fiber and paper-based barrier coatings are capturing premium shelf-ready packaging slots from rigid film formats in beverage multipacks.
Strategic Opportunities
- Underpenetrated geography:Central Highlands coffee processors in Dak Lak and Lam Dong provinces remain underserved by high-barrier film distributors, creating first-mover whitespace.
- Regulatory tailwind:Extended producer responsibility frameworks scheduled for enforcement will reward early adopters of mono-material recyclable structures with compliance cost advantages.
- Technology convergence:Digital printing integration with blown film lines is enabling short-run customization for regional brand owners previously locked out of rotogravure minimums.
Industry Challenges
- Certification timeline compression:BIS-equivalent conformity assessment procedures for food-contact materials are extending approval cycles beyond typical procurement windows.
- Capex intensity:Seven-layer coextrusion lines required for high-barrier seafood applications demand capital commitments that strain mid-tier converters in Long An province.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Plastic Packaging Films Market |
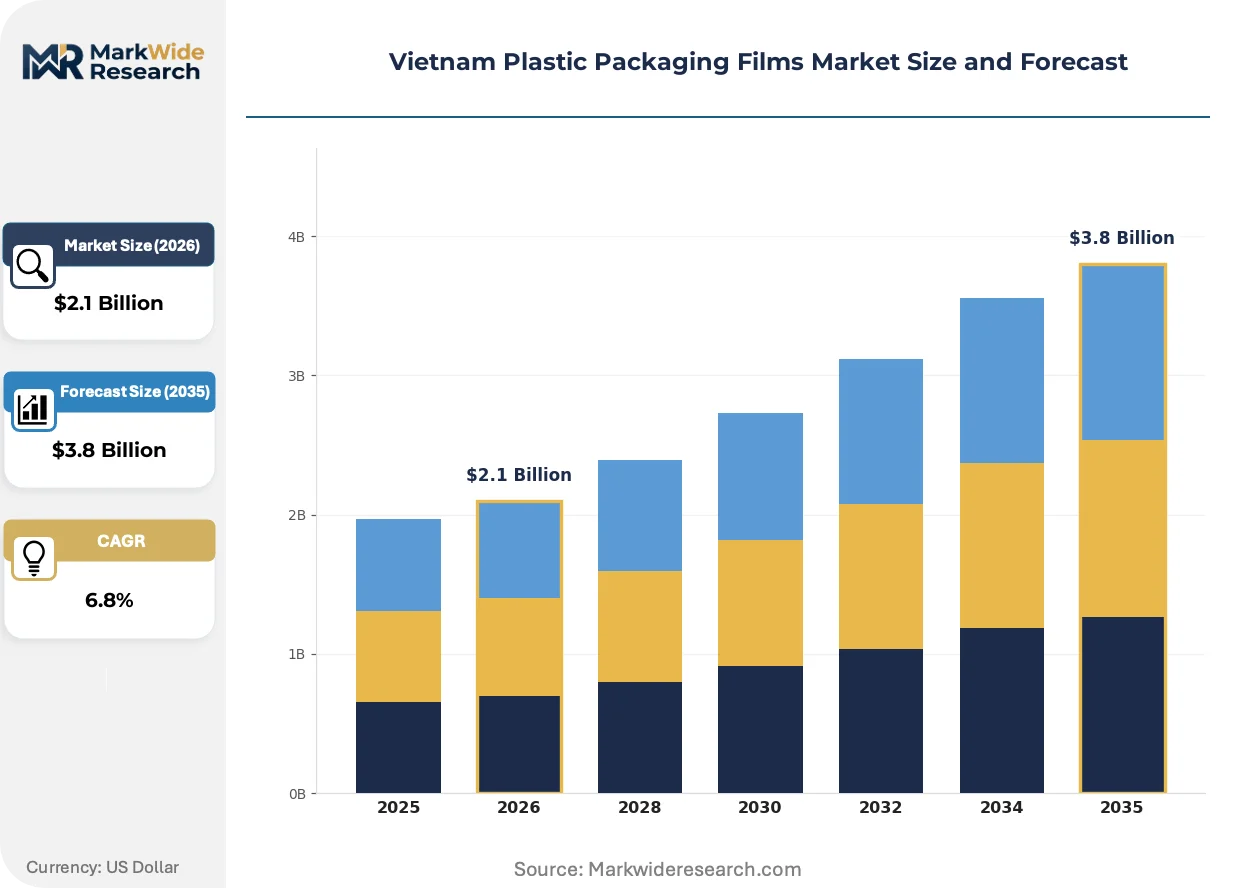
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Food Packaging, Medical Supplies, Consumer Goods, Industrial Packaging Thickness: Thin Films, Medium Films, Heavy Films, Micro Films End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics |
| Companies Covered | Rang Dong Long An Plastic JSC, Polifilm Vietnam Co. Ltd., IFC Plastic Co., Ltd., Feliz Plastic Vietnam Co., Ltd., Vietnam Packing Group, A.J. Plast (Vietnam) Co. Ltd., Nan Ya Plastics Corp (Vietnam), Dai Dong Tien Plastic Packaging JSC, Tan Tien Plastic Packaging Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Plastic Packaging Films Market Trends and Innovations
Digitalization and material science advances are compressing product development cycles while regulatory stringency is locking in formulation standards. Vietnamese converters face simultaneous pressure to lightweight, barrier-enhance, and circularize film outputs.
Mono-material polyethylene structures with enhanced ethylene vinyl alcohol compatibility layers are rewriting barrier performance benchmarks for tropical fruit logistics. A.J. Plast and regional competitors are retrofitting lines to produce these formats for dragon fruit and mango exporters. The technology is compressing demand for legacy nylon-containing multilayer constructions that complicate mechanical recycling streams.
Vietnam Chemicals Agency enforcement of phthalate and heavy metal limits under ASEAN-harmonized technical regulations is accelerating laboratory certification investments. Domestic compounders must now document compliance through accredited testing before commercial release. Food-contact film segments serving infant nutrition and pharmaceutical packaging are absorbing the highest compliance costs.
Contract manufacturing arrangements are displacing captive film production among mid-sized food processors in the southern industrial corridor. Third-party toll extruders in Binh Duong are capturing volume through flexible minimum order quantities and faster color matching. This pattern concentrates procurement leverage with converters holding redundant extrusion assets across multiple resin platforms.
Vietnam Plastic Packaging Films Market Segmentation
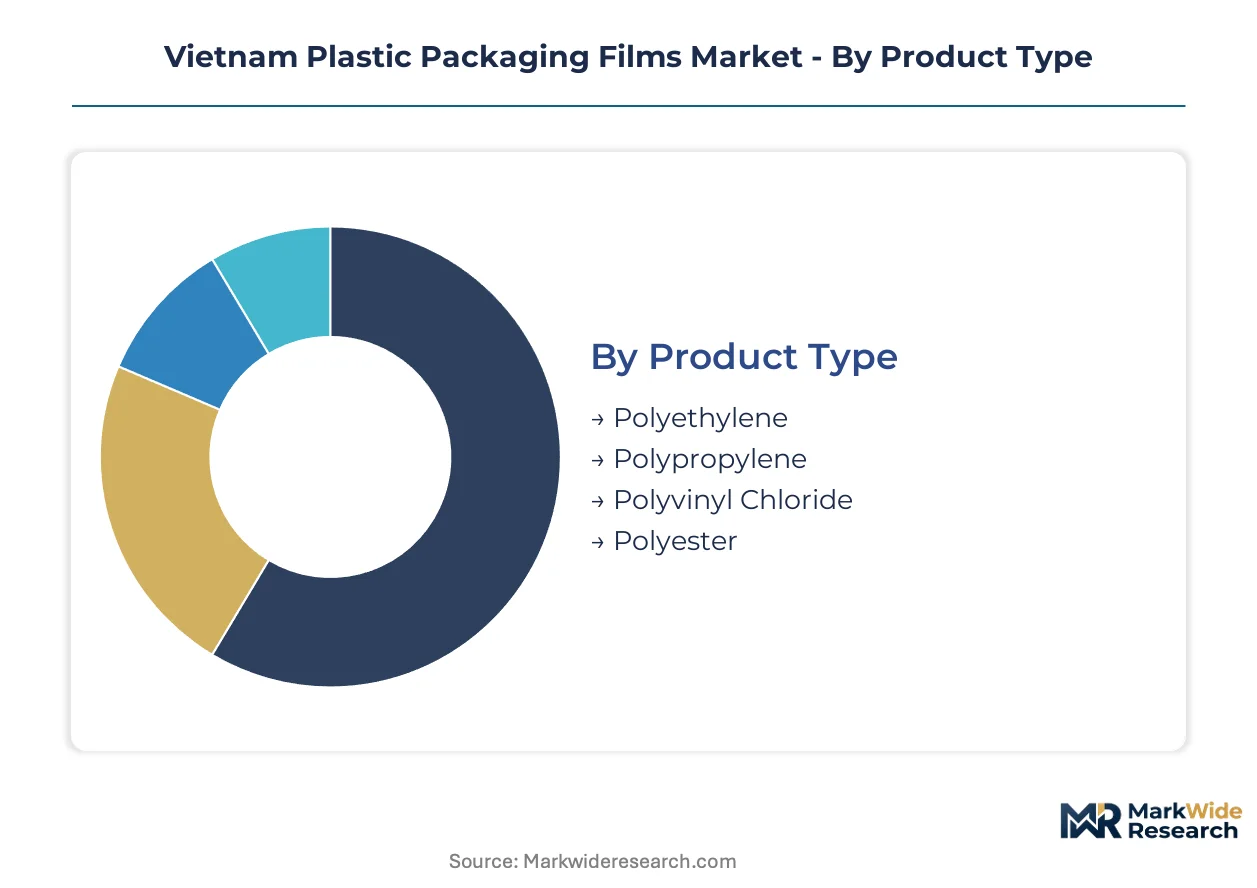
Segmentation in Vietnam's plastic packaging films market reveals how regulatory compliance burdens and technical specifications fragment procurement patterns across resin platforms and end-use applications. Distinct certification pathways for food-contact versus medical-grade materials create divergent margin pools that reshape competitive positioning.
Product Type:
Certification requirements vary sharply across polymer chemistries. Polyethylene and polypropylene formulations face Vietnam Chemicals Agency scrutiny for heavy metal content under ASEAN-harmonized technical regulations. PVC and polyester grades trigger additional phthalate testing protocols for food-contact and medical applications.
- Polyethylene:Blown and cast extrusion formats dominate throughput across the southern industrial corridor. Ho Chi Minh City-based food processors specify low-density grades for fresh produce wrapping where heat-seal tolerance and moisture barrier performance drive procurement. Vietnam's recycled content mandates are compressing formulation timelines for post-consumer recyclate integration.
- Polypropylene:Biaxially oriented structures command premium positioning in medical supplies and electronics packaging where optical clarity and sterilization tolerance matter. Binh Duong converters are expanding metallized and coextruded barrier variants for export-oriented seafood processors requiring extended shelf-life performance.
- Polyvinyl Chloride:Shrink film and blister pack formats retain niche demand in pharmaceutical and personal care segments despite regulatory pressure on plasticizer chemistry.
- Polyester:High-tensile strength and dimensional stability position PET films in electronics component packaging and industrial lamination applications.
Leading the category by volume: Polyethylene. Growing fastest: Polypropylene.
Application:
Cost tier differentiation separates commodity wrapping from specialized barrier systems. Food packaging absorbs the highest absolute volume while medical and industrial segments capture superior unit economics through technical specification premiums.
- Food Packaging:Multilayer coextrusion and vacuum skin formats are displacing legacy single-ply constructions across fresh produce and processed meat segments. Long An province extruders are retrofitting seven-layer lines to serve dragon fruit and mango exporters requiring controlled-atmosphere performance.
- Medical Supplies:Sterilizable barrier films and peelable pouch structures face Vietnam's Ministry of Health registration requirements alongside international ISO compliance. Central Highlands pharmaceutical distributors are consolidating procurement with certified compounders to shorten approval cycles.
- Consumer Goods:Printed laminates and overwrap films for household products concentrate demand in high-throughput rotogravure converters.
- Industrial Packaging:Stretch wrap and shrink bundling formats for palletization and logistics applications prioritize tensile strength and puncture resistance over optical properties.
Food Packaging captures the dominant revenue share. Medical Supplies delivers the steepest margin expansion trajectory.
Thickness:
Volume concentration patterns reflect lightweighting imperatives versus durability requirements. Thin and micro film formats are gaining share in retail shelf-ready applications while heavy films retain industrial and agricultural demand.
- Thin Films:10-30 micron gauges dominate fresh produce wrapping and single-serve confectionery where material minimization reduces per-unit cost. Southern retail chains are specifying downgauged polyethylene for private-label vegetable packaging to meet extended producer responsibility thresholds.
- Heavy Films:100-150 micron structures retain demand in agricultural mulching and industrial pallet wrapping where puncture resistance and UV stability justify material intensity. Dak Lak coffee processors specify heavy-gauge silage films for bean storage and transport protection.
- Medium Films:Intermediate gauges balance barrier performance with converting efficiency across general-purpose food and consumer goods applications.
- Micro Films:Sub-10 micron experimental formats are emerging in premium electronics interleaving and pharmaceutical unit-dose packaging.
Thin Films lead absolute volume. Heavy Films sustain the most stable pricing environment.
End User:
Customer type fragmentation creates divergent service requirements. Food and beverage processors prioritize volume scale and color-matching flexibility while pharmaceutical buyers demand batch documentation and audit trails.
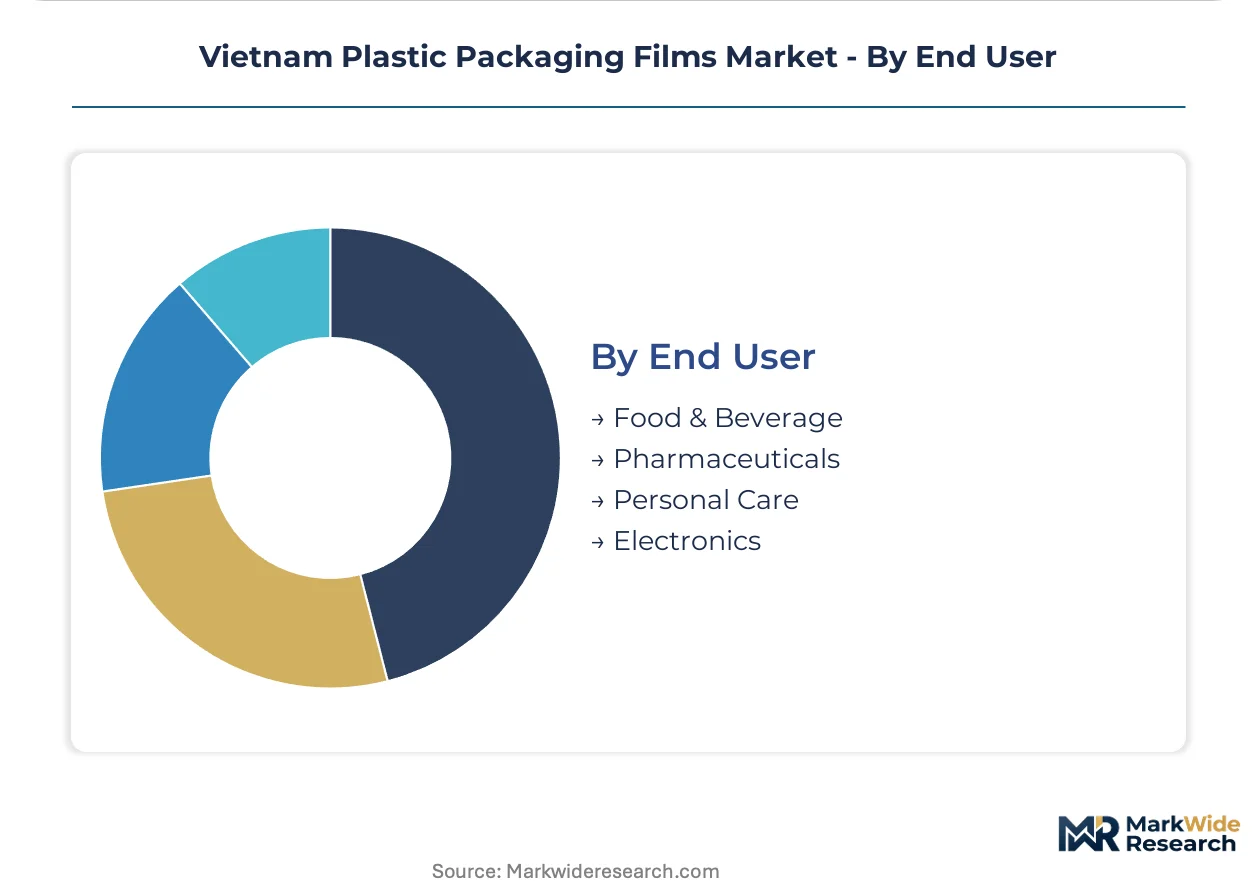
- Food & Beverage:Processed seafood, fresh produce, and beverage multipacks generate the highest procurement volumes across the southern industrial corridor. Export-oriented processors in Ho Chi Minh City are consolidating supplier relationships to secure EFSA-compliant documentation for EU market access.
- Pharmaceuticals:Blister foil laminates, cold-form structures, and sterilizable pouch films require Vietnam Ministry of Health registration and GMP-adjacent manufacturing protocols. Compliance costs are concentrating procurement with established compounders holding redundant certification.
- Personal Care:Printed overwrap and sachet films for cosmetics and hygiene products demand high-definition graphic reproduction and fragrance barrier properties.
- Electronics:Anti-static and moisture-barrier formats for semiconductor and component packaging prioritize cleanroom manufacturing and ionic contamination control.
Food & Beverage dominates procurement volume. Pharmaceuticals expands most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City anchors Vietnam's plastic packaging films demand through its southern industrial corridor, where Binh Duong and Long An provinces cluster blown film extrusion capacity serving food processors and seafood exporters.
Southeast Region
Ho Chi Minh City processors specify multilayer barrier films for dragon fruit and mango exports to EU markets under EFSA compliance requirements. Vietnam's Ministry of Natural Resources and Environment enforces recycled content thresholds through circular economy roadmaps that compress formulation timelines. Binh Duong province extruders retrofit seven-layer coextrusion lines to capture procurement volumes from export-oriented seafood packers.
Mekong Delta
Fresh produce wrapping for rice and vegetable distribution generates steady demand for downgauged polyethylene films across Can Tho and An Giang distribution hubs. The Vietnam Chemicals Agency monitors phthalate compliance under ASEAN-harmonized technical regulations that extend certification cycles. Long An province hosts integrated blown film operations supplying domestic food processors with cost-optimized polyethylene structures.
Central Highlands
Coffee processors in Dak Lak and Lam Dong provinces remain underserved by high-barrier film distributors, creating first-mover whitespace for controlled-atmosphere packaging. Extended producer responsibility frameworks scheduled for enforcement will reward early adopters of mono-material recyclable structures. Dak Lak silage film demand for bean storage and transport protection sustains heavy-gauge polyethylene procurement.
North Central Coast
Industrial packaging for logistics and palletization concentrates demand for stretch wrap and shrink bundling formats around Da Nang port operations. BIS-equivalent conformity assessment procedures for food-contact materials tighten market access for unverified imports. Thua Thien Hue province converters face technical limitations as mechanical recycling infrastructure cannot deliver food-grade rPET flake at required purity levels.
Northern Region
Hanoi-based pharmaceutical distributors consolidate procurement with certified compounders to shorten Ministry of Health registration cycles for sterilizable barrier films. Cassava-derived PLA formulations displace conventional polyethylene in fresh produce wrapping across northern retail chains. Bac Ninh and Hai Duong provinces attract electronics packaging demand for anti-static and moisture-barrier formats serving semiconductor manufacturers.
Vietnam Plastic Packaging Films Market Competitive Landscape
The competitive structure tilts toward integrated domestic converters with captive resin access and specialized multilayer specialists serving export compliance requirements. Mid-tier toll extruders capture volume through flexible minimum order quantities, fragmenting procurement leverage across redundant asset bases. Two archetypes dominate: vertically integrated compounders with backward resin control and technology-licensed specialists delivering barrier performance for tropical logistics. Competitive moves concentrate on line retrofitting for mono-material recyclable structures and digital printing integration for short-run customization.
Among integrated domestic producers, Rang Dong Long An Plastic JSC exemplifies the cost-optimized polyethylene supplier archetype through its Long An province positioning. Polifilm Vietnam Co. Ltd. represents the specialized multilayer barrier film segment serving export-oriented processors. A.J. Plast (Vietnam) Co. Ltd. anchors the controlled-atmosphere technology tier for tropical fruit logistics applications. These three occupy distinct competitive positions without direct overlap in technical specification or customer procurement patterns.
| Leading Market Players |
|---|
| Rang Dong Long An Plastic JSC |
| Polifilm Vietnam Co. Ltd. |
| IFC Plastic Co., Ltd. |
| Feliz Plastic Vietnam Co., Ltd. |
| Vietnam Packing Group |
| A.J. Plast (Vietnam) Co. Ltd. |
| Nan Ya Plastics Corp (Vietnam) |
| Dai Dong Tien Plastic Packaging JSC |
| Tan Tien Plastic Packaging Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
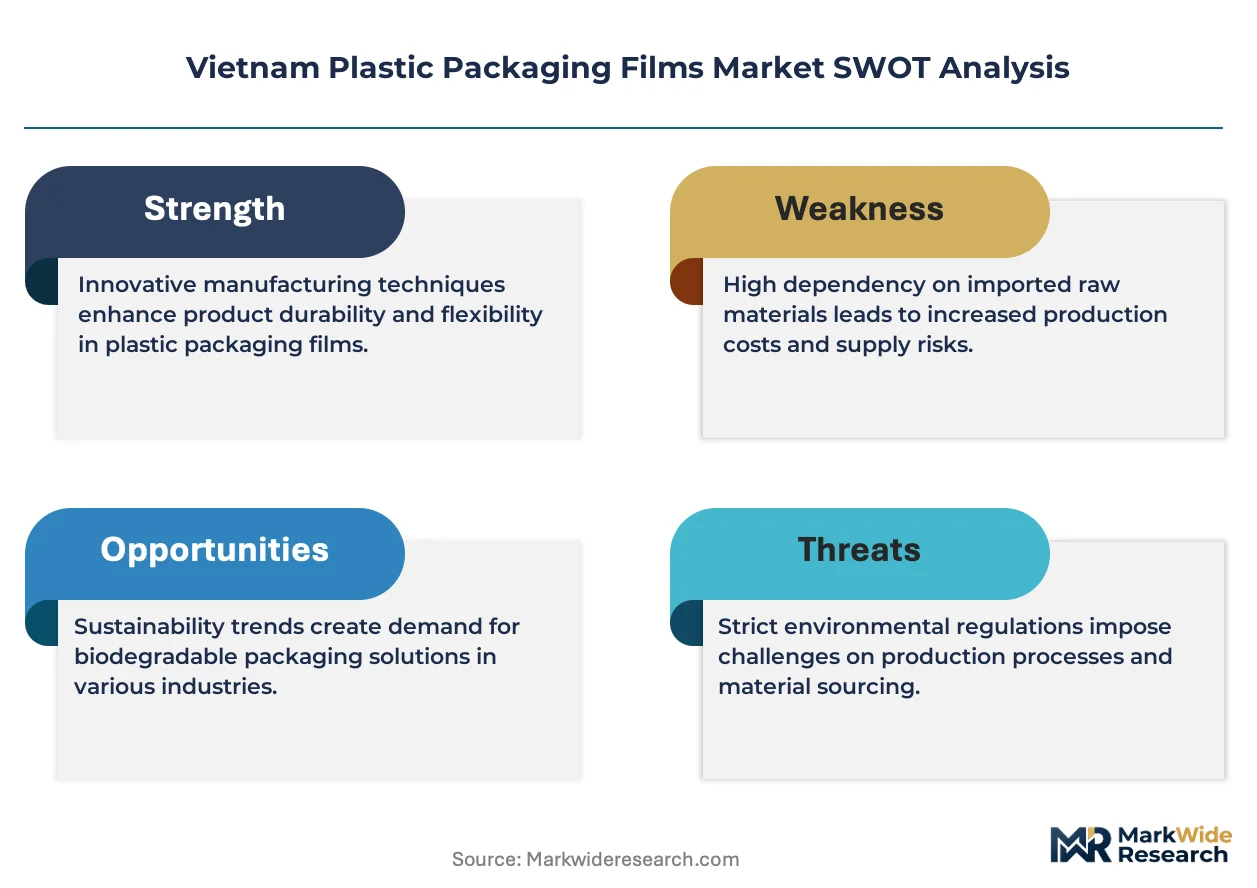
Blown film extrusion technicians concentrated in Binh Duong province command wage premiums that compress pricing spreads between commodity polyethylene grades and specialized multilayer barrier formats. Labor-cost differentials between the southern industrial corridor and emerging extrusion zones in Long An directly shape three-tier pricing structures across premium, standard, and economy levels.
Pricing Analysis
Yield-per-meter performance anchors value-based pricing for seven-layer coextrusion lines serving export-oriented seafood processors. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified barrier films from domestic-grade polyethylene and unbranded commodity wraps. Cost compression in standard-grade polyethylene is intensifying because integrated compounders with captive resin access are squeezing toll extruder margins. Domestic food processors exhibit highest price sensitivity, while pharmaceutical buyers absorbing Ministry of Health registration costs show lowest elasticity.
Supply Chain Analysis
Freight cost differentials between Singapore petrochemical hubs and Ho Chi Minh City ports feed into landed resin pricing for non-integrated converters. Raw material supply draws from Saudi ethylene crackers, South Korean polypropylene exporters, and domestic Vietnamese naphtha crackers. Feedstock exposure to ethylene and propylene spot volatility creates margin vulnerability for mid-tier extruders lacking long-term offtake contracts. Distribution runs through converter-direct relationships with food processors, supplemented by regional distributor networks serving smaller personal care and electronics packaging buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seven-layer coextrusion line availability constrains high-barrier film supply, propping pricing for qualified converters serving EU export compliance requirements.
For Market Incumbents: Hedge resin cost exposure through backward integration into naphtha cracking or long-term ethylene offtake agreements with Singapore traders. Secure redundant Vietnam Chemicals Agency certification pathways ahead of extended producer responsibility enforcement to defend margin pools against mid-tier toll extruders capturing volume through flexible minimum order quantities. For New Entrants and Emerging Players: Begin with Central Highlands coffee processors in Dak Lak and Lam Dong provinces, where controlled-atmosphere packaging demand exceeds qualified distributor supply. Capture procurement relationships through mono-material recyclable structure offerings that align with circular economy roadmap incentives, using digital printing integration for short-run customization as the primary go-to-market wedge. For Investors and Strategic Acquirers: Re-rating potential sits with specialized multilayer barrier film specialists given EU EFSA compliance tailwinds and seafood export volume concentration. Long-term viability over the next decade hinges on retrofitting timelines for recyclable content mandates and mechanical recycling infrastructure maturity. Watch enforcement cadence around Vietnam Chemicals Agency phthalate testing protocols as the inflection signal for compliance-cost concentration among certified compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Seven-Layer Coextrusion Line Retrofit | Enables EFSA-compliant barrier performance for Ho Chi Minh City seafood exporters shipping to EU markets. |
| Backward Integration into Naphtha Cracking | Captures resin cost control for Binh Duong converters facing ethylene spot price volatility. |
| Mono-Material Recyclable Structure Development | Aligns with Ministry of Natural Resources and Environment circular economy roadmap thresholds. |
| Digital Printing Line Integration | Unlocks short-run customization for regional brand owners previously excluded by rotogravure minimums. |
| Vietnam Chemicals Agency Certification Investment | Accelerates Ministry of Health registration cycles for pharmaceutical barrier film segments. |
Research Methodology
Multi-period observation of extrusion capacity additions, resin import volumes, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with plant managers at blown film operations, procurement leads at downstream food processors, distribution channel partners in the southern industrial corridor, and technical R&D directors at compounder facilities. Secondary validation drew from Vietnam Chemicals Agency technical regulation filings, customs and trade data on polyethylene and polypropylene imports, SEC disclosures from regional petrochemical suppliers, and ASEAN harmonized standards documentation. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Input-output matrices mapping resin throughput to end-use application demand generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include polymer chemistry grade, food-contact versus industrial application, thickness tier, and geographic production cluster within Vietnam's regional industrial corridors. CAGRs were derived from trend extrapolation of historical capacity utilization and demand elasticity estimates, incorporating ethylene and propylene price forecasting inputs alongside regulatory compliance timeline assumptions.
Underlying measurement precision varies by segment; food packaging and polyethylene chemistry carry tighter precision than emerging biodegradable feedstock categories. Forecasts reflect documented assumptions about enforcement timing for extended producer responsibility frameworks and mechanical recycling infrastructure development pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global Specialty Films Polymer Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Printed Plastic Films Market
Poly film
Tube Laminating Films Market
Poly film
MOPP Packaging Films Market
Poly film
PCR Lidding Films Market
Poly film
Polyester Film Market
Poly film
Cleanroom Film and Bags Market
Poly film
Bopet Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
Polycarbonate Films Market
Poly film
Bio-PET Film Market
Poly film
Silicone Release Films Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Lidding Films Market