
 Printed Plastic Films Market | 2026-2036
Printed Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Plastic Films Market Analytics
Food-grade barrier specification is rotating toward higher oxygen and moisture resistance across the printed plastic films supply base. Amcor Plc leverages its integrated film-to-package pipeline to anchor premium barrier portfolios in North America and Europe. Berry Global Inc. sustains scale advantages through multi-site extrusion and print capacity across diversified resin platforms. Huhtamaki competes on food-service and retail-ready printed formats with strong cold-chain performance credentials.
Printed plastic films denote polymer substrates—typically polyethylene, polypropylene, or polyester ranging from 12 to 150 microns—surface-treated via corona or flame processes to receive solvent-based, water-based, or UV-curable inks for branded visual communication and functional barrier performance. Their primary purpose spans primary packaging, pressure-sensitive labels, and point-of-sale decoration where print fidelity, adhesion, and regulatory compliance converge. Flexible films lead volume due to their dominance in food packaging rollstock and form-fill-seal applications, while specialty films command margin pools through holographic and tamper-evident security features. Laminated films are gaining structural share in healthcare and electronics end users where multi-layer oxygen barrier and chemical resistance specifications are non-negotiable.
FDA food-contact substance notifications, EU REACH substance restrictions, and BIS certification requirements for imported packaging materials collectively govern resin selection, ink formulation, and migration testing protocols across major supply corridors. The EU Packaging and Packaging Waste Regulation is forcing substrate-thinning and recyclability redesigns that favor mono-material polyethylene and polypropylene constructions over legacy multi-polymer laminates. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating capital allocation toward compatible print and conversion equipment.
Market Dynamics
Multi-layer laminate delamination and the EU Packaging and Packaging Waste Regulation are forcing substrate redesigns toward mono-material polyethylene and polypropylene constructions, rewiring extrusion and print capacity investments across the supply base.
Growth Catalysts
- Extended shelf-life packaging:Food and beverage brands in India and Southeast Asia are expanding printed film specifications for barrier performance in tropical climates.
- REACH compliance:ECHA substance restrictions on phthalates and heavy metals in inks are accelerating migration-safe formulation adoption across European converters.
- Digital inkjet adoption:UV-curable ink systems are reducing makeready waste and enabling shorter run lengths for regional brand SKUs.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene feedstock prices fluctuate with crude oil and naphtha markets, compressing converter margins.
- Recyclability redesign burden:The EU Packaging and Packaging Waste Regulation mandates mono-material compatibility, requiring capital-intensive extrusion line reconfiguration.
- Paper substrate substitution:Fiber-based flexible packaging gains traction in dry food categories, threatening volume in legacy plastic film segments.
Strategic Opportunities
- Healthcare barrier films:Sterile packaging for medical devices and pharmaceuticals demands multi-layer oxygen barrier specifications with tamper-evident print features.
- India manufacturing absorption:Domestic flexible packaging clusters in Gujarat and Maharashtra are capturing diverted orders from Chinese suppliers facing tariff headwinds.
- Chemical recycling feedstock:Advanced recycling outputs are qualifying for food-contact applications under evolving FDA notification pathways.
Industry Challenges
- Migration testing capacity:FDA food-contact substance notifications and EU overall migration limits require specialized analytical laboratories with extended queue times.
- Legacy equipment integration:Solvent-based gravure presses face retrofit costs for water-based or UV ink compatibility without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Plastic Films Market |
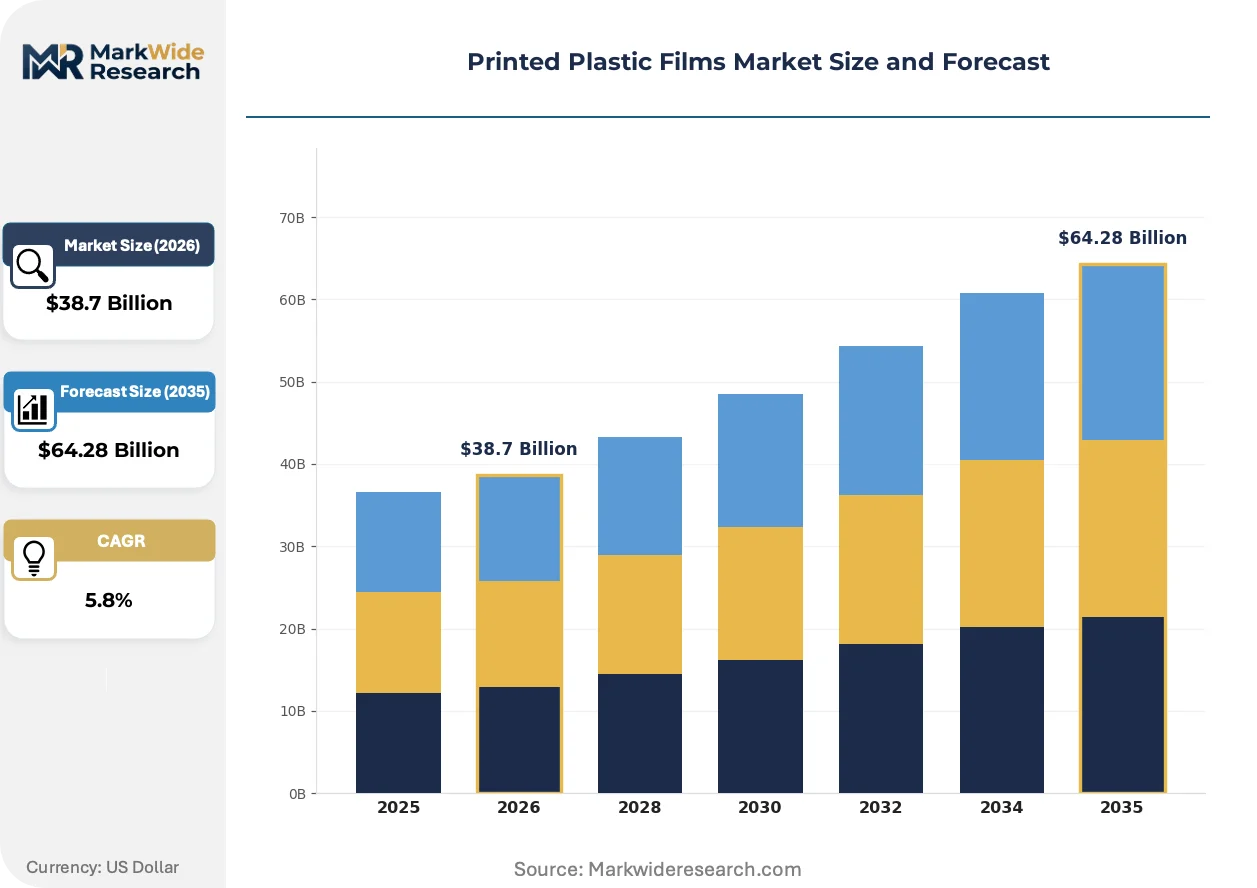
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Laminated Films, Specialty Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Packaging, Labels, Decoration, Signage End User: Food & Beverage, Healthcare, Consumer Goods, Electronics |
| Companies Covered | Amcor Plc, Berry Global Inc., Uflex Ltd., Innovia Films Ltd., Toray Industries Inc., Jindal Poly Films Ltd., Huhtamaki, Sealed Air Corporation, Taghleef Industries LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Plastic Films Market Evolving Landscape
Print fidelity, barrier performance, and circularity requirements are converging to reshape extrusion, surface treatment, and ink formulation priorities across converter operations.
Water-based flexographic ink systems are decomposing the historical dominance of solvent-based gravure in food packaging applications. Mid-size converters in North America and Europe are adopting these systems to reduce volatile organic compound emissions and simplify regulatory compliance. This transition is decomposing capital barriers between premium and standard print tiers, enabling smaller brands to access shelf-ready graphics previously reserved for high-volume accounts.
The EU Packaging and Packaging Waste Regulation is mandating design-for-recycling standards that prohibit multi-polymer laminates unless proven recyclable at scale. European converters are reengineering barrier layers to maintain oxygen and moisture resistance within mono-material polyethylene or polypropylene constructions. Food and healthcare packaging segments face the steepest redesign timelines, with some suppliers accelerating pilot lines in Germany and the Netherlands to validate performance claims.
Brand-led specification of post-consumer recycled content is compressing traditional virgin resin procurement cycles. Major retailers in France and the United Kingdom are imposing minimum recycled content thresholds for private-label flexible packaging, forcing film suppliers to qualify mechanically recycled polyethylene streams for food-contact layers. This specification cascade is most visible in frozen food and snack categories, where print registration and seal integrity must hold across recycled resin variability.
Printed Plastic Films Market Segmentation
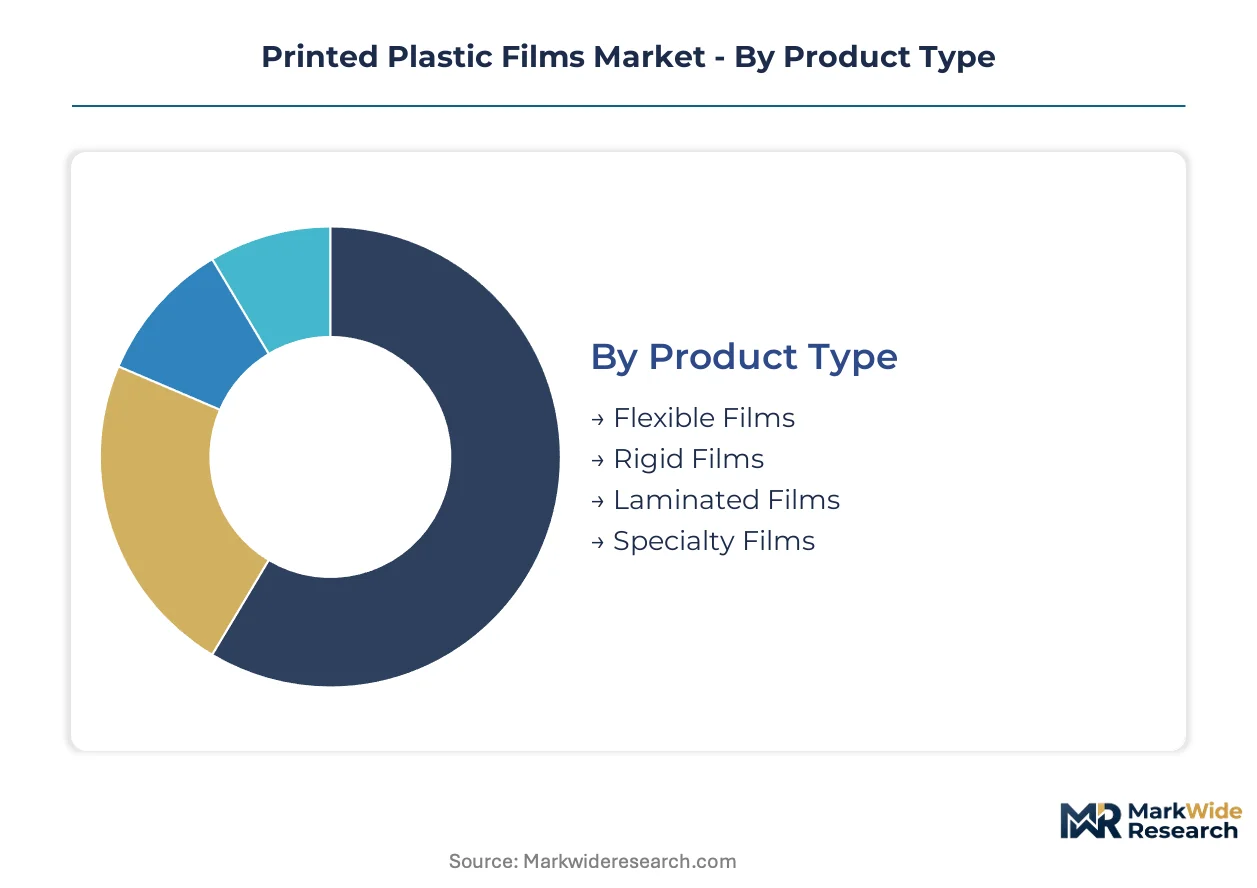
Segmentation in printed plastic films separates commodity rollstock from engineered barrier solutions, with each tier commanding distinct equipment investments and regulatory compliance burdens. Converter capabilities and brand specification power cluster differently across product types, materials, and end-use verticals.
Product Type:
Flexible films move predominantly through form-fill-seal converters serving high-volume food brands, while rigid and specialty grades route through sheet extruders and security printers respectively.
- Flexible Films:Polyethylene and polypropylene substrates from 12 to 150 microns, surface-treated for flexographic or gravure printing. Demand concentrates in tropical climate food packaging across India and Southeast Asia where moisture barrier specifications are tightening.
- Laminated Films:Multi-layer constructions combining oxygen barrier layers with printable skins. Healthcare and electronics end users in Germany and the Netherlands are piloting redesigns to meet EU Packaging and Packaging Waste Regulation mono-material mandates without sacrificing chemical resistance.
- Rigid Films:Polyester and PVC sheets for thermoformed trays and blister packs. Pharmaceutical packaging in the United States drives specification through FDA food-contact substance notification pathways.
- Specialty Films:Holographic and tamper-evident substrates with security print features. Cold-chain logistics in France and the United Kingdom specify these for high-value consumer goods authentication.
Flexible films dominate installed base. Laminated films are where expansion concentrates as healthcare barrier requirements intensify.
Material:
Resin selection determines recyclability compliance, with European converters absorbing higher costs for mono-material qualification against ECHA substance restrictions.
- Polyethylene:Linear low-density and high-density grades for seal layers and print surfaces. Post-consumer recycled content thresholds imposed by French and UK retailers are forcing mechanical recycling stream qualification for food-contact layers.
- Polypropylene:Biaxially oriented films for clarity and stiffness in snack and frozen food packaging. German and Dutch converters are reengineering barrier specifications within mono-polypropylene constructions to satisfy design-for-recycling standards.
- Polyvinyl Chloride:Rigid calendered sheets for pharmaceutical blister packs. Migration testing protocols under REACH constrain plasticizer selection for European healthcare applications.
- Polyester:PET films for high-temperature resistance and dimensional stability. Electronics packaging in Japan specifies these for moisture barrier in semiconductor shipment.
Polyethylene holds the largest volume position. Polypropylene is climbing the fastest as mono-material redesigns accelerate.
Application:
Application mix shifts with brand owner sustainability commitments, pressuring decoration and signage segments against fiber-based alternatives while packaging absorbs regulatory redesign costs.
- Packaging:Primary and secondary flexible formats for food, healthcare, and consumer goods. Extended shelf-life specifications in India are expanding oxygen and moisture barrier requirements for tropical distribution.
- Labels:Pressure-sensitive and shrink-sleeve formats for brand communication. UV-curable inkjet adoption is reducing makeready waste for regional SKU proliferation in North American beverage brands.
- Decoration:Point-of-sale films and wraparound graphics. Retailers in the United Kingdom are substituting fiber-based alternatives for non-food categories, compressing volume in legacy plastic film segments.
- Signage:Large-format printed banners and display films. Outdoor durability specifications favor PVC and polyester constructions despite recyclability limitations.
Packaging commands the deepest installed equipment base. Labels are where digital print conversion is advancing most rapidly.
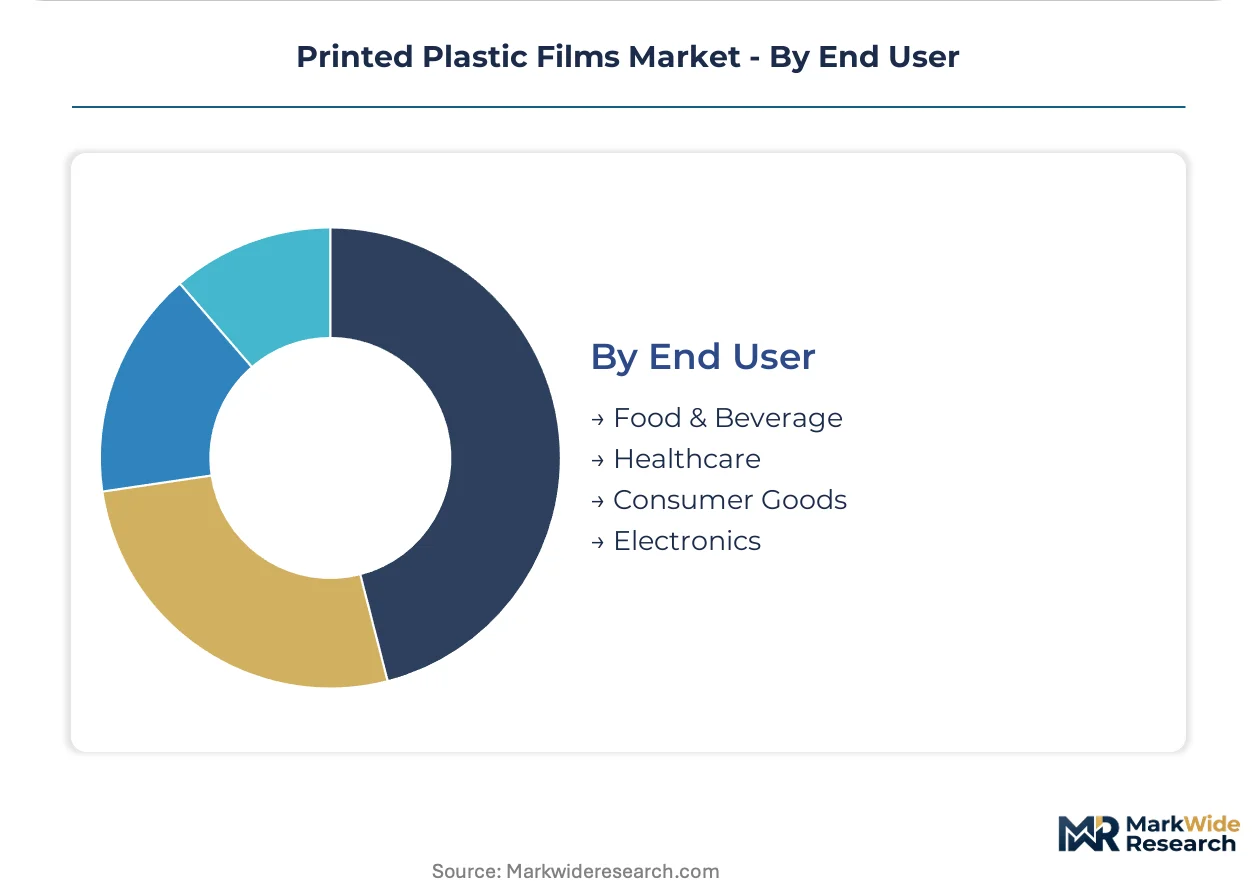
End User:
End-user concentration determines specification power, with food and healthcare brands dictating barrier performance standards that cascade through converter tiers.
- Food & Beverage:The largest demand pool spanning snack, frozen, and ready-meal packaging. Tropical climate distribution in Southeast Asia is driving oxygen barrier specification upgrades.
- Healthcare:Sterile packaging for medical devices and pharmaceuticals with tamper-evident print requirements. FDA notification pathways and EU MDR compliance are lengthening qualification timelines.
- Consumer Goods:Personal care and household product packaging with premium decoration demands. French retailer recycled content mandates are forcing material redesigns in private-label flexible packaging.
- Electronics:Moisture barrier films for component shipment and anti-static protection. Japanese and German electronics manufacturers specify multi-layer constructions with chemical resistance properties.
Food & Beverage anchors converter capacity utilization. Healthcare is where barrier specification premiums are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in printed plastic films are tilting toward manufacturing clusters in India and Southeast Asia as European and North American converters absorb regulatory redesign costs. Regional supply bases are rewiring around mono-material compliance mandates and tropical climate barrier specifications.
United States
Food and beverage brands are expanding cold-chain printed film specifications for extended shelf-life dairy and ready-meal segments. FDA food-contact substance notifications govern resin and ink selection through migration testing protocols. Flexible packaging converters in the Chicago-Gary industrial corridor are reconfiguring extrusion lines for post-consumer recycled content qualification.
Germany
Healthcare and electronics manufacturers are piloting mono-material barrier films to satisfy EU Packaging and Packaging Waste Regulation design-for-recycling standards. ECHA REACH substance restrictions on phthalates and heavy metals are accelerating water-based ink formulation adoption. Converter clusters in North Rhine-Westphalia are validating oxygen barrier performance in reengineered polypropylene constructions.
India
Domestic flexible packaging demand is concentrating in Gujarat and Maharashtra as regional manufacturers capture orders diverted from Chinese suppliers facing tariff headwinds. BIS certification requirements for imported packaging materials are tightening material safety verification protocols. Extended shelf-life specifications for tropical climate distribution are driving oxygen and moisture barrier upgrades across snack and spice packaging segments.
Japan
Electronics manufacturers specify multi-layer polyester films with chemical resistance for semiconductor shipment moisture barrier applications. METI industrial standards and JIS certification frameworks govern resin purity and dimensional stability requirements. Converter operations in the Nagoya-Chubu region are integrating UV-curable inkjet systems to reduce makeready waste for shorter regional SKU runs.
France
Major retailers are imposing minimum post-consumer recycled content thresholds for private-label flexible packaging in frozen food and snack categories. ANSM and CNIL frameworks intersect with EU REACH compliance for healthcare packaging material safety. Industrial clusters around Lyon and the Hauts-de-France region are qualifying mechanically recycled polyethylene streams for food-contact layer integration.
Printed Plastic Films Market Competitive Landscape
Concentration sits with integrated multinational converters and regional flexible packaging specialists competing on barrier specification depth and regulatory compliance velocity. The vendor base stratifies across three tiers: global film-to-package integrators with captive resin and print capacity, mid-scale regional converters with extrusion-to-print integration, and specialized security film manufacturers serving authentication and tamper-evident segments. Dominant competitive moves include extrusion line reconfiguration for mono-material recyclability and strategic partnerships with advanced recycling operators to secure food-contact qualified feedstock.
Among integrated multinational converters, Amcor Plc and Berry Global Inc. exemplify the film-to-package archetype with broad geographic manufacturing footprints. Huhtamaki occupies a position within the food-service and retail-ready format specialization tier. These three companies represent distinct strategic postures: integrated resin-to-print pipeline control, multi-site scale advantages across diversified resin platforms, and cold-chain performance credentials in flexible packaging formats.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Uflex Ltd. |
| Innovia Films Ltd. |
| Toray Industries Inc. |
| Jindal Poly Films Ltd. |
| Huhtamaki |
| Sealed Air Corporation |
| Taghleef Industries LLC |
| Others |
Value Network & Pricing Analysis
Water-based ink substitution for solvent-based gravure systems is rewiring converter cost structures while shifting supply geography toward European and North American clusters with stricter VOC regulations. This substitution simultaneously compresses legacy equipment valuation in Asia-Pacific and elevates pricing power for converters with certified low-migration formulations.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure with volume-tiered discounts. Price differentiation rests on FDA food-contact certification grade and geographic delivery cost from extrusion hubs. Cost compression in standard barrier grades is intensifying because Indian and Southeast Asian converters absorb diverted orders at thinner margins. Private-label retail buyers exhibit highest price sensitivity, while pharmaceutical sterile packaging buyers accept premium positioning for validated migration testing documentation.
Supply Chain Analysis
Strategic stockpiling of polyethylene and polypropylene resin dominates converter inventory strategy ahead of crude-linked price volatility windows. Raw material sourcing draws from Saudi Arabia, South Korea, and the United States for virgin resin, with mechanical recycling feedstock emerging from French and UK collection infrastructure. Single-source vulnerability concentrates in specialty oxygen barrier coextrusion equipment from German and Japanese suppliers. Distribution runs through form-fill-seal converter networks serving multinational food brands with just-in-time rollstock delivery schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printed plastic films market sits in a cyclical recovery phase as post-pandemic inventory destocking concludes and brand owners restock for extended shelf-life packaging specifications. Resin price normalization and converter capacity reconfiguration for mono-material recyclability are driving the current cycle.
For Market Incumbents: Compound barrier specification depth through captive coextrusion capacity additions in Germany and the Netherlands to defend against emerging Asian converters with thinner margin structures. Accelerate ECHA REACH-compliant ink formulation certification to maintain European market access as substance restrictions tighten on phthalate plasticizers.
For New Entrants and Emerging Players: Lead with digital inkjet retrofit services for mid-size North American converters seeking shorter run-length capabilities without full press replacement. Target the healthcare sterile packaging segment in the United States where FDA notification pathways create qualification moats against commodity competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging rollstock specialists in the US Midwest with stranded solvent-based gravure capacity. Five-to-ten year viability hinges on successful mono-material barrier layer reengineering and advanced recycling feedstock partnerships. Watch for BIS certification enforcement intensity in India as the signal indicating tariff-diversion sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Reconfiguration | EU Packaging and Packaging Waste Regulation compliance enables continued access to French and UK retail supply chains. |
| Advanced Recycling Feedstock Partnership | FDA food-contact qualification pathways unlock post-consumer recycled content for premium barrier specifications. |
| Water-Based Ink Formulation Certification | ECHA REACH substance restrictions favor converters with validated low-migration gravure and flexographic systems. |
| Digital Inkjet System Integration | UV-curable platforms reduce makeready waste for regional SKU proliferation in North American beverage brands. |
| Tropical Climate Barrier Specification Development | Extended shelf-life requirements in India and Southeast Asia concentrate demand for oxygen and moisture-resistant constructions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade flow databases, and industry association technical publications. Primary interviews incorporated converter operations directors, brand owner packaging specification leads, resin procurement managers, and analytical laboratory migration testing specialists. Secondary validation drew from FDA food-contact substance notifications, ECHA REACH candidate list updates, BIS certification registries, and customs import data for flexible packaging materials. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include product type tier, resin material grade, end-use application vertical, and regional manufacturing cluster concentration across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories. Industry-specific forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation timelines and tropical climate barrier specification adoption curves in South Asian markets.
The analysis sits within stated boundaries; outcomes outside sustained resin price normalization and regulatory enforcement continuity would require recalibration. Forecasts reflect assumptions regarding mono-material redesign feasibility and advanced recycling scale-up velocity. Revision becomes warranted when FDA food-contact notification queue times or ECHA substance restriction expansion crosses thresholds that alter qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Polyolefin Battery Separator Films Market
Poly film
Global Thermoplastic Films Market
Poly film
North America Polyimide Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Surface Printed Film Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Isotropic Film Market
Poly film
Silicone-Coated PET Films Market
Poly film
Bundling Film Market
Poly film
Vietnam Plastic Packaging Films Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Recyclable Lidding Films Market
Poly film
PP Film Blowing Machine Market