
 Global Polycarbonate Sheets and Films Market | 2026-2036
Global Polycarbonate Sheets and Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polycarbonate Sheets and Films Market Outlook
Automotive glazing demand is realigning the polycarbonate sheets and films value chain toward lightweight, impact-resistant optical grades. Covestro AG leverages its polymer science heritage to sustain leadership in automotive headlamp lens applications across German OEM supply chains. SABIC anchors its position through backward integration into bisphenol-A feedstock and captive supply of specialized resin grades for Middle Eastern and Asian converters. TEIJIN LIMITED differentiates through high-refractive-index optical films serving Japanese electronics brands.
Polycarbonate sheets and films are thermoplastic polyester derivatives manufactured via extrusion or calendering, typically offering transparency above 85% light transmission alongside exceptional impact resistance exceeding 250 J/m notch strength. Multi-wall sheets command premium positioning in European greenhouse and skylight construction where thermal insulation drives specification. Films occupy the fastest-expanding margin pool as foldable display substrates and automotive interior touch surfaces multiply. Solid sheets remain mature in safety equipment and riot shield fabrication where thickness-standard procurement dominates.
REACH registration through ECHA governs monomer purity and additive migration limits for European import eligibility, while China's GB standards enforce flame-retardant classifications in public infrastructure applications. FDA compliance requirements for food-contact films and EPA guidelines on bisphenol-A traceability further fragment certification obligations across export destinations. Stakeholders must monitor regulatory divergence between EU F-Gas phase-down timelines and emerging state-level building codes in the United States before committing regional capacity expansion.
Market Dynamics
Automotive electrification is compressing glazing specification cycles as OEMs demand thinner, lighter optical grades that maintain impact performance across wider temperature ranges. This pressure is propagating backward through resin formulation and extrusion equipment requirements.
Growth Catalysts
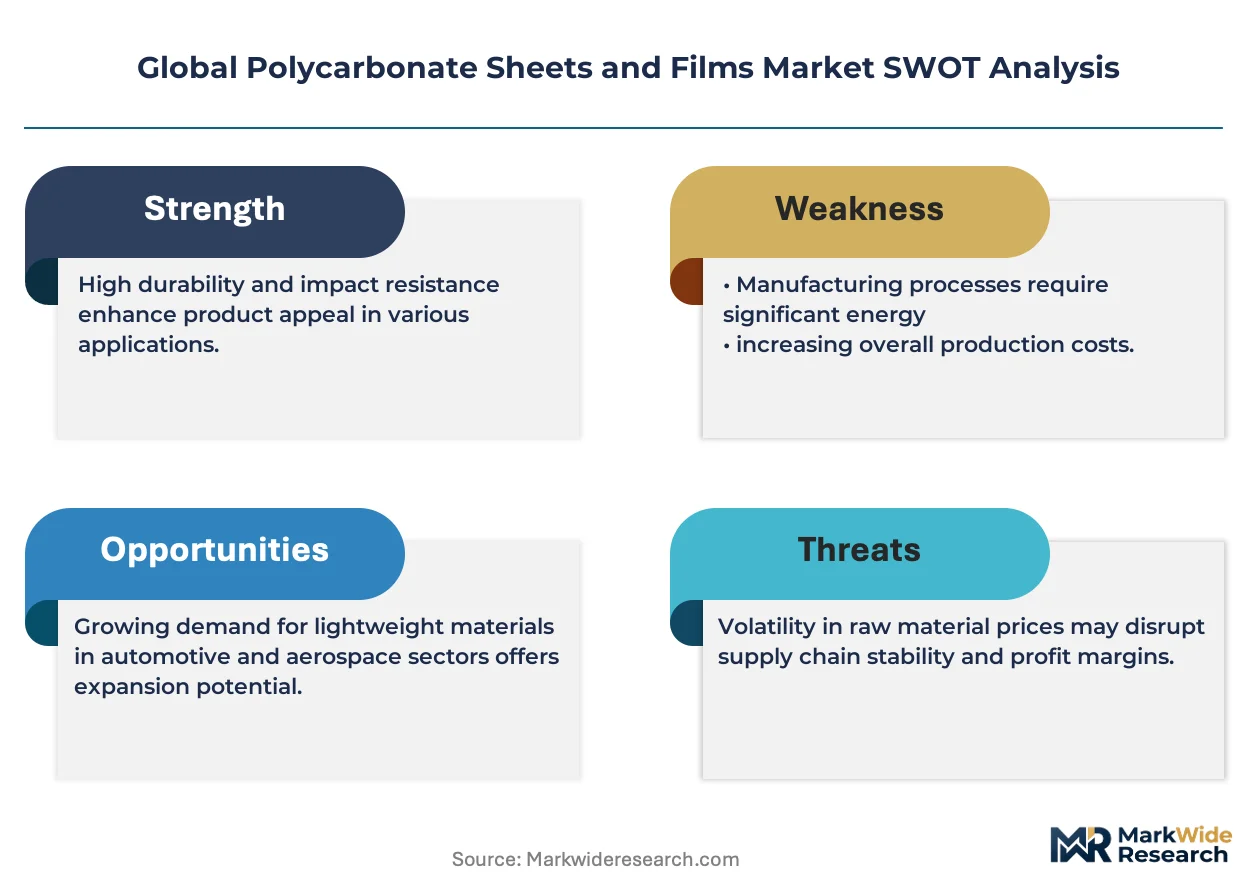
- EU F-Gas Regulation phase-down:The refrigerant transition is accelerating demand for polycarbonate thermal insulation in commercial refrigeration display cases and cold-chain infrastructure across Germany, France, and Italy.
- Foldable display substrates:Electronics OEMs in South Korea and Japan are specifying ultra-thin optical films for hinge-compatible screen protection, creating pull-through for high-clarity extrusion grades.
- China's dual carbon goals:Provincial energy-efficiency mandates in Jiangsu and Zhejiang are specifying multi-wall polycarbonate sheets for agricultural greenhouse retrofits and commercial skylight installations.
Market Restraints
- Bisphenol-A feedstock concentration:Three integrated petrochemical complexes in the US Gulf Coast and Rotterdam harbor control over 60% of merchant BPA supply, creating vulnerability to force majeure events.
- Acrylic substitution in signage:Cast acrylic sheet producers in Turkey and Thailand are capturing price-sensitive outdoor advertising applications with UV-stabilized alternatives at 30-40% cost discount.
- REACH authorization complexity:ECHA's evolving substance restrictions on flame-retardant additives are extending compliance timelines for European converters by 12-18 months.
Strategic Opportunities
- India's PLI scheme for electronics:Display and component manufacturing incentives are attracting optical film lamination investments in Tamil Nadu and Karnataka, creating localized demand for virgin resin imports.
- Photovoltaic backsheet integration:Bifacial solar module architectures are specifying co-extruded polycarbonate barrier films as fluoropolymer alternatives, with pilot adoption in Chinese and Malaysian panel assembly.
- Automotive interior touch surfaces:Haptic feedback integration is electrifying specification of textured, anti-fingerprint films for center console and steering wheel applications.
Industry Challenges
- Optical-grade extrusion technician scarcity:The precision calibration required for sub-50-micron film gauge control exceeds current vocational training output in Central European and North American manufacturing hubs.
- Multi-certification stacking:Simultaneous pursuit of FDA food-contact, UL fire-rated, and automotive OEM material approvals is stretching quality assurance bandwidth at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polycarbonate Sheets and Films Market |
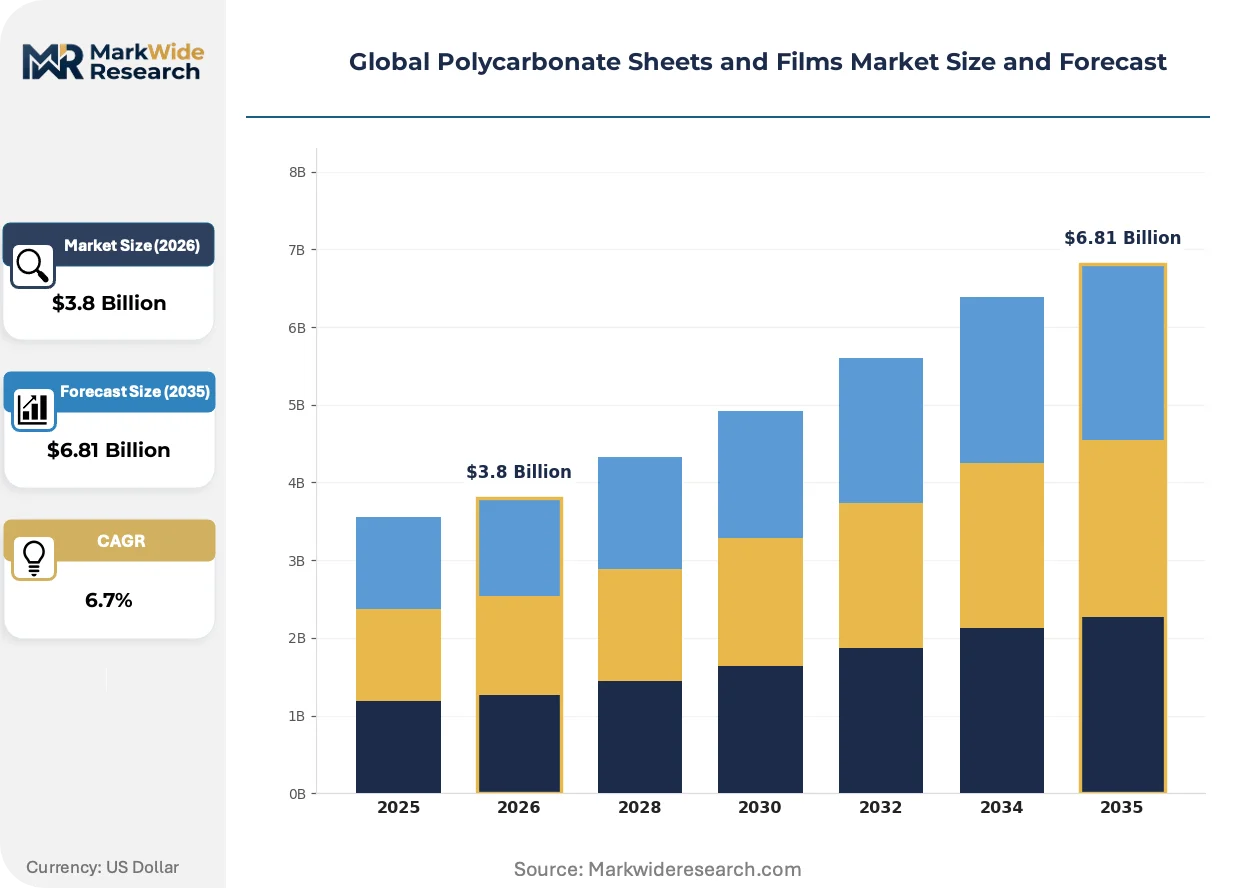
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Sheets, Solid Sheets, Multi-wall Sheets, Films End User: Construction, Automotive, Electronics, Packaging Application: Upholstery, Lighting, Safety Equipment, Signage Thickness: Thin, Medium, Thick, Ultra-thick |
| Companies Covered | LG Chem, Trinseo, SABIC, 3A Composites GmbH, Palram Industries Ltd., Covestro AG, Mitsubishi Gas Chemical Company, Inc., Arla Plast, TEIJIN LIMITED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polycarbonate Sheets and Films Market Strategic Shifts
Material science advances are compressing the performance gap between commodity extrusion grades and specialty optical formulations. Three convergent developments are restructuring competitive positioning.
Nano-layer co-extrusion is electrifying barrier performance in packaging and electronic applications. This process stacks hundreds of alternating polymer layers to achieve gas permeability below 1 cc/m²/day. Medical device manufacturers in Massachusetts and Minnesota are qualifying these structures for sterile barrier packaging. The technology is compressing addressable market share for ethylene vinyl alcohol copolymers and aluminum oxide vapor-deposited alternatives.
REACH authorization amendments are tightening additive migration limits for food-contact applications. ECHA's 2024 update to Annex XVII restricts specific phosphate ester flame retardants previously standard in reusable container films. German and Dutch converters are reformulating with oligomeric phosphonate alternatives at 15-20% raw material cost premium. The regulatory friction is advantaging integrated resin producers with captive additive synthesis capabilities.
Specification consolidation among automotive Tier 1 suppliers is compressing approved vendor lists for headlamp lens and HUD combiner applications. Magna, Faurecia, and Hyundai Mobis are converging on dual-source strategies requiring identical resin certificates from both suppliers. This behavioral shift is elevating importance of lot-to-lot consistency documentation and real-time rheological data sharing. The pattern is most visible in Baden-Württemberg and Lower Saxony supply corridors serving German premium OEMs.
Global Polycarbonate Sheets and Films Market Segmentation
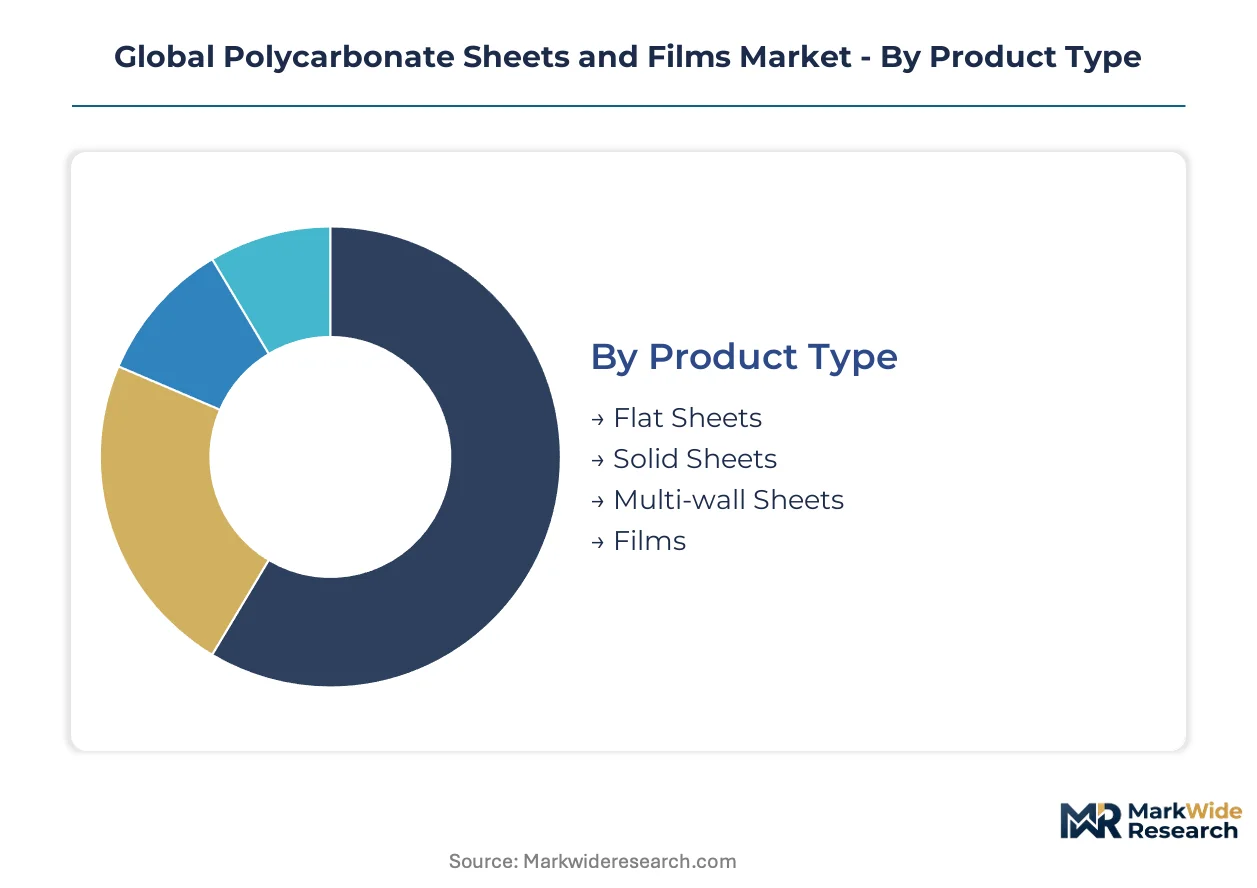
Polycarbonate sheets and films serve divergent performance requirements across optical clarity, impact resistance, and thermal insulation. Specification-grade differentiation determines margin capture, with extrusion gauge control and additive packages separating commodity from premium positioning.
Product Type:
Manufacturing process and cellular architecture define the specification ladder for extruded polycarbonate formats.
- Flat Sheets:Single-layer extrusions with uniform thickness distribution serve general-purpose glazing and machine guarding. Construction procurement in Germany and France specifies these for industrial skylights where cost efficiency outweighs thermal performance.
- Solid Sheets:High-density monolithic structures deliver maximum impact resistance exceeding 250 J/m notch strength. Safety equipment fabricators in the US and Japan specify these for riot shields and protective barriers where ballistic performance is mandatory.
- Multi-wall Sheets:Cellular rib structures create trapped air chambers for thermal insulation. Greenhouse retrofit programs in China's Jiangsu province and commercial cold-chain infrastructure across Italy specify these for energy-efficiency compliance.
- Films:Sub-500 micron calendered or cast formats enable optical-grade surface precision. Foldable display manufacturers in South Korea and automotive interior suppliers in Baden-Württemberg drive specification for hinge-compatible and haptic-feedback applications.
Mature deployment sits with flat and solid sheets in established safety and construction applications. Newer deployment is concentrated in films serving electronics substrate and automotive interior touch surfaces.
End User:
Customer industry determines certification stacking intensity and technical service requirements.
- Construction:Building codes and energy-efficiency mandates shape procurement. Multi-wall sheet demand concentrates in European greenhouse retrofits and Chinese provincial infrastructure programs.
- Automotive:OEM material approvals and lot-to-lot consistency documentation dominate. Headlamp lens and HUD combiner applications in German supply corridors require identical resin certificates from dual-source strategies.
- Electronics:Optical clarity and dimensional stability specifications are most stringent. Ultra-thin film demand from South Korean and Japanese display manufacturers is climbing the fastest.
- Packaging:FDA food-contact and sterile barrier requirements apply. Medical device manufacturers in Massachusetts and Minnesota qualify nano-layer co-extruded structures for pharmaceutical packaging.
Established volume concentration remains with construction procurement. Steepest expansion trajectory is visible in electronics substrate specifications.
Application:
Functional performance requirements separate commodity from premium-grade positioning.
- Upholstery:Textured and anti-fingerprint surface treatments serve automotive interior applications. Center console and steering wheel specifications from Hyundai Mobis and Faurecia incorporate haptic feedback integration.
- Lighting:High-transmission optical grades exceeding 85% light transmission are mandatory. LED diffusion panels and architectural luminaire covers in French and Italian commercial buildings specify these.
- Safety Equipment:Thickness-standard procurement dominates with certified impact testing. Riot shield and protective visor fabrication for law enforcement and military end-users requires batch traceability.
- Signage:UV-stabilized grades compete with cast acrylic alternatives. Turkish and Thai acrylic producers are capturing price-sensitive outdoor advertising applications at substantial cost discount.
Long-established specification patterns persist in safety equipment and signage. Emerging deployment concentrates in upholstery applications with integrated electronics functionality.
Thickness:
Gauge control precision and extrusion equipment capability stratify manufacturing economics.
- Thin:Sub-100 micron films require precision calendering for optical-grade surface finish. Foldable display hinge compatibility and automotive anti-fingerprint layers specify these.
- Medium:1-6 mm sheets balance structural rigidity with thermoformability. General industrial glazing and equipment guarding applications standardize here.
- Thick:6-12 mm solid sheets deliver maximum impact absorption. Safety barriers and protective structures in high-traffic environments require these.
- Ultra-thick:Above 12 mm monolithic structures serve specialized ballistic and blast-resistant applications. Military and critical infrastructure protection programs specify limited volumes.
Volume concentration centers on medium gauge for broad construction and industrial applications. Fastest specification growth is visible in thin gauge films serving electronics and automotive interior segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang provinces anchor polycarbonate demand through electronics manufacturing clusters and agricultural greenhouse retrofit programs. Germany's Baden-Württemberg and Lower Saxony corridors concentrate automotive glazing supply chains serving premium OEMs. Japanese optical film specialists in Kansai and Kanto regions supply foldable display substrates to South Korean electronics brands.
China
Provincial dual carbon mandates in Jiangsu and Zhejiang are accelerating multi-wall sheet procurement for commercial skylight and greenhouse applications. GB standards enforced by SAMR tighten flame-retardant classifications for public infrastructure deployment. Dongguan and Shenzhen electronics corridors are absorbing premium optical film imports for display substrate lamination.
Germany
Automotive electrification is compressing glazing specification cycles as Baden-Württemberg-based Tier 1 suppliers demand thinner optical grades. ECHA REACH registration governs monomer purity and additive migration limits for converter eligibility. The Lower Saxony supply corridor serving Volkswagen and BMW anchors headlamp lens and HUD combiner resin demand.
United States
Cold-chain infrastructure expansion across Texas and California is pulling thermal insulation sheets for commercial refrigeration display cases. EPA guidelines on bisphenol-A traceability fragment certification obligations for food-contact film exporters. Massachusetts and Minnesota medical device clusters are qualifying nano-layer co-extruded structures for sterile barrier packaging.
Japan
Electronics OEMs in Osaka and Tokyo metropolitan areas specify ultra-thin optical films for hinge-compatible foldable display protection. METI industrial standards shape high-refractive-index formulation requirements for premium applications. Kansai-based converters supply South Korean display manufacturers with specialized extrusion grades.
India
PLI scheme incentives for electronics manufacturing are attracting optical film lamination investments in Tamil Nadu and Karnataka. BIS certification requirements govern import eligibility for construction-grade multi-wall sheets. Bangalore and Chennai industrial corridors are creating localized demand for virgin resin imports from Middle Eastern suppliers.
Global Polycarbonate Sheets and Films Market Competitive Environment
Top-tier vendors anchor resin formulation and captive feedstock control, while mid-scale converters compete on extrusion precision and certification stacking speed. The vendor base stratifies across integrated petrochemical majors, regional extrusion specialists, and optical-grade film laminators. Three archetypes dominate: backward-integrated resin producers with BPA feedstock security, precision extrusion houses serving automotive OEM approvals, and nano-layer co-extrusion technology licensors. Capacity expansion in Asian manufacturing hubs and strategic partnerships for foldable display substrate qualification represent the dominant competitive vectors.
Among German-integrated chemical producers, Covestro AG and 3A Composites GmbH exemplify the premium optical-grade archetype through polymer science heritage and extrusion precision capabilities. TEIJIN LIMITED occupies a position within the Japanese high-performance film tier, while SABIC anchors Middle Eastern supply through captive bisphenol-A production serving Asian converter demand.
| Leading Market Players |
|---|
| LG Chem |
| Trinseo |
| SABIC |
| 3A Composites GmbH |
| Palram Industries Ltd. |
| Covestro AG |
| Mitsubishi Gas Chemical Company, Inc. |
| Arla Plast |
| TEIJIN LIMITED |
| Others |
Value Chain & Pricing Dynamics
Precision optical-grade extrusion technician concentration in Central European manufacturing hubs creates labor-cost differentials that widen pricing-tier spreads between premium automotive-certified resin and commodity construction-grade sheet.
Pricing Analysis
Short-lead-time premiums for REACH-registered optical grades run 15-25% above spot inventory pricing for standard multi-wall construction sheet. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM-certified resin, industrial glazing grades, and price-sensitive signage alternatives. Cost compression in the economy tier intensifies because Turkish and Thai acrylic producers capture outdoor advertising applications at substantial discount. Price-sensitive buyers concentrate in construction procurement, while automotive Tier 1 suppliers demonstrate lowest price elasticity due to dual-source qualification requirements.
Supply Chain Analysis
Certification and qualification gating through ECHA REACH registration, FDA food-contact approval, and automotive OEM material certificates fragments converter eligibility and extends compliance timelines. Supply concentrates in Germany, China, and Saudi Arabia, with backward-integrated resin producers anchoring feedstock security. Raw material dependencies center on bisphenol-A monomer, specialty additive packages, and precision extrusion equipment. Single-source vulnerability sits with three integrated petrochemical complexes controlling merchant BPA supply. Distribution runs through regional converter networks serving construction, automotive, and electronics end-users with distinct certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH authorization amendments create a barrier-to-entry moat for integrated resin producers with captive additive synthesis capabilities.
For Market Incumbents: Anticipate specification consolidation among automotive Tier 1 suppliers by deepening lot-to-lot consistency documentation and real-time rheological data sharing capabilities. Defend against acrylic substitution in signage by accelerating nano-layer co-extrusion qualification for pharmaceutical packaging applications. Prioritize backward integration into bisphenol-A feedstock to mitigate force majeure exposure from concentrated merchant supply. For New Entrants and Emerging Players: Nano-layer co-extrusion technology licensing offers a technology-first wedge into medical device sterile barrier packaging where ethylene vinyl alcohol copolymers face displacement. Target India's PLI scheme electronics manufacturing clusters in Tamil Nadu and Karnataka for optical film lamination investments. Pursue photovoltaic backsheet integration as the most penetrable application, with pilot adoption already visible in Chinese and Malaysian panel assembly. For Investors and Strategic Acquirers: Re-rating potential sits with precision extrusion houses serving automotive OEM approvals given specification consolidation trends among German Tier 1 suppliers. Long-term viability favors converters with multi-certification bandwidth spanning FDA, UL, and automotive material approvals. Watch for India's electronics manufacturing incentive disbursement velocity as an inflection indicator for regional resin demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A Feedstock | Captive supply security mitigates force majeure risk from US Gulf Coast and Rotterdam harbor concentration. |
| Nano-Layer Co-Extrusion Technology Licensing | Medical device manufacturers in Massachusetts and Minnesota qualify these structures for sterile barrier packaging. |
| Automotive OEM Material Certificate Expansion | Dual-source strategies from Magna, Faurecia, and Hyundai Mobis elevate lot-to-lot consistency requirements. |
| India PLI Scheme Electronics Manufacturing Investment | Tamil Nadu and Karnataka corridors create localized demand for virgin resin imports from Middle Eastern suppliers. |
| Photovoltaic Backsheet Barrier Film Qualification | Bifacial solar module architectures in China and Malaysia specify co-extruded polycarbonate as fluoropolymer alternatives. |
Study Parameters
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone for resin production and converter capacity mapping. Primary interviews with plant managers at extrusion facilities, procurement leads at automotive Tier 1 suppliers, distribution channel partners, and technical R&D directors at integrated chemical producers validated grade-level demand segmentation. Bottom-up and top-down triangulation reconciled regional consumption estimates against import-export flows and end-use industry production indices.
Bottom-up modeling aggregated grade-specific volume through extrusion line utilization rates, gauge-thickness yield factors, and end-use industry consumption coefficients across the projection horizon. Top-down validation cross-checked aggregate market value against macroeconomic drivers including construction spending, automotive production, and electronics manufacturing output. Segmentation dimensions spanned product architecture, end-user industry, application function, and regional regulatory cluster. CAGRs derived from regression analysis against historical price-volume relationships and forward-looking capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under force majeure events in concentrated bisphenol-A supply and accelerated REACH authorization amendments. Forecasts reflect assumptions around regulatory compliance timelines, automotive electrification adoption curves, and foldable display substrate qualification rates. A model refresh is warranted upon material change in EU F-Gas Regulation phase-down velocity or China's provincial dual carbon mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Global EVOH Films for Packaging Market
Poly film
PET Lidding Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Stretch Films Packs Market
Poly film
Global Specialty Films Polymer Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Isotropic Film Market
Poly film
Japan Plastic Packaging Film Market
Poly film
China Plastic Packaging Film Market
Poly film
Global BOPP Films Market
Poly film
North America Polyimide Films Market
Poly film
Metallized Film Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Craft Plastic Films Market
Poly film
Global Blown Stretch Packaging Films Market