
 Forming Films Market | 2026-2036
Forming Films Market Size, Share, and Industry Trends Forecast 2026-2036
Forming Films Market Foresight
China's petrochemical expansion along the Yangtze River delta is reshaping raw material availability for forming film converters worldwide. Berry Global Inc. leverages integrated resin-to-film operations across North American manufacturing corridors. Dow anchors its position through proprietary metallocene polyethylene catalyst technology optimized for deep-draw thermoforming. Amcor competes via pharmaceutical-grade cleanroom extrusion capacity in multiple European regulatory jurisdictions.
Forming films are thermoplastic sheets engineered to 50-500 micron gauges, heated above glass-transition temperature then vacuum- or pressure-formed into three-dimensional cavities for product containment and protection. Polypropylene formulations dominate food packaging trays due to moisture barrier performance and microwave compatibility, while thermoplastic polyurethane films command premium positioning in medical device enclosures requiring gamma sterilization resistance. Blown film processes retain cost leadership in commodity industrial packaging, whereas cast film lines occupy higher-margin pharmaceutical wrapping segments demanding precise thickness tolerances.
FDA 21 CFR Part 177 indirect food additive regulations and EU REACH Annex XIV authorization requirements govern monomer migration limits and substance restrictions across export-bound production. The EU MDR and FDA's evolving guidance on sterile barrier systems are elevating validation documentation burdens for pharmaceutical-grade forming film suppliers. Stakeholders must monitor convergence between sustainability mandates and barrier performance specifications as bio-based feedstock certifications become procurement gatekeepers.
Market Dynamics
Pharmaceutical serialization mandates and fluoropolymer phase-out timelines are compressing supplier qualification cycles while simultaneously forcing material platform transitions across European and North American converting operations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon blowing agents is accelerating converter migration toward pentane and CO2-based foam technologies for insulated forming film applications.
- Thermoformable barrier films:Unit-dose blister pack demand from chronic disease medication portfolios is expanding cleanroom extrusion capacity requirements in Germany's pharmaceutical packaging corridor.
- China's Yangtze River delta:Petrochemical expansion along this industrial belt is improving propylene and ethylene raw material availability for Asia-Pacific converters serving export markets.
Market Restraints
- Fluoropolymer feedstock concentration:High-barrier PVDF and ECTFE resin supply concentrates among three chemical producers, creating vulnerability to force majeure disruptions.
- Metallocene catalyst licensing:Proprietary single-site catalyst technologies remain controlled by a narrow patent estate, limiting independent film producers' access to premium polyethylene grades.
- EU REACH Annex XIV:Authorization requirements for phthalate plasticizers in medical-grade PVC forming films are extending reformulation timelines and elevating compliance costs.
Strategic Opportunities
- India's pharmaceutical packaging:CDSCO's alignment with ICH Q1A stability guidelines is creating demand for moisture-barrier forming films among domestic generic drug exporters.
- Bio-based feedstock certification:ISCC PLUS and RSB chain-of-custody standards are becoming procurement gatekeepers for European healthcare distributors seeking scope 3 emissions reductions.
- Gamma-stable TPU films:Convergence of thermoplastic polyurethane chemistry with electron-beam crosslinking is opening surgical tray and implantable device enclosure applications.
Industry Challenges
- Cleanroom extrusion technician scarcity:Qualified operators capable of maintaining ISO 14644-1 Class 7 environments during pharmaceutical-grade film production command wage premiums that compress converter margins.
- Validation documentation burdens:EU MDR technical file requirements and FDA's evolving sterile barrier system guidance are extending qualification timelines for new forming film specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forming Films Market |
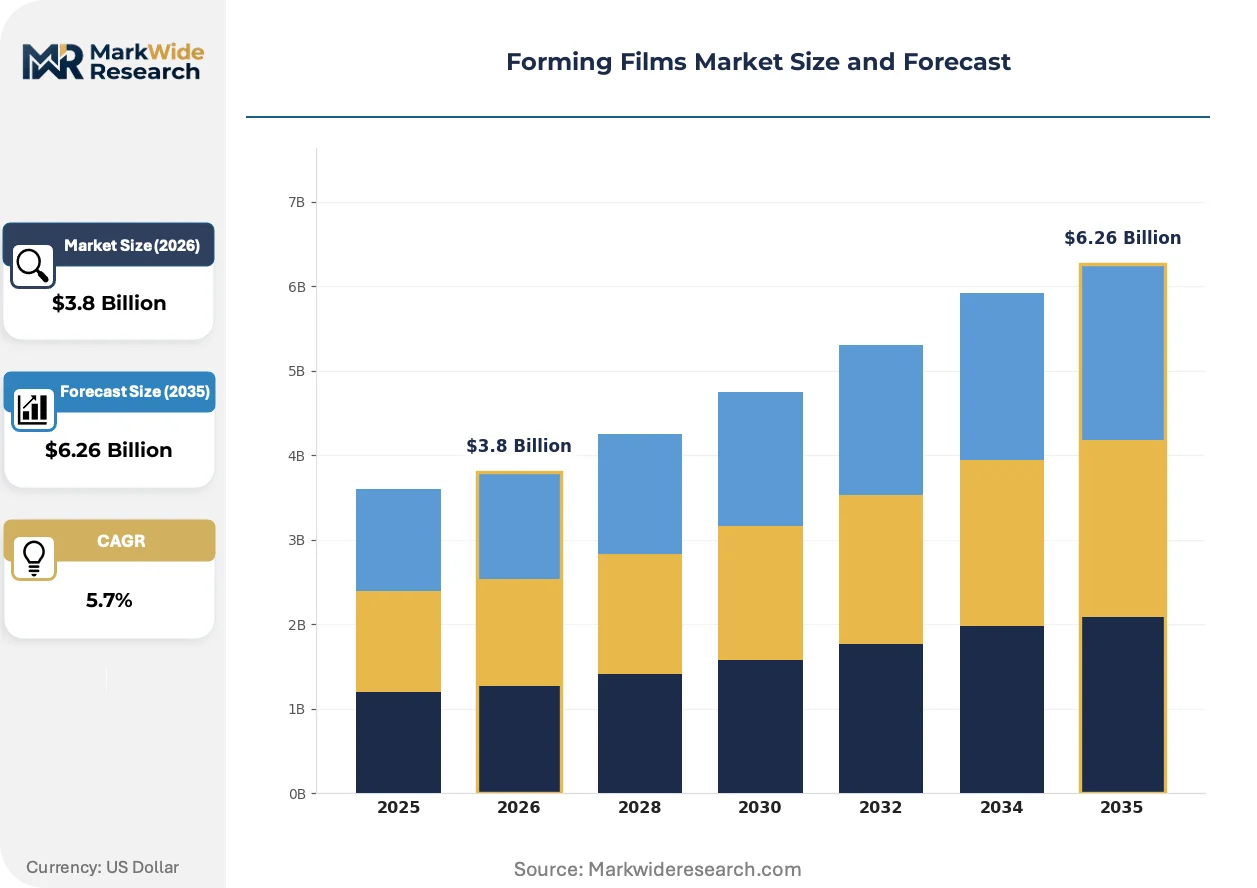
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyvinyl Chloride, Polyethylene Terephthalate, Polypropylene, Polystyrene, Thermoplastic Polyurethane Application: Food Packaging, Cosmetic Enclosures, Pharmaceutical Wrapping, Electronic Component Protection, Industrial Packaging Form: Coated Films, Laminated Films, Cast Films, Blown Films, Extruded Films End User Industry: Consumer Goods Manufacturers, Electronic Device Makers, Pharmaceutical Producers, Industrial Goods Suppliers, Cosmetic Companies |
| Companies Covered | Berry Global Inc., Coveris, Uflex Limited, Dow, Amcor, Sealed Air Corporation, Mondi Group, Winpak, Wihuri Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forming Films Market Shifts & Advancements
Real-time thickness monitoring and predictive maintenance systems are digitizing quality assurance workflows across cast film extrusion lines, while regulatory chemistry restrictions and circular economy mandates are rewriting material selection criteria.
Machine vision inspection augmented by edge computing is digitizing defect detection in pharmaceutical-grade forming film production. Cleanroom extrusion operators in Germany and Switzerland are deploying these systems to eliminate manual sampling intervals. The technology is digitizing quality documentation for FDA 21 CFR Part 11 compliance.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated polymer options for high-barrier medical packaging. The European Chemicals Agency's 2023 restriction proposal is forcing converters toward silicon oxide-coated polyester and ethylene vinyl alcohol laminates. German pharmaceutical packaging corridors are responding with accelerated qualification of alternative barrier structures.
Hospital procurement consortia are consolidating supplier panels and demanding total-cost-of-ownership transparency for sterile barrier systems. Group purchasing organizations in the United States are unbundling forming film from tray contracts to capture direct sourcing savings. This concentration is most visible in cardiovascular device packaging where original equipment manufacturers face margin compression.
Forming Films Market Segmentation
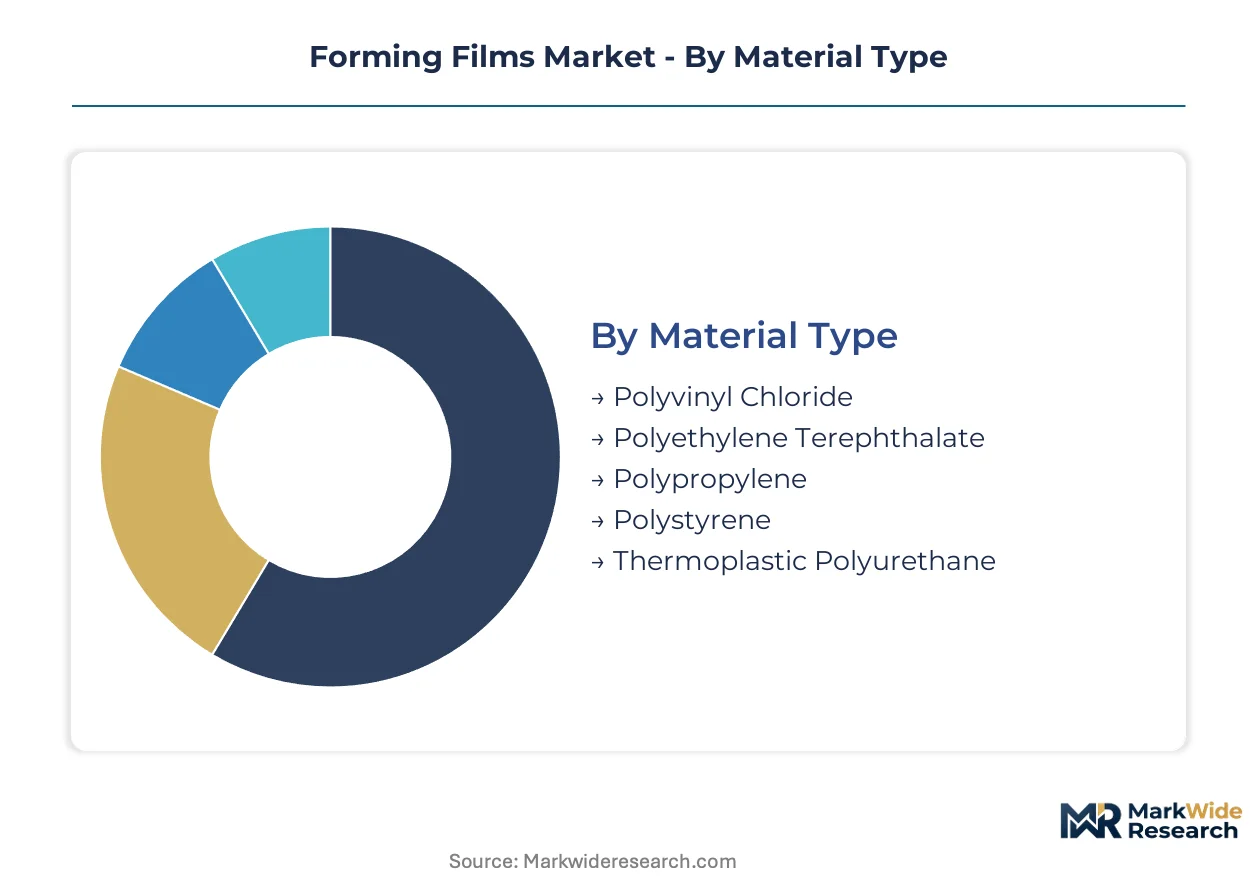
Forming film procurement patterns diverge sharply across material chemistry and processing method, with pharmaceutical-grade specifications commanding extended qualification cycles while food packaging segments turn inventory rapidly. Understanding these velocity differentials enables suppliers to calibrate working capital and technical service investments against segment-specific margin profiles.
Material Type:
Polypropylene and polyethylene terephthalate formulations rotate through converter order books fastest due to standardized food and industrial specifications, whereas thermoplastic polyurethane and high-barrier fluoropolymer alternatives linger in validation queues for medical applications.
- Polypropylene:Metallocene-catalyzed homopolymer and random copolymer grades dominate thermoformed food trays and dairy containers. German dairy processors along the Lower Rhine corridor specify high-clarity, nucleated formulations for extended shelf-life yogurt cups. Moisture barrier performance and microwave compatibility sustain replacement demand against polystyrene in ready-meal applications.
- Thermoplastic Polyurethane:Aromatic and aliphatic TPU films engineered for gamma sterilization resistance command premium positioning in surgical tray and implantable device enclosures. Swiss medical device manufacturers in the Lake Geneva cluster specify electron-beam crosslinked grades for orthopedic implant packaging where ECHA fluoropolymer restrictions have eliminated incumbent PVDF options.
- Polyvinyl Chloride:Plasticized PVC forming films retain cost advantage in blister pack applications despite REACH Annex XIV authorization burdens for phthalate plasticizers. Reformulation toward citrate and trimellitate alternatives extends qualification timelines for EU-bound pharmaceutical production.
- Polyethylene Terephthalate:Amorphous PET and glycol-modified PETG sheets serve deep-draw cosmetic enclosures and electronics clamshells. Clarity and printability specifications from French perfume houses drive demand for ultra-low haze grades.
- Polystyrene:General-purpose and high-impact polystyrene sheets persist in disposable food service trays and industrial dunnage. Price sensitivity in commoditized applications accelerates substitution toward polypropylene where resin spreads compress.
Polypropylene anchors the volume base while thermoplastic polyurethane gains share at the steepest rate as medical packaging fluoropolymer phase-outs accelerate alternative qualification.
Application:
Food packaging and industrial applications generate the highest shipment velocities with standardized specifications, whereas pharmaceutical wrapping and electronic component protection require extended validation documentation and cleanroom production protocols that elongate sales cycles.
- Pharmaceutical Wrapping:Unit-dose blister packs and surgical tray lidding films demand ISO 14644-1 Class 7 cleanroom extrusion with full batch traceability. FDA 21 CFR Part 177 compliance and EU MDR technical file requirements extend supplier qualification to 18-24 months for new specifications.
- Food Packaging:Modified atmosphere trays, lidding films, and vacuum skin packs rotate through converter inventories rapidly. German retail chains specify oxygen transmission rates below 1 cc/m²/day for premium meat and cheese applications.
- Electronic Component Protection:Antistatic and static-dissipative forming films protect semiconductor wafers and printed circuit boards during shipment. ESD control specifications from Taiwanese electronics assemblers drive demand for carbon-loaded and inherently conductive polymer grades.
- Cosmetic Enclosures:Deep-draw transparent cavities for fragrance, skincare, and color cosmetic presentations emphasize optical clarity and scuff resistance. Italian luxury packaging houses specify cast PETG with velvet-touch coatings for premium unboxing experiences.
- Industrial Packaging:Returnable dunnage trays, automotive component carriers, and agricultural seedling trays prioritize unit cost and impact strength over barrier performance. Mexican automotive supplier parks near Querétaro sustain demand for recycled-content polypropylene formulations.
Food packaging commands the largest shipment volumes while pharmaceutical wrapping expands most quickly as chronic disease medication portfolios and serialization mandates multiply unit-dose requirements.
Form:
Cost structures stratify sharply between commodity blown film operations with rapid die changeovers and precision cast lines serving pharmaceutical tolerance specifications that demand extended setup and quality assurance intervals.
- Cast Films:Chill-roll cast extrusion achieves thickness tolerances within ±3% for pharmaceutical and optical applications. Swiss and German cleanroom lines supply FDA 21 CFR Part 11 compliant documentation for sterile barrier systems.
- Blown Films:Tubular film processes retain cost leadership in industrial and agricultural applications where gauge uniformity requirements relax. Biaxial orientation capabilities serve shrink-wrap and collation film markets.
- Laminated Films:Multi-layer adhesive and extrusion lamination combines barrier polymers with sealant and structural substrates. EVOH and SiOx-coated polyester alternatives to fluoropolymer barriers concentrate qualification activity in German pharmaceutical corridors.
- Coated Films:Solvent and aqueous coatings impart heat-seal, release, or barrier functionality to base substrates. Silicon oxide vapor deposition on polyester replaces fluorinated options for high-oxygen-barrier medical packaging.
- Extruded Films:Sheet extrusion for thermoforming feedstock emphasizes width consistency and gauge profile for downstream forming efficiency. Inline thickness monitoring systems from Austrian equipment suppliers digitize quality documentation.
Blown films carry the volume base while laminated films climb the fastest as barrier complexity requirements intensify across pharmaceutical and extended-shelf-life food segments.
End User Industry:
Consumer goods manufacturers and cosmetic companies rotate forming film inventories rapidly with seasonal demand patterns, whereas pharmaceutical producers and electronic device makers impose rigid qualification protocols that freeze specifications across multi-year contracts.
- Pharmaceutical Producers:Multinational drug manufacturers and contract packaging organizations demand ISCC PLUS certified bio-based content for scope 3 emissions reporting. German generic drug exporters along the Frankfurt-Stuttgart corridor specify thermoformable barrier films with WVTR below 0.1 g/m²/day.
- Consumer Goods Manufacturers:Food processors and household product companies prioritize total delivered cost and line speed compatibility. Mexican and Thai export-oriented processors specify high-slip grades for automated thermoforming lines.
- Electronic Device Makers:Semiconductor and consumer electronics assemblers require ESD protection and particulate cleanliness. South Korean memory chip manufacturers specify ionic contamination levels below 10 ppm for wafer shipping trays.
- Cosmetic Companies:Prestige fragrance and skincare houses emphasize shelf presence and tamper evidence. French and Italian luxury brands drive demand for metallized and holographic forming film finishes.
- Industrial Goods Suppliers:Automotive tier suppliers and agricultural distributors prioritize durability and nesting efficiency for returnable packaging systems. German automotive logistics providers specify RFID-embedded forming films for container tracking.
Consumer goods manufacturers anchor demand volumes while pharmaceutical producers drive the steepest specification upgrades as serialization mandates and sustainability certifications rewrite procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 177 and EU REACH Annex XIV govern export-bound forming film production, with regulatory stringency concentrating converter investments in Germany, the United States, China, and Switzerland.
Germany
Frankfurt-Stuttgart pharmaceutical packaging corridor drives thermoformable barrier film demand for unit-dose blister packs. EU F-Gas Regulation accelerates fluoropolymer alternatives toward silicon oxide-coated polyester laminates. Cleanroom extrusion facilities in Baden-Württemberg maintain ISO 14644-1 Class 7 environments for sterile barrier systems.
United States
Serialization mandates and chronic disease medication portfolios expand pharmaceutical-grade forming film procurement. FDA evolving guidance on sterile barrier systems elevates validation documentation burdens for domestic suppliers. Berry Global Inc. anchors integrated resin-to-film operations across Midwest manufacturing corridors.
China
Petrochemical expansion along Yangtze River delta improves propylene and ethylene availability for Asia-Pacific converters. NMPA alignment with international stability guidelines supports domestic generic drug exporter demand. Shanghai and Jiangsu province clusters supply moisture-barrier films for regional pharmaceutical packaging.
Switzerland
Swissmedic requirements and ECHA fluoropolymer restrictions converge on Lake Geneva medical device manufacturers. Electron-beam crosslinked TPU films displace PVDF options in orthopedic implant packaging. Cleanroom operators deploy machine vision systems for FDA 21 CFR Part 11 compliant quality documentation.
India
CDSCO alignment with ICH Q1A stability guidelines creates demand for moisture-barrier forming films among generic drug exporters. Domestic pharmaceutical packaging growth concentrates in Maharashtra and Gujarat industrial belts. ISCC PLUS certification requirements from European healthcare distributors drive bio-based feedstock adoption.
Forming Films Market Competitive Landscape
Integrated multinational resin producers and specialized pharmaceutical-grade converters split the market into distinct capability tiers. Consolidation concentrates among resin-to-film integrated operations and cleanroom-certified extrusion specialists. Three archetypes dominate: petrochemical-integrated film producers, pharmaceutical-grade cleanroom operators, and regional flexible packaging converters. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among North American integrated producers, Berry Global Inc. and Dow exemplify the petrochemical-anchored archetype with captive resin supply chains. Amcor occupies a position within the pharmaceutical-grade tier, leveraging multi-jurisdictional cleanroom certification. These three represent the structural poles around which mid-cap specialists and regional converters organize their competitive positioning.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Coveris |
| Uflex Limited |
| Dow |
| Amcor |
| Sealed Air Corporation |
| Mondi Group |
| Winpak |
| Wihuri Group |
| Others |
Supply & Pricing Matrix
Undercapacity in German cleanroom extrusion facilities drives aggressive capacity booking by pharmaceutical converters and sustains premium pricing for ISO 14644-1 Class 7 certified forming films. This utilization tension concentrates negotiating leverage among certified suppliers while forcing buyers into longer-term offtake commitments to secure allocation.
Pricing Analysis
Price spreads between German pharmaceutical-grade cast film and Chinese commodity blown film exceed 4x on a per-kilogram basis, reflecting certification tier and cleanroom production cost differentials. Three-tier pricing structure separates FDA-validated sterile barrier grades from industrial food packaging specifications and economy recycled-content formulations. Pricing pressure stems from resin cost volatility in propylene and ethylene feedstocks, with polypropylene homopolymer grades experiencing the steepest compression. Consumer goods manufacturers exhibit highest price sensitivity due to standardized specifications and rapid inventory turns, while pharmaceutical producers accept premiums for multi-year validation stability.
Supply Chain Analysis
Extended payment terms of 90-120 days from European healthcare distributors force supply-chain finance facilities upon mid-tier Asian converters, compressing working capital returns. Raw material sourcing concentrates in Germany, China, and Saudi Arabia for metallocene polyethylene catalyst systems and high-purity resin grades. Fluoropolymer feedstock dependence rests on three chemical producers for PVDF and ECTFE resins, creating single-source vulnerability for high-barrier medical packaging. Distribution runs through pharmaceutical packaging corridors in Germany, regional converting hubs in China's Yangtze River delta, and integrated resin-to-film operations across North American manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forming films occupy an early-cycle expansion phase as fluoropolymer phase-out timelines and pharmaceutical serialization mandates accelerate material platform transitions. Chronic disease medication portfolios and unit-dose blister pack demand provide durable tailwinds for barrier film qualification.
For Market Incumbents: Harden cleanroom certification moats through multi-jurisdictional FDA and EMA validation investments, while capturing backward integration into metallocene catalyst licensing to secure premium polyethylene grade access. Threats from silicon oxide-coated polyester alternatives to fluoropolymer barriers demand accelerated R&D in EVOH laminate structures to defend specification share. For New Entrants and Emerging Players: India's pharmaceutical packaging corridor between Maharashtra and Gujarat represents the most penetrable entry point, where CDSCO alignment with ICH stability guidelines creates demand for moisture-barrier films among generic drug exporters. Bio-based feedstock certification capabilities and ISCC PLUS chain-of-custody documentation provide differentiation for European healthcare distributor procurement panels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical-grade cleanroom operators with multi-year validation contracts and sterile barrier system technical files. Five-to-ten year viability favors converters with captive resin supply and established FDA 21 CFR Part 11 quality documentation systems. The signal to watch is ECHA restriction proposal progression on per- and polyfluoroalkyl substances, which would accelerate alternative barrier qualification timelines and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644-1 Class 7 certification in Baden-Württemberg secures pharmaceutical contract flows. |
| Backward Integration into Catalyst Systems | Metallocene polyethylene technology access reduces feedstock cost volatility exposure. |
| Bio-based Feedstock Certification | ISCC PLUS documentation opens European healthcare distributor procurement panels. |
| Alternative Barrier Qualification | Silicon oxide-coated polyester laminates replace fluoropolymer options under ECHA restrictions. |
| Long-term Pharmaceutical Supply Agreements | Multi-year offtake contracts with Frankfurt-Stuttgart corridor generics manufacturers stabilize utilization. |
Research Methodology
Desk research of customs trade databases, SEC filings from resin producers, and ECHA regulatory submissions preceded structured interviews with cleanroom extrusion plant managers, pharmaceutical packaging procurement leads, and medical device regulatory affairs directors. Primary fieldwork across German pharmaceutical corridors and Chinese Yangtze River delta converting clusters combined with secondary validation from FDA 21 CFR guidance documents and EU MDR technical file requirements. Bottom-up shipment analysis by material grade and application triangulated against top-down resin consumption estimates from petrochemical trade associations.
Assumptions held fixed include regulatory phase-out timelines for fluorinated polymers and pharmaceutical serialization mandate implementation schedules, while variables included resin price volatility bands and cleanroom capacity utilization rates across the projection horizon. Segmentation modeling incorporated material chemistry, processing method, application vertical, and end-user industry tier dimensions. CAGRs derived from regression analysis against historical pharmaceutical packaging output and food processing equipment investment cycles, with specific inputs from chronic disease medication portfolio expansions and generic drug export growth patterns.
Practitioners should monitor ECHA restriction proposal advancement, NMPA stability guideline alignment progress, and metallocene catalyst patent estate expirations for early signals of competitive repositioning. Forecasts reflect documented assumptions; macroeconomic contraction in pharmaceutical capital expenditure, accelerated fluoropolymer substitution timelines, or feedstock supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
PP Film Blowing Machine Market
Poly film
Global Cast Polypropylene Packaging Films Market
Poly film
Wrap Around Label Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
PE Foam Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Poly Coated Kraft Paper Market
Poly film
Co Extruded Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Poly Tubing Market
Poly film
Colourless Polyimide Films Market
Poly film
Easy Peel Film Packaging Market
Poly film
Global Polycarbonate Sheets and Films Market