
 Polished Concrete Market | 2026-2036
Polished Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Polished Concrete Market Intelligence
The supply channel directly serving independent polishing contractors is narrowing as material manufacturers build certified networks. Sika AG leverages its chemical expertise to offer integrated systems of densifiers and sealers, often tied to specific applicator training. Husqvarna AB competes by bundling its advanced grinding equipment with comprehensive operator certification programs, influencing contractor choice. This shift consolidates influence with large-scale suppliers.
Polished concrete is a multi-step process involving mechanical grinding of a concrete slab with progressively finer diamond tools to achieve a specified sheen, often up to a 3000-grit finish. The surface is then treated with a chemical densifier to increase hardness and a sealer for stain protection. Within applications, warehouses provide stable volume, while high-end commercial spaces command premium pricing for decorative finishes. The product mix shows densifiers and sealers as critical consumables, while floor grinders represent a significant capital equipment purchase for contractors.
Regulatory frameworks significantly influence material selection and work practices in the polished concrete industry. The US EPA's limits on Volatile Organic Compounds (VOCs) drive the formulation of water-based sealers, while Europe's REACH directive governs the chemical composition of densifiers. Concurrently, standards from bodies like OSHA in the United States mandate dust control measures during grinding to mitigate silica exposure. Future contractor success will depend on navigating the trade-offs between high-performance systems and evolving environmental and safety compliance.
Market Dynamics
The central dynamic in the polished concrete market is the tension between architectural demand for sophisticated aesthetics and the increasing burden of environmental and worker safety regulations. This force shapes material formulation, contractor certification, and equipment design, pushing the industry towards more integrated and compliant systems.
Growth Catalysts
- Commercial Sector Adoption:The pursuit of durable, low-maintenance, and aesthetically versatile flooring in commercial spaces like retail stores, offices, and showrooms provides a consistent demand stream.
- Regulatory Push for Greener Materials:Mandates from bodies like the US EPA and Europe's REACH directive limiting VOC content are accelerating the switch to water-based, low-odor densifiers and sealers.
- Construction Activity:Sustained new commercial construction and large-scale renovation projects, particularly concentrated in the United States and Germany, create a direct and reliable volume pipeline for polishing services.
Market Restraints
- Substrate Dependency:The final quality of a polished concrete floor is highly dependent on the condition and quality of the initial concrete slab, a factor often outside the polishing contractor's control.
- High Capital Outlay:The initial investment in professional-grade grinding and dust extraction equipment represents a significant capital barrier for new or smaller contractors.
- Consolidated Supply Channels:The trend of material manufacturers creating exclusive certified applicator networks limits product access and choice for independent contractors, concentrating market power.
Strategic Opportunities
- Residential Market Penetration:Targeting high-end residential projects, including basements, garages, and living spaces, offers a significant area for market expansion beyond the commercial core.
- Functional Surface Integration:The opportunity exists to embed technologies like radiant heating elements or data sensors into concrete slabs prior to the polishing process, creating value-added smart floors.
- Decorative Innovation:Developing a wider array of decorative options, including custom colors, aggregates, and patterns, can unlock premium pricing tiers in high-design commercial and hospitality segments.
Industry Challenges
- Skilled Labor Scarcity:Operating advanced grinding machinery and correctly applying chemical treatments requires specific training, and a shortage of experienced technicians can constrain growth and quality.
- Navigating Compliance:Contractors face the operational challenge of adhering to a complex mix of regulations, including OSHA's silica dust rules and EPA's VOC limits, which requires constant process and equipment updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polished Concrete Market |
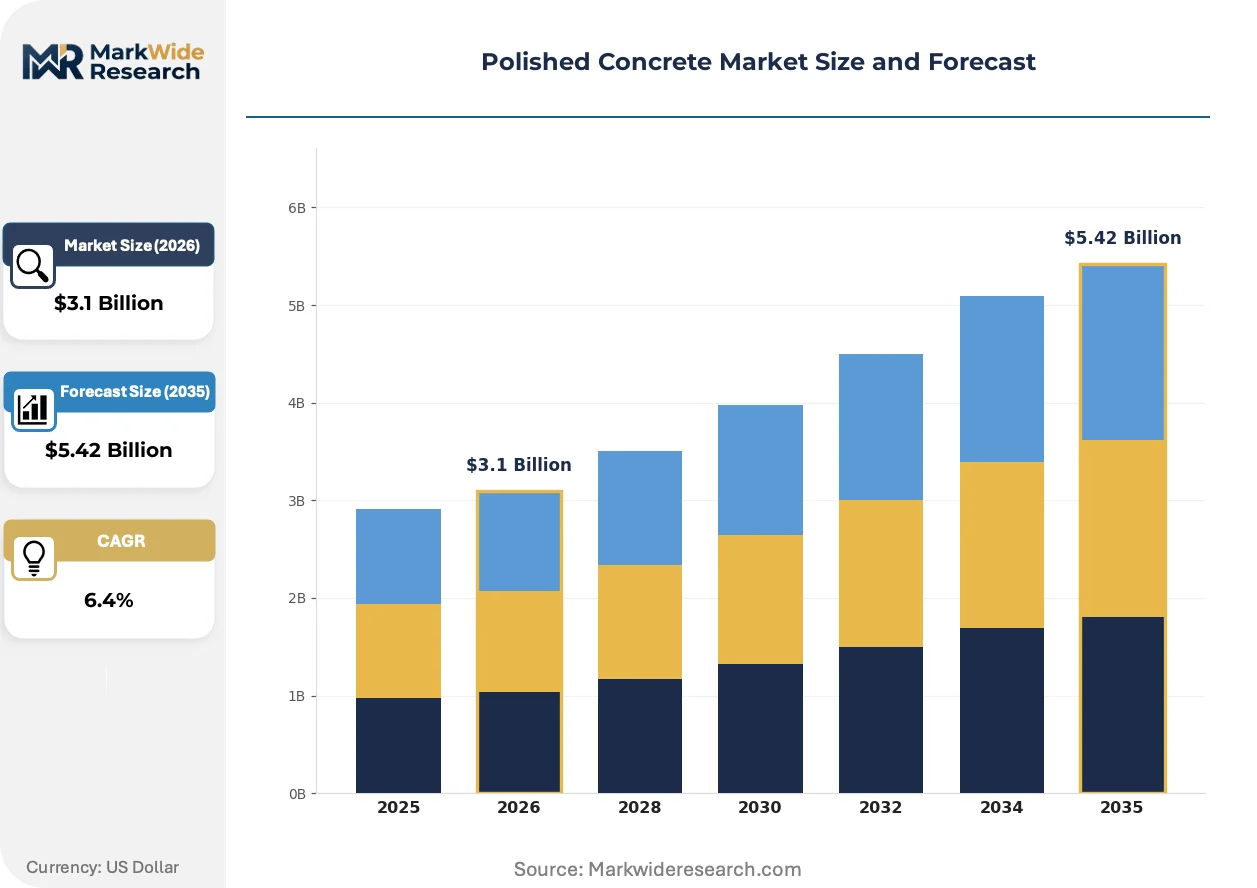
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Grinder, Densifier, Sealer, Polishing Pad, Diamond Tool, Edger Application: Commercial Spaces, Industrial Facilities, Educational Institutions, Warehouses, Showrooms, Public Buildings End User: Construction Companies, Facility Managers, Property Developers, Interior Designers, Government Organizations Technology: Diamond Polishing, Acid Etching, Mechanical Grinding, Resin Bond, Metal Bond, Vacuum Assisted Polishing |
| Companies Covered | BASF SE, Sika AG, PPG Industries Inc., 3M Company, The Sherwin-Williams Company, UltraTech Cement Limited, Boral Limited, Husqvarna AB, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polished Concrete Market Strategic Shifts & Innovations
The polished concrete industry is professionalizing, driven by innovations in material science and a stricter regulatory environment. These shifts are moving the market away from a simple trade toward a specialized practice demanding certified expertise and advanced, system-based approaches to flooring.
Chemical densifier technology provides the foundation for surface hardness and durability. Advanced lithium silicate formulations are gaining traction over traditional sodium or potassium silicates for their deeper penetration and superior gloss retention. High-end commercial and data center projects are rapidly adopting these premium chemicals, and the market for floor treatments is migrating from simple topical coatings toward integrated, penetrating systems that chemically modify the concrete itself.
Worker safety regulations are fundamentally altering job site practices. The US Occupational Safety and Health Administration's (OSHA) standard for respirable crystalline silica exposure mandates stringent dust control measures during grinding operations. This forces contractors to invest in and utilize either wet grinding methods or industrial-grade vacuum systems with HEPA filtration. This regulation most directly impacts contractors in the United States, increasing equipment costs and operational complexity.
A notable behavioral shift is occurring in how polishing services are specified and procured for major projects. Clients are increasingly requiring that applicators be certified directly by the manufacturer of the densifier and sealer systems. This disrupts the traditional open-bid model for independent contractors, creating a preference for firms within a manufacturer's certified network. This trend is most pronounced in large-scale commercial and institutional projects in North America where long-term performance warranties are critical.
Polished Concrete Market Segmentation
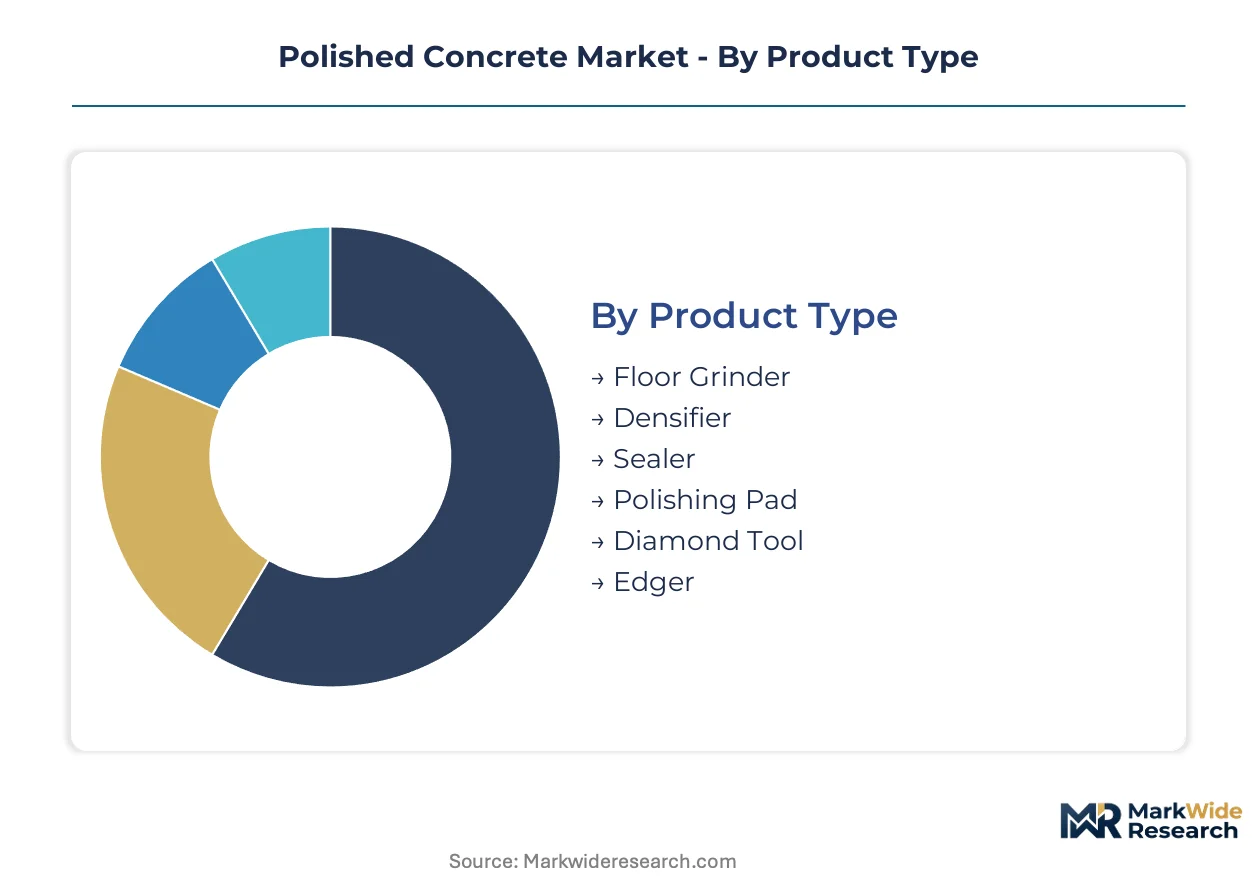
The polished concrete market segments reflect the diverse inputs and processes required to transform raw concrete into a finished surface. Understanding these distinct categories helps identify where value accrues across the supply chain, from specialized equipment to chemical treatments and application techniques.
Product Type:
The turnover rates for product types vary significantly, with consumables requiring frequent replenishment compared to capital equipment. Capital outlays for machinery represent a slower cycle, while chemical treatments and abrasives are purchased regularly.
- Densifier:These chemical solutions penetrate concrete to increase surface hardness and abrasion resistance, typically silicate-based formulations. Demand concentrates in commercial and industrial settings in the United States, driven by requirements for long-term durability.
- Sealer:Applied after densification, sealers protect the polished surface from stains and moisture, often using water-based or acrylic formulations. High-traffic retail spaces in Germany frequently specify advanced sealers for enhanced aesthetic protection.
- Floor Grinder:Heavy-duty machinery equipped with rotating diamond abrasives for initial surface preparation and progressive polishing. These represent a significant capital investment for contractors entering the market.
- Polishing Pad:Abrasive pads, often resin-bonded, used in sequence with floor grinders to achieve specific levels of sheen. Contractors purchase these routinely based on project requirements.
- Diamond Tool:Metal-bonded or resin-bonded tools containing industrial diamonds, essential for the mechanical grinding and polishing stages. Their lifespan depends on usage intensity and substrate hardness.
- Edger:Smaller, specialized grinding machines designed to polish concrete surfaces close to walls and corners where larger grinders cannot reach. These ensure a consistent finish across the entire floor area.
Densifier products dominate the installed chemical base. Sealer products are where expansion concentrates due to evolving aesthetic and protective demands.
Application:
Application segments are differentiated by the volume of material and labor required, with large-scale industrial projects consuming significant quantities and high-end commercial spaces demanding specialized finishes.
- Commercial Spaces:These include retail stores, offices, and showrooms, prioritizing aesthetic appeal, durability, and ease of maintenance. Projects often feature custom designs and higher sheen levels.
- Industrial Facilities:Encompassing factories, manufacturing plants, and workshops, these applications emphasize extreme durability, chemical resistance, and non-slip properties. Volume requirements are substantial for these large-footprint areas.
- Warehouses:Large-scale storage facilities that require highly durable, reflective, and easy-to-clean floors to support heavy machinery traffic and logistics operations. These projects drive consistent demand for polishing services.
- Educational Institutions:Schools and universities utilize polished concrete for its longevity, low maintenance, and aesthetic qualities in high-traffic hallways and common areas. Budgets often influence material choices.
- Showrooms:Spaces designed to display products, where polished concrete enhances visual appeal and provides a sophisticated backdrop. High-gloss finishes are frequently specified.
- Public Buildings:Government offices, libraries, and community centers adopt polished concrete for its cost-effectiveness, sustainability profile, and ability to withstand heavy foot traffic.
High-volume applications like warehouses provide a stable foundation. Premium commercial spaces drive innovation in decorative finishes.
End User:
End user segments reflect the primary decision-makers and procurement channels for polished concrete services, ranging from direct project owners to specialized contractors.
- Construction Companies:These firms integrate polished concrete as part of new build or major renovation projects, often subcontracting the specialized polishing work. They focus on project timelines and overall cost efficiency.
- Facility Managers:Responsible for the upkeep and maintenance of existing commercial and industrial properties, they procure polishing services for refurbishment or ongoing floor care. Long-term durability and maintenance costs are key considerations.
- Property Developers:These entities initiate and oversee new commercial or residential developments, specifying polished concrete for its aesthetic and functional benefits to attract tenants or buyers. Design trends influence their choices.
- Interior Designers:Often specify polished concrete for its aesthetic versatility and modern appeal in commercial and high-end residential projects. They focus on color, aggregate exposure, and sheen level.
- Government Organizations:Procure polished concrete for public infrastructure, administrative buildings, and schools, driven by mandates for durability, sustainability, and life-cycle cost efficiency.
Construction companies frequently initiate polishing projects. Facility managers drive recurring service demand.
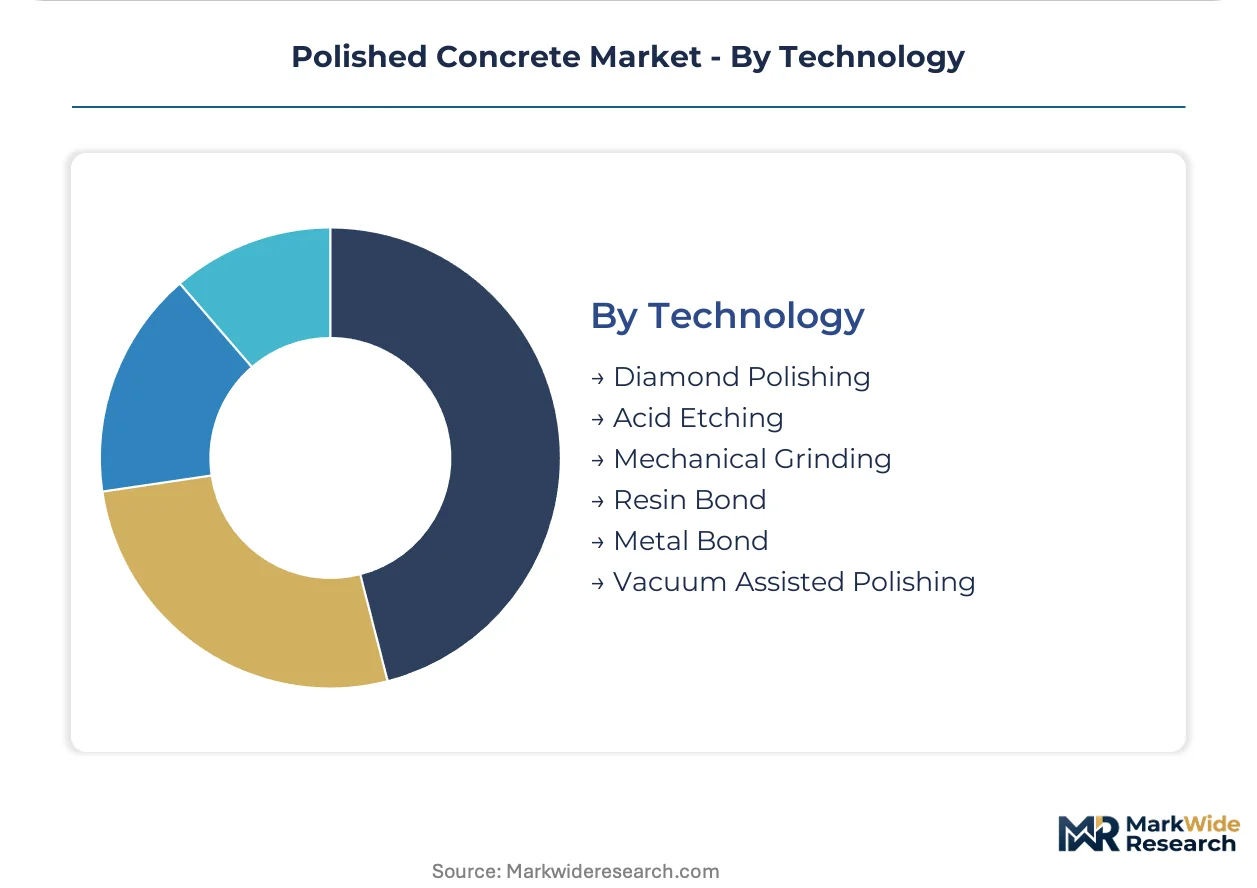
Technology:
Technology segments highlight the distinct methods and material science employed in achieving polished concrete surfaces, influencing both performance and environmental compliance.
- Diamond Polishing:This broad category encompasses the use of diamond abrasives in various forms to mechanically grind and polish concrete surfaces to a desired sheen. It is the most common method.
- Mechanical Grinding:The core process involving heavy machinery with rotating diamond tools to remove surface imperfections and progressively refine the concrete. This method is fundamental to modern polished concrete.
- Vacuum Assisted Polishing:Integrates dust extraction systems with grinding equipment to capture respirable silica, ensuring compliance with worker safety regulations like those from OSHA. This technology is critical for health and safety on job sites.
- Acid Etching:A chemical process using acids to lightly abrade the concrete surface, primarily for decorative effects or preparing for coatings, rather than achieving a true mechanical polish. This method has environmental considerations.
- Resin Bond:Refers to diamond tools where abrasive particles are embedded in a resin matrix, typically used for the finer polishing stages to achieve high gloss. These tools are crucial for aesthetic finishes.
- Metal Bond:Diamond tools where abrasive particles are set in a metal matrix, primarily used for aggressive grinding and initial stock removal of concrete. These tools are essential for surface preparation.
Mechanical grinding forms the process foundation. Vacuum assisted polishing represents a critical safety and compliance innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robust port infrastructure underpins the global distribution of construction materials, influencing regional market dynamics for polished concrete. These logistical hubs facilitate the movement of specialized equipment and chemical treatments across continents. Key regions demonstrate distinct drivers and regulatory influences shaping market expansion.
United States
Demand for polished concrete in the United States is strong due to extensive commercial construction and renovation projects. The US EPA's VOC limits significantly influence the formulation of water-based sealers and densifiers. Major metropolitan areas like New York City and Los Angeles drive substantial demand for high-end decorative finishes in commercial spaces.
Germany
Germany's robust commercial construction sector, particularly in retail and office spaces, provides consistent demand for polished concrete. The REACH directive governs the chemical composition of densifiers, ensuring environmental compliance. Industrial centers such as the Ruhr Area and Munich see high adoption rates for durable, low-maintenance flooring solutions in manufacturing facilities.
China
China's rapid urbanization and infrastructure development fuel significant demand for polished concrete in industrial and commercial applications. The country's dual carbon goals promote sustainable construction practices, favoring long-lasting and energy-efficient flooring options. Large-scale projects in cities like Shanghai and Beijing integrate polished concrete for its aesthetic and functional benefits in public buildings.
India
India's expanding commercial and warehousing sectors are driving demand for polished concrete due to its durability and cost-effectiveness. BIS standards for construction materials are increasingly influencing product selection and quality requirements. Industrial corridors around Mumbai and Delhi are witnessing increased adoption for large-volume industrial flooring projects.
Polished Concrete Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential materials and equipment. The market exhibits a tiered structure, with large chemical companies offering integrated solutions alongside specialized equipment manufacturers. Strategic archetypes include chemical formulators, equipment providers, and comprehensive system suppliers. Key competitive moves involve building certified applicator networks and diversifying product portfolios to cover both consumables and capital goods.
Within the integrated system supplier archetype, companies like Sika AG and BASF SE leverage extensive chemical expertise to offer comprehensive material solutions. Sika AG provides integrated systems of densifiers and sealers, often linking product supply to specific applicator training for quality assurance. Similarly, BASF SE, with its broad chemical portfolio, contributes advanced formulations that enhance concrete durability and aesthetics. Meanwhile, Husqvarna AB exemplifies a strategy centered on equipment, bundling its advanced grinding machinery with comprehensive operator certification programs. These entities represent the market's drive towards more integrated and professionally supported solutions for polished concrete applications.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| PPG Industries Inc. |
| 3M Company |
| The Sherwin-Williams Company |
| UltraTech Cement Limited |
| Boral Limited |
| Husqvarna AB |
| Saint-Gobain |
| Others |
Cost & Logistics Intelligence
Contractor capacity utilization in major commercial hubs like New York City directly impacts pricing for polishing services, influencing both material procurement and project bids.
Pricing Analysis
Volume-based project pricing structures govern polished concrete services, with significant discounts offered for large-scale industrial and warehouse projects. Price differentiation stems from manufacturer certification levels for applicators and the degree of decorative customization required for high-end commercial spaces. Upward pricing pressure arises from increasing regulatory compliance costs, including specialized equipment for OSHA silica dust rules. Industrial facilities and educational institutions exhibit higher price sensitivity compared to premium commercial and showroom clients.
Supply Chain Analysis
Specialized chemical feedstocks for densifiers and sealers, alongside industrial diamond sources, form the upstream supply chain for polished concrete. Geographic concentration for these critical inputs includes chemical production in Germany and the United States, with diamond tooling often sourced from China. Single-source vulnerability for advanced lithium silicate formulations and high-grade diamond abrasives presents a structural risk. Distribution runs through certified manufacturer networks and specialized construction material distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
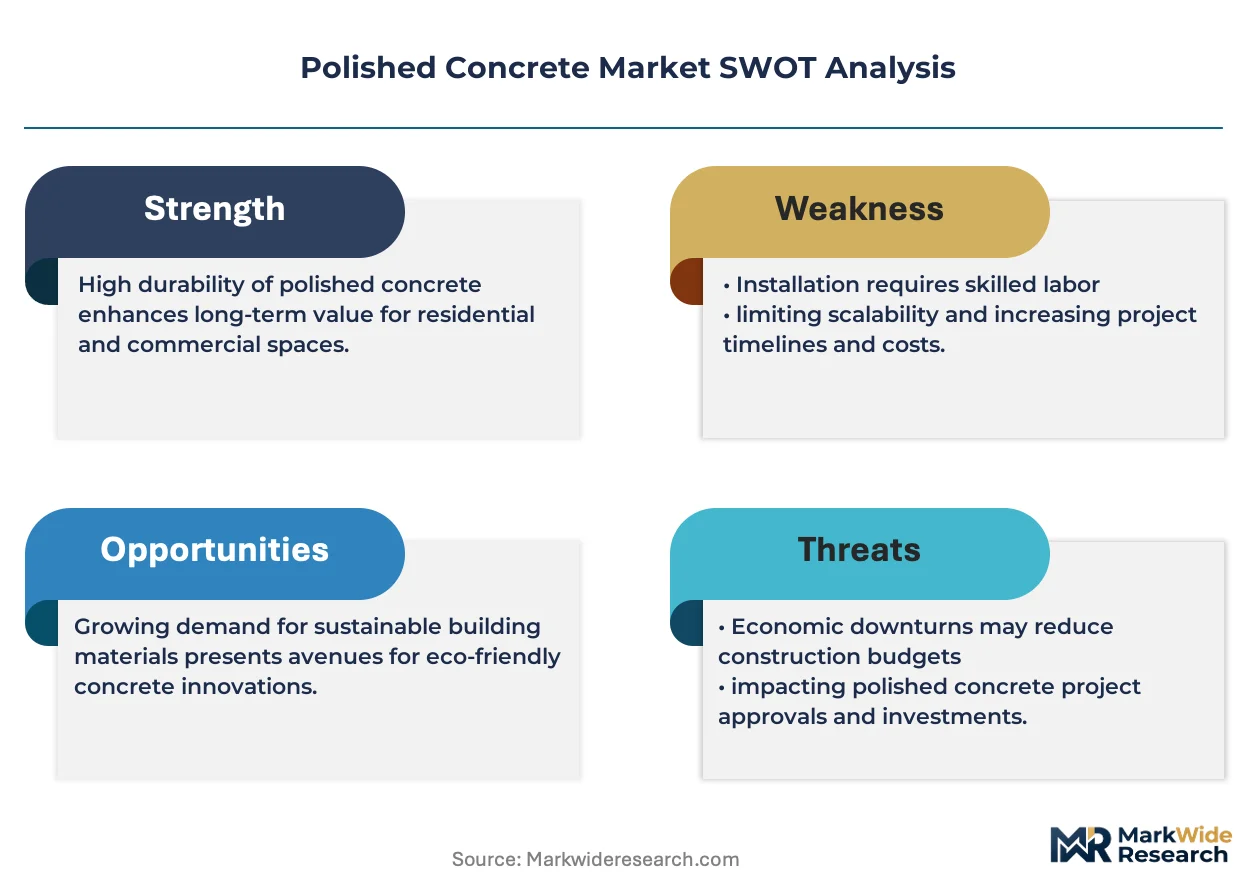
Analyst Recommendations
The polished concrete market faces significant growth constraints due to a pronounced shortage of skilled labor capable of operating advanced grinding machinery and correctly applying complex chemical treatments. This talent gap creates strategic opportunities and challenges across the value chain.
For Market Incumbents: Harden existing certified applicator networks by offering advanced training in high-performance systems and regulatory compliance. Incumbents should invest in developing next-generation low-VOC chemical formulations to preempt future regulatory shifts from bodies like the US EPA. This strategy mitigates the threat of emerging non-compliant solutions and reinforces market leadership through superior product integration and channel control.
For New Entrants and Emerging Players: Build out specialized service offerings targeting the high-end residential market, focusing on basements, garages, and luxury living spaces. New entrants can also explore functional surface integration, embedding technologies like radiant heating elements during the pre-polishing phase. The most penetrable segment lies in niche decorative finishes for smaller commercial projects, leveraging a premium service model focused on unique aesthetic solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized chemical formulators providing densifiers and sealers, offering stable cash flows over the long term. Investors should target vertically integrated equipment manufacturers with robust consumable portfolios and established certified applicator programs. A critical signal to watch is the expansion rate of manufacturer-sponsored training and certification programs, indicating increasing control over the service delivery ecosystem.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Certified Applicator Networks | This initiative ensures quality control and long-term performance warranties for major projects. |
| Invest in Low-VOC Material R&D | Developing compliant water-based sealers addresses US EPA and REACH regulatory mandates. |
| Integrate Functional Surface Technologies | Embedding radiant heating elements creates value-added smart floors for commercial clients. |
| Diversify Decorative Finish Options | Offering custom colors and aggregates unlocks premium pricing tiers in hospitality segments. |
| Advance Silica Dust Control Solutions | Improving HEPA filtration systems helps contractors meet stringent OSHA worker safety regulations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents from the US EPA and Europe's REACH directive, alongside construction industry reports. Primary interviews engaged polishing contractors, material manufacturers, facility managers, and property developers to capture market nuances. This approach ensured bottom-up and top-down triangulation of market data. The analysis integrated insights from equipment suppliers and chemical formulators.
Forecast inputs considered commercial construction activity, renovation project pipelines, and evolving environmental regulations across the analysis window. The analytical framework modeled market dynamics across product types, application segments, end-user categories, and specific polishing technologies. Compound annual growth rates were derived from historical data and projected market drivers. Industry-specific inputs included the adoption rate of low-VOC sealers and capital expenditure on advanced grinding equipment.
Stress conditions across commercial construction spending and regulatory stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained economic growth and continued regulatory enforcement. Cross-checking against national construction statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
North Africa Cement Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
PVC Window Market