
 Elastomeric Expansion Joint Market | 2026-2036
Elastomeric Expansion Joint Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Expansion Joint Market Insights
Advanced compounding of fluoroelastomer and hydrogenated nitrile variants is rewriting durability benchmarks for high-cycle expansion joint applications. EagleBurgmann leverages its sealing technology heritage to dominate critical infrastructure tenders across Central Europe. BOA Group anchors its position through backward integration into precision metal bellows and elastomer bonding processes. Senior Flexonics competes on geographic reach, with manufacturing footprints spanning North America and Asia-Pacific.
An elastomeric expansion joint is a flexible connector manufactured from synthetic rubber compounds—typically EPDM, neoprene, or silicone—reinforced with fabric plies and metal flanges, designed to absorb thermal expansion, vibration, and misalignment in piping and ducting systems. These joints accommodate movement ranges from 10 mm to over 300 mm axial compression while maintaining pressure ratings up to 25 bar, serving essential functions in power generation, chemical processing, and building HVAC distribution networks. Single sealed configurations retain the largest installed base due to their cost efficiency in standard-duty water and air handling applications, though custom designed variants command the deepest margin pools where project-specific geometry and chemical resistance requirements preclude catalog solutions. EPDM compounds lead volume demand given their superior ozone and weathering resistance in outdoor installations, while silicone grades are displacing neoprene in high-temperature exhaust and turbine applications.
ISO 9001 quality management and EN 1533 ductile iron standards shape product certification requirements across European supply chains, while the US EPA's New Source Performance Standards for industrial boilers drive retrofit demand for emission-compliant expansion joint materials. In China, GB/T 12777 pressure piping standards and MEE environmental enforcement tighten market access for imported elastomeric components. Stakeholders must monitor divergence between regional material approval regimes and the pace of bio-based elastomer commercialization.
Market Dynamics
The EU F-Gas Regulation and REACH compliance frameworks are compressing material specification windows, forcing compounders to accelerate fluorocarbon alternative development while maintaining high-temperature performance thresholds for power generation and district heating infrastructure.
Growth Catalysts
- High-temperature hydrogenated nitrile compounds:These materials extend service life in turbine exhaust applications beyond 150°C thresholds, capturing procurement interest from combined-cycle power plant operators in Germany's industrial corridor.
- EPDM ozone resistance specifications:Outdoor HVAC and water distribution networks across the EMEA region specify EPDM compounds for installations exposed to ultraviolet degradation and atmospheric pollutants.
- Combined heat and power retrofit mandates:District heating utilities in Scandinavia and Central Europe are replacing legacy metallic expansion joints with elastomeric alternatives to reduce thermal losses and vibration transmission.
Market Restraints
- Fluoroelastomer feedstock concentration:Specialty fluoropolymer resin supply concentrates among a limited base of chemical producers, creating input cost volatility and allocation risk for high-performance joint manufacturers.
- REACH substance restriction timelines:The European Chemicals Agency's phased restrictions on per- and polyfluoroalkyl substances compress reformulation windows while qualification protocols extend commercialization cycles.
- Metallic bellows substitution in ultra-high-pressure:Precision-formed stainless steel bellows retain preference in nuclear and supercritical steam applications above 25 bar, capping elastomeric penetration in premium pressure tiers.
Strategic Opportunities
- Bio-based synthetic rubber commercialization:Bio-EPDM and bio-silicone pilot production from agricultural feedstocks offers pathway to carbon footprint reduction for sustainability-mandated infrastructure tenders.
- Digital twin integration for predictive maintenance:Embedding fiber optic strain sensors within elastomeric plies enables real-time deformation monitoring, creating subscription revenue streams from asset operators.
- India's National Infrastructure Pipeline:Thermal power and petrochemical capacity additions under the government's capital expenditure program generate import substitution demand for domestically manufactured expansion joints.
Industry Challenges
- Multi-standard certification complexity:Manufacturers serving cross-border projects must simultaneously maintain EN 1533 ductile iron approvals, ISO 9001 quality systems, and country-specific pressure equipment directives, extending bid preparation timelines.
- Skilled elastomer-to-metal bonding technicians:The specialized craft of vulcanizing fabric-reinforced compounds to precision-machined flanges faces generational workforce gaps in traditional manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Expansion Joint Market |
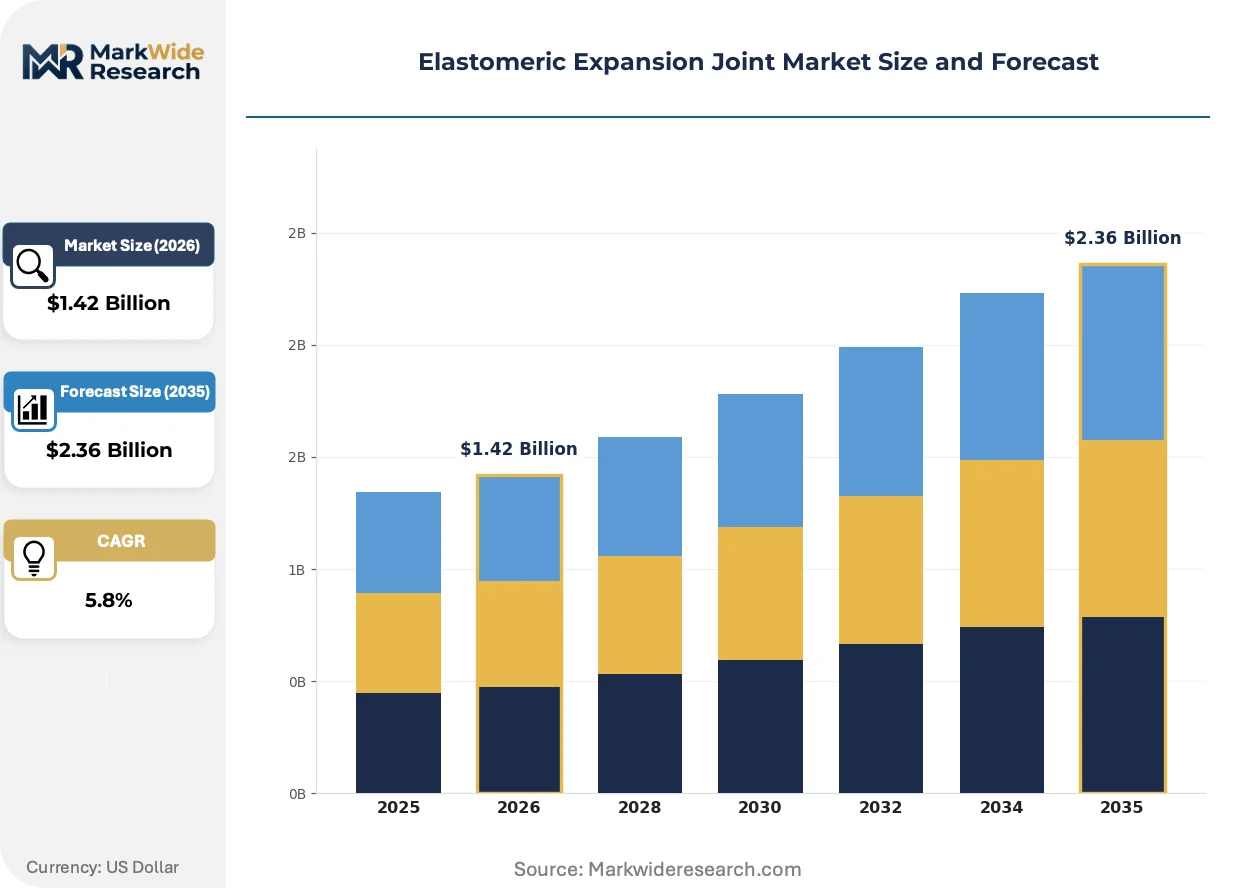
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Sealed, Double Sealed, Multi-Sealed, Custom Designed Material: EPDM, Neoprene, Silicone, PVC Installation Method: Above Ground, Below Ground, Indoor, Outdoor End User Segment: Infrastructure, Automotive, Aerospace, Marine |
| Companies Covered | Senior Flexonics, EagleBurgmann, Witzenmann GmbH, BOA Group, Flexider, Macoga, Metraflex, Garlock, ContiTech AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Expansion Joint Market Trends and Innovations
Computational materials science and embedded sensor architectures are compressing product development cycles while enabling condition-based maintenance contracts that restructure traditional equipment procurement economics.
Multilayer fluoroelastomer-silicone hybrid compounds are virtualizing the performance envelope for high-cycle applications by combining chemical resistance with thermal stability in single-architected joints. Power plant maintenance contractors in Germany and the Netherlands are specifying these hybrids for flue gas desulfurization ducting where sulfuric acid condensate and temperature spikes co-occur. The technology is virtualizing the historical trade-off between chemical compatibility and heat aging, collapsing the need for separate inventory stocking of neoprene and silicone variants.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon propellants and process agents is redirecting compounder R&D toward aqueous dispersion curing systems and supercritical CO2 processing. Fluorocarbon elastomer manufacturers face reformulation costs and capital equipment replacement for mixing and extrusion lines previously dependent on solvent-based processing. German chemical processors are responding by consolidating production in fewer, larger facilities capable of capturing and recycling alternative blowing agents.
Engineering-procurement-construction firms are unbundling expansion joint specification from general piping contracts, creating direct manufacturer-to-operator relationships that compress distributor margins. Major district heating utilities in Denmark and Sweden now maintain approved vendor lists with pre-qualified elastomeric joint suppliers, bypassing traditional MRO distributors for critical spares. This disintermediation is most pronounced in Nordic markets where utility consolidation has concentrated buying power among three national heating network operators.
Elastomeric Expansion Joint Market Segmentation
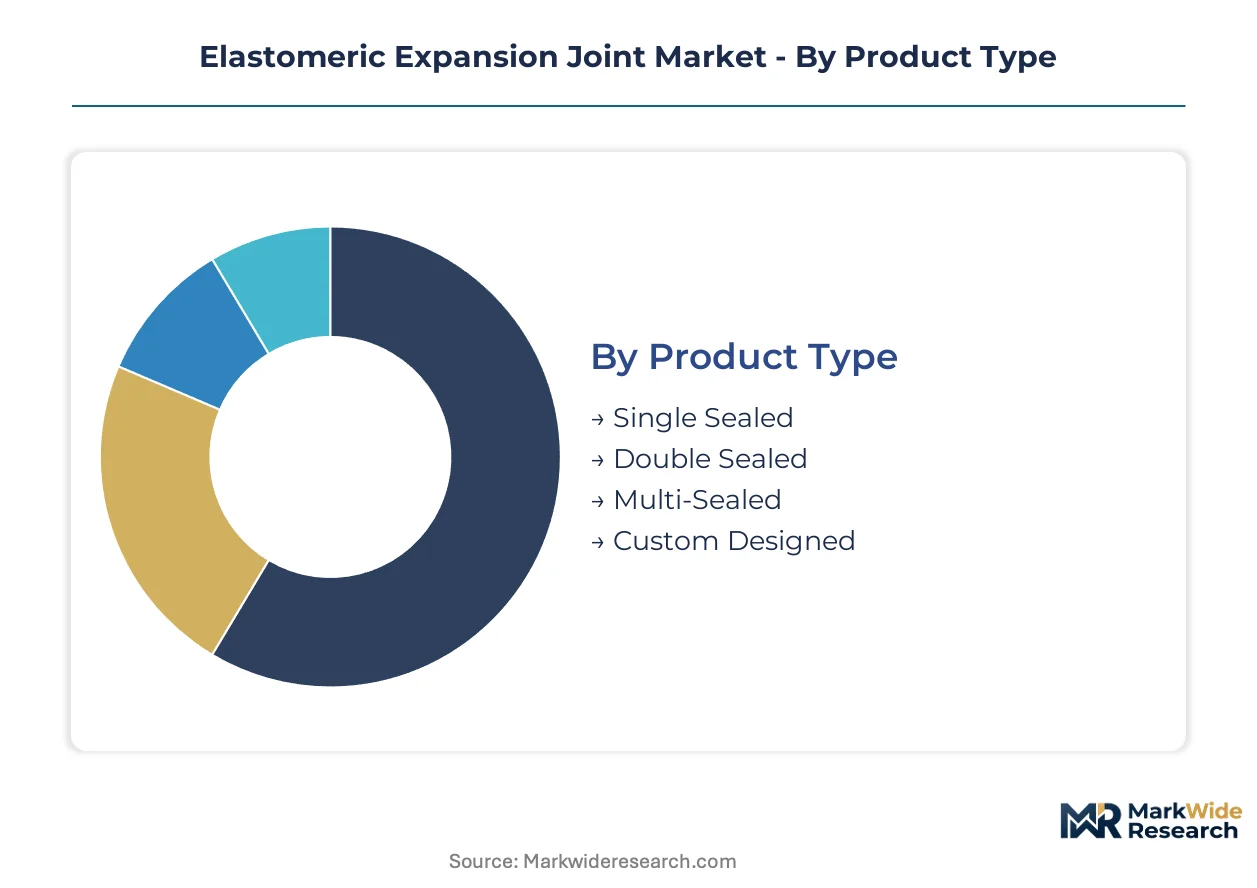
Elastomeric expansion joint procurement varies sharply by duty cycle, environmental exposure, and regulatory jurisdiction. Compound selection and sealing architecture determine lifecycle economics across power generation, chemical processing, and building infrastructure applications.
Product Type:
Single-arch designs dominate low-pressure HVAC and water distribution, while multi-sealed configurations capture premium process industry specifications.
- Single Sealed:Fabric-reinforced EPDM or neoprene compounds vulcanized to ductile iron flanges serve standard-duty air and water handling systems. District heating utilities in Denmark and Sweden specify these for thermal expansion absorption in buried distribution networks where cost efficiency outweighs redundancy requirements.
- Double Sealed:Dual-elastomer layers with intermediate fabric reinforcement create redundant sealing planes for chemical processing and flue gas desulfurization ducting. Combined-cycle power plant operators in Germany's industrial corridor favor these for turbine exhaust applications where thermal cycling and condensate exposure co-occur.
- Multi-Sealed:Triple-layer architectures with fluoroelastomer inner plies and silicone outer jackets address aggressive chemical and temperature profiles in refinery and petrochemical service.
- Custom Designed:Project-specific geometry, non-standard movement ranges, and proprietary flange interfaces serve OEM equipment integration and retrofit constraints in legacy industrial infrastructure.
The dominant share belongs to Single Sealed configurations, while Custom Designed variants are climbing the fastest as project-specific qualification protocols displace catalog specifications.
Material:
Compound selection traces a cost-performance frontier from commodity EPDM through high-temperature silicone and chemical-resistant fluoroelastomer grades.
- EPDM:Ethylene-propylene-diene terpolymer compounds deliver superior ozone and ultraviolet resistance for outdoor installations. Scandinavian district heating networks and German municipal water utilities specify EPDM for buried and exposed piping subject to atmospheric degradation and thermal aging.
- Silicone:Polysiloxane-based elastomers maintain elasticity beyond 200°C, displacing neoprene in turbine exhaust and high-temperature ventilation applications. REACH compliance pressures and F-Gas Regulation constraints are accelerating silicone adoption as fluorocarbon alternatives face substance restriction timelines.
- Neoprene:Chloroprene compounds retain installed base in marine and coastal applications where oil resistance and moderate weathering performance suffice.
- PVC:Thermoplastic formulations serve cost-sensitive drainage and low-pressure air handling where elastomeric flexibility requirements are minimal.
EPDM retains volume leadership in outdoor infrastructure, though silicone is expanding most quickly in power generation retrofit programs.
Installation Method:
Mounting geometry dictates reinforcement architecture, with buried installations requiring enhanced crush resistance and moisture barriers.
- Above Ground:Exposed piping in power plants and chemical facilities demands UV-stabilized compounds and weather-resistant cover plies. German industrial corridor specifications emphasize EN 1533 ductile iron flange compatibility for rack-mounted process piping.
- Below Ground:Buried district heating and water distribution networks require reinforced arch designs resistant to soil loading and groundwater ingress. Danish utility procurement standards mandate 50-year service life projections for subterranean elastomeric joints.
- Indoor:Controlled-environment HVAC and process piping within buildings permits lighter-weight constructions with reduced weathering specifications.
- Outdoor:Bridge-mounted and rooftop installations combine thermal expansion absorption with wind load and seismic movement accommodation.
Above Ground deployment holds the dominant position, while Below Ground applications are gaining share fastest as district heating network expansion accelerates across Northern Europe.
End User Segment:
Demand concentrates in heavy infrastructure, with automotive and aerospace representing specialized niche specifications.
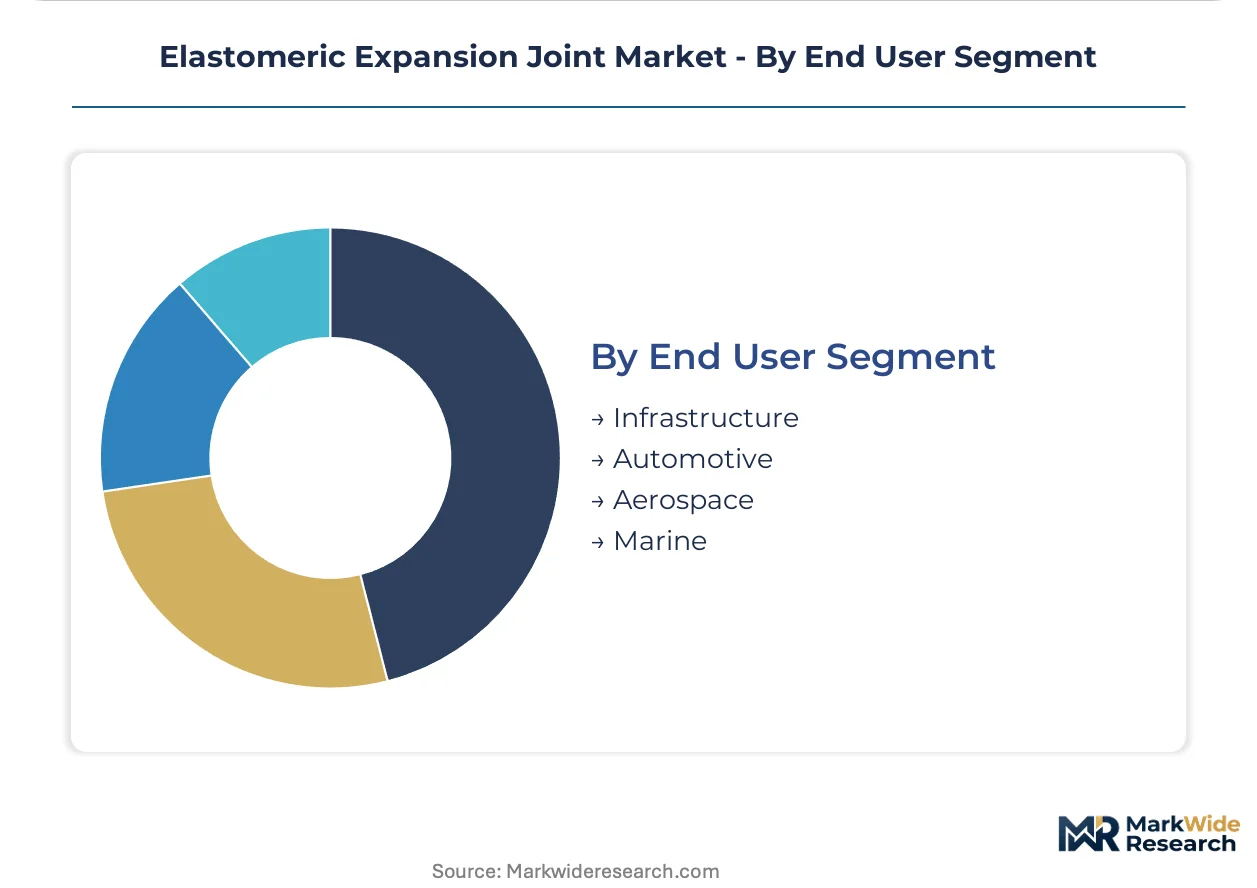
- Infrastructure:Power generation, district heating, water treatment, and building HVAC systems generate the bulk of elastomeric joint procurement. Combined heat and power retrofit mandates across Germany, Denmark, and Sweden are replacing legacy metallic expansion joints with elastomeric alternatives to reduce thermal losses.
- Automotive:Exhaust system flex joints and vibration isolation mounts in commercial vehicles require compact, high-cycle elastomeric designs.
- Aerospace:Aircraft environmental control systems and ground support equipment specify lightweight, fire-resistant silicone compounds meeting stringent smoke and toxicity standards.
- Marine:Shipboard piping, offshore platform HVAC, and desalination plant intake systems demand saltwater-resistant neoprene and EPDM formulations.
Infrastructure commands the dominant share, while Marine applications are expanding most quickly as offshore energy and desalination capacity builds accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers supply elastomeric expansion joints to district heating utilities across Scandinavia and Central Europe, anchoring a trade corridor that channels precision-engineered components northward from the industrial corridor around Düsseldorf and Cologne.
Germany
Combined-cycle power plant operators in the Rhine-Ruhr and Bavarian industrial zones specify hydrogenated nitrile compounds for turbine exhaust service above 150°C. The EU F-Gas Regulation and REACH compliance frameworks tighten material specifications for fluorocarbon alternatives. Witzenmann GmbH and BOA Group anchor regional supply chains serving EMEA procurement.
Denmark
Danish district heating utilities consolidate buying power through three national network operators, bypassing traditional MRO distributors for critical spares. The Danish Energy Agency enforces 50-year service life projections for subterranean elastomeric joints in buried distribution networks. Copenhagen's metropolitan heating grid replaces legacy metallic expansion joints with elastomeric alternatives to cut thermal losses.
Sweden
Scandinavian district heating retrofit mandates drive replacement of metallic joints with EPDM-reinforced elastomeric configurations in buried and exposed piping. Swedish Environmental Protection Agency oversight aligns with EU Green Deal decarbonization targets for combined heat and power infrastructure. Stockholm's district heating authority maintains approved vendor lists with pre-qualified suppliers for critical network spares.
Netherlands
Power plant maintenance contractors specify multilayer fluoroelastomer-silicone hybrid compounds for flue gas desulfurization ducting where sulfuric acid condensate and temperature spikes coincide. Dutch emission regulations under the EU Industrial Emissions Directive accelerate material upgrade cycles. Rotterdam's port-industrial complex generates demand for saltwater-resistant neoprene formulations in marine HVAC and desalination intake systems.
China
GB/T 12777 pressure piping standards and MEE environmental enforcement tighten market access for imported elastomeric components in thermal power and petrochemical capacity additions. Provincial infrastructure investment under the National Infrastructure Pipeline generates import substitution demand for domestically manufactured expansion joints. Yangtze River Delta fabricators scale production to serve state-owned utility procurement.
Elastomeric Expansion Joint Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates premium-tier supply among German and Swiss engineering groups while fragmenting standard-duty production across regional metalworking clusters. Two strategic archetypes dominate: vertically integrated European specialists with captive elastomer compounding and bonding capabilities, and geographic-diversified fabricators competing on multi-regional manufacturing footprints. Competitive moves center on backward integration into precision metal bellows production and disintermediation of distributor relationships through direct utility procurement channels.
Among German-based engineering groups, Witzenmann GmbH and BOA Group exemplify the vertically integrated archetype with in-house control over elastomer-to-metal bonding processes. EagleBurgmann occupies a position representing sealing technology heritage applied to critical infrastructure tenders across Central Europe. Senior Flexonics sits within the geographic-diversification archetype, with manufacturing footprints spanning North America and Asia-Pacific to serve project logistics requirements.
| Leading Market Players |
|---|
| Senior Flexonics |
| EagleBurgmann |
| Witzenmann GmbH |
| BOA Group |
| Flexider |
| Macoga |
| Metraflex |
| Garlock |
| ContiTech AG |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in standard-duty EPDM compounding across China's Yangtze River Delta compresses spot pricing for commodity-grade expansion joints, forcing European manufacturers to emphasize qualification-intensive custom geometries and REACH-certified compounds to defend margin structures.
Pricing Analysis
Technology-generation pricing gaps separate legacy neoprene formulations from hydrogenated nitrile and fluoroelastomer-silicone hybrids, with next-generation compounds commanding substantial premiums for turbine exhaust and flue gas desulfurization service. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, though cost compression in commodity EPDM intensifies as Chinese fabricators absorb excess capacity. District heating utilities in Scandinavia exhibit lowest price sensitivity due to mandated service life requirements, while MRO distributors face margin erosion from direct manufacturer-to-operator procurement channels.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for elastomeric expansion joint procurement, particularly for fabric-reinforced compounds and ductile iron flange castings. Manufacturing concentrates in Germany, China, and India, with specialty fluoropolymer resin supply resting on a limited base of chemical producers in the United States and Japan. Raw material dependencies span synthetic rubber feedstocks, fabric reinforcement textiles, and precision-machined metal components. Distribution runs through engineering-procurement-construction firms and direct utility procurement channels, with the latter gaining share in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's phasedown of hydrofluorocarbon process agents constitutes a regulatory inflection that will reshape compounder economics and procurement specifications across power generation and district heating infrastructure.
For Market Incumbents: Harden qualification protocols for fluorocarbon alternative compounds to preempt ECHA substance restriction timelines. Anchor backward integration into precision metal bellows production to capture margin pools in multi-sealed architectures. Defend against distributor disintermediation by securing approved vendor list positions with consolidated Nordic heating network operators.
For New Entrants and Emerging Players: Build out bio-based synthetic rubber pilot capacity to serve sustainability-mandated infrastructure tenders in Germany and Denmark. Target India's National Infrastructure Pipeline thermal power additions where import substitution demand favors domestic fabrication. Pursue embedded sensor integration partnerships to enable predictive maintenance subscription revenue from asset operators.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fluoroelastomer compounding as aqueous dispersion curing systems and supercritical CO2 processing equipment replace solvent-based lines. The viable acquisition window favors vertically integrated specialists with captive elastomer-to-metal bonding capabilities and EN 1533 certification infrastructure. Monitor ECHA restriction timeline acceleration as the signal indicating compounder consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Bellows | Captures margin pools in multi-sealed configurations for German power plant operators. |
| Bio-Based Compound Commercialization | Positions suppliers for EU Green Deal procurement mandates across Scandinavian district heating. |
| Embedded Sensor Architecture Development | Enables condition-based maintenance contracts restructuring traditional equipment economics. |
| Direct Utility Procurement Channel | Bypasses MRO distributor margins in consolidated Nordic heating network markets. |
| REACH Alternative Qualification Investment | Preempts ECHA restriction timelines compressing fluorocarbon elastomer commercialization windows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed industrial equipment manufacturers, European Chemicals Agency regulatory databases, and district heating utility procurement records. Interviews with plant engineers at combined-cycle power facilities, procurement leads at Scandinavian heating network operators, technical R&D directors at elastomer compounders, and aftermarket service heads at expansion joint distributors informed demand-side validation. Bottom-up unit economics and top-down sectoral expenditure analysis were triangulated to anchor market sizing.
Forecast inputs include modeled projections across product type, material compound, installation method, and end-use segment dimensions, with additional granularity for regional regulatory cluster differentiation. Volume and value outputs across the analysis window reflect elasticity-adjusted demand functions incorporating power plant retrofit cycles, district heating network expansion pipelines, and REACH compliance cost pass-through assumptions. CAGRs were derived from segment-level growth rate reconciliation against macro infrastructure investment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated chemical processors or state-backed Chinese fabricators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Drywall Compound and Drywall Mud Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market