
 Industrial Thermal Insulation Market | 2026-2036
Industrial Thermal Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Thermal Insulation Market Outlook
The premium engineered insulation tier is decoupling from commodity fiberglass on thermal performance guarantees and lifecycle cost metrics. Owens Corning leverages its glass fiber science platform to dominate standardized building and industrial applications. ROCKWOOL International A/S anchors its position in high-temperature mineral wool systems for power and process industries. Armacell International S.A. specializes in flexible elastomeric foams for cold-service pipeline and equipment insulation.
Industrial thermal insulation encompasses materials engineered to reduce heat transfer between process equipment and ambient environments, typically rated by thermal conductivity coefficients below 0.05 W/m·K and operating temperature thresholds spanning cryogenic to 1200°C service. Its primary purpose centers on energy conservation, personnel protection, and process temperature stability across continuous manufacturing operations. Mineral wool and calcium silicate segments lead in high-temperature applications above 650°C where fiberglass degrades, while polyurethane foam captures cold-service and cryogenic insulation demand. The retrofit installation category expands fastest as aging industrial infrastructure faces efficiency mandates, whereas prefabricated modules concentrate margin pools through reduced field labor and faster turnaround.
OSHA workplace thermal exposure standards, EPA energy efficiency regulations for industrial boilers, and ISO 23993 insulation performance benchmarks collectively reshape product specifications and compliance documentation burdens. The EU F-Gas Regulation and REACH chemical restrictions further constrain blowing agent and binder chemistries available to European suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and building code harmonization efforts that will determine which insulation technologies qualify for green procurement preferences.
Market Dynamics
Retrofit mandates across aging chemical processing infrastructure are forcing insulation specification upgrades faster than greenfield project cycles, compressing vendor qualification timelines and elevating lifecycle cost analytics over upfront material pricing.
Growth Catalysts
- EPA Boiler MACT Standards:Stringent emissions limits on industrial boilers are compelling facility-wide thermal efficiency upgrades, driving replacement of degraded legacy insulation in US refineries and petrochemical plants.
- Calcium Silicate Systems:Superior compressive strength and dimensional stability above 650°C are displacing refractory brick in high-temperature process equipment, capturing share in power generation and steel applications.
- Gulf Coast Petrochemical Corridor:Concentrated ethylene cracker and derivatives capacity expansion along the Texas-Louisiana coast is generating sustained demand for engineered insulation systems with rapid turnaround installation capabilities.
Market Restraints
- Alumina-Silica Raw Material Volatility:Refractory ceramic fiber feedstock costs fluctuate with bauxite and kaolin mining output constraints, compressing margin stability for high-temperature insulation manufacturers.
- Chinese Mineral Wool Dominance:Concentrated production capacity in Shandong and Hebei provinces creates supply security vulnerabilities for European and North American buyers dependent on imported basalt and slag wool.
- Fiberglass Temperature Ceiling:Thermal degradation above 540°C permanently excludes fiberglass from critical process applications, capping addressable market scope regardless of cost competitiveness.
Strategic Opportunities
- India Petrochemical Buildout:Reliance Industries and Indian Oil Corporation are expanding Jamnagar and Paradip refinery complexes, creating demand for high-performance insulation with local content compliance under PLI scheme incentives.
- Cryogenic LNG Infrastructure:Expanding liquefaction and regasification terminal construction requires vacuum-insulated panels and polyurethane foam systems for sub-minus 160°C service conditions.
- EU Carbon Border Adjustment Mechanism:Embodied carbon tracking requirements are favoring domestically manufactured insulation with verified lifecycle assessments, disadvantaging imports from carbon-intensive production regions.
Industry Challenges
- Certified Insulation Inspector Shortage:Qualified technicians capable of verifying ASTM C335 thermal conductivity testing and NACE coating compatibility are in critically short supply, extending project commissioning timelines.
- Legacy Asbestos Abatement Complexity:Removal of deteriorating asbestos-containing insulation from 1970s-era industrial infrastructure requires specialized remediation protocols that disrupt operational continuity and inflate retrofit costs.
- Multi-Material System Integration:Combining mineral wool, calcium silicate, and protective jacketing in layered configurations demands precision sequencing that field crews frequently execute inconsistently, compromising thermal performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Thermal Insulation Market |
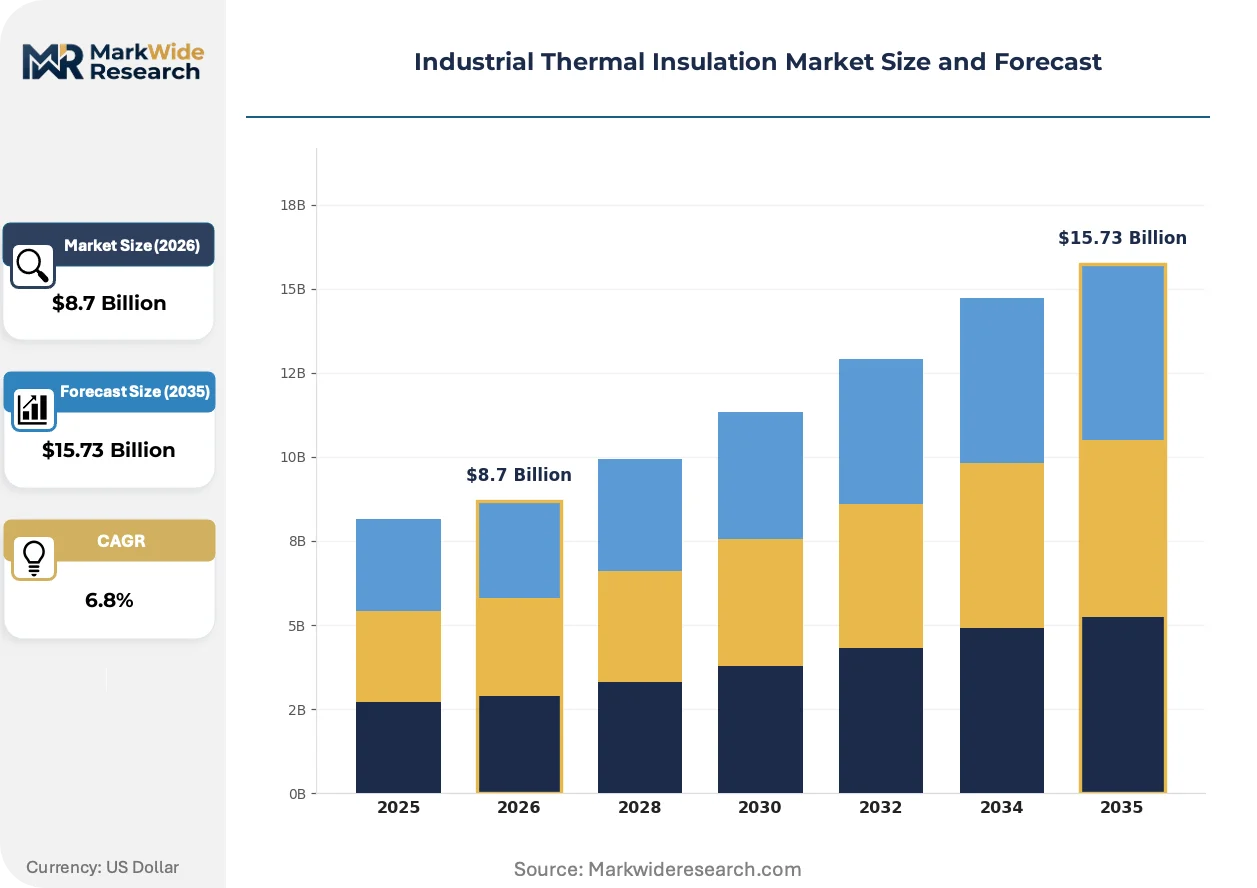
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Mineral Wool, Calcium Silicate, Polyurethane Application: Pipelines, Boilers, Tanks, Industrial Ovens End User: Oil & Gas, Power Generation, Chemical Processing, Manufacturing Installation Type: On-site, Prefabricated, Retrofits, New Constructions |
| Companies Covered | Owens Corning, ROCKWOOL International A/S, Johns Manville, Knauf Insulation, BASF SE, Saint-Gobain, Kingspan Group PLC, Armacell International S.A., Paroc Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Thermal Insulation Market Strategic Shifts
Aerogel composite technologies and digital thermal monitoring systems are converging to redefine performance benchmarks, while regulatory carbon accounting is embedding itself into material selection protocols across process industries.
Aerogel-blanket insulation is consolidating its position in space-constrained applications where thermal efficiency per unit thickness determines project feasibility. Offshore platform operators and modular skid fabricators are specifying silica aerogel composites at accelerating rates despite premium pricing. This material consolidation is compressing the addressable market for conventional multi-layer insulation systems in sub-sea and weight-critical installations.
The EU F-Gas Regulation is systematically restricting hydrofluorocarbon blowing agents in polyurethane foam production, forcing reformulation toward hydro-olefin and water-blown alternatives with modified thermal performance profiles. European cold-service insulation suppliers are absorbing compliance costs while documenting revised lambda values for ISO 23993 certification. This regulatory compression is disadvantaging smaller formulators lacking R&D scale to achieve equivalent insulation values with alternative chemistries.
Integrated energy service contracting is displacing discrete material procurement in large industrial accounts, with insulation performance bundled into guaranteed efficiency outcomes. Engineering-procurement-construction firms are capturing specification authority previously held by maintenance departments, consolidating vendor relationships around turnkey thermal management providers. This channel transformation is most advanced in German chemical parks and US integrated refinery complexes where single-point accountability reduces interface risk.
Industrial Thermal Insulation Market Segmentation
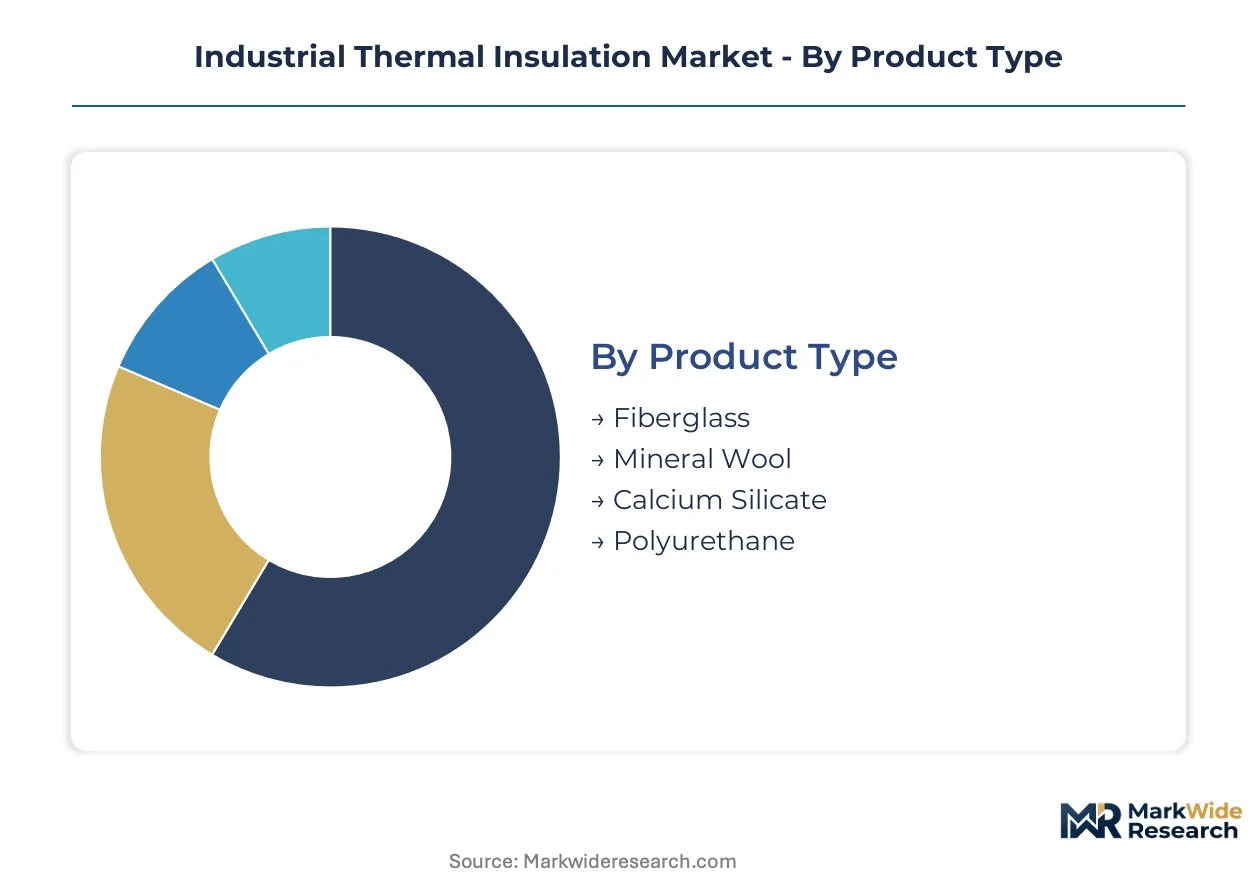
Industrial thermal insulation segments diverge sharply on capital intensity, installation complexity, and regulatory exposure. Procurement patterns cluster around lifecycle cost rather than upfront material pricing, compressing vendor margins in commoditized tiers while rewarding engineered solutions with performance guarantees.
Product Type:
Capital intensity escalates from commodity fiberglass through specialized aerogel composites, with mineral wool and calcium silicate demanding the heaviest upfront manufacturing investment in high-temperature curing equipment and raw material preprocessing infrastructure.
- Mineral Wool:Manufactured from molten basalt or slag spun into fibrous matrices, this segment achieves operating temperatures to 750°C without thermal degradation. Demand concentrates in German power plants and US Gulf Coast refineries where OSHA personnel protection mandates drive specification. Rock and slag wool variants dominate where fire resistance ratings exceed two hours.
- Calcium Silicate:Hydrous calcium silicate formed under autoclave pressure yields rigid boards with compressive strength exceeding 100 psi and dimensional stability through 650°C service. US power generation utilities specify this material for boiler and turbine insulation where mechanical loading occurs. The segment captures premium pricing through ASTM C533 certification requirements.
- Fiberglass:Borosilicate glass fibers bound with phenolic resins serve sub-540°C applications in commercial and light industrial settings.
- Polyurethane:Closed-cell rigid foams blown with hydro-olefin agents insulate cryogenic and sub-ambient pipeline systems.
Most installed capacity flows through Fiberglass. Expansion is steepest in Calcium Silicate.
Application:
Application segments separate by thermal cycling severity, with continuous-duty process equipment demanding engineered multi-layer systems while intermittent-service installations tolerate standardized material packages.
- Pipelines:External cladding systems combine insulation with moisture barriers and protective jacketing to maintain process fluid temperatures across thousands of linear feet. Texas-Louisiana petrochemical corridor operators specify pre-insulated piping modules to compress turnaround schedules. The segment absorbs the largest share of field labor hours in greenfield construction.
- Boilers:High-temperature steam generators require calcium silicate or mineral wool with refractory backup layers to manage thermal shock and erosion. EPA Boiler MACT compliance deadlines are forcing replacement of degraded legacy insulation across US refinery complexes. Inspection protocols under NBIC guidelines extend commissioning timelines.
- Tanks:Vertical and horizontal storage vessels employ spray-applied polyurethane or board insulation depending on product temperature requirements.
- Industrial Ovens:Batch and continuous thermal processing equipment utilizes ceramic fiber modules for rapid heat-up cycles.
Procurement volume concentrates in Pipelines. Specification upgrades are accelerating fastest in Boilers.
End User:
End user segments stratify by safety culture maturity, with oil and gas majors enforcing the most rigorous material certification and installation quality protocols through corporate engineering standards.
- Chemical Processing:Ethylene crackers, ammonia plants, and chlor-alkali facilities operate across cryogenic to 1000°C temperature ranges, demanding material portfolios spanning polyurethane through refractory ceramic fiber. Reliance Industries' Jamnagar complex and BASF Ludwigshafen site generate concentrated demand for integrated thermal management contracting. The segment leads adoption of digital thermal monitoring systems.
- Oil & Gas:Upstream production, midstream transport, and downstream refining operations specify insulation for personnel protection, freeze protection, and energy conservation simultaneously. US Gulf Coast ethylene expansion and Middle East LNG liquefaction projects are driving specification of rapid-installation prefabricated modules. NACE coating compatibility requirements complicate material selection.
- Power Generation:Coal, gas, and nuclear plants prioritize thermal efficiency improvements to extend asset life amid renewable displacement.
- Manufacturing:Food processing, cement, and metals fabrication facilities balance insulation performance against sanitation and mechanical durability requirements.
Contract value aggregates highest in Oil & Gas. Technology adoption is advancing most rapidly in Chemical Processing.
Installation Type:
Installation segments are restructuring around labor scarcity, with prefabricated modules capturing share where qualified field crews cannot be mobilized within project schedules.
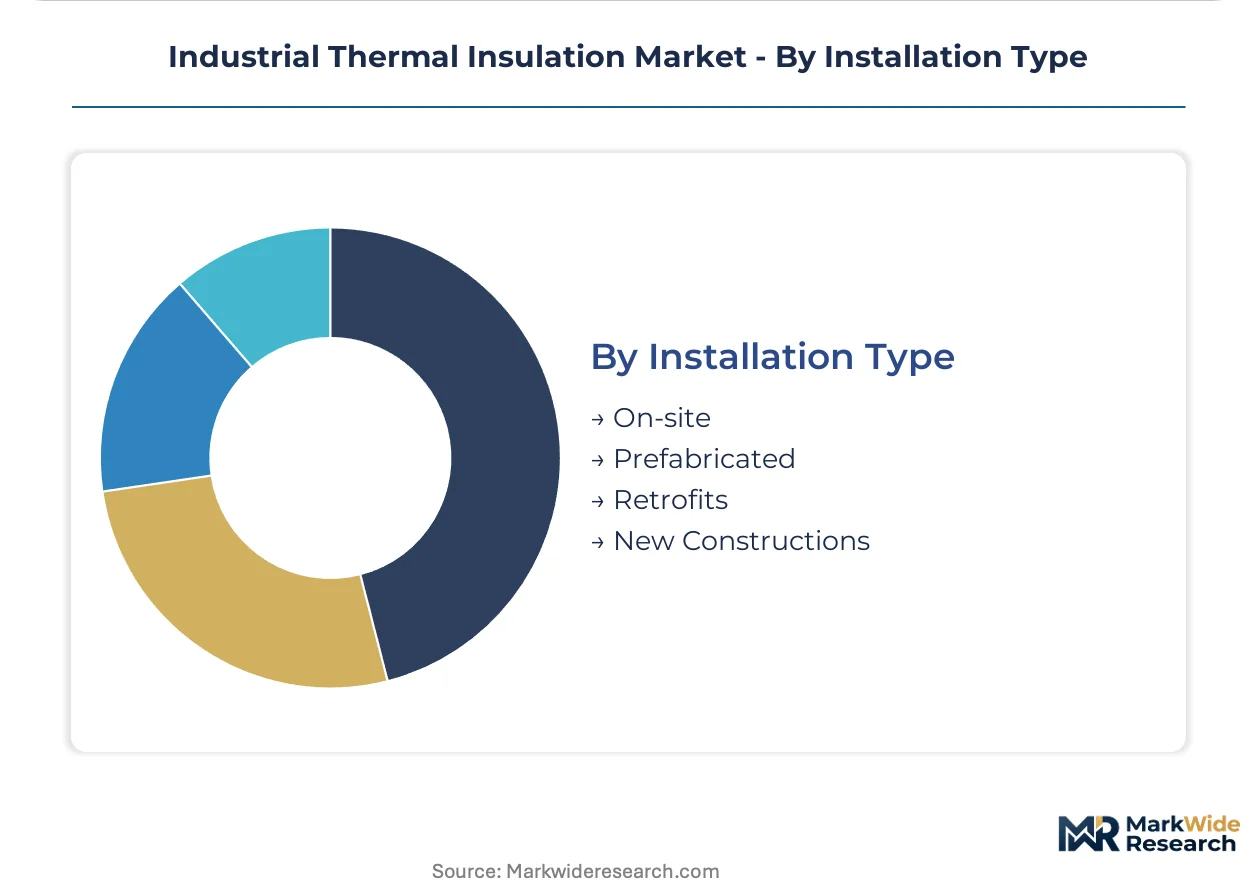
- Retrofits:Removal and replacement of degraded insulation on operating process equipment demands hot-work permitting, asbestos abatement protocols, and compressed shutdown windows. US refinery maintenance departments are outsourcing these packages to specialty contractors with NACE and API certification. The segment carries the highest safety incident exposure.
- Prefabricated:Factory-insulated piping, vessels, and equipment skids arrive at site with completed jacketing and quality documentation, reducing field labor by 60-70 percent. Modular construction of LNG trains and offshore platforms is standardizing this approach. German chemical parks and Singapore Jurong Island complexes specify prefabrication for turnaround efficiency.
- On-site:Traditional field application of insulation boards, blankets, and foams remains dominant in maintenance budgets.
- New Constructions:Greenfield projects integrate insulation specification into front-end engineering with lifecycle cost analytics.
Labor hours concentrate in On-site execution. Share capture is occurring fastest in Prefabricated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified insulation technicians concentrate along the US Gulf Coast petrochemical corridor, anchoring North American demand density. German engineering standards propagate through EU chemical parks. Chinese mineral wool production clusters in Shandong and Hebei provinces.
United States
EPA Boiler MACT compliance deadlines and OSHA thermal hazard enforcement are forcing insulation retrofits across aging refinery infrastructure. The Texas-Louisiana Gulf Coast corridor sustains concentrated demand from ethylene cracker expansions and LNG liquefaction terminal construction. Houston-area specialty contractors capture specification authority through integrated energy service contracting models.
Germany
Chemical park operators in Ludwigshafen and Leverkusen specify prefabricated insulation modules to compress turnaround schedules under strict TÜV certification requirements. The EU F-Gas Regulation restricts hydrofluorocarbon blowing agents, forcing polyurethane foam reformulation toward hydro-olefin alternatives. BASF's integrated manufacturing complex anchors domestic supply chain coordination for high-performance systems.
China
Dual carbon goals and MEE emissions enforcement are accelerating thermal efficiency upgrades across steel and cement sectors. Shandong and Hebei provinces concentrate basalt and slag wool production capacity, creating supply security leverage for domestic buyers. The Yangtze River Delta petrochemical cluster generates sustained demand for calcium silicate systems in power generation applications.
India
PLI scheme incentives and BIS insulation performance standards are reshaping procurement toward local content compliance. Reliance Industries' Jamnagar refinery complex and Indian Oil Corporation's Paradip expansion create concentrated demand for engineered high-temperature systems. Gujarat's specialty manufacturing corridor attracts insulation fabricators seeking proximity to petrochemical buildouts.
Saudi Arabia
SABIC's Jubail Industrial City expansion and NEOM giga-project construction are generating demand for rapid-installation prefabricated modules. The country's national industrial regulator enforces thermal efficiency mandates aligned with Vision 2030 diversification targets. The Eastern Province concentrates downstream petrochemical capacity requiring cryogenic and high-temperature insulation portfolios.
Industrial Thermal Insulation Market Competitive Environment
Top-tier vendors anchor premium engineered insulation tiers, while commodity fiberglass producers compete on volume scale and distribution reach. The vendor base stratifies across three functional archetypes: integrated glass fiber science platforms, high-temperature mineral wool specialists, and flexible foam formulators serving cold-service applications. Consolidation pressure intensifies as engineering-procurement-construction firms bundle insulation into guaranteed efficiency outcomes, compressing discrete material procurement channels. Strategic moves concentrate on backward integration into raw material preprocessing and technology licensing for aerogel composite manufacturing.
Within the glass fiber science platform tier, Owens Corning exemplifies scale-driven standardization across building and industrial applications. ROCKWOOL International A/S occupies a position anchoring high-temperature mineral wool systems for power and process industries. Armacell International S.A. represents the flexible elastomeric foam specialization vector for cold-service pipeline and equipment insulation. These three corporate structures illustrate how geographic origin and product-category focus determine competitive positioning within the broader industrial thermal insulation ecosystem.
| Leading Market Players |
|---|
| Owens Corning |
| ROCKWOOL International A/S |
| Johns Manville |
| Knauf Insulation |
| BASF SE |
| Saint-Gobain |
| Kingspan Group PLC |
| Armacell International S.A. |
| Paroc Group |
| Others |
Value Chain & Pricing Dynamics
Alumina-silica feedstock costs cascade through calcium silicate and refractory ceramic fiber pricing tiers, compressing margins for high-temperature insulation manufacturers while elevating lifecycle cost analytics over upfront material bids in procurement evaluations. Basalt and slag wool supply concentration in Shandong and Hebei provinces amplifies cost volatility for mineral wool systems, forcing buyers toward long-term offtake contracts to hedge against raw material swings.
Pricing Analysis
Bundled energy service contracts now command premium positioning against discrete material procurement, with engineering-procurement-construction firms capturing specification authority through guaranteed efficiency outcomes. Price differentiation hinges on ASTM C533 certification grade and ISO 23993 thermal performance documentation, with uncertified commodity fiberglass facing erosion from Chinese mineral wool imports. Cost compression in standard-grade fiberglass intensifies because of overcapacity in Asian production basins. Maintenance departments at US Gulf Coast refineries exhibit highest price sensitivity, while German chemical park operators prioritize TÜV-certified prefabricated modules with minimal total cost of ownership variance.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale petrochemical and LNG project demand, bypassing traditional distribution layers for factory-insulated piping and vessel skids. Raw material sourcing draws from bauxite and kaolin deposits in Australia and Brazil, basalt mining operations in Shandong province, and phenolic resin production in the US Gulf Coast. Single-source vulnerability concentrates in Chinese mineral wool capacity, where export license volatility and carbon border adjustment exposure threaten supply security for European buyers. Distribution runs through specialty contractors with NACE and API certification, consolidating vendor relationships around turnkey thermal management providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA Boiler MACT compliance deadlines and EU F-Gas Regulation restrictions force specification upgrades toward certified engineered systems with verified lifecycle assessments.
For Market Incumbents: Acquire aerogel composite manufacturing capabilities to defend premium positioning against emerging thermal monitoring integration threats. Backward integration into basalt preprocessing infrastructure in the US Southeast reduces exposure to Chinese supply volatility. Lock in multi-year EPC partnership frameworks to secure specification authority before integrated energy service contracting fully displaces discrete procurement channels. For New Entrants and Emerging Players: Aerogel-blanket production technology offers a technology-first wedge into offshore platform and modular skid applications where space constraints override cost sensitivity. Target India's Jamnagar and Paradip petrochemical corridors for local content-compliant manufacturing under PLI scheme incentives. Pursue joint development agreements with engineering-procurement-construction firms to bypass entrenched incumbent distribution relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where certified insulation inspector shortages extend project commissioning timelines and inflate specialty contractor valuations. Mid-cap mineral wool and calcium silicate manufacturers with captive raw material supply and established TÜV or ASTM certification pathways represent viable acquisition targets over a five-to-ten year industrial efficiency upgrade cycle. Watch EPA enforcement intensity and EU carbon border adjustment implementation pace as inflection indicators for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Preprocessing | Captive basalt and slag supply insulates margin stability against Chinese export volatility. |
| Aerogel Composite Manufacturing Scale-Up | Silica aerogel capacity expansion captures offshore platform specification shifts. |
| Prefabricated Module Production Footprint | Factory-insulated skid output compresses field labor dependence and turnaround schedules. |
| Digital Thermal Monitoring System Integration | Sensor-embedded insulation packages bundle hardware with predictive maintenance subscriptions. |
| EU F-Gas Compliant Polyurethane Reformulation | Hydro-olefin blown foam systems secure ISO 23993 certification for European cold-service demand. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Saudi Arabia, with primary inputs from each territory combined with secondary validation. Plant engineers, maintenance directors at petrochemical facilities, EPC contractor procurement leads, and specialty insulation contractor operations heads provided field-level demand and specification intelligence. Secondary sources included EPA Boiler MACT compliance filings, EU F-Gas Regulation implementation guidance, SEC 10-K disclosures from publicly traded insulation manufacturers, and customs trade data tracking basalt and slag wool import flows. Bottom-up project pipeline enumeration and top-down industrial construction spending estimates were triangulated to anchor volume assumptions.
Granularity-level modeling distinguished product type, application, end user, and installation method segments across the projection horizon. Calcium silicate and mineral wool demand were modeled separately for high-temperature service above 650°C, while polyurethane and aerogel systems were tracked for cryogenic and sub-ambient applications. CAGRs were derived from regression analysis against industrial boiler retrofit cycles, ethylene cracker expansion schedules, and LNG liquefaction terminal construction pipelines. Regional regulatory enforcement intensity and carbon border adjustment mechanism implementation timelines served as scenario-weighting inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to alumina-silica raw material cost volatility, Chinese export license restrictions, and certified insulation technician supply constraints. Periodic stress-testing of base assumptions against EPA enforcement patterns and EU chemical restriction expansions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Clay Roof Tiles Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
US and Canada Corner Beads and Caps Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
PU Waterstops Market